
 Europe Aircraft MRO Market | 2026-2036
Europe Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft MRO Market Foresight
Market Context
European MRO hangar capacity is consolidating around major hubs in Germany, Switzerland, and France. Lufthansa Technik anchors wide-body engine services through its Hamburg and Munich facilities. MTU Aero Engines AG specializes in geared turbofan maintenance, leveraging vertical repair networks across Poland and Romania. Safran competes on landing gear and nacelle systems, sustaining long-term contracts with Airbus operators.
Technical Definition and Segment Structure
Europe Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to maintain airworthiness under EASA Part-145 certification, requiring traceable materials, calibrated tooling, and documented release-to-service protocols for commercial aviation safety. Engine overhaul commands the deepest margin pools due to long-cycle contracts and proprietary OEM intellectual property, while predictive maintenance technology grows fastest as airlines deploy sensor-driven fleet health monitoring to minimize aircraft-on-ground downtime. Component repair remains fragmented across specialized shops, though advanced robotics adoption concentrates in high-value avionics and hydraulics restoration.
Regulatory Framework and Outlook
EASA mandates continuous airworthiness management under Commission Regulation (EU) No 1321/2014, while REACH chemicals restrictions and the EU Green Deal carbon benchmarks reshape material selection and waste disposal protocols across MRO operations. The EU AI Act introduces conformity requirements for automated inspection systems, compelling shops to validate algorithmic defect detection against human-certified standards. Stakeholders must monitor how EASA integrates sustainable aviation fuel infrastructure wear factors into future maintenance intervals.
Market Dynamics
Digital twin integration and predictive analytics are compressing maintenance intervals across European airline fleets, forcing MRO providers to restructure labor deployment and parts forecasting around real-time sensor data rather than calendar-based schedules.
Growth Catalysts
- EASA Part-145 certification expansion:Eastern European facilities in Poland and Romania are securing approvals for engine module repairs, drawing work packages from Western European carriers seeking cost arbitrage.
- Sustainable aviation fuel compatibility retrofits:Seal and gasket replacement cycles are accelerating as SAF blends introduce new elastomer degradation patterns requiring specialized component overhaul.
- Geared turbofan fleet maturation:Power-by-the-hour contracts for Pratt & Whitney GTF engines are maturing into heavy maintenance events, concentrating demand in specialized shops.
Market Restraints
- Titanium and nickel alloy price volatility:Aerospace-grade superalloy input costs swing with mining supply disruptions, compressing margin on engine hot-section repairs.
- OEM intellectual property lock-in:Proprietary diagnostic software for next-generation engines restricts independent MRO access to fault codes and repair protocols.
- REACH chemical substitution mandates:Chromate-based corrosion inhibitors face phase-out timelines, forcing reformulation of surface treatments with unproven field performance.
Strategic Opportunities
- EU Green Deal maintenance interval recalibration:Carbon-neutral hangar operations certification could differentiate providers bidding for airline ESG-mandated contracts.
- Drone-based airframe inspection:Automated visual systems for fuselage damage assessment reduce scaffold deployment and inspector hours per check.
- Swiss and Austrian alpine corridor specialization:Geographic positioning for rapid-response AOG services targeting business aviation and cargo operators.
Industry Challenges
- Non-destructive testing technician shortage:Eddy current and ultrasonic inspection certification pipelines cannot match retirement rates in Germany and France.
- Legacy avionics obsolescence:Analog cockpit system support requires cannibalization from retired fleets as manufacturers discontinue component production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft MRO Market |
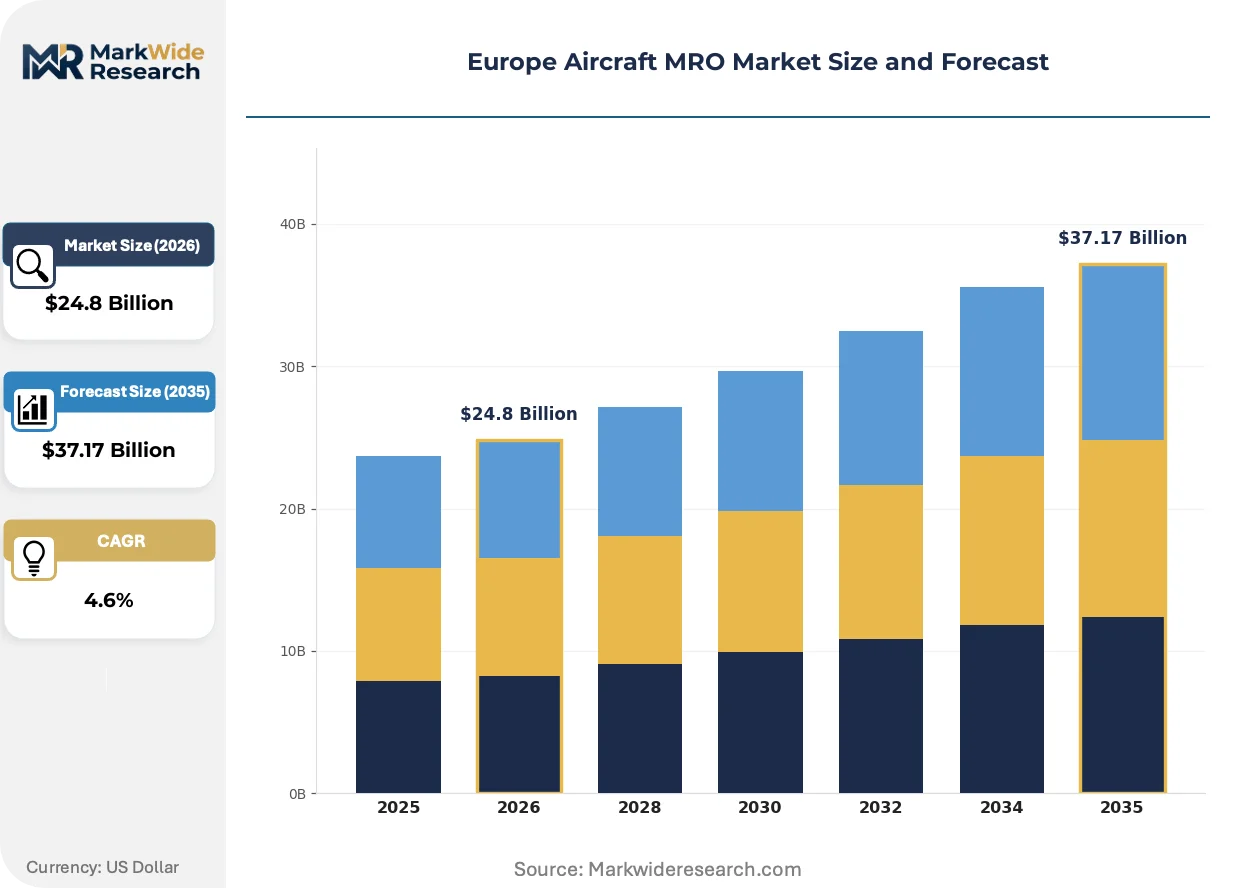
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Line Maintenance End User: Commercial Airlines, Cargo Airlines, Government Agencies, Private Operators Technology: Predictive Maintenance, Advanced Robotics, Data Analytics, High-Performance Computing Application: Scheduled Maintenance, Unscheduled Maintenance, Modifications, Upgrades |
| Companies Covered | SR Technics Switzerland Ltd., MTU Aero Engines AG, Lufthansa Technik, Sabena technics S.A.S., FLTechnics, UAB, Rolls-Royce Holdings plc, Safran, AAR CORP, Air France Industries KLM Engineering & Maintenance, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft MRO Market Shifts & Advancements
Predictive maintenance platforms are displacing scheduled overhaul models across European commercial aviation, compressing aircraft-on-ground windows and redistributing value capture toward data-analytics providers and sensor hardware suppliers.
Robotic cold spray deposition is consolidating metal restoration workflows for turbine blade repair, eliminating traditional welding heat-affected zones. Lufthansa Technik and MTU Aero Engines are deploying automated systems for nickel superalloy buildup on high-pressure compressor airfoils. This consolidation of repair methodology is compressing turnaround times from weeks to days while reducing skilled welder dependency.
REACH chemicals restrictions are forcing systematic replacement of hexavalent chromium surface treatments across European MRO networks. The EU Green Deal benchmarks are accelerating adoption of trivalent chrome and sol-gel alternatives for corrosion protection. Component repair shops in Germany and France face the steepest compliance curves as national environmental agencies front-load enforcement.
Airline procurement departments are unbundling line maintenance from heavy check contracts, fragmenting supplier relationships that once spanned decades. Low-cost carriers in the United Kingdom and Spain are driving this disaggregation, sourcing ad-hoc AOG support through digital platforms rather than exclusive MRO agreements. This pattern is most visible in narrow-body fleet management where operational flexibility outweighs volume commitment discounts.
Europe Aircraft MRO Market Segmentation
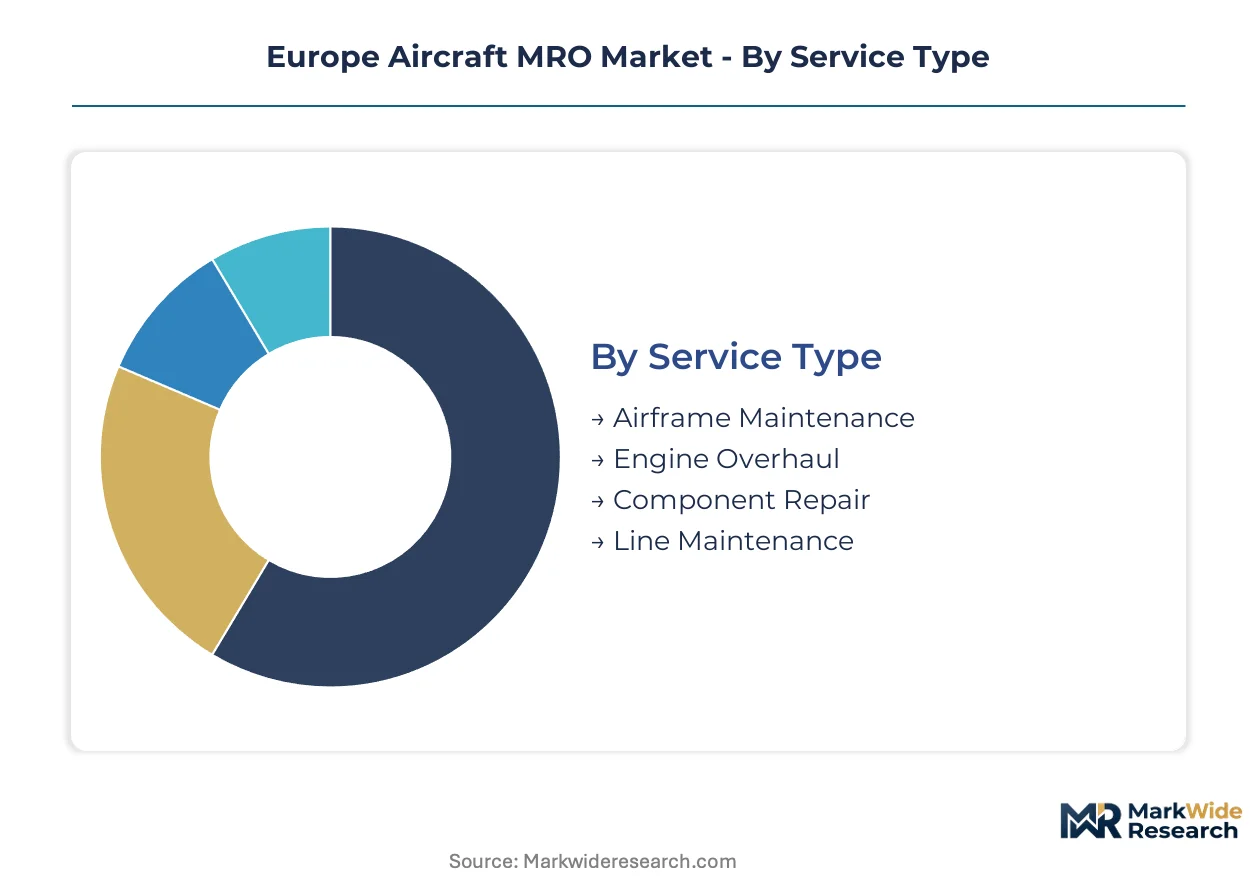
European MRO procurement increasingly segments contracts by technical capability tiers rather than bundled service packages. Airlines unbundle line maintenance from heavy checks to optimize cost and flexibility across their fleets.
Service Type:
EASA Part-145 certification requirements vary sharply across these segments, with engine overhaul demanding the most stringent OEM-authorized approvals and proprietary tooling investments.
- Engine Overhaul:Deep margin pools concentrate here due to long-cycle power-by-the-hour contracts and proprietary intellectual property lock-in from Pratt & Whitney and Rolls-Royce. Demand clusters in Germany and Switzerland where Lufthansa Technik and MTU Aero Engines anchor specialized geared turbofan facilities.
- Airframe Maintenance:Heavy check intervals compress as digital twin integration enables condition-based scheduling rather than calendar-driven removals. Polish and Romanian shops capture growing volumes from Western European carriers seeking cost arbitrage on C-check packages.
- Component Repair:Fragmented across specialized avionics and hydraulics shops with REACH chemical substitution mandates reshaping surface treatment protocols.
- Line Maintenance:Airlines increasingly source through digital platforms rather than exclusive agreements, particularly among low-cost carriers in the United Kingdom and Spain.
Leading the category by volume: Airframe Maintenance. Growing fastest: Engine Overhaul.
End User:
Procurement sophistication and contract duration diverge significantly across these customer types, from ESG-mandated RFPs to emergency AOG spot buys.
- Commercial Airlines:Fleet renewal programs under EASA airworthiness mandates drive scheduled maintenance demand. Germany, France, and United Kingdom carriers dominate contract value, with predictive maintenance platform adoption compressing aircraft-on-ground windows.
- Cargo Airlines:E-commerce volume surges from Leipzig and Luxembourg hubs accelerate utilization rates, shortening maintenance intervals for converted freighter fleets.
- Government Agencies:Military derivative aircraft require specialized security-cleared facilities with national sovereignty restrictions limiting vendor pools.
- Private Operators:Business aviation demands rapid-response AOG services concentrated in Swiss and Austrian alpine corridors for geographic positioning advantages.
Commercial Airlines command the largest contract values. Cargo Airlines are climbing the fastest as e-commerce fleet utilization intensifies.
Technology:
Capital deployment and ROI timelines separate mature digital tools from emerging automation platforms requiring validation against human-certified EASA standards.
- Predictive Maintenance:Sensor-driven fleet health monitoring displaces scheduled overhaul models, redistributing value capture toward data-analytics providers. Airlines deploy these platforms to minimize downtime, though EU AI Act conformity requirements compel algorithmic validation against human-certified defect detection standards.
- Advanced Robotics:Robotic cold spray deposition consolidates turbine blade repair workflows, eliminating welding heat-affected zones. Lufthansa Technik and MTU Aero Engines deploy automated nickel superalloy buildup systems.
- Data Analytics:Real-time parts forecasting and labor deployment restructuring follow digital twin integration across airline fleets.
- High-Performance Computing:Structural simulation and remaining-useful-life modeling support extended maintenance interval petitions to EASA.
Predictive Maintenance captures the largest installed base. Advanced Robotics shows the steepest expansion trajectory as repair methodology consolidation accelerates.
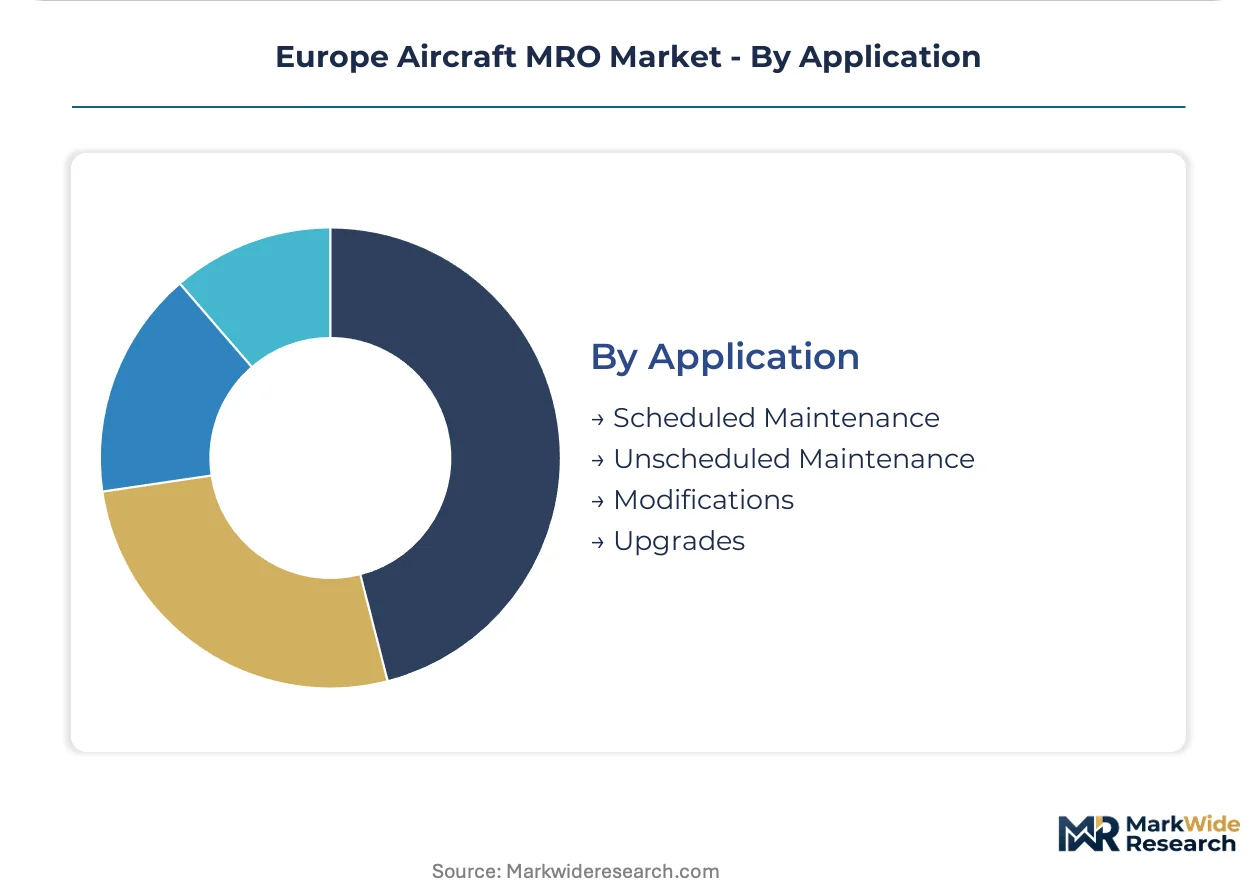
Application:
Revenue predictability and margin stability separate contracted scheduled work from volatile unscheduled events and capital-intensive modification programs.
- Scheduled Maintenance:Calendar-based and flight-hour-triggered checks provide baseline revenue visibility. Digital twin integration is compressing these intervals as real-time sensor data replaces fixed schedules.
- Unscheduled Maintenance:AOG events command premium pricing with Swiss and Austrian providers specializing in rapid-response services for business aviation and cargo operators.
- Modifications:Sustainable aviation fuel compatibility retrofits accelerate seal and gasket replacement cycles as SAF blends introduce new elastomer degradation patterns.
- Upgrades:Avionics modernization faces legacy analog system obsolescence, requiring cannibalization from retired fleets as manufacturers discontinue component production.
Scheduled Maintenance anchors the revenue base. Modifications are gaining share fastest as SAF retrofit mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium and nickel superalloy supply corridors from Norwegian mining operations and Russian feedstock alternatives anchor MRO capacity distribution across Western and Eastern Europe. EASA Part-145 certification density concentrates in German-speaking industrial regions, while cost arbitrage draws engine module work toward Polish and Romanian facilities.
Germany
Lufthansa Technik and MTU Aero Engines anchor engine overhaul demand through Hamburg, Munich, and Hannover facilities serving global airline fleets. EASA mandates under Commission Regulation (EU) No 1321/2014 drive continuous airworthiness management investments. The Bavarian aerospace cluster around Munich specializes in geared turbofan maintenance, drawing power-by-the-hour contracts from Pratt & Whitney operators.
United Kingdom
Rolls-Royce Derby headquarters sustains deep supply chain linkages to independent MRO networks across the Midlands and Southeast England. REACH chemicals restrictions from ECHA force systematic replacement of hexavalent chromium surface treatments at British component shops. London Gatwick and Manchester maintenance bases capture growing narrow-body line maintenance volumes from low-cost carriers unbundling traditional service contracts.
France
Air France Industries KLM Engineering & Maintenance anchors heavy check capacity at Paris-Charles de Gaulle and Toulouse-Blagnac airports near Airbus manufacturing sites. The EU Green Deal carbon benchmarks reshape hangar energy profiles and waste disposal protocols across French MRO operations. Safran Landing Systems in Toulouse concentrates landing gear and nacelle overhaul for Airbus A320 and A350 operators.
Switzerland
SR Technics Switzerland Ltd. maintains Zurich-based wide-body engine and component repair serving Middle East and Asian carrier transit traffic. Swissmedic alignment with EASA standards enables seamless cross-border certification recognition for alpine corridor rapid-response services. Geneva and Basel facilities specialize in business aviation AOG support, leveraging geographic positioning for cargo and private operator emergency interventions.
Poland
FLTechnics, UAB and expanding independent shops in Warsaw and Krakow secure EASA Part-145 approvals for engine module repairs and C-check packages. Cost differentials of 25-35% below Western European rates attract work packages from German and UK carriers seeking maintenance arbitrage. The Małopolska aviation cluster develops specialized non-destructive testing technician pipelines to address certification gaps across the region.
Europe Aircraft MRO Market Competitive Landscape
Global majors compete with regional champions across certification tiers and proprietary tooling access. The vendor base clusters around three structural layers: OEM-authorized engine specialists with intellectual property lock-in, independent airframe and component shops competing on turnaround speed, and digital-platform intermediaries fragmenting line maintenance procurement. Consolidation pressures intensify as airlines unbundle service packages and predictive analytics redistribute value toward data providers. Dominant competitive moves include EASA Part-145 certification expansion into Eastern Europe and robotic cold spray deposition adoption for turbine blade repair workflows.
Within the OEM-anchored tier, Lufthansa Technik and MTU Aero Engines represent the German-engineered maintenance archetype, occupying positions defined by geared turbofan specialization and vertical repair network control. Safran exemplifies the French systems-integrator model, anchoring landing gear and nacelle service portfolios through long-term Airbus operator contracts. Among independent challengers, SR Technics Switzerland Ltd. sits within the alpine rapid-response specialist category, while FLTechnics, UAB represents the Eastern European cost-arbitrage archetype expanding certification scope westward.
| Leading Market Players |
|---|
| SR Technics Switzerland Ltd. |
| MTU Aero Engines AG |
| Lufthansa Technik |
| Sabena technics S.A.S. |
| FLTechnics, UAB |
| Rolls-Royce Holdings plc |
| Safran |
| AAR CORP |
| Air France Industries KLM Engineering & Maintenance |
| Others |
Supply & Pricing Matrix
REACH chemicals phase-out timelines in Europe gate both qualified supply and premium-tier pricing access, as EASA Part-145 shops that reformulate surface treatments ahead of enforcement capture margin premiums while laggards face contract disqualification. The EU Green Deal carbon benchmarks compound this bifurcation, certifying hangar operations for ESG-mandated airline procurement at price premiums.
Pricing Analysis
Warranty and service-bundling unbundling reshapes contract structures across European MRO, with power-by-the-hour engine agreements retaining full-service premiums while line maintenance fragments into transactional spot purchases. Pricing stratifies across OEM-authorized, independent-certified, and non-certified tiers, with Pratt & Whitney and Rolls-Royce intellectual property lock-in sustaining margin premiums in engine overhaul. Cost compression in airframe heavy checks intensifies as Polish and Romanian shops undercut Western European rates. Low-cost carriers exhibit highest price sensitivity, while flag carriers prioritize ESG-compliant suppliers over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian titanium sponge and Russian nickel feedstock alternatives, exposing engine hot-section repair shops to aerospace-grade superalloy supply disruptions. Germany, Switzerland, and France anchor component manufacturing, while Poland and Romania expand module repair capacity. Raw material dependencies center on nickel superalloys, titanium alloys, and chromate-free corrosion inhibitors. Tariff exposure on aerospace metals imported from non-EU sources threatens margin stability. Distribution runs through EASA-certified logistics networks with traceable material documentation mandatory for release-to-service protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Aircraft MRO operates as a cost-of-compliance market where EASA Part-145 certification density creates barrier-to-entry moats for incumbent shops, forcing new entrants to absorb multi-year approval timelines and proprietary tooling investments before capturing airline contracts.
For Market Incumbents: Deepen robotic cold spray deposition capabilities to compress turbine blade turnaround times and reduce skilled welder dependency against MTU Aero Engines and Lufthansa Technik automation investments. Expand EASA Part-145 certification scope into Polish and Romanian facilities to capture cost-arbitrage work packages from Western European carriers seeking C-check savings. For New Entrants and Emerging Players: EU AI Act conformity requirements for automated inspection systems open a window for algorithmic defect-detection specialists to validate platforms against human-certified standards before incumbent shops retrofit legacy workflows. Target drone-based airframe inspection for narrow-body fleets at London Gatwick and Manchester bases where low-cost carriers unbundle traditional maintenance agreements. Lead with rapid-response AOG services in Swiss and Austrian alpine corridors where geographic positioning commands premium pricing from business aviation operators. For Investors and Strategic Acquirers: EASA Part-145 certification expansion announcements from Eastern European facilities are the leading indicator that cost-arbitrage consolidation is accelerating and independent shops with approved engine module capabilities will command acquisition premiums. Over the medium-term horizon, prioritize vertically integrated providers with proprietary repair networks spanning Germany, Poland, and Romania. Monitor REACH chemical substitution compliance curves as the signal for which component shops will retain airline contracts versus face disqualification.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Part-145 Certification Expansion | Eastern European approvals for engine module repairs capture Western European carrier work packages seeking cost arbitrage. |
| Robotic Cold Spray Deposition Adoption | Automated nickel superalloy buildup eliminates welding heat-affected zones and compresses high-pressure compressor airfoil turnaround. |
| REACH Chemical Substitution Compliance | Trivalent chrome and sol-gel surface treatment reformulation ahead of enforcement secures ESG-mandated airline contract eligibility. |
| Predictive Maintenance Platform Integration | Sensor-driven fleet health monitoring displaces calendar-based scheduling and redistributes value toward data-analytics providers. |
| Drone-Based Airframe Inspection Deployment | Automated visual damage assessment reduces scaffold deployment and inspector hours per C-check at Polish and Romanian shops. |
Research Methodology
Document review covered EASA regulatory filings, airline fleet renewal disclosures, and REACH chemical substitution timelines, complemented by interviews with MRO operations directors, EASA certification auditors, airline procurement managers, and predictive maintenance platform engineers. Secondary validation drew from Commission Regulation (EU) No 1321/2014 implementation reports, EU Green Deal carbon benchmark disclosures, and OEM power-by-the-hour contract announcements. Bottom-up triangulation across facility-level capacity data and top-down reconciliation against regional fleet projections anchored market sizing.
Market value and volume estimates emerged from segment-level modeling across service type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from fitted growth curves calibrated to EASA mandate implementation schedules, geared turbofan fleet maturation patterns, and predictive maintenance platform adoption trajectories. Forecast inputs incorporated airline fleet renewal programs, sustainable aviation fuel compatibility retrofit mandates, and robotic automation deployment rates at Lufthansa Technik and MTU Aero Engines facilities.
The model assumes a particular technology adoption path for predictive maintenance platforms; alternative pathways for EU AI Act algorithmic validation standards would alter the outlook for automated inspection system penetration. Forecasts reflect assumptions regarding EASA certification expansion timelines, titanium and nickel alloy supply stability, and airline unbundling of maintenance contracts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market