
 On-Premises MRO Software Market | 2026-2036
On-Premises MRO Software Market Size, Share, and Industry Trends Forecast 2026-2036
On-Premises MRO Software Market Analysis
Germany is reshaping competitive dynamics in on-premises MRO software as industrial operators expand localized server capacity for maintenance platforms. SAP SE leverages its deep ERP integration to anchor enterprise accounts across European manufacturing hubs. IBM Corporation competes through hybrid-ready architectures that sustain long-term client retention in regulated sectors. Oracle Corporation specializes in database-centric EAM deployments that dominate energy and utility installations requiring air-gapped environments.
On-premises MRO software encompasses computerized maintenance management systems, enterprise asset management platforms, and integrated procurement modules deployed on local servers rather than cloud infrastructure. These systems execute work order scheduling, asset lifecycle tracking, spare parts inventory optimization, and compliance documentation generation through direct database connections with minimal external network exposure. CMMS and EAM product types lead current revenue generation as legacy manufacturing facilities prioritize direct system control over SaaS alternatives. Inventory management segments are gaining traction among aerospace end users where serialized part traceability demands localized data retention. Deployment models increasingly favor hybrid configurations that bridge on-premises cores with limited cloud connectivity for vendor updates.
ISO 55000 asset management standards and EU GDPR data localization requirements shape product architecture decisions for European deployments. The US FAA mandates rigorous documentation retention for aviation MRO activities, reinforcing demand for non-cloud systems in defense-adjacent supply chains. Stakeholders must monitor evolving cybersecurity certification requirements from national regulators as these frameworks increasingly dictate acceptable deployment architectures for critical infrastructure operators.
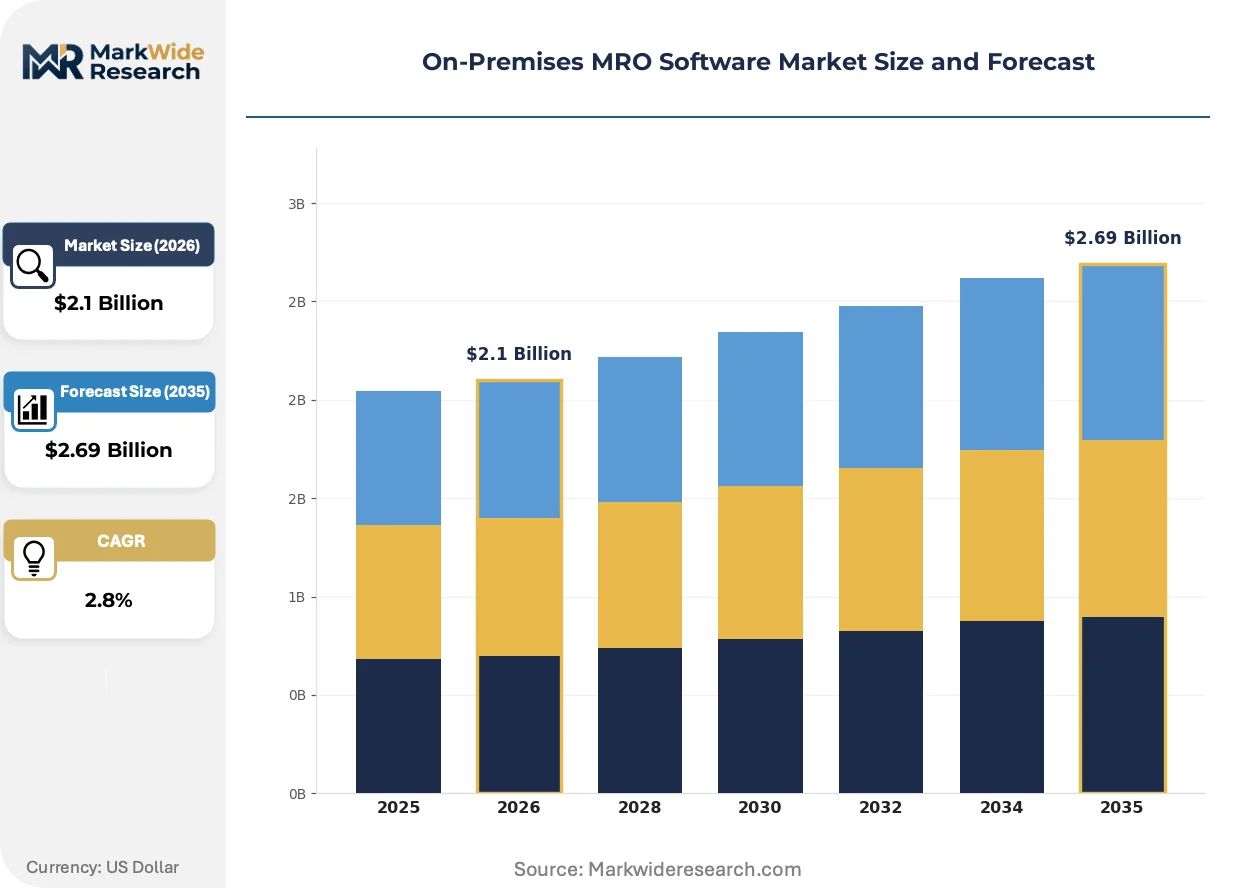
Market Dynamics
Data sovereignty mandates and cybersecurity hardening requirements are forcing industrial operators to retain maintenance records on localized infrastructure rather than migrate to cloud platforms. Defense contractors and critical infrastructure operators now treat on-premises deployment as a non-negotiable procurement criterion.
Growth Catalysts
- GDPR data localization:European manufacturers must store operational data within jurisdictional boundaries, accelerating server-based CMMS adoption across German automotive and French energy installations.
- Air-gapped environments:Nuclear facilities and military depots require physically isolated networks for asset tracking, creating specialized demand for hardened EAM architectures.
- Legacy system integration:Decades-old SCADA and PLC investments in US Midwest manufacturing necessitate on-premises middleware that cloud-native platforms cannot replicate.
Market Restraints
- Skilled technician scarcity:Local server maintenance requires certified database administrators and network engineers unavailable in secondary US industrial cities.
- Hardware refresh cycles:Five-to-seven-year capital equipment replacement timelines strain maintenance budgets at mid-sized Japanese precision manufacturers.
- Cloud substitution pressure:SaaS vendors offering comparable feature sets at lower total cost of ownership tempt finance departments at UK-based process industries.
Strategic Opportunities
- Hybrid architecture expansion:Edge computing nodes paired with centralized on-premises cores enable real-time vibration monitoring at German steel mills while retaining data control.
- India industrial corridor penetration:PLI scheme beneficiaries building domestic manufacturing capacity represent untapped CMMS demand as facilities scale beyond spreadsheet-based maintenance.
- FAA documentation mandates:Aviation MRO providers serving US defense supply chains must maintain immutable audit trails, favoring localized database deployments over cloud alternatives.
Industry Challenges
- Cybersecurity certification delays:CMMS vendors struggle to obtain Common Criteria evaluation for government deployments, stretching sales cycles to eighteen months.
- Interoperability fragmentation:Proprietary data formats from Siemens, Rockwell, and Schneider Electric complicate unified asset visibility in multi-vendor European plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Premises MRO Software Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.69 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMMS, EAM, Inventory Management, Procurement Software End User: Manufacturing, Aerospace, Utilities, Automotive Deployment Model: On-Premises, Hybrid, Customized, Standalone Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, IFS AB, Ramco Systems Limited, HCL Technologies Limited, GE Aviation, Honeywell International Inc., Lufthansa Technik AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Premises MRO Software Market Emerging Trajectories
Digital twin technology and predictive analytics are migrating from cloud environments to localized edge infrastructure. Vendors now engineer compact, rack-mounted solutions that deliver real-time processing without external data transmission.
Containerized microservices architecture is rendering obsolete monolithic CMMS deployments that required dedicated physical servers per facility. Aerospace MRO operators in Seattle and Toulouse are adopting Kubernetes-orchestrated maintenance platforms that consolidate multiple plant systems onto shared local hardware. This compression eliminates redundant infrastructure while preserving the air-gapped isolation that defense contracts demand.
EU AI Act risk classification rules are reshaping procurement specifications for automated maintenance scheduling algorithms. Systems deployed in German chemical processing must now document training data provenance and decision auditability, favoring on-premises models where operators control the entire inference pipeline. Energy utilities in Rotterdam and Milan are retrofitting existing EAM installations with explainable AI modules that satisfy regulator interrogation without cloud dependency.
Maintenance departments are consolidating vendor relationships and demanding unified platforms that span CMMS, EAM, and procurement functions. Japanese automotive suppliers in Nagoya and Toyota City are replacing point solutions with integrated suites from single vendors, reducing integration overhead and support fragmentation. This concentration favors established software providers with proven on-premises track records over emerging cloud-native competitors.
On-Premises MRO Software Market Segmentation
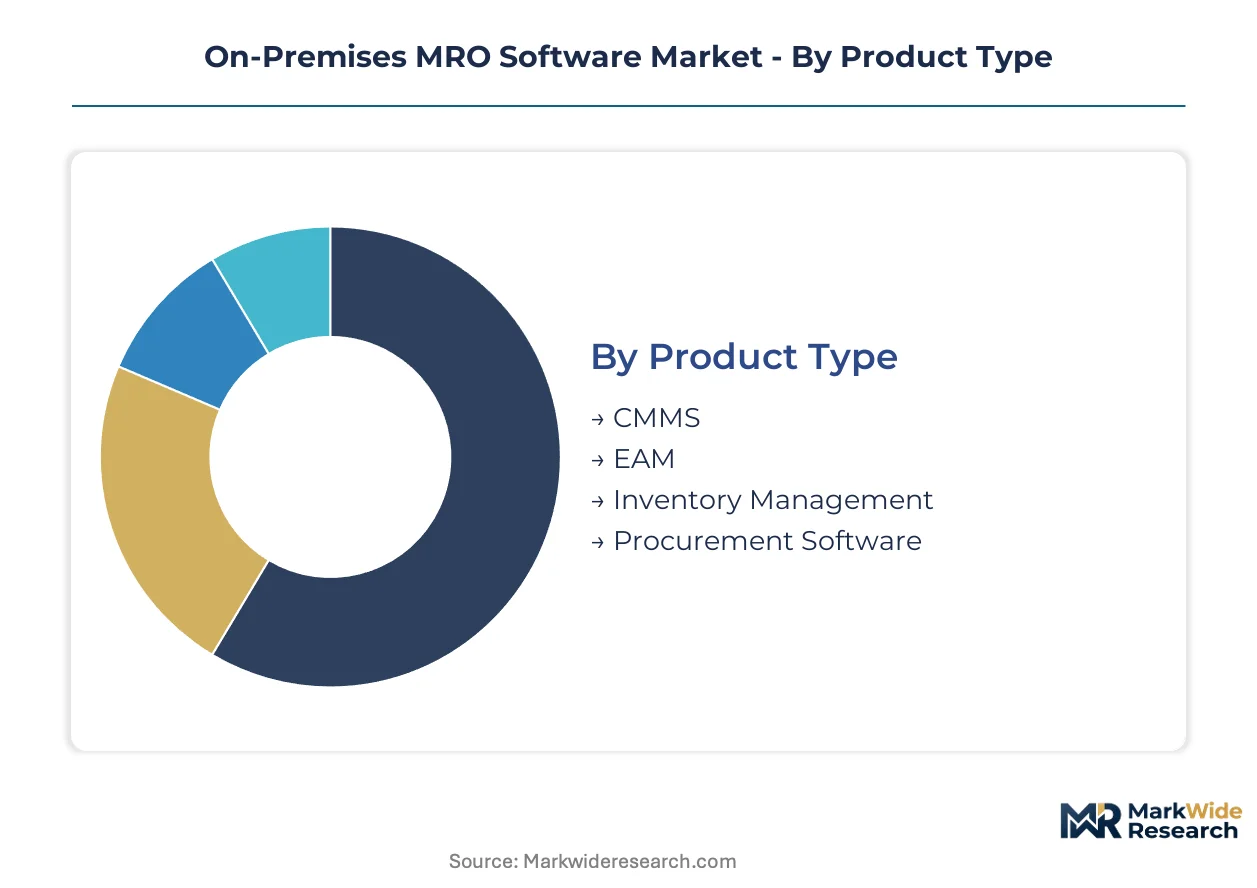
Segmentation in on-premises MRO software reveals how deployment constraints, regulatory mandates, and integration complexity fragment purchasing behavior across industrial buyers. Understanding these divisions exposes where vendors must customize architectures versus where standardized platforms suffice.
Product Type:
After-sales service intensity varies dramatically across product categories, with systems requiring continuous calibration and database administration commanding premium support contracts.
- CMMS:Computerized maintenance management systems orchestrate work order scheduling, preventive maintenance calendars, and technician dispatch through localized SQL databases. Demand concentrates in US Midwest automotive stamping plants where union maintenance crews require direct system control without cloud latency. GDPR data localization requirements in German automotive clusters reinforce CMMS preference over SaaS alternatives.
- EAM:Enterprise asset management platforms extend lifecycle tracking across capital-intensive infrastructure, integrating financial depreciation with operational performance metrics. Energy utilities in Rotterdam and Milan deploy EAM for ISO 55000 compliance, with air-gapped installations satisfying EU NIS2 cybersecurity directives for critical infrastructure operators.
- Inventory Management:Serialized part traceability modules serve aerospace MRO depots where FAA documentation mandates immutable audit trails for flight-critical components.
- Procurement Software:Sourcing modules integrate vendor qualification and purchase requisition workflows within localized ERP ecosystems at Japanese precision manufacturers.
By volume, CMMS leads. By growth pace, EAM is ahead.
End User:
Cost tier differentiation separates capital-rich defense contractors from budget-constrained mid-tier manufacturers.
- Manufacturing:Discrete and process manufacturers deploy on-premises MRO to preserve SCADA integration with decades-old PLC investments. US steel mills and German chemical processors prioritize localized control over cloud subscription models.
- Aerospace:Commercial aviation and defense MRO operators require physically isolated networks for classified maintenance activities. Seattle and Toulouse maintenance hubs favor hardened EAM architectures that satisfy ITAR and EU dual-use export controls.
- Utilities:Electric generation and water treatment operators face FERC and EPA audit requirements that favor immutable on-premises record retention.
- Automotive:Tier-1 suppliers in Nagoya and Toyota City consolidate point solutions into unified suites, reducing vendor fragmentation across multi-plant maintenance operations.
Manufacturing dominates current installations. Aerospace is expanding most quickly.
Deployment Model:
Application criticality determines whether organizations accept any external network exposure.
- On-Premises:Fully isolated server installations serve nuclear facilities and military depots requiring Common Criteria certification for government procurement eligibility.
- Hybrid:Edge computing nodes paired with centralized local cores enable real-time vibration monitoring at German steel mills while retaining data sovereignty.
- Customized:Bespoke configurations address proprietary data formats from Siemens, Rockwell, and Schneider Electric in multi-vendor European plants.
- Standalone:Single-facility deployments persist at mid-sized Japanese precision manufacturers with limited IT staffing.
Hybrid architectures are gaining share fastest. Pure on-premises retains the largest installed base.
Service Type:
Customer maturity separates organizations needing full implementation support from those requiring only break-fix maintenance.
- Consulting:Business process reengineering services guide legacy manufacturing facilities transitioning from spreadsheet-based maintenance to structured CMMS workflows.
- Implementation:System integration and data migration projects concentrate in India industrial corridor beneficiaries scaling beyond manual maintenance tracking.
- Maintenance:Database administration and server patching contracts address skilled technician scarcity in secondary US industrial cities.
- Support:Help desk and troubleshooting services sustain operations at UK process industries facing cloud substitution pressure from finance departments.
Implementation services generate largest contract values. Support contracts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters deploy on-premises CMMS for GDPR-compliant maintenance records, while US defense contractors prioritize air-gapped EAM systems for ITAR-controlled facilities. Japanese precision manufacturers favor localized inventory modules over cloud alternatives. Indian industrial corridor beneficiaries are scaling from spreadsheet-based tracking to structured maintenance platforms.
United States
Defense contractors and FAA-regulated aviation MRO operators drive demand for hardened on-premises architectures. ITAR documentation mandates and FERC audit requirements for utilities reinforce localized deployment preferences. Seattle and Wichita maintenance hubs adopt containerized microservices that preserve air-gapped isolation while consolidating redundant infrastructure.
Germany
Automotive stamping plants and chemical processors expand localized server capacity for maintenance platforms. EU GDPR data localization requirements and EU AI Act risk classification rules shape procurement specifications for automated scheduling algorithms. Stuttgart and Ludwigshafen industrial clusters retrofit existing EAM installations with explainable AI modules that satisfy regulator interrogation.
Japan
Tier-1 automotive suppliers consolidate point solutions into unified CMMS-EAM suites to reduce vendor fragmentation. METI industrial standards and hardware refresh cycles strain maintenance budgets at mid-sized precision manufacturers. Nagoya and Toyota City facilities replace legacy spreadsheet-based tracking with integrated procurement modules deployed on local servers.
India
PLI scheme beneficiaries building domestic manufacturing capacity represent untapped CMMS demand as facilities scale operations. The country's national industrial policy incentivizes localized data retention for critical infrastructure operators. Gujarat and Maharashtra industrial corridors transition from manual maintenance tracking to structured CMMS workflows with full implementation support.
United Kingdom
Process industries face cloud substitution pressure from finance departments despite operational preferences for localized control. UK regulatory frameworks for critical infrastructure cybersecurity increasingly dictate acceptable deployment architectures. Midlands-based manufacturers balance SaaS cost advantages against GDPR compliance requirements for operational data retention.
On-Premises MRO Software Market Vendor Landscape
Capability concentration sits with ERP-integrated specialists; scale advantage sits with database-centric platform providers. The vendor base organizes around three strategic archetypes: legacy enterprise software houses with deep manufacturing footprints, aviation-specific maintenance platforms with defense supply chain credentials, and hybrid-ready architecture providers bridging on-premises cores with limited cloud connectivity. Competitive moves concentrate on M&A for specialized compliance modules and strategic partnerships with industrial automation vendors for SCADA integration.
Within the ERP-integrated tier, SAP SE and Oracle Corporation exemplify archetypes anchored in European and US manufacturing hubs respectively. IBM Corporation occupies a position representing hybrid-ready architectures that sustain long-term client retention in regulated sectors. These three entities collectively illustrate how competitive positioning depends on pre-existing enterprise relationships and database administration expertise rather than cloud-native feature velocity.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| IFS AB |
| Ramco Systems Limited |
| HCL Technologies Limited |
| GE Aviation |
| Honeywell International Inc. |
| Lufthansa Technik AG |
| Others |
Supply Flow & Price Mechanics
Undercapacity in certified database administration across secondary US industrial cities tightens vendor pricing power while forcing buyers toward bundled service contracts. This utilization squeeze simultaneously elevates implementation premiums and compresses hardware margins as distributors compete for limited deployment slots.
Pricing Analysis
Long-term enterprise licensing contracts dominate procurement for defense contractors and critical infrastructure operators, with five-to-seven-year terms locking in predictable cost structures. Price differentiation separates ISO 55000-certified EAM suites from basic CMMS offerings, while customization depth for SCADA integration commands additional premiums. Pricing pressure stems from SaaS substitution threats in UK process industries where finance departments favor operational expenditure models. Mid-sized Japanese precision manufacturers exhibit highest price sensitivity due to constrained capital budgets, whereas FAA-regulated aviation MRO operators accept premium positioning for air-gapped compliance assurance.
Supply Chain Analysis
Export-control regimes including ITAR and EU dual-use regulations restrict technology flows to defense-adjacent maintenance platforms, fragmenting vendor sourcing across jurisdictional boundaries. Supply concentration centers on Germany for industrial automation middleware, the United States for hardened server hardware, and Japan for precision sensor integration. Raw material dependencies include specialized semiconductors for edge-computing nodes, rare-earth components for vibration monitoring equipment, and certified storage media for immutable audit trails. Single-source vulnerability runs through proprietary data format licensing from Siemens, Rockwell, and Schneider Electric. Distribution runs through systems integrators with SCADA expertise rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of Common Criteria-certified implementation engineers creates bottlenecks that determine competitive survival more than feature velocity. This talent gap rewards early certification investment and captive training programs.
For Market Incumbents: Pre-empt SaaS substitution threats by embedding containerized microservices that preserve air-gapped isolation while demonstrating cloud-comparable total cost of ownership. Fortify vertical integration into SCADA middleware to capture proprietary data format licensing revenue streams. Prioritize Common Criteria certification acceleration to shorten eighteen-month government sales cycles before emerging competitors achieve parity. For New Entrants and Emerging Players: Pursue white-space penetration in India's PLI scheme industrial corridors where facilities transition from spreadsheet-based maintenance to structured CMMS workflows. Target mid-sized precision manufacturers in Japan's secondary industrial cities underserved by incumbent implementation capacity. Lead with hybrid architecture offerings that bridge edge-computing real-time monitoring with localized data control, satisfying German steel mill procurement specifications without full EAM suite complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized microservices sub-segments as Kubernetes-orchestrated platforms eliminate redundant physical server requirements per facility. Long-term viability over the next decade hinges on regulatory compliance moats rather than feature differentiation. Acquisition targets should display established SCADA integration expertise and existing Common Criteria evaluation progress. Watch cybersecurity certification backlogs at national regulators as the primary inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Certification | Eu AI Act compliance positions vendors for German chemical processor procurement mandates. |
| SCADA Middleware Acquisition | Proprietary data format control captures integration revenue from multi-vendor European plants. |
| Common Criteria Fast-Track | Accelerated government certification unlocks eighteen-month defense contractor sales cycles. |
| Edge Computing Partnership | Real-time vibration monitoring integration penetrates German steel mill upgrade budgets. |
| India Implementation Scaling | Full-service deployment capacity captures PLI scheme manufacturing corridor expansion demand. |
Methodological Framework
A spread of perspectives from maintenance directors at US Midwest automotive plants, IT procurement officers in German chemical processing, platform engineers at Japanese Tier-1 suppliers, and integration specialists serving Indian industrial corridors converged on the working assumptions. These primary interviews combined with secondary validation from FAA documentation mandates, EU GDPR localization requirements, SEC filings of listed software vendors, and customs data on industrial automation equipment imports. Bottom-up facility-level deployment tracking and top-down vendor revenue analysis provided triangulation across the analysis window.
Demand-supply-balance framing anchored the analytical approach, modeling deployment velocity against certified implementation engineer availability across regional markets. Segmentation dimensions included product type, end-use industry, deployment model complexity, and regional regulatory cluster. CAGRs derived from facility expansion pipelines and hardware refresh cycle timing. Industry-specific forecast inputs incorporated PLI scheme beneficiary scaling trajectories and EU AI Act compliance deadline sequencing.
Sensitivities concentrate around cybersecurity certification timeline extensions, SaaS substitution acceleration in UK process industries, and single-source middleware licensing disputes. Forecasts reflect assumptions on regulatory stability and skilled technician pipeline development. Material shifts in ITAR interpretation or EU dual-use control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market