
 Middle-East and Africa Aircraft Engine MRO Market | 2026-2036
Middle-East and Africa Aircraft Engine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aircraft Engine MRO Market Foresight
Low-cost carrier fleet expansion is recalibrating MRO demand patterns across the Middle-East and Africa. GE Aviation leverages its regional partnerships to anchor overhaul capacity in Dubai and Istanbul. Emirates Engineering sustains vertical integration advantages through captive maintenance at Al Maktoum International. Joramco competes on narrow-body specialization, serving operators across Jordan, Egypt, and East Africa with cost-competitive turnaround cycles.
Aircraft engine MRO encompasses the inspection, disassembly, repair, reassembly, and testing of gas turbine powerplants to restore thrust output, fuel efficiency, and cycle-life compliance per manufacturer specifications. The process requires precision machining of high-pressure compressor blades, thermal barrier coating refurbishment, and full-throttle bench validation before return to service. Overhaul services for jet engines capture the largest value pool given the complexity of high-bypass turbofan rebuilds and OEM-controlled parts pricing. Predictive maintenance technology is expanding fastest as operators deploy vibration analysis and oil-debris monitoring to extend on-wing intervals and reduce unscheduled shop visits.
GCAA in the UAE, EASA through bilateral agreements, and South Africa's SACAA enforce airworthiness directives that mandate documented traceability for life-limited engine components and certified repair station accreditation. These frameworks shape market access by requiring substantial capital investment in test cell infrastructure and specialized technician training programs. Stakeholders must monitor regulatory convergence between Gulf standards and European Aviation Safety Agency protocols as this alignment will determine which facilities qualify for cross-border engine acceptance certificates.
Market Dynamics
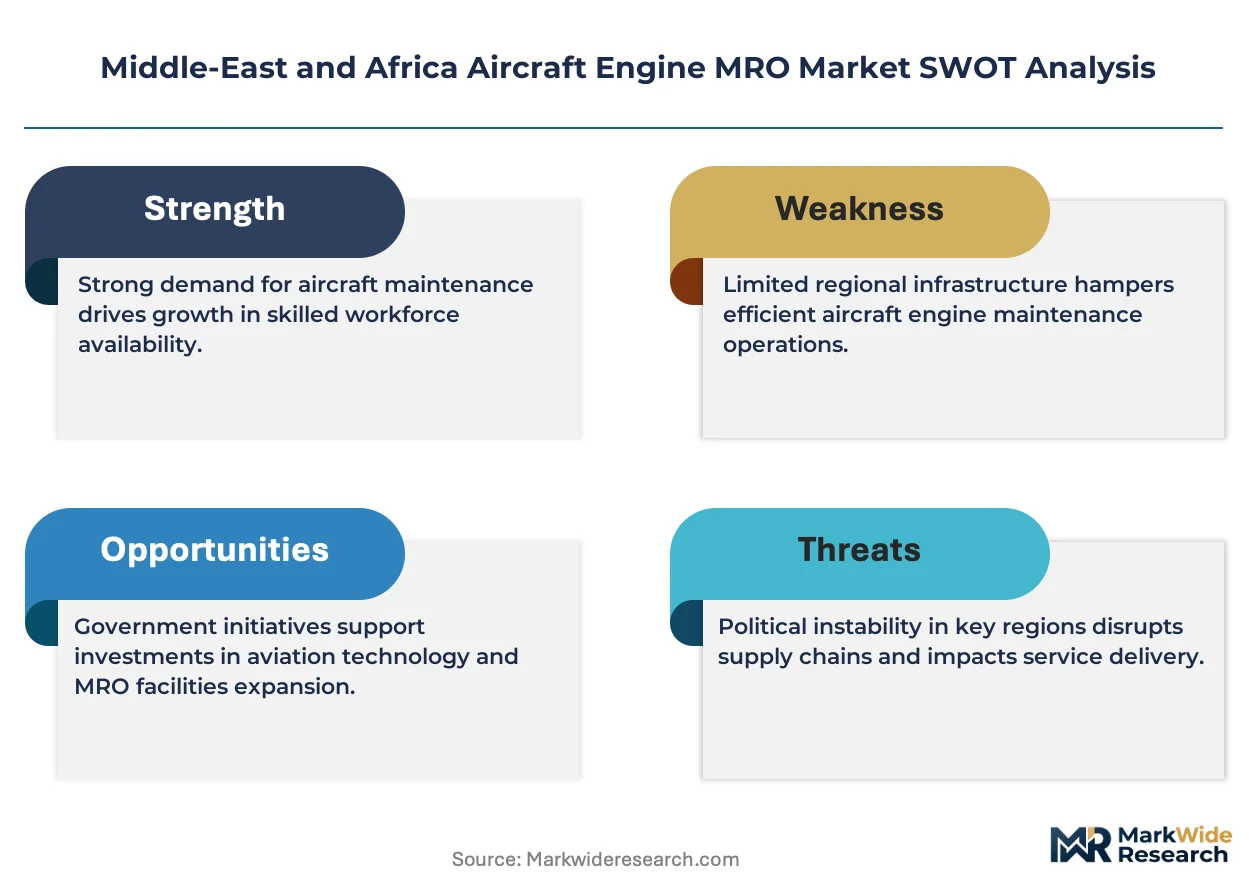
GCAA-EASA regulatory convergence is compressing certification timelines for overhaul facilities while forcing capital redeployment toward test cell infrastructure and specialized technician pipelines across the Gulf.
Growth Catalysts
- Low-cost carrier fleet expansion:Narrow-body aircraft utilization rates are climbing across Egypt, Jordan, and Saudi Arabia, generating shop visit demand for CFM56 and LEAP-1B powerplants.
- Predictive maintenance technology:Vibration analysis and oil-debris monitoring systems are extending on-wing intervals, reducing unscheduled removals and smoothing MRO demand forecasting for operators.
- GCAA airworthiness directive alignment:The UAE regulator's traceability mandates for life-limited components are accelerating documentation standardization across Dubai-based overhaul stations.
Market Restraints
- OEM-controlled parts pricing:Proprietary high-pressure compressor blade sourcing from GE Aviation and Rolls-Royce inflates material costs for independent MRO providers.
- Test cell infrastructure concentration:Full-throttle engine validation capability clusters in the UAE and Turkey, limiting market access for facilities in East Africa and the Levant.
- Specialized technician scarcity:Thermal barrier coating refurbishment and precision machining skills face supply bottlenecks across Saudi Arabia and South Africa.
Strategic Opportunities
- East African cargo operator penetration:Ethiopian Airlines and Nairobi-based freighter fleets remain underserved for wide-body engine overhaul, creating greenfield entry points.
- Power-by-the-hour contract expansion:Risk-transfer service models are gaining traction among Saudi low-cost carriers seeking to outsource residual value risk.
- EASA bilateral agreement leverage:Turkish and UAE facilities can capture European operator overflow demand through mutual recognition certificates.
Industry Challenges
- Life-limited component traceability compliance:GCAA and SACAA documentation requirements impose multi-year certification timelines for new repair station entrants.
- Legacy engine type obsolescence:CFM56-3 and V2500-A1 shop visits are declining as regional fleets transition to newer powerplants, stranding specialized tooling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aircraft Engine MRO Market |
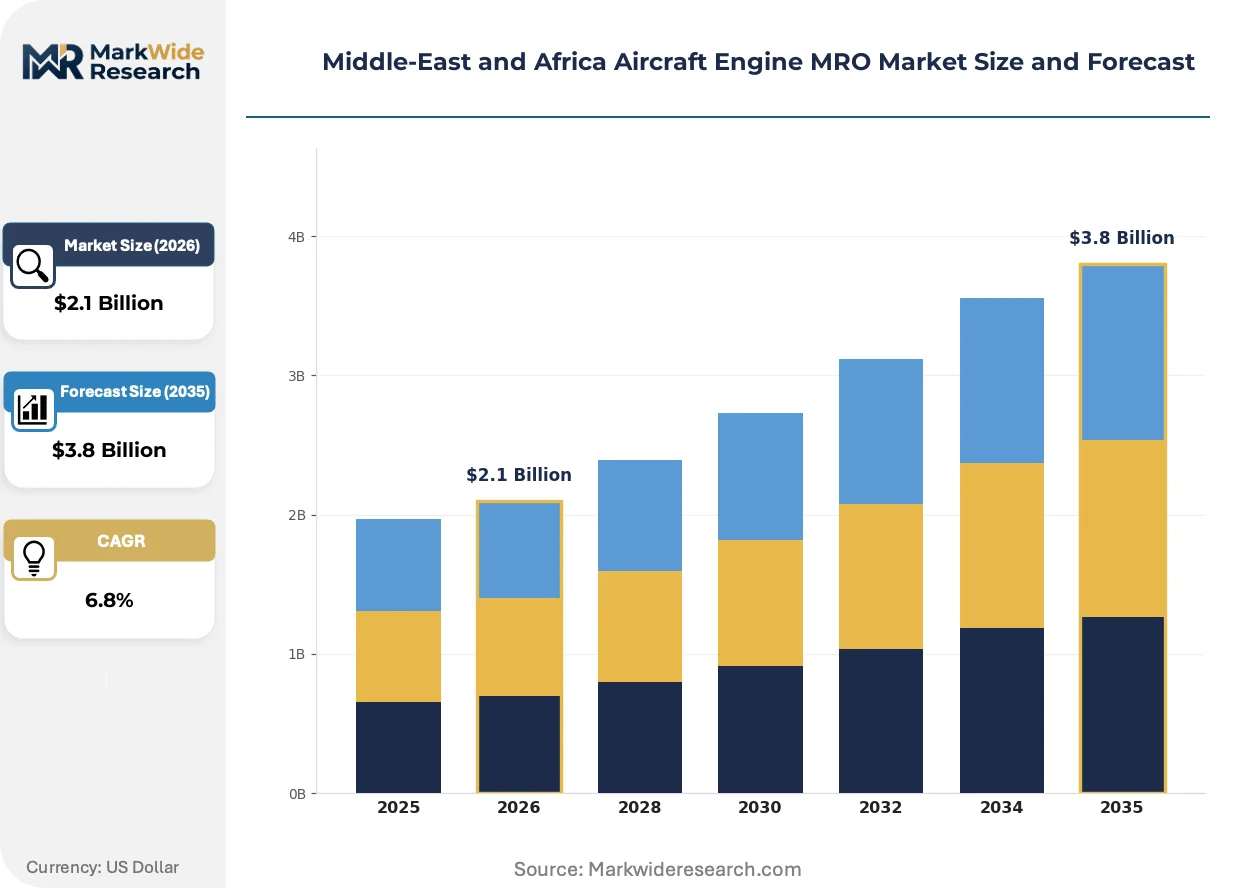
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Commercial Airlines, Cargo Operators, Military Aviation, MRO Organizations Service Type: Overhaul, Repair, Maintenance, Component Replacement Engine Type: Jet Engines, Turboprop Engines, Turbojet Engines, Auxiliary Power Units Technology: Digital Maintenance, Predictive Maintenance, Traditional Maintenance, Remote Diagnostics |
| Companies Covered | GE Aviation, Rolls-Royce, Safran Aircraft Engines, MTU Aero Engines, Emirates Engineering, Lufthansa Technik, CFM International, Joramco, Turkish Technic, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aircraft Engine MRO Market Shifts & Advancements
Digital thread integration and on-wing sensing technologies are compressing traditional overhaul cycles while redistributing value capture between OEMs and independent MRO providers across the Middle-East and Africa.
On-wing health monitoring is decentralizing maintenance planning authority from centralized engineering departments to flight operations teams. Low-cost carriers in Saudi Arabia and the UAE are deploying real-time oil analysis sensors across A320neo and 737 MAX fleets. This distributed diagnostic capability is reducing unscheduled shop visits and compressing the addressable market for routine overhaul services.
EASA's expanding bilateral recognition framework with GCAA and SACAA is harmonizing repair station accreditation standards across the Gulf and Southern Africa. The alignment eliminates redundant audit requirements for facilities serving European-registered aircraft. Turkish and Emirati overhaul providers are capturing incremental volume from European operators seeking cost-competitive turnaround cycles outside the EU.
Power-by-the-hour contracting is displacing traditional time-and-material invoicing among regional cargo and passenger operators. Saudi Arabian low-cost carriers are bundling engine coverage with airframe maintenance under multi-year risk-transfer agreements. This preference shift concentrates procurement authority with fleet managers and compresses margins for standalone overhaul bids in the UAE and Jordan.
Middle-East and Africa Aircraft Engine MRO Market Segmentation
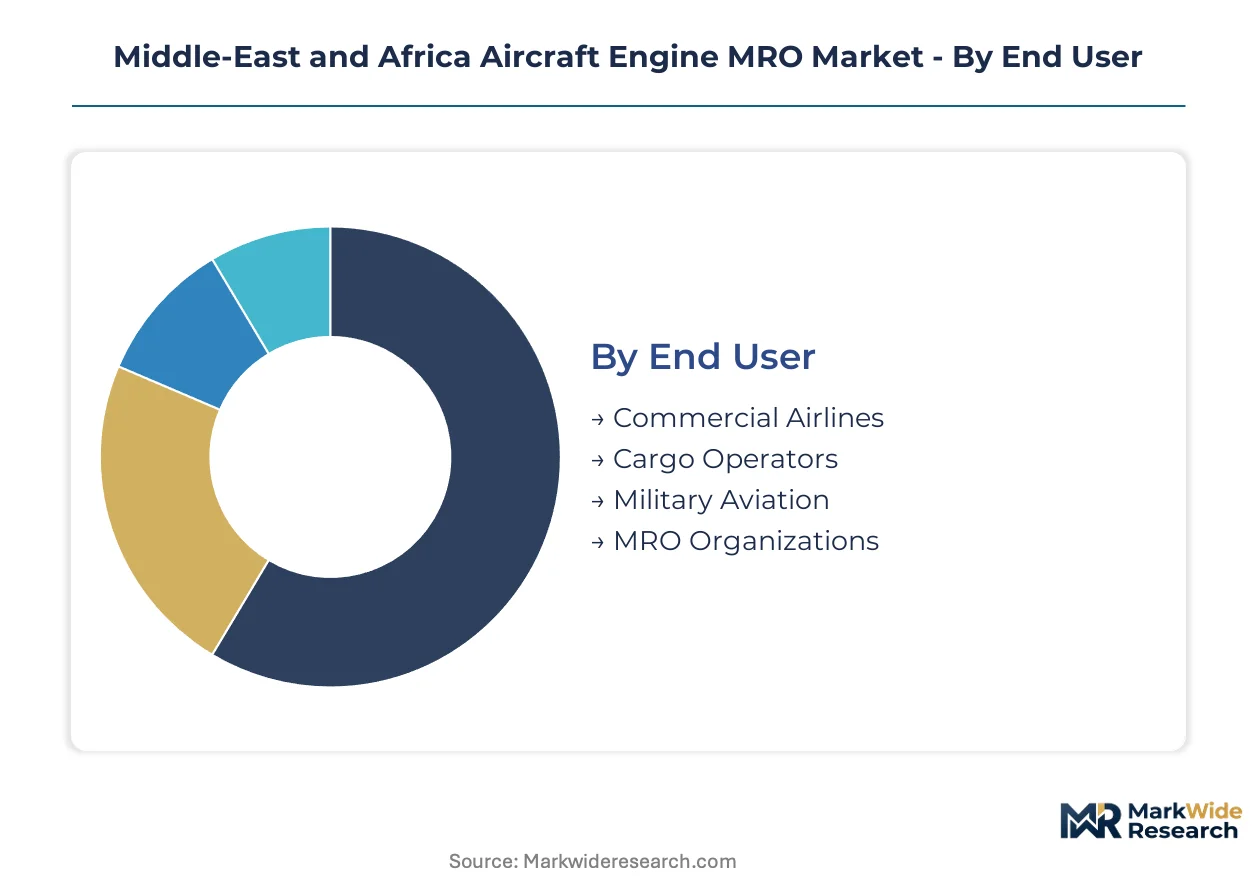
Aircraft engine MRO segmentation reveals distinct procurement patterns across operator types and powerplant technologies. Each axis shapes facility investment priorities and service portfolio design differently.
End User:
Operator business models dictate overhaul scheduling, contract structures, and geographic preferences for shop placement.
- Commercial Airlines:Full-service carriers generate scheduled shop visit demand for high-bypass turbofans at Dubai and Istanbul overhaul clusters. Fleet scale enables power-by-the-hour contracts that transfer residual value risk to MRO providers.
- Cargo Operators:Freighter fleets concentrate in Addis Ababa and Nairobi, driving wide-body engine overhaul demand with compressed turnaround requirements. E-commerce volume growth is accelerating heavy maintenance cycles for converted 767-300ER and A330-200P2F powerplants.
- Military Aviation:Royal Saudi Air Force and UAE Armed Forces sustain captive maintenance infrastructure with classified component handling protocols.
- MRO Organizations:Independent providers compete on narrow-body specialization across Jordan and Egypt with cost-competitive turnaround cycles.
Commercial airlines lead on scale; cargo operators lead on momentum.
Service Type:
Service intensity correlates directly with engine cycle accumulation and regulatory compliance thresholds.
- Overhaul:Complete disassembly, inspection, and reassembly of gas turbine powerplants restores thrust output and cycle-life compliance. Demand clusters in UAE test cell facilities for V2500 and GEnx powerplants.
- Repair:Precision machining of high-pressure compressor blades and thermal barrier coating refurbishment addresses specific component degradation without full module replacement.
- Maintenance:Line maintenance and A-check engine servicing sustain on-wing intervals for low-cost carrier fleets across Saudi Arabia and Egypt.
- Component Replacement:Life-limited part exchanges require documented traceability per GCAA and EASA airworthiness directives.
Overhaul commands the highest revenue per event; predictive-enabled maintenance is expanding most quickly.
Engine Type:
Powerplant architecture determines facility tooling requirements and technician specialization profiles.
- Jet Engines:High-bypass turbofan rebuilds for A320neo and 737 MAX fleets capture the largest value pool given OEM-controlled parts pricing and test cell infrastructure requirements.
- Turboprop Engines:PT6A and PW100 overhauls serve regional connectivity fleets in East Africa with lower capital barriers to entry.
- Turbojet Engines:Legacy military and business jet powerplants sustain niche demand in Saudi Arabia and UAE defense sectors.
- Auxiliary Power Units:GTCP and APS3200 servicing supports ground power reliability for hub airport operations at Jeddah and Dubai.
Jet engines dominate revenue concentration; turboprop services offer the steepest expansion trajectory in underserved East African markets.
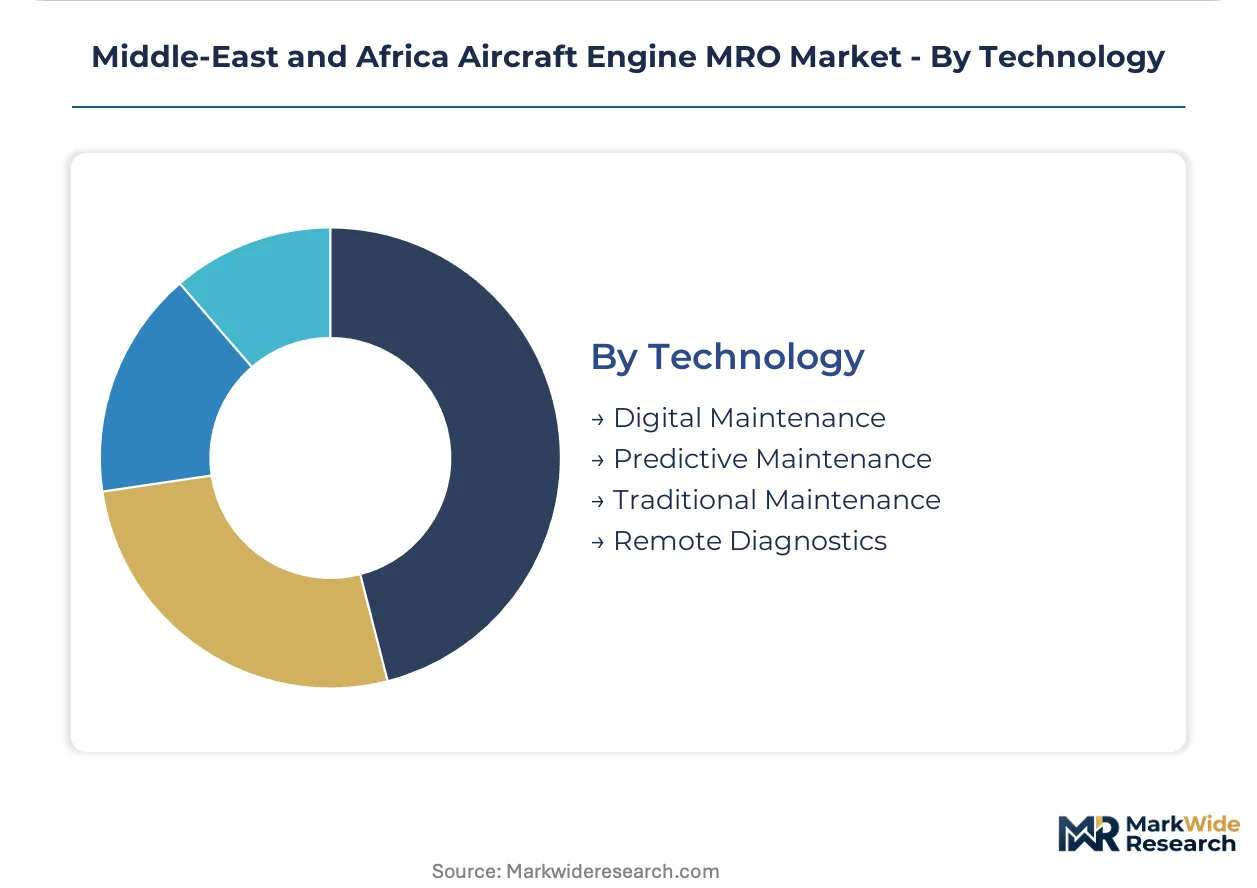
Technology:
Diagnostic capability redistribution is altering value capture between OEMs and independent providers.
- Digital Maintenance:Integrated fleet management platforms consolidate work scope planning across multi-operator maintenance programs. Emirates Engineering deploys proprietary systems at Al Maktoum International.
- Predictive Maintenance:Vibration analysis and oil-debris monitoring extend on-wing intervals for Saudi low-cost carrier A320neo fleets.
- Traditional Maintenance:Scheduled hard-time overhauls persist for legacy engine types and regulatory-conservative operators.
- Remote Diagnostics:Real-time sensor data transmission enables pre-positioning of replacement components at outstations across the Levant.
Digital maintenance anchors current investment; predictive systems are gaining share fastest among new-technology engine fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing engine overhaul capacity toward jurisdictions with streamlined certification pathways. The UAE and Turkey capture European operator overflow through EASA bilateral recognition, while East African markets remain underserved for wide-body powerplant services.
United Arab Emirates
Dubai International and Al Maktoum International anchor the region's densest test cell infrastructure for high-bypass turbofan validation. GCAA traceability mandates for life-limited components accelerate documentation standardization across Emirates Engineering and third-party facilities. Abu Dhabi's industrial zone clusters specialized thermal barrier coating refurbishment capacity serving Saudi and Qatari operator fleets.
Saudi Arabia
Riyadh-based low-cost carriers are deploying predictive maintenance sensors across A320neo and 737 MAX fleets to extend on-wing intervals. The Saudi General Authority of Civil Aviation enforces airworthiness directives aligned with EASA protocols for cross-border engine acceptance. Jeddah's King Abdulaziz International hosts expanding MRO infrastructure targeting narrow-body shop visit demand from regional cargo operators.
Turkey
Istanbul's overhaul cluster captures European operator volume through mutual recognition certificates under expanded EASA bilateral frameworks. Turkish Technic maintains capacity for V2500 and LEAP-1B powerplants serving Middle Eastern low-cost carrier overflow. Ankara's regulatory alignment with GCAA standards facilitates engine acceptance documentation for UAE-registered aircraft.
South Africa
Johannesburg-based facilities face technician scarcity for precision machining of high-pressure compressor blades despite SACAA certification requirements. The South African Civil Aviation Authority mandates documented traceability matching GCAA standards for life-limited component exchanges. Cape Town's maintenance infrastructure concentrates on turboprop overhauls for regional connectivity fleets rather than jet engine rebuilds.
Egypt
Cairo International Airport generates narrow-body engine shop visit demand from expanding low-cost carrier operations across North Africa. Egyptian civil aviation regulations require repair station accreditation mirroring EASA technical standards for component overhaul acceptance. Joramco's Amman facility serves Egyptian operator overflow, though indigenous test cell capacity remains limited for full-throttle validation.
Middle-East and Africa Aircraft Engine MRO Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM-affiliated providers commanding high-bypass turbofan overhauls while independent specialists capture narrow-body volume. The vendor base concentrates around Dubai and Istanbul test cell clusters, creating tiered access based on certification scope. Three archetypes dominate: OEM-captive facilities with vertical integration advantages, independent narrow-body specialists competing on turnaround speed, and European-anchored providers leveraging bilateral recognition for overflow capture. Capacity expansion and strategic partnerships represent the dominant competitive vectors as facilities seek to bridge East African coverage gaps.
Within the OEM-captive tier, GE Aviation and Rolls-Royce anchor proprietary overhaul networks controlling high-value component sourcing. Emirates Engineering exemplifies airline-integrated maintenance scale at Al Maktoum International. Among independent specialists, Joramco occupies a position serving Levant and East African markets with cost-competitive narrow-body focus.
| Leading Market Players |
|---|
| GE Aviation |
| Rolls-Royce |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Emirates Engineering |
| Lufthansa Technik |
| CFM International |
| Joramco |
| Turkish Technic |
| Others |
Supply & Pricing Matrix
Power-by-the-hour contract proliferation among Saudi low-cost carriers is compressing standalone overhaul margins and forcing suppliers to bundle residual value risk into long-term service agreements. This procurement shift concentrates buying power with fleet managers and redistributes pricing pressure across component sourcing and test cell utilization tiers.
Pricing Analysis
Direct-to-OEM discount structures dominate high-bypass turbofan overhauls, with GE Aviation and Rolls-Royce capturing margin through proprietary high-pressure compressor blade sourcing. Price differentiation rests on EASA certification tier and volume scale, with bilateral-recognized UAE facilities commanding premium rates over Egyptian and Jordanian competitors. Cost compression in narrow-body services is intensifying because independent specialists compete on turnaround speed. Cargo operators in East Africa exhibit highest price sensitivity due to limited test cell alternatives, while Emirates Engineering captive maintenance shows lowest sensitivity given vertical integration advantages.
Supply Chain Analysis
EASA-GCAA mutual recognition certificates gate component traceability for life-limited parts, concentrating qualified supplier networks in the UAE, Turkey, and Germany. Raw material dependencies center on nickel-based superalloys for thermal barrier coatings, precision-forged titanium compressor blades, and specialized high-temperature sealants. Single-source vulnerability runs through OEM-controlled proprietary component sourcing for LEAP-1B and GEnx powerplants. Distribution runs through hub-and-spoke logistics anchored at Dubai International and Istanbul Airport free trade zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as predictive maintenance sensor deployment shifts procurement preference toward digitally integrated overhaul providers with real-time fleet analytics capabilities.
For Market Incumbents: Acquire test cell infrastructure in underserved East African markets to preempt Ethiopian Airlines and Nairobi-based cargo operator demand. Consolidate thermal barrier coating refurbishment capacity in Abu Dhabi's industrial zone to capture Saudi and Qatari fleet overflow. Defend against independent narrow-body specialists by embedding predictive analytics into power-by-the-hour contracts. For New Entrants and Emerging Players: Enter via EASA bilateral recognition pathway to serve European operator overflow at Turkish and Emirati facilities. Target turboprop overhaul white space in East African regional connectivity markets where PT6A and PW100 service gaps persist. Pursue component-level specialization in precision machining rather than full engine rebuild capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with independent MRO providers holding EASA-GCAA dual certification and narrow-body specialization in Levant markets. Five-to-ten year viability favors facilities with established technician pipelines and test cell infrastructure rather than greenfield entrants facing multi-year accreditation timelines. Monitor GCAA-SACAA regulatory convergence as inflection signal for South African market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Test Cell Infrastructure Expansion | Full-throttle validation capacity at Al Maktoum International captures GEnx and V2500 demand from Saudi operators. |
| Predictive Maintenance Platform Integration | Real-time oil-debris monitoring deployment across A320neo fleets extends on-wing intervals for Emirates Engineering. |
| EASA Bilateral Certification Investment | Mutual recognition certificates enable Turkish Technic to serve European-registered aircraft overflow. |
| East African Market Entry | Addis Ababa and Nairobi cargo hub penetration addresses underserved wide-body engine overhaul demand. |
| Technician Pipeline Development | Specialized thermal barrier coating training programs alleviate scarcity constraints across Saudi Arabia and South Africa. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MRO operations directors, airline fleet managers, GCAA regulatory affairs leads, and engine OEM aftermarket strategists with secondary validation through EASA airworthiness directive databases, GCAA certification registries, and customs trade data on aircraft engine component flows. Bottom-up facility capacity modeling and top-down operator fleet projections were triangulated against bilateral agreement documentation between European and Gulf regulators.
Historical reference periods anchored the forecast window to established shop visit cycles and fleet renewal timelines across the projection horizon. Segmentation dimensions modeled include end-user business model, service type intensity, engine architecture category, and technology adoption tier. CAGRs were derived from capacity utilization trends and regulatory alignment trajectories. Forecast inputs incorporated narrow-body fleet expansion rates in Saudi Arabia and predictive maintenance sensor penetration across UAE-based operators.
Inputs from GCAA certification databases and EASA bilateral agreement records were available through the study window; gaps in proprietary OEM parts pricing data introduce uncertainty bands around independent MRO margin projections. Forecasts reflect documented assumptions on regulatory convergence timing and technician training pipeline development. A model refresh is warranted upon material change in EASA-GCAA mutual recognition certificate issuance velocity or Saudi low-cost carrier fleet expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market