
 GCC Drone Pilot Training Market | 2026-2036
GCC Drone Pilot Training Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Drone Pilot Training Market Insights
Certification-tier instruction is rotating toward advanced unmanned aerial system credentials as energy and logistics operators raise hiring standards. Sanad Academy leverages its Dubai-based fleet of multi-rotor and fixed-wing platforms to anchor emirate-level training contracts. FalconViz sustains its position through geospatial analytics integration, while Prince Sultan Aviation Academy competes via military-adjacent curriculum pathways that extend into civilian certification streams.
GCC drone pilot training encompasses structured instruction in unmanned aircraft operation, airspace navigation protocols, and payload-specific mission planning, typically requiring 40–200 flight hours depending on certification tier. The primary commercial purpose is to produce operators capable of executing beyond-visual-line-of-sight surveys for infrastructure, agriculture, and emergency response sectors. Certification Programs currently command premium pricing due to regulatory mandates from aviation authorities across the Gulf states, while Specialized Courses in thermographic inspection and LiDAR mapping represent the fastest-expanding enrollment category. Commercial Operators dominate end-user demand, though Government Agencies are deepening procurement of sovereign training capacity.
The UAE General Civil Aviation Authority, Saudi Arabia's General Authority of Civil Aviation, and Qatar's Civil Aviation Authority each enforce distinct remote pilot licensing frameworks that shape curriculum design and instructor qualification thresholds. Compliance with these national aviation regimes determines market access for training providers and dictates minimum simulator-to-live-flight ratios. Stakeholders must monitor harmonization pressures between national licensing systems and emerging GCC-wide unmanned aircraft protocols.
Market Dynamics
Regulatory mandates from Saudi Arabia's General Authority of Civil Aviation and the UAE General Civil Aviation Authority are compressing training timelines while elevating simulator-to-live-flight ratios, forcing providers to restructure curriculum delivery around sovereign certification tiers rather than generic instruction modules.
Growth Catalysts
- Beyond-visual-line-of-sight mandates:Saudi Arabia's General Authority of Civil Aviation now requires BVLOS certification for pipeline inspection contracts, pulling operators into advanced credential programs.
- Qatar:The Civil Aviation Authority's remote pilot licensing framework is tightening instructor qualification thresholds, creating captive demand for accredited training centers.
- Thermographic inspection:Oilfield operators across the GCC are embedding thermal payload proficiency into procurement specifications, accelerating enrollment in specialized sensor courses.
Market Restraints
- Simulator hardware costs:High-fidelity flight simulation systems sourced from European manufacturers inflate upfront capital requirements for new market entrants.
- Instructor scarcity:Qualified trainers holding both military aviation backgrounds and civilian unmanned systems credentials concentrate in Dubai and Riyadh, limiting geographic expansion.
- Regulatory fragmentation:Divergent licensing frameworks between the UAE, Saudi Arabia, and Qatar prevent curriculum standardization and inflate compliance overhead.
Strategic Opportunities
- Oman:The Sultanate's nascent civil aviation regulations for unmanned systems present first-mover positioning before mandatory licensing takes effect.
- LiDAR mapping convergence:Surveying firms are bundling point-cloud analysis training with pilot certification, creating premium course tiers.
- Kuwait:Government procurement of sovereign drone capacity for border security is generating demand for military-to-civilian crossover instruction.
Industry Challenges
- Certification timeline compression:Operators seeking rapid workforce deployment struggle with the 40-200 flight hour variance across GCC national frameworks.
- Curriculum-hardware synchronization:Training fleets must refresh annually to match evolving commercial drone platforms, straining capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Drone Pilot Training Market |
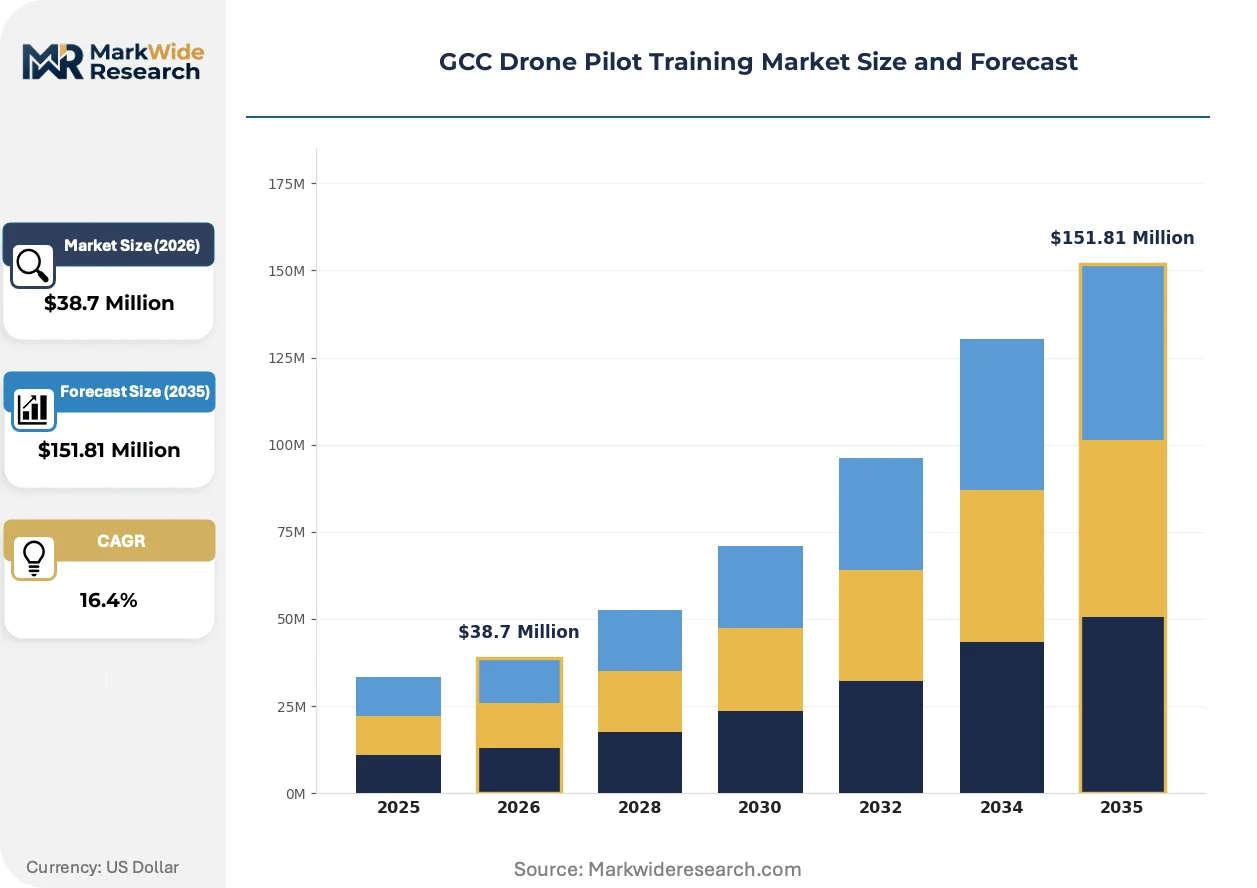
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $151.81 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Basic Training, Advanced Training, Certification Programs, Specialized Courses End User: Commercial Operators, Government Agencies, Military, Hobbyists Course Duration: Short-term, Medium-term, Long-term, Flexible Certification Level: Beginner, Intermediate, Expert, Professional |
| Companies Covered | FalconViz, Emirates Flight Training Academy, The Drone Centre, Prince Sultan Aviation Academy, Etihad Aviation Training, Aerodyne Geospatial, UAV Coach, Sanad Academy, Gulf Air Academy, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Drone Pilot Training Market Trends and Innovations
Instructional delivery across the GCC is pivoting from classroom-centric models toward integrated simulator-live flight sequences, with regulatory bodies now mandating minimum synthetic training hours before airspace access.
Virtual reality flight simulation is decomposing traditional two-phase training structures. Saudi Aramco contractor fleets now require VR pre-certification before live platform hours. This compression is collapsing the historical 6-month training cycle into 8-week intensive modules.
The UAE General Civil Aviation Authority's 2024 remote pilot competency framework is forcing curriculum recertification every 24 months. Training providers must now submit instructor flight logs for audit. Energy sector procurement teams are screening vendor compliance against this rolling mandate.
Certification-driven purchasing is displacing price-based selection in drone service procurement. Saudi pipeline operators now weight pilot credential tiers above hourly rates in vendor scorecards. This preference shift concentrates contract awards with training-integrated service providers in the Eastern Province.
GCC Drone Pilot Training Market Segmentation
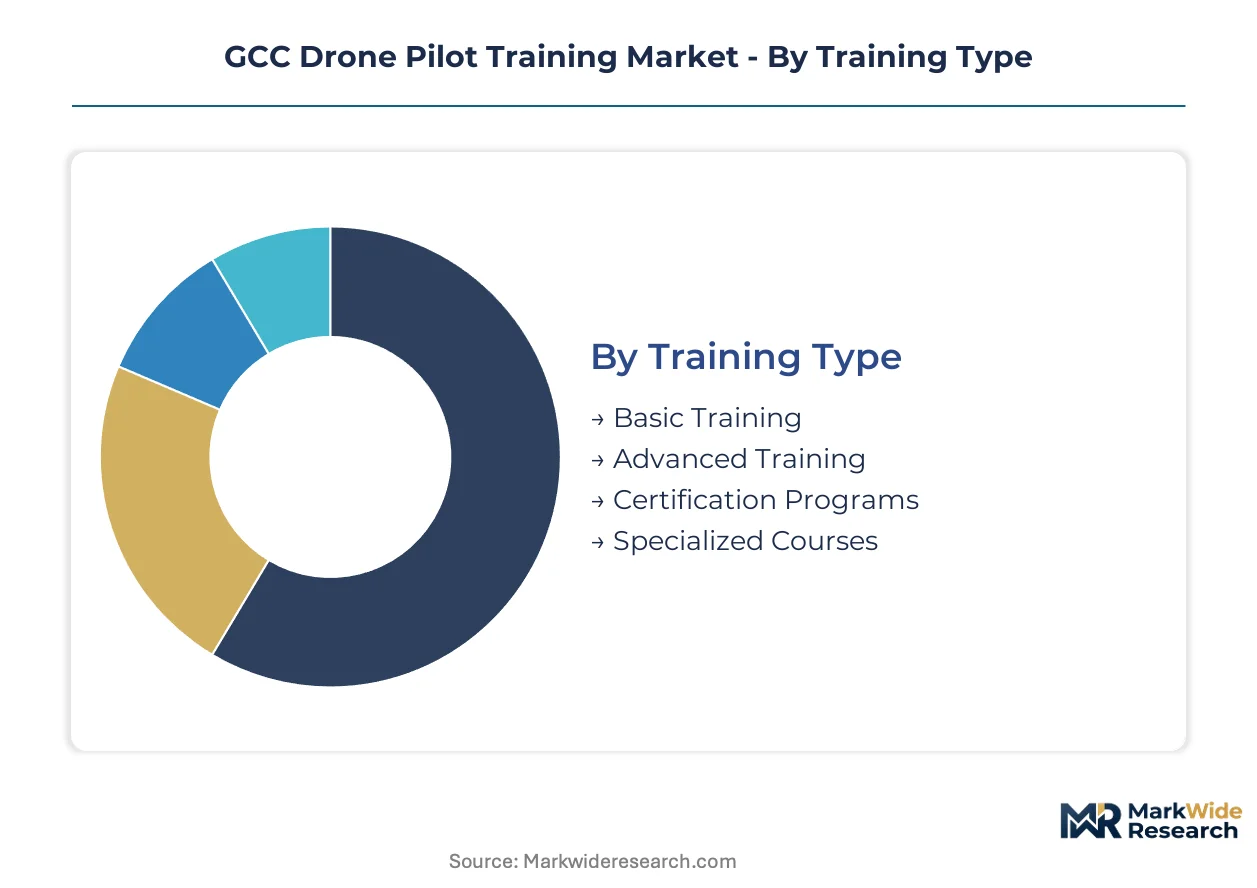
Training providers in the GCC structure curriculum offerings around sovereign aviation mandates that dictate flight hour minimums and simulator ratios. Segment boundaries reflect how Saudi Arabia's General Authority of Civil Aviation and the UAE General Civil Aviation Authority tier their remote pilot licensing frameworks.
Training Type:
Margin pools concentrate in advanced credential streams where energy sector procurement mandates BVLOS certification.
- Certification Programs:Structured curricula delivering sovereign-compliant remote pilot licenses with mandated simulator-to-live-flight ratios. Saudi Aramco contractor fleets now require these credentials before airspace access, compressing traditional training timelines into intensive 8-week modules.
- Specialized Courses:Payload-specific instruction in thermographic inspection and LiDAR mapping for infrastructure surveyors. Oilfield operators across the Eastern Province embed thermal proficiency into procurement specifications, accelerating enrollment in these sensor-focused tiers.
- Advanced Training:Beyond-visual-line-of-sight and multi-rotor coordination for commercial fleet operators.
- Basic Training:Entry-level unmanned aircraft operation and airspace navigation protocols for new entrants.
Certification Programs hold installed capacity. Specialized Courses are rotating up the share rankings.
End User:
Procurement volume splits between sovereign capacity builders and commercial service contractors.
- Commercial Operators:Energy, logistics, and surveying firms certifying pilot workforces for contract eligibility. Pipeline operators in Saudi Arabia now weight credential tiers above hourly rates in vendor scorecards, concentrating awards with training-integrated providers.
- Government Agencies:National ministries acquiring sovereign drone capacity for border security and emergency response. Kuwait's government procurement of border security systems is generating demand for military-to-civilian crossover instruction pathways.
- Military:Defense establishments transitioning personnel into civilian certification streams.
- Hobbyists:Recreational operators seeking baseline airspace compliance credentials.
Commercial Operators anchor current enrollment. Government Agencies are climbing the fastest.
Course Duration:
Regulatory fragmentation across GCC aviation authorities prevents standardization of training cycle length.
- Short-term:Compressed modules under 40 flight hours for rapid workforce deployment.
- Medium-term:Standard certification cycles aligned with UAE GCAA competency frameworks.
- Long-term:Extended curricula incorporating VR pre-certification and multi-platform proficiency.
- Flexible:Modular scheduling accommodating rotational oilfield workforces in the Eastern Province.
Medium-term holds installed capacity. Short-term is rotating up the share rankings.
Certification Level:
Curriculum design must synchronize with rolling 24-month recertification mandates from the UAE General Civil Aviation Authority.
- Professional:Expert-tier credentials with instructor audit requirements and flight log submissions. Energy sector procurement teams screen vendor compliance against these rolling mandates.
- Expert:Advanced mission planning and payload integration for geospatial analytics firms.
- Intermediate:Visual-line-of-sight expansion and basic payload operation.
- Beginner:Foundation unmanned systems theory and simulator orientation.
Professional holds installed capacity. Expert is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Training capacity concentrates in the UAE and Saudi Arabia, where sovereign aviation mandates and energy sector procurement create captive demand. The remaining GCC states present sequential entry opportunities as licensing frameworks mature.
Saudi Arabia
Saudi Aramco contractor fleets now require BVLOS certification before airspace access, compressing training cycles into intensive modules. The General Authority of Civil Aviation mandates simulator-to-live-flight ratios that elevate curriculum costs. Riyadh and the Eastern Province host the densest training center clusters, where pipeline operators weight credential tiers above hourly rates in procurement scorecards.
United Arab Emirates
Dubai-based energy and logistics operators are raising hiring standards for advanced unmanned aerial system credentials. The General Civil Aviation Authority's 2024 remote pilot competency framework forces curriculum recertification every 24 months with instructor flight log audits. Sanad Academy anchors emirate-level contracts through its multi-rotor and fixed-wing fleet infrastructure.
Qatar
The Civil Aviation Authority's remote pilot licensing framework is tightening instructor qualification thresholds, creating captive demand for accredited centers. Thermographic inspection proficiency is embedding into oilfield procurement specifications. Doha concentrates enrollment growth as survey firms bundle point-cloud analysis with pilot certification.
Oman
The Sultanate's nascent civil aviation regulations for unmanned systems present first-mover positioning before mandatory licensing takes effect. Border security and infrastructure inspection applications are driving early commercial pilot demand. Muscat is emerging as the primary training hub as operators anticipate regulatory alignment with neighboring frameworks.
Kuwait
Government procurement of sovereign drone capacity for border security is generating demand for military-to-civilian crossover instruction. The national aviation regulator is developing remote pilot licensing frameworks modeled on Saudi and UAE precedents. Kuwait City hosts the initial training infrastructure as defense contractors transition personnel into civilian certification streams.
GCC Drone Pilot Training Market Competitive Landscape
Concentration sits with aviation-academy-affiliated providers and specialized geospatial training firms. The market structure is tiered, with sovereign-contract-holding institutions commanding premium positioning and independent operators competing on course modularity. Three archetypes dominate: military-adjacent academies leveraging defense infrastructure, commercial drone service providers with captive training arms, and standalone certification centers focused on rapid workforce deployment. Competitive moves center on curriculum-hardware synchronization and strategic partnerships with energy sector procurement teams.
Within the aviation-academy tier, Emirates Flight Training Academy and Etihad Aviation Training exemplify carrier-backed institutions with integrated simulator infrastructure. Prince Sultan Aviation Academy occupies a position bridging military and civilian certification pathways. Sanad Academy anchors the commercial-specialist segment through Dubai-based fleet resources. FalconViz represents the geospatial-analytics-integrated archetype, where training bundles with surveying service contracts.
| Leading Market Players |
|---|
| FalconViz |
| Emirates Flight Training Academy |
| The Drone Centre |
| Prince Sultan Aviation Academy |
| Etihad Aviation Training |
| Aerodyne Geospatial |
| UAV Coach |
| Sanad Academy |
| Gulf Air Academy |
| Others |
Pricing and Supply Chain Analysis
Virtual reality simulation hardware replacing European-sourced flight training systems is redrawing procurement geography toward Asian electronics manufacturing hubs while compressing per-student equipment amortization costs across GCC training centers.
Pricing Analysis
The UAE General Civil Aviation Authority's 2024 remote pilot competency framework dictates the pricing tier structure across certification programs. Three-tier pricing separates Professional-grade credentials with instructor audit requirements from Intermediate visual-line-of-sight modules and Beginner simulator orientation. Price differentiation hinges on certification level and mandated flight hour ratios, with BVLOS programs commanding premiums due to scarce qualified instructor availability. Pricing pressure stems from simulator hardware cost compression as Asian manufacturers enter the flight training equipment market, though energy sector procurement teams show lowest price sensitivity when screening vendor compliance against rolling recertification mandates.
Supply Chain Analysis
Simulator hardware inventory lead times from European manufacturers stretch 12-18 months, forcing training providers to pre-position equipment ahead of regulatory mandate effective dates. Geographic supply concentration centers on Germany, France, and China for high-fidelity flight simulation systems. Raw material dependencies span aerospace-grade aluminum airframes, lithium-ion battery packs, and precision gyroscopic sensors. Single-source vulnerability runs through specialized motion platform actuators sourced from a consolidated vendor base. Distribution runs through direct OEM relationships for fleet-scale purchases and regional distributors for spare parts and maintenance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC drone pilot training market is recovering from pandemic-disrupted certification backlogs as energy sector procurement of sovereign drone capacity accelerates workforce credentialing cycles.
For Market Incumbents: Shield market position by deepening instructor certification pipelines through military-to-civilian crossover partnerships, as qualified trainer scarcity concentrates competitive advantage in Dubai and Riyadh. Pursue backward integration into VR simulation hardware through technology licensing agreements to offset European OEM pricing power and compress capital deployment timelines for fleet expansion. For New Entrants and Emerging Players: Modular scheduling gaps for rotational oilfield workforces in Saudi Arabia's Eastern Province represent the most penetrable service layer, as incumbent providers optimize for full-time enrollment density. Target flexible course duration segments with compressed 8-week intensive modules aligned to Saudi Aramco contractor procurement windows. Go-to-market leverage rests on direct engagement with energy sector procurement teams rather than traditional aviation academy channel relationships. For Investors and Strategic Acquirers: Oman's transition from nascent to mandatory unmanned systems licensing reshapes the acquisition landscape by creating first-mover positioning ahead of regulatory harmonization with Saudi and UAE frameworks. Long-term viability favors training-integrated service providers with captive energy sector contracts over standalone certification centers exposed to price-based competition. Monitor instructor qualification threshold tightening across Qatar's Civil Aviation Authority as the signal indicating regulatory convergence momentum.| Strategic Initiative | Industry Significance |
|---|---|
| VR Simulation Hardware Partnership | Reduces equipment lead times from European suppliers while lowering per-student capital intensity. |
| Energy Sector Procurement Integration | Aligns curriculum design with Saudi Aramco contractor credential requirements for contract eligibility. |
| Instructor Certification Pipeline Investment | Addresses scarcity of trainers holding both military aviation and civilian unmanned systems credentials. |
| Oman Market Entry Positioning | Captures first-mover advantage before mandatory licensing frameworks take regulatory effect. |
| LiDAR Mapping Course Bundling | Creates premium revenue tiers as surveying firms integrate point-cloud analysis with pilot training. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with training academy directors, aviation regulator compliance officers, energy sector procurement managers, and simulator equipment distributors; alongside secondary validation through GCAA and GACA regulatory filings, customs import records for flight simulation hardware, and energy sector contractor procurement databases. Bottom-up enrollment volume estimates triangulated against top-down market sizing from sovereign aviation authority licensing statistics.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning training type, end-user category, course duration tier, and certification level aligned to national regulatory clusters. CAGRs derived from enrollment trajectory analysis and pricing elasticity assumptions tied to hardware cost curves. Industry-specific forecast inputs incorporated simulator-to-live-flight ratio mandates and rolling 24-month recertification compliance windows.
Underlying assumptions cover regulatory mandate enforcement consistency and energy sector procurement continuity, with deviation risk concentrated in regulatory harmonization delays between GCC national aviation authorities. Forecasts reflect these baseline conditions, with revision becoming warranted when instructor qualification threshold divergence crosses thresholds that prevent curriculum standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Asia-Pacific Tactical UAV Market
UAV
Europe Tethered Drone Market
UAV
Global Drone Sensor Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Rc Helicopter Market
UAV
Drone Identification System Market
UAV
Global Renewable Drones Market
UAV
Counter Drone System Market
UAV
Drone Delivery Services Market
UAV
Drone Payload Market
UAV
Multirotor Drones Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
UAV Payload Market
UAV
Bubble Drone Market
UAV
Commercial Drone Market