
 Narrowbody Aircraft MRO Market | 2026-2036
Narrowbody Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Narrowbody Aircraft MRO Market Foresight
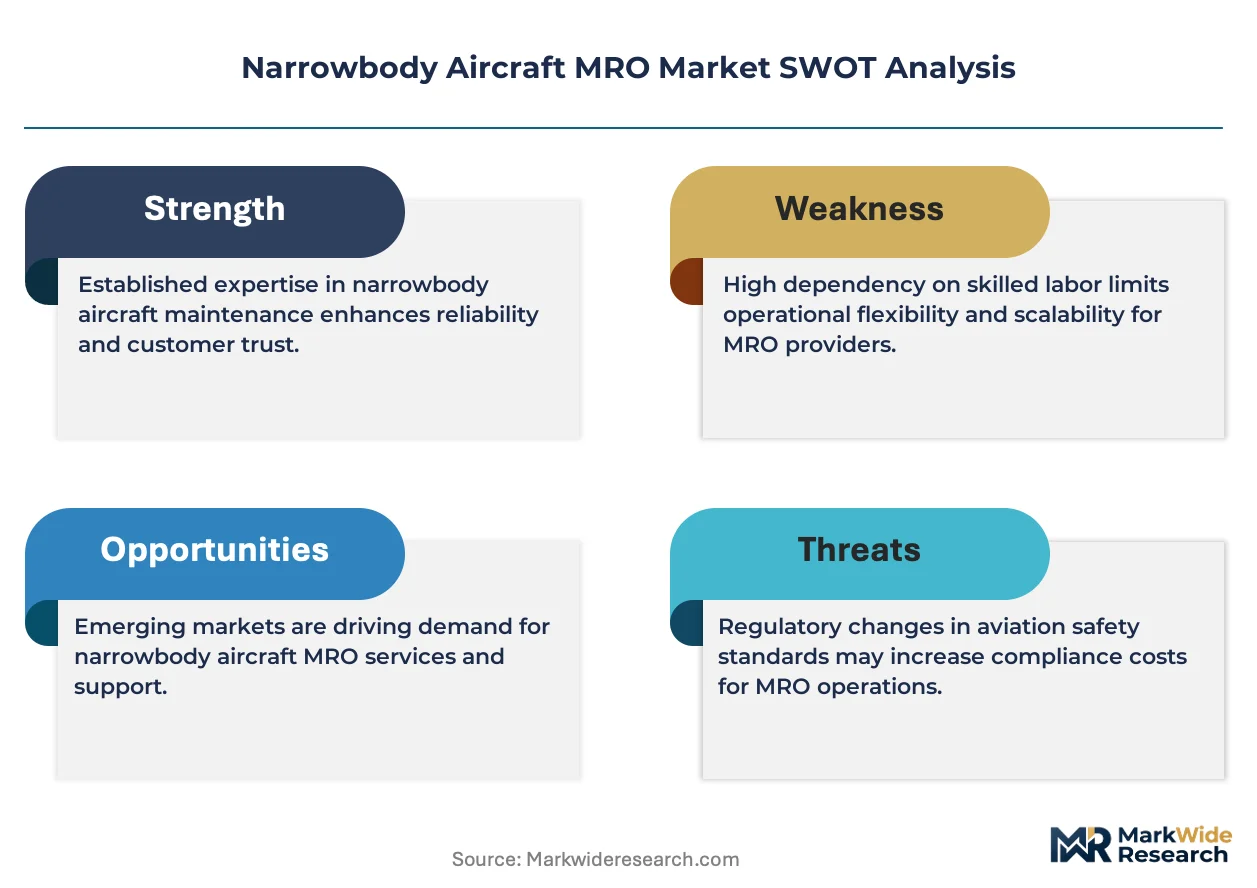
EASA Part 145 certification is redrawing competitive boundaries in narrowbody MRO. Lufthansa Technik leverages its European network to dominate engine services for CFM56 and LEAP powerplants. ST Engineering Aerospace anchors its position through heavy maintenance capacity in Singapore and expanding US footprint. Delta TechOps differentiates via captive airline demand and in-house production of component repairs.
Narrowbody aircraft MRO encompasses the inspection, repair, overhaul, and modification of single-aisle commercial jets typically seating 100-240 passengers, with engine hot-section refurbishment requiring borescope inspection intervals as low as 1,500 flight cycles for high-utilization operators. Engine services commands the deepest margin pools given proprietary tooling requirements and OEM intellectual property controls. Predictive maintenance platforms are displacing traditional hard-time overhauls as airlines seek to optimize turnaround windows and minimize AOG exposure.
FAA Airworthiness Directives and EASA Part M requirements govern overhaul standards and documentation traceability, while CAAC certification gates access to China's expanding narrowbody fleet. Regulatory divergence between FAA and EASA on composite repair protocols forces dual-certification investments for global MRO networks. Stakeholders must monitor how next-generation engine monitoring systems reshape liability frameworks between OEMs and independent repair shops.
Market Dynamics
FAA Airworthiness Directives on LEAP and PW1100G engines are compressing overhaul intervals while low-cost carriers in Southeast Asia push utilization rates to structural limits. This regulatory-demand tension is redrawing capacity allocation across the MRO network.
Growth Catalysts
- Aging Fleet Demographics:Indonesia and Vietnam operate narrowbody fleets exceeding 15 years average age, generating sustained heavy maintenance demand for airframe structural inspections and corrosion prevention programs.
- EASA Part 145 Certification Expansion:European regulatory recognition enables cross-border maintenance approvals, allowing MRO providers to consolidate work packages across multiple jurisdictions without redundant inspections.
- Predictive Maintenance Platforms:Engine health monitoring systems utilizing real-time vibration analysis and oil debris sensors are extending on-wing time between shop visits for high-utilization operators.
Market Restraints
- OEM Intellectual Property Controls:Proprietary tooling and repair schemes for composite fan blades and hot-section components limit independent shop access to margin-rich engine work.
- Specialized Labor Scarcity:Borescope inspection technicians and non-destructive testing specialists require multi-year certification pipelines that lag fleet expansion rates in emerging markets.
- Dual-Certification Burden:Divergent FAA and EASA composite repair protocols force MRO networks to maintain parallel qualification systems, inflating overhead without revenue differentiation.
Strategic Opportunities
- Indonesian Archipelago Logistics:Geographic fragmentation across 17,000 islands creates demand for mobile maintenance units and rapid-response AOG teams serving dispersed low-cost carrier bases.
- CAAC Certification Pathways:China's expanding narrowbody fleet under COMAC C919 and ARJ21 programs offers first-mover advantages for MRO providers achieving civil aviation administration approval.
- Component Repair In-Housing:Airlines with captive MRO divisions are internalizing rotable component overhaul, compressing turnaround times and capturing margin previously flowing to third-party shops.
Industry Challenges
- Legacy System Integration:Paper-based maintenance logs and proprietary OEM software platforms resist interoperability with new predictive analytics systems, forcing expensive middleware development.
- Certification Timeline Compression:EASA Part 145 and FAA repair station approvals require 18-24 month qualification cycles that misalign with airline fleet expansion schedules in high-growth markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narrowbody Aircraft MRO Market |
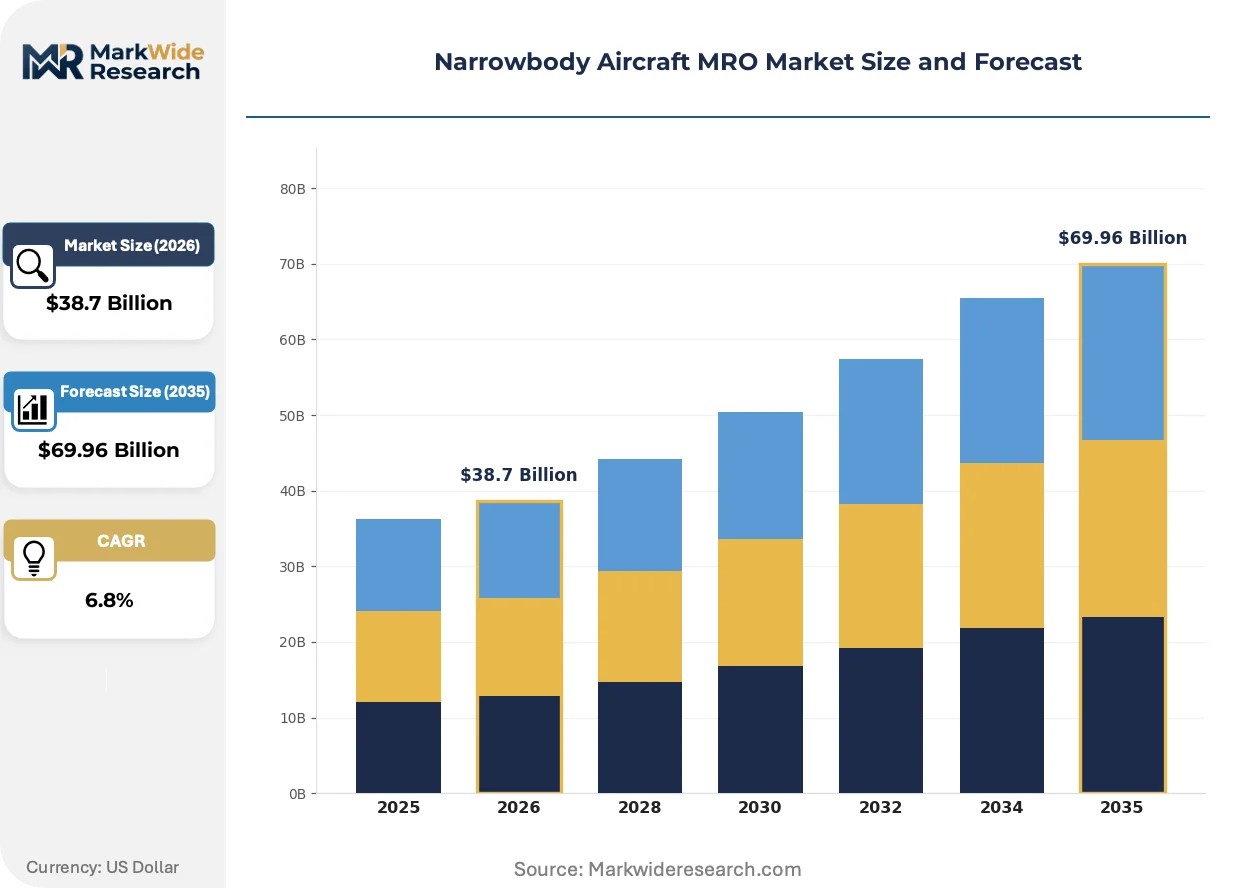
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Line Maintenance, Heavy Maintenance, Component Overhaul, Engine Services End User: Airline Operators, MRO Service Providers, Military Operators, Cargo Airlines Aircraft Type: Single-Aisle Jets, Regional Jets, Cargo Narrowbodies, Others Technology: Predictive Maintenance, Digital Twin, Robotics, AI-Based Solutions |
| Companies Covered | GE Aviation, Lufthansa Technik, ST Engineering Aerospace, AAR Corp, Pratt & Whitney, Delta TechOps, GMF AeroAsia, HAECO, StandardAero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narrowbody Aircraft MRO Market Shifts & Advancements
Predictive analytics and additive manufacturing are restructuring how narrowbody maintenance gets performed, who performs it, and what credentials matter. These shifts are compressing traditional overhaul economics while opening new competitive entry points.
Digital twin technology for engine performance modeling is bifurcating the MRO market between operators with sufficient fleet scale to justify in-house analytics platforms and smaller carriers dependent on OEM-managed services. Full-service airlines with 100-plus narrowbody aircraft are deploying proprietary algorithms to optimize shop visit timing. Independent repair shops without data science capabilities are losing pricing leverage on power-by-the-hour contracts.
EASA's evolving stance on composite repair substantiation is tightening documentation requirements for carbon fiber laminate restoration. Repair stations must now demonstrate statistical process control across batch-cured adhesive joints. Asian MRO hubs serving European-registered aircraft are investing in automated fiber placement equipment to meet traceability mandates that manual processes cannot satisfy.
Airline procurement departments are unbundling heavy maintenance packages into discrete work scopes awarded through competitive tender. Low-cost carriers in Vietnam and the Philippines now separately contract line maintenance, base checks, and engine overhauls rather than accepting bundled proposals. This fragmentation benefits specialized providers with narrow certification scopes while pressuring full-service MROs to defend position on individual work streams.
Narrowbody Aircraft MRO Market Segmentation
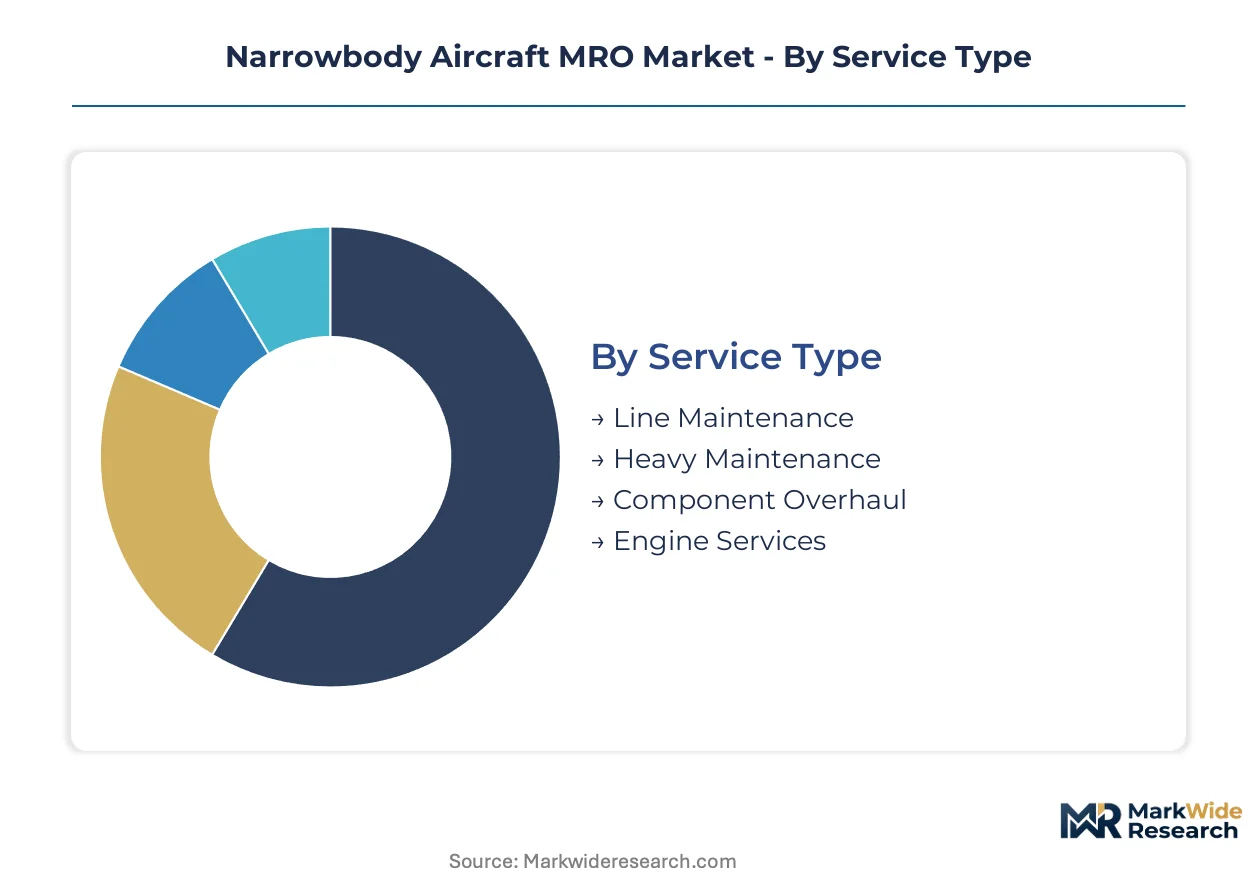
Narrowbody MRO procurement splits along operational criticality and regulatory jurisdiction. Service type determines margin structure, while technology adoption separates fleet-scale operators from dependent regional carriers.
Service Type:
FAA Airworthiness Directives and EASA Part 145 standards create divergent certification requirements across maintenance categories, with engine services commanding the most restrictive proprietary controls.
- Engine Services:Hot-section refurbishment and borescope inspections for LEAP and PW1100G powerplants require OEM-authorized tooling and controlled repair schemes. High-utilization operators in Indonesia and Vietnam compress shop visit intervals to 1,500 flight cycles, concentrating demand at EASA-certified hubs with proprietary access.
- Heavy Maintenance:Structural inspections, corrosion prevention programs, and C-check intervals for aging narrowbody fleets exceed 15 years average age in Southeast Asian markets. Airframe work generates sustained volume but thinner margins than engine services due to lower certification barriers.
- Component Overhaul:Rotable component repair for avionics, landing gear, and hydraulics.
- Line Maintenance:Routine pre-flight checks and minor repairs at operational bases.
Established volume favors heavy maintenance; emerging adoption favors engine services.
End User:
Customer type determines contract structure, with captive airline MRO divisions internalizing work that third-party shops previously captured.
- Airline Operators:Full-service carriers with 100-plus narrowbody fleets deploy proprietary predictive analytics platforms to optimize shop visit timing. Delta TechOps and Lufthansa Technik leverage in-house production of component repairs to compress turnaround windows and capture margin.
- MRO Service Providers:Independent repair stations compete on EASA Part 145 and FAA dual-certification scope, though OEM intellectual property controls limit access to margin-rich engine work. ST Engineering Aerospace anchors capacity in Singapore with expanding US footprint.
- Cargo Airlines:Narrowbody freighter conversions and high-cycle utilization patterns.
- Military Operators:Defense procurement with classified maintenance protocols and sovereign capability requirements.
Airline operators gain share fastest through in-housing; independent MROs defend position on specialized certifications.
Aircraft Type:
Airframe generation determines maintenance intensity, with next-generation composite structures requiring substantiation protocols that manual processes cannot satisfy.
- Single-Aisle Jets:Boeing 737 and Airbus A320 family aircraft dominate fleet counts and generate baseline MRO demand across all service categories.
- Regional Jets:Embraer E-Jets and A220 platforms with lower flight hour accumulation but specialized component ecosystems.
- Cargo Narrowbodies:Converted 737-800SF and A321P2F freighters with high-cycle utilization driving accelerated inspection schedules.
- Others:Out-of-production types and emerging COMAC C919 platforms awaiting mature MRO networks.
Single-aisle jets anchor current volume; cargo narrowbodies show steepest expansion trajectory.
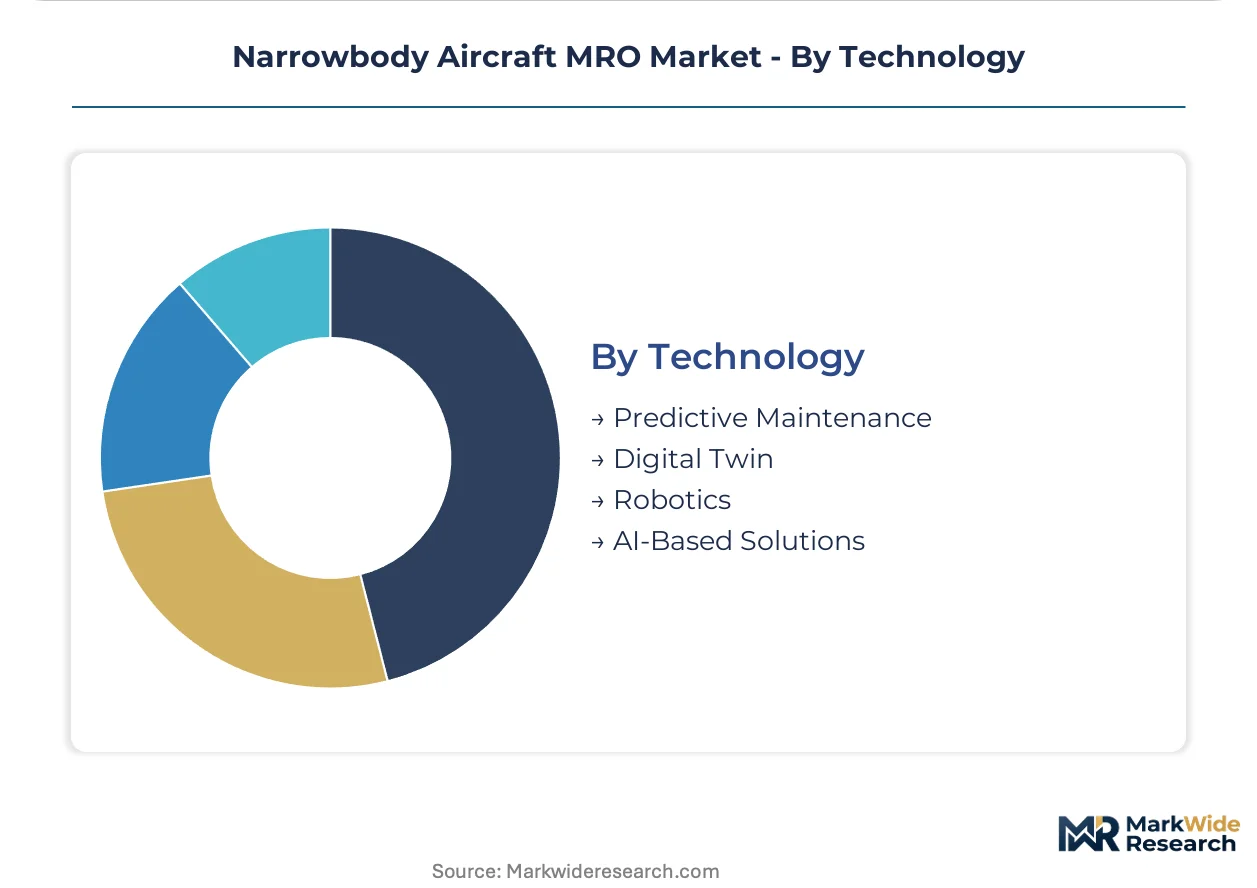
Technology:
Digital capability bifurcates the market between operators with sufficient scale to justify proprietary platforms and smaller carriers dependent on OEM-managed services.
- Predictive Maintenance:Real-time vibration analysis and oil debris sensors extend on-wing time between shop visits. Airlines unbundle heavy maintenance packages into discrete work scopes awarded through competitive tender, displacing traditional hard-time overhauls.
- Digital Twin:Engine performance modeling platforms require data science capabilities that independent repair shops lack, eroding pricing leverage on power-by-the-hour contracts for smaller carriers.
- Robotics:Automated fiber placement equipment for composite repair traceability mandates.
- AI-Based Solutions:Machine learning algorithms for anomaly detection in maintenance logs.
Predictive maintenance holds established adoption; digital twin deployment climbs fastest among fleet-scale operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low-cost carriers dominate narrowbody MRO procurement, with fleet utilization rates and regulatory compliance shaping geographic demand patterns across concentrated operational bases.
Indonesia
Lion Air and Garuda Indonesia subsidiary Citilink operate aging 737-800 and A320 fleets averaging 15-plus years, driving heavy maintenance demand for structural inspections. The country's Directorate General of Civil Aviation enforces airworthiness directives aligned with FAA standards for LEAP engine overhauls. Batam Island hosts GMF AeroAsia's heavy maintenance facility, where capacity expansion targets archipelago-wide AOG response coverage.
Vietnam
VietJet Air and Bamboo Airways push narrowbody utilization to 14 flight hours daily, compressing shop visit intervals for hot-section refurbishment. The Civil Aviation Administration of Vietnam mandates EASA Part 145 equivalent certification for foreign MRO providers serving registered aircraft. Tan Son Nhat International Airport anchors third-party maintenance demand, with independent shops competing for unbundled line maintenance contracts.
Singapore
Changi Airport's hub status concentrates transit maintenance for regional low-cost carriers including Scoot and Jetstar Asia. The Civil Aviation Authority of Singapore maintains bilateral agreements with EASA and FAA for reciprocal certification recognition. Seletar Aerospace Park hosts ST Engineering Aerospace's expanded narrowbody capacity, targeting US market access through acquired facilities.
United States
Delta Air Lines and American Airlines operate captive MRO divisions serving 100-plus narrowbody fleets with proprietary predictive analytics platforms. FAA repair station regulations govern engine overhaul standards, with Airworthiness Directives on PW1100G compressing maintenance intervals. Atlanta and Minneapolis maintenance bases exemplify airline in-housing trends, internalizing component repair previously outsourced to third-party shops.
China
COMAC C919 deliveries and ARJ21 fleet expansion generate MRO network development demand ahead of mature aftermarket infrastructure. CAAC certification gates access to civil aviation maintenance contracts, with type-specific approvals required for new-generation powerplants. Shanghai and Tianjin maintenance clusters concentrate state-affiliated capacity, though foreign joint ventures pursue approval pathways for independent engine services.
Narrowbody Aircraft MRO Market Competitive Landscape
Player mix skews toward full-service airline captives and diversified aerospace conglomerates, with independent specialists defending position on certification scope. Tiered competitive structure separates OEM-authorized engine shops from airframe-heavy generalists. Dominant archetypes include airline-owned MRO divisions, diversified Asian engineering groups, and OEM-affiliated service networks. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with geographic licensing agreements and technology sharing reshaping market access.
Among diversified Asian engineering groups, ST Engineering Aerospace exemplifies regional hub-and-spoke capacity deployment. Lufthansa Technik occupies a position representing European regulatory leverage and OEM-authorized engine access. Delta TechOps anchors the airline-captive archetype, demonstrating how fleet scale justifies in-house production of component repairs. These three entities collectively illustrate how certification scope, geographic footprint, and customer ownership structure differentiate competitive positioning in narrowbody MRO procurement.
| Leading Market Players |
|---|
| GE Aviation |
| Lufthansa Technik |
| ST Engineering Aerospace |
| AAR Corp |
| Pratt & Whitney |
| Delta TechOps |
| GMF AeroAsia |
| HAECO |
| StandardAero |
| Others |
Supply & Pricing Matrix
Ninety-day turnaround windows for LEAP engine overhauls concentrate pricing power at EASA-certified hubs with proprietary tooling access, compressing margins for independent shops lacking OEM authorization while inflating premiums for authorized providers serving Southeast Asian low-cost carriers.
Pricing Analysis
Cost-plus contracts indexed to labor-hour benchmarks and OEM parts tariffs dominate engine services, with power-by-the-hour agreements commanding premiums over transactional overhauls. Price differentiation hinges on EASA Part 145 certification tier and fleet-scale volume commitments, with airlines operating 100-plus narrowbodies extracting steeper discounts than regional operators. Pricing pressure intensifies as airlines unbundle heavy maintenance packages and separately tender line maintenance, base checks, and engine work. Low-cost carriers in Vietnam and Indonesia exhibit highest price sensitivity, captive airline MRO divisions least.
Supply Chain Analysis
Just-in-time inventory strategies govern rotable component flows, though strategic stockpiling of LEAP hot-section parts buffers against FAA Airworthiness Directive-driven demand surges. Supply concentrates in Singapore, Germany, and the United States for proprietary tooling and OEM-authorized repair schemes. Raw material dependencies include nickel-based superalloys, titanium fan blades, and carbon fiber composites. Single-source vulnerability from OEM intellectual property controls on repair documentation forces dual-certification investments. Distribution runs through hub-and-spoke networks anchored at Changi, Frankfurt-Hahn, and Atlanta maintenance clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms are disrupting traditional hard-time overhaul economics, with regulatory compression of LEAP and PW1100G intervals creating urgency for stakeholders to recalibrate capability investments.
For Market Incumbents: Secure OEM-authorized tooling access for next-generation powerplants before independent shops achieve regulatory qualification, while expanding heavy maintenance capacity in Indonesia and Vietnam to capture aging fleet demand. Threat from airlines in-housing component repairs demands backward integration into rotable overhaul production. Certification investment in CAAC pathways offers defensive positioning against Chinese market closure.
For New Entrants and Emerging Players: Differentiate on mobile maintenance units serving Indonesia's archipelago dispersion, where geographic fragmentation creates white-space beyond established hub capacity. Target unbundled line maintenance contracts at Vietnamese airports as entry point, leveraging EASA Part 145 equivalence to bypass full heavy certification timelines. Go-to-market angle emphasizes rapid AOG response versus incumbent turnaround windows.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EASA and FAA certification moats widen as composite repair substantiation tightens. Acquisition archetype: mid-cap independent shops with dual-certification scope but lacking engine proprietary access, positioned for consolidation into diversified networks. Signal to watch is CAAC approval velocity for foreign joint ventures, indicating Chinese market accessibility inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CAAC Certification Investment | Unlocks access to COMAC C919 aftermarket before infrastructure matures. |
| Predictive Analytics Platform Deployment | Enables fleet-scale operators to optimize shop visit timing against OEM service contracts. |
| Mobile Maintenance Unit Expansion | Addresses Indonesian archipelago logistics gaps that fixed hubs cannot serve. |
| Composite Repair Automation | Satisfies EASA traceability mandates that manual fiber placement cannot meet. |
| Component Repair In-Housing | Captures margin previously flowing to third-party shops while compressing turnaround times. |
Research Methodology
Cross-validation between primary interviews with MRO operations directors, airline fleet managers, and regulatory compliance officers and secondary validation against FAA Airworthiness Directive filings, EASA certification databases, and CAAC type approval records anchors the qualitative findings. Bottom-up triangulation aggregates facility-level capacity and utilization data, while top-down verification cross-checks against OEM production forecasts and airline fleet expansion plans disclosed in investor filings.
Sensitivity analysis on utilization rate assumptions and regulatory interval compression scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end-user archetype, aircraft generation, and technology adoption tier. CAGRs derive from fitted growth curves against historical maintenance event frequencies and fleet age demographics. Industry-specific forecast inputs incorporate LEAP and PW1100G shop visit interval trends and EASA evolving composite repair substantiation timelines.
Material uncertainties — OEM intellectual property enforcement intensity, CAAC foreign approval velocity, and predictive maintenance platform adoption curves — sit outside the modeled envelope. Forecasts reflect assumptions on certification timeline standardization and labor pipeline development. Revision becomes warranted when regulatory divergence between FAA and EASA on composite protocols crosses thresholds forcing redundant qualification systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market