
 Global Multiple Launch Rocket Systems Market | 2026-2036
Global Multiple Launch Rocket Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multiple Launch Rocket Systems Market Intelligence
The distinction between high-end, precision-guided systems and lower-cost, high-volume unguided rockets is hardening. This split separates systems designed for strategic effects from those intended for area saturation. Lockheed Martin Corporation dominates the premium segment with its advanced guidance and long-range capabilities. Conversely, companies like Hanwha Corporation and Roketsan Roket Sanayii ve Ticaret A.S. compete effectively by offering cost-efficient, reliable systems to a broader international client base.
A multiple launch rocket system is a mobile artillery platform capable of firing multiple rockets in rapid succession. These systems are typically mounted on wheeled or tracked chassis to ensure high battlefield mobility and survivability. The primary military purpose is to deliver overwhelming firepower for surface-to-surface attack and counter-battery fire missions. Demand for guided rockets with GPS and inertial navigation is outpacing that for traditional unguided variants due to superior accuracy.
Export controls, such as the US International Traffic in Arms Regulations (ITAR), significantly influence market access and technology transfer. NATO Standardization Agreements (STANAGs) dictate interoperability requirements for allied nations, shaping system design and procurement for member states like Germany and Poland. National defense procurement agencies in countries like India and Brazil impose domestic production and technology-sharing mandates. System vendors must navigate these complex, often conflicting, national and alliance-level requirements to secure contracts.
Market Dynamics
The central dynamic is the bifurcation of the market into two distinct classes: high-cost, long-range precision strike systems and affordable, high-volume saturation rockets. This technological and doctrinal split is forcing militaries to make fundamental procurement choices between strategic effects and area denial capabilities.
Growth Catalysts
- Precision Guidance Technology:The integration of GPS and Inertial Navigation Systems (INS) into rockets enhances accuracy, driving demand from armed forces seeking to minimize collateral damage and improve first-hit probability.
- Defense Modernization Programs:National efforts to upgrade or replace aging artillery fleets, particularly in geopolitical hotspots like Poland and South Korea, create a consistent stream of new system orders.
- Alliance Interoperability Mandates:NATO Standardization Agreements (STANAGs) compel member states to procure systems that are compatible with allied munitions and command structures, fueling coordinated acquisition cycles across the alliance.
Market Restraints
- Export Control Regimes:Regulations such as the US International Traffic in Arms Regulations (ITAR) strictly control the transfer of sensitive guidance technology, limiting access for non-allied nations and complicating international co-development.
- High System and Munition Costs:The expense associated with precision-guided rockets and their advanced launchers restricts the quantity that many national defense budgets can afford, limiting overall stockpile depth and training opportunities.
- Logistical and Support Burden:These complex systems require a significant logistical tail, including specialized transport vehicles, maintenance crews, and reload equipment, which can strain the operational capacity of smaller military forces.
Strategic Opportunities
- Integration of Artificial Intelligence:Developing AI-driven fire control software for autonomous target recognition and threat prioritization offers a path to creating more responsive and effective counter-battery and strike systems.
- Emerging Market Modernization:Nations in South America and Southeast Asia, such as Brazil, represent an underpenetrated market for cost-effective rocket artillery systems as they seek to modernize their ground forces.
- Development of Containerized Systems:Designing modular, container-based launchers that can be mounted on ships or standard trucks provides opportunities to expand the system's utility beyond traditional land-based roles.
Industry Challenges
- Legacy System Integration:Ensuring that new digital MLRS platforms can seamlessly communicate with older, analog command-and-control networks presents a significant and costly technical hurdle for many operators.
- Critical Component Bottlenecks:The supply chain for essential components like solid rocket motor propellant and high-performance microelectronics for guidance kits is concentrated, creating vulnerability to disruptions.
- Specialized Talent Shortages:A widening gap exists in the availability of trained technicians and operators who can maintain and effectively employ the increasingly complex software and electronics within modern guided rocket systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multiple Launch Rocket Systems Market |
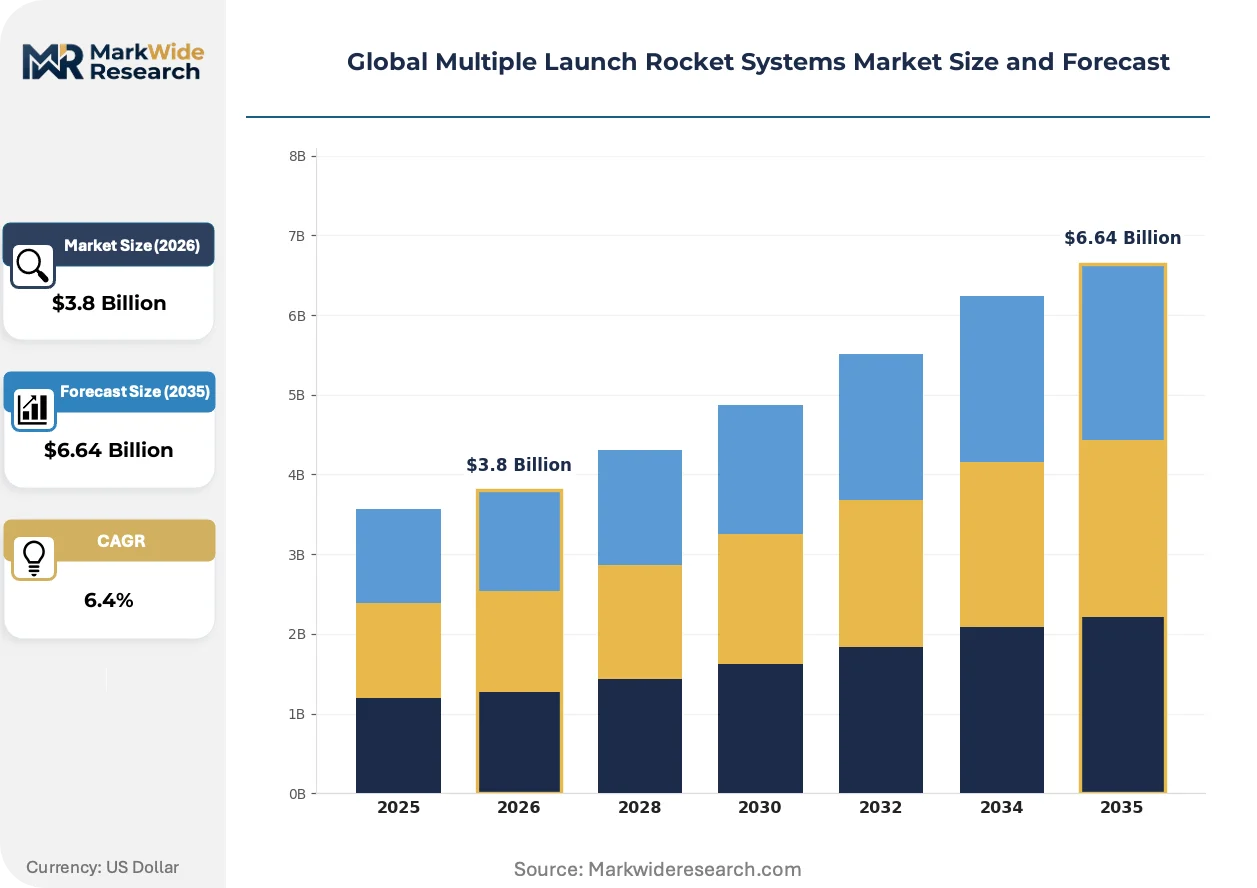
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Towed, Mounted, Wheeled, Tracked Technology: Guided Rockets, Unguided Rockets, GPS-Guided, Inertial Navigation, Laser-Guided Application: Anti-Personnel, Surface-to-Surface Attack, Area Denial, Counter-Battery Fire, Suppression of Enemy Air Defenses End User: Army Combat Units, Artillery Regiments, Special Forces, Paramilitary Groups, Defense Contractors |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, Hanwha Corporation, Roketsan Roket Sanayii ve Ticaret A.S., Elbit Systems Ltd., Avibrás Indústria Aeroespacial, KNDS N.V., IMI Systems Ltd., Diehl Defence GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multiple Launch Rocket Systems Market Strategic Shifts & Innovations
The evolution of multiple launch rocket systems is defined by their transformation from area-denial weapons into flexible, multi-domain assets. This shift is driven by advancements in munitions, software-defined capabilities, and evolving national industrial policies that prioritize technology sovereignty.
Autonomous targeting software integrates data from multiple sensors to identify and prioritize threats without direct human intervention. Advanced army combat units are adopting this capability to dramatically shorten sensor-to-shooter timelines. This software-driven automation is rewriting tactical doctrine, enabling dynamic artillery responses to rapidly changing battlefield conditions.
National industrial participation mandates, exemplified by India's defense procurement policies and similar requirements in Brazil, are intensifying. These regulations compel foreign system vendors to transfer technology and establish in-country manufacturing partnerships to secure contracts. The guided rocket and launcher segments are most impacted, altering business models from direct importation to licensed local production.
A clear preference for modular, multi-role launch platforms is emerging among military planners. This model displaces single-purpose systems with versatile launchers capable of firing a mix of guided rockets and tactical ballistic missiles from a common chassis. This demand for flexibility is most pronounced in recent defense acquisitions by Australia and several Eastern European nations.
Global Multiple Launch Rocket Systems Market Segmentation
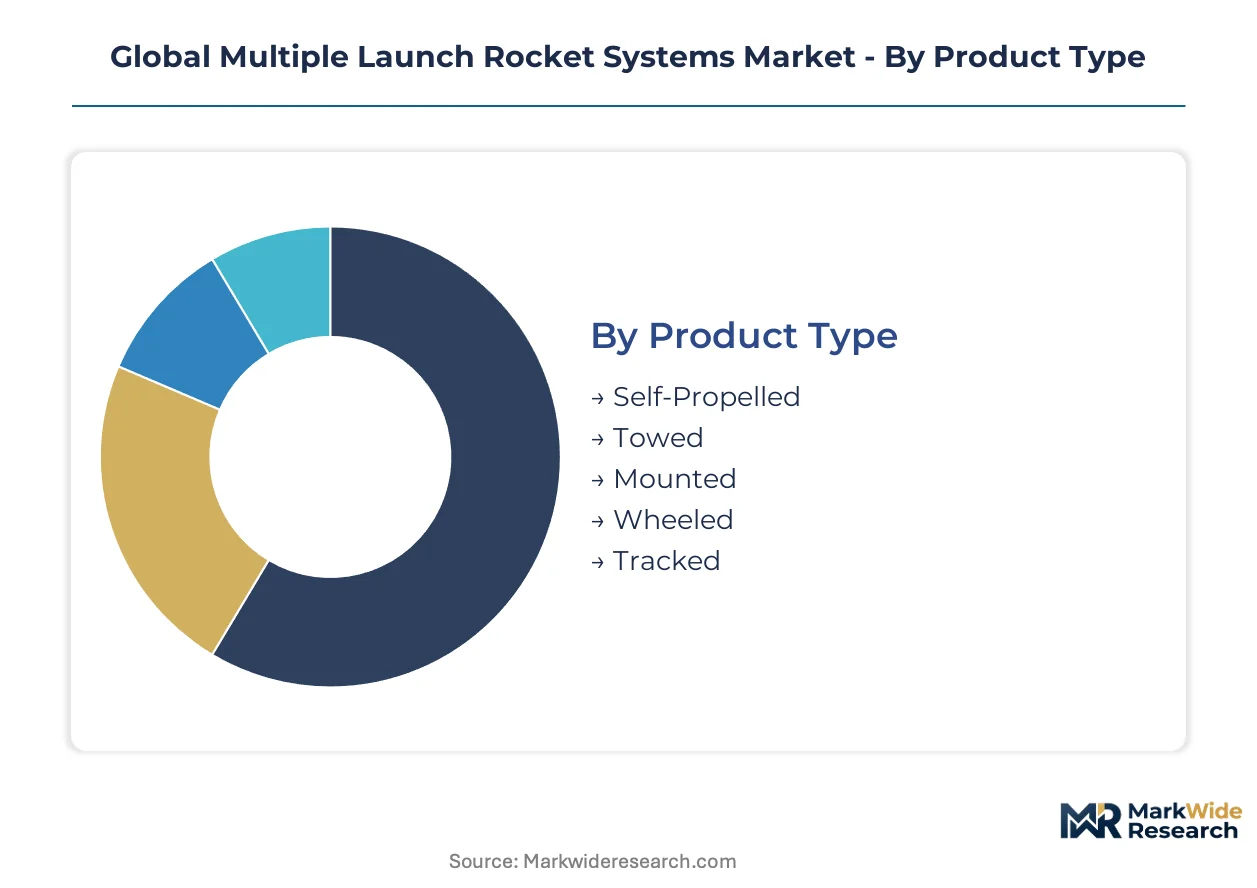
The Global Multiple Launch Rocket Systems Market is precisely categorized to reflect the diverse operational requirements and technological advancements driving procurement decisions. This segmentation highlights the various configurations, guidance systems, tactical applications, and end-user profiles shaping the MLRS industry.
Product Type:
The product type category spans a spectrum from highly customized integrated platforms to more standardized modular solutions, reflecting varied military doctrines and budgetary constraints.
- Self-Propelled:These integrated systems combine the launcher and vehicle, offering high mobility and rapid deployment capabilities. Advanced army combat units in countries like South Korea prioritize self-propelled systems for their shoot-and-scoot tactics.
- Tracked:Mounted on continuous tracks, these systems provide superior off-road performance and enhanced armor protection. Militaries in Poland and Australia favor tracked MLRS for operations in challenging terrains and increased survivability.
- Towed:Requiring a separate prime mover for transport, towed MLRS offer a more cost-effective entry point for defense forces with limited budgets.
- Mounted:This segment includes launchers integrated onto various wheeled or tracked chassis, providing flexibility for different operational needs.
- Wheeled:Chassis offers high road speed and reduced maintenance, making them suitable for rapid deployment across extensive road networks in countries like Germany.
Leading the category by volume: Wheeled. Growing fastest: Self-Propelled.
Technology:
This category highlights the cost-performance trade-offs inherent in MLRS munitions, from basic area effects to pinpoint precision strike capabilities.
- Guided Rockets:These munitions incorporate advanced avionics for enhanced accuracy and extended range capabilities. Demand from armed forces seeking to minimize collateral damage and improve first-hit probability drives this segment.
- GPS-Guided:Utilizing satellite signals for precise targeting, these rockets are critical for engaging fixed or slow-moving objectives. Geopolitical flashpoints concentrate demand for these systems in countries like Poland.
- Unguided Rockets:These are basic, high-volume munitions designed for area saturation, often favored by paramilitary groups for their cost efficiency.
- Inertial Navigation:This technology provides autonomous guidance using internal sensors, offering a robust alternative or complement to GPS in contested environments.
- Laser-Guided:Employing a laser designator for terminal guidance, these rockets are suitable for precision strikes against specific high-value targets.
The increasing focus on minimizing collateral damage and improving target accuracy defines the evolution within this technology segment.
Application:
This category delineates the diverse mission sets and tactical roles MLRS fulfill, ranging from direct combat support to strategic interdiction.
- Surface-to-Surface Attack:This represents the primary role of MLRS, delivering overwhelming firepower against ground targets. Army combat units require this capability for offensive operations and tactical advantage.
- Counter-Battery Fire:Rapidly engaging and neutralizing enemy artillery positions, this application is critical for achieving fire superiority. Advanced army combat units use this to protect friendly forces and suppress enemy fire.
- Anti-Personnel:Rockets designed to neutralize enemy infantry formations and unarmored vehicles across a wide area.
- Area Denial:This application utilizes specialized submunitions or warheads to restrict enemy movement and access within a designated zone.
- Suppression of Enemy Air Defenses:Employs specialized munitions to degrade or destroy enemy air defense systems, enabling air superiority for friendly aircraft.
The versatility of MLRS across these applications underscores their indispensable role in modern warfare and strategic deterrence.
End User:
This category highlights the varied organizational entities that deploy and operate MLRS, each with distinct procurement drivers and operational requirements.
- Army Combat Units:These are the primary operational users of MLRS for direct combat support and deep strike missions within ground forces. National defense procurement agencies in countries like India prioritize robust systems for these units.
- Artillery Regiments:Specialized military formations dedicated to operating and maintaining MLRS and other indirect fire systems. These regiments are crucial for coordinated fire plans in countries like South Korea.
- Special Forces:These elite units employ lighter, more mobile MLRS variants for rapid deployment and precision strike in irregular warfare scenarios.
- Paramilitary Groups:These groups often acquire simpler, often unguided, MLRS for area saturation and psychological impact in asymmetric conflicts.
- Defense Contractors:These entities are involved in the development, manufacturing, and maintenance of MLRS for various national militaries and international clients.
Each end-user segment influences MLRS design and procurement based on distinct operational requirements and budgetary considerations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul, a hub for defense innovation, drives significant demand for advanced multiple launch rocket systems. This focus stems from ongoing regional security concerns and continuous investment in military readiness. The city's defense contractors are pivotal in developing self-propelled MLRS for rapid deployment tactics.
United States
United States military forces prioritize precision-guided rockets and long-range strike capabilities for strategic deterrence. The US International Traffic in Arms Regulations (ITAR) strictly controls sensitive guidance technology exports. Defense manufacturing centers in Texas and Florida concentrate on developing advanced guidance systems for next-generation MLRS.
Poland
Poland's defense modernization programs generate consistent demand for new MLRS, driven by geopolitical flashpoints. NATO Standardization Agreements (STANAGs) dictate interoperability requirements for system procurement. Defense industry hubs near Warsaw are expanding production capacity for allied MLRS platforms.
South Korea
South Korea consistently procures self-propelled MLRS for rapid deployment and effective counter-battery fire missions. National defense procurement agencies prioritize robust systems for advanced army combat units. Changwon's industrial complex focuses on manufacturing these self-propelled MLRS platforms.
Germany
Germany favors wheeled chassis MLRS for high road speed and reduced maintenance, aligning with alliance interoperability mandates. NATO Standardization Agreements (STANAGs) shape system design and procurement for member states. Munich's defense sector collaborates on multi-role launch platforms compatible with alliance munitions.
Australia
Australia seeks tracked MLRS for challenging terrains and modular multi-role launch platforms for enhanced flexibility. National defense procurement agencies impose technology-sharing requirements on foreign vendors. Adelaide's defense industry is involved in integrating modular systems for diverse operational needs.
Global Multiple Launch Rocket Systems Market Key Industry Players
Capital-heavy producers, typically large integrated defense contractors, compete with specialized component and software developers in the MLRS market. The market structure exhibits consolidation within the premium segment, dominated by a few global players, and fragmentation among providers of cost-effective solutions. Key strategic archetypes include advanced guidance system innovators, platform integrators, and munition specialists. Companies often engage in technology licensing, strategic partnerships, and targeted mergers and acquisitions to expand their market reach and secure critical supply chain components.
Within the premium segment, Lockheed Martin Corporation, a prominent US-based entity, represents integrated defense capabilities and advanced guidance systems. Conversely, Hanwha Corporation, a South Korean firm, and Roketsan Roket Sanayii ve Ticaret A.S., based in Turkey, exemplify providers of cost-efficient and reliable systems. These companies occupy a strong position by offering accessible technology to a broader international client base seeking effective area saturation capabilities. Their offerings cater to diverse operational requirements across different defense budgets.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| Hanwha Corporation |
| Roketsan Roket Sanayii ve Ticaret A.S. |
| Elbit Systems Ltd. |
| Avibrás Indústria Aeroespacial |
| KNDS N.V. |
| IMI Systems Ltd. |
| Diehl Defence GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Vertical integration by prime contractors anchors both supply position and pricing power within the Multiple Launch Rocket Systems market. This strategic choice influences the availability of critical components and the final system cost for national defense procurement agencies.
Pricing Analysis
Value-based pricing for advanced MLRS systems ties directly to enhanced accuracy and mission success rates. The dominant pricing structure is contract-based long-term offtake, often bundled with training and maintenance services. Customization level and after-sales service represent key price differentiation drivers. Pricing softness reflects intense competition for cost-efficient systems, especially in emerging markets. Paramilitary groups remain the most price-sensitive buyers, while advanced army combat units prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical MLRS components mitigate single-vendor risks for defense ministries. Geographic supply concentration for key inputs exists in countries like the United States for advanced guidance systems and South Korea for robust chassis platforms. Solid rocket motor propellant and high-performance microelectronics are crucial component dependencies. Single-source vulnerability for specialized guidance kits presents a structural supply chain risk. Distribution runs through direct sales channels from prime contractors to national defense procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Multiple Launch Rocket Systems market is primarily a cost-of-compliance story, where adherence to NATO Standardization Agreements creates a significant barrier to entry for non-compliant players.
For Market Incumbents: Anticipate continued geopolitical flashpoints by investing in modular system development to ensure multi-role compatibility. Diversify critical component sourcing beyond single-country dependencies to mitigate supply chain disruptions. Leverage existing relationships with allied nations to reinforce market share against emerging competitors. Focus R&D efforts on AI-driven fire control software to maintain a technological edge against evolving threats.
For New Entrants and Emerging Players: Regional defense contractors should focus on local manufacturing partnerships to fulfill national industrial participation mandates in countries like India and Brazil. Target the cost-effective, unguided rocket segment, which offers a lower barrier to entry for area saturation capabilities. A go-to-market angle focusing on robust, reliable systems with accessible technology transfer provisions can penetrate underpenetrated markets. Emphasize simplified logistics and reduced maintenance burdens for smaller military forces.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated defense contractors seeking advanced guidance technology specialists. The long-term viability of MLRS manufacturers remains strong over the next 5-10 years, driven by ongoing modernization programs. An acquisition target archetype would be a mid-sized firm specializing in precision guidance kits or autonomous targeting software. The signal to watch is an increase in multi-nation joint development programs for next-generation MLRS platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | This expands system versatility, enabling a common chassis to launch diverse munitions for global militaries. |
| AI-Driven Fire Control Software | This shortens sensor-to-shooter timelines, enhancing battlefield responsiveness for advanced army combat units. |
| Localized Manufacturing Partnerships | This satisfies national industrial participation mandates, securing contracts in emerging markets like Brazil. |
| Advanced Guidance System Integration | This improves rocket accuracy, minimizing collateral damage and increasing first-hit probability for NATO forces. |
| Supply Chain Resilience Programs | This mitigates critical component bottlenecks, ensuring consistent production for defense contractors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary interviews were conducted with defense procurement officers, artillery regiment commanders, R&D leads at defense contractors, and specialized component suppliers. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation of data points.
Market segmentation by product type, technology, application, and end-user was modeled at a granular level. The analytical framework incorporated historical trends and projected future demand across the analysis window. Compound annual growth rates were derived from a weighted average of market drivers, restraints, and strategic opportunities. Geopolitical stability and national defense budgets served as key industry-specific forecast inputs.
Caveats apply where unforeseen geopolitical shifts or rapid technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding defense spending priorities and supply chain stability over the projection horizon. Deviation in global conflict intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Global Artillery Systems Market