
 Aircraft MRO Market | 2026-2036
Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft MRO Market Intelligence
Cargo operators and low-cost carriers is decoupling from traditional full-service airline maintenance patterns, creating divergent fleet age profiles and turnaround requirements. Lufthansa Technik anchors European widebody overhaul capacity through its Hamburg and Malta facilities. GE Aerospace dominates engine overhaul through its global network of licensed service facilities. ST Engineering Aerospace leverages Singapore's regulatory hub status to serve Asia-Pacific operators.
Aircraft maintenance, repair, and overhaul encompasses the technical servicing of airframes, engines, and components to sustain airworthiness certification, involving non-destructive testing, life-limited part tracking, and corrosion control per manufacturer maintenance planning documents. Engine Overhaul captures the largest value pool within Service Type segmentation due to material costs and specialized tooling requirements. Predictive Maintenance within Maintenance Stage segmentation is expanding fastest as operators deploy sensor analytics to shift from hard-time to condition-based interventions. Component Repair sustains margin concentration where OEM-approved repair processes limit competitive entry.
FAA airworthiness directives and EASA continuing airworthiness program instructions govern inspection intervals and mandatory modification compliance, directly shaping MRO demand timing and documentation burdens. The EU Green Deal emissions trading framework and ICAO carbon offset requirements are pressuring operators to extend engine on-wing time and optimize maintenance events. Stakeholders must monitor regulatory divergence between FAA and EASA on predictive maintenance credit approval, as harmonization gaps will determine where next-generation digital MRO platforms achieve scale first.
Market Dynamics
Next-generation narrowbody fleets are fragmenting maintenance demand patterns as operators retire aging widebodies ahead of schedule, forcing MRO providers to retool hangar configurations and technician specializations simultaneously.
Growth Catalysts
- EU Green Deal Emissions Trading:The framework pressures operators to extend engine on-wing time, compressing maintenance intervals and expanding predictive analytics contracts.
- Low-cost carrier narrowbody expansion:Southeast Asian LCCs are accelerating fleet turnover rates, generating concentrated demand for line maintenance and rapid component turnaround services.
- Sensor analytics platforms:Condition-based monitoring is automating hard-time inspection schedules, enabling MRO providers to capture recurring software revenue alongside physical servicing.
Market Restraints
- Titanium and superalloy supply concentration:Engine overhaul material costs fluctuate with Russian and Chinese sponge titanium export restrictions, squeezing margin predictability.
- OEM-approved repair process lock-in:Component repair stations face structural barriers where manufacturers control technical data rights, limiting independent competitive entry.
- FAA-EASA predictive maintenance credit divergence:Non-harmonized approval timelines for digital inspection credits force dual certification investments, raising platform development costs.
Strategic Opportunities
- Indonesia and Vietnam MRO infrastructure:Underpenetrated archipelagic markets lack sufficient heavy maintenance hangars, creating first-mover advantages for greenfield facility investments.
- Sustainable aviation fuel compatibility retrofits:Engine modification mandates for SAF blends will generate surge demand for combustion chamber and fuel system overhauls through 2030.
- Blockchain component provenance tracking:Convergence of distributed ledger technology with life-limited part databases enables premium pricing for certified traceability services.
Industry Challenges
- Airframe-specific technician certification:Type rating scarcity for A350 and 787 systems extends hiring timelines, constraining capacity expansion at independent overhaul facilities.
- Legacy MRO software integration:Predictive maintenance platforms face execution friction when interfacing with decades-old inventory management systems, delaying ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft MRO Market |
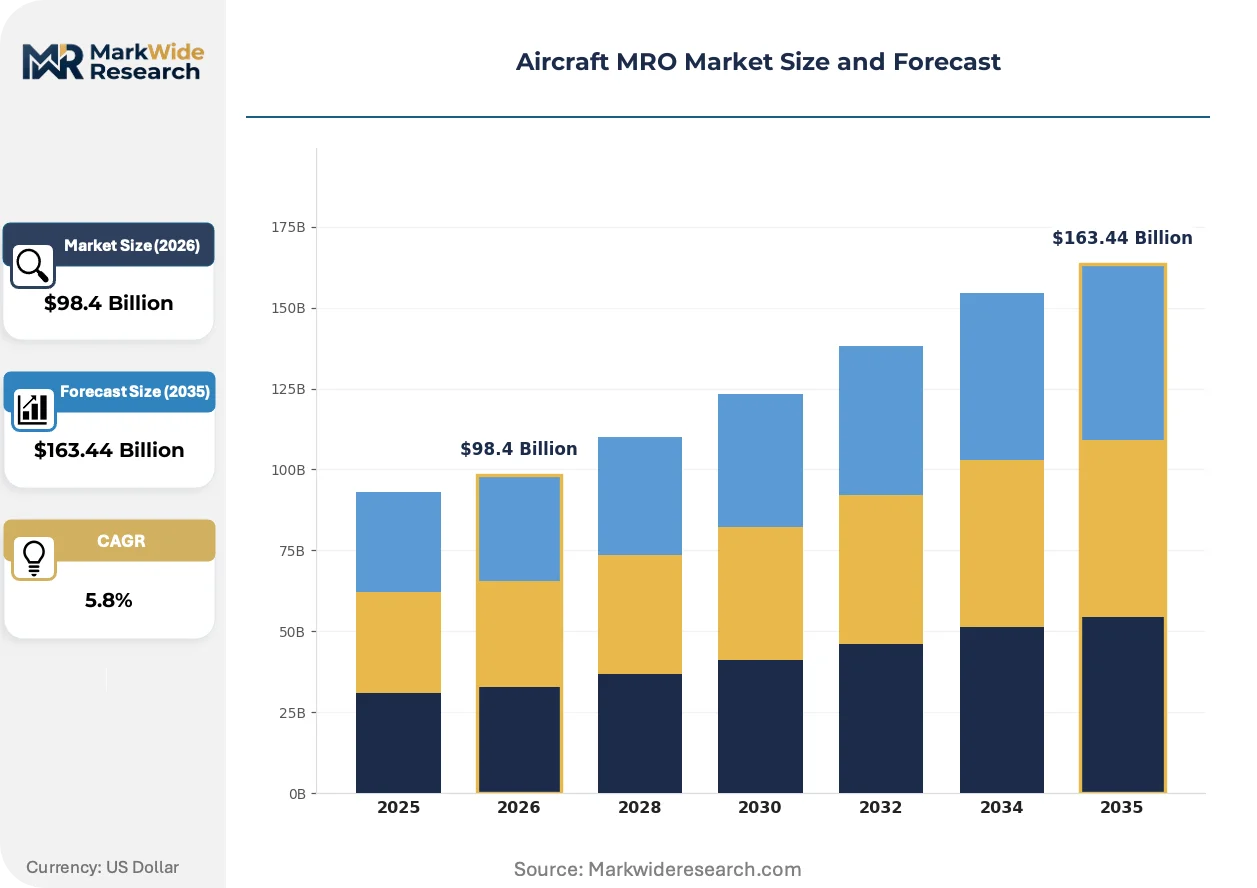
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $163.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engine Overhaul, Line Maintenance, Component Repair, Avionics Upgrades, Structural Inspection Aircraft Type: Fixed-Wing, Rotary-Wing, Business Jets, Regional Aircraft, Cargo Aircraft End User: Airlines, Leasing Companies, Military Operators, Private Owners, Government Agencies Maintenance Stage: Scheduled Maintenance, Unscheduled Maintenance, Preventive Maintenance, Predictive Maintenance, Retrofit |
| Companies Covered | AAR Corp, Lufthansa Technik, Delta TechOps, ST Engineering Aerospace, Air France Industries KLM Engineering & Maintenance, GE Aerospace, HAECO, MTU Aero Engines, SAFRAN Aircraft Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft MRO Market Strategic Shifts & Innovations
Digital thread technologies are compressing the gap between flight operations data and shop floor execution, enabling real-time maintenance scheduling that was structurally impossible under paper-based airworthiness documentation systems.
Robotic non-destructive testing systems are automating fuselage and wing inspection protocols across European and North American heavy maintenance facilities. Lufthansa Technik and MRO providers serving Delta and United fleets have deployed automated ultrasonic scanning arrays that reduce inspection man-hours by half. The technology is automating crack detection in composite structures, compressing A-check intervals and enabling overnight turnaround scheduling that manual inspection regimes cannot match.
EASA's continuing airworthiness program instructions now mandate enhanced documentation for predictive maintenance credit applications, creating compliance complexity for operators seeking inspection interval extensions. The regulation forces MRO providers to maintain dual audit trails for sensor data and physical inspection records. Asian operators are responding by centralizing digital MRO platform procurement in Singapore and Hong Kong to access harmonized certification support.
Power-by-the-hour contracts are displacing traditional time-and-material billing across narrowbody engine overhaul procurement. Low-cost carriers in Southeast Asia now specify guaranteed availability clauses rather than per-shop-visit pricing, transferring operational risk to GE Aerospace and Pratt & Whitney service networks. This restructuring is most visible in Indonesia and the Philippines, where Lion Air and Cebu Pacific have consolidated engine maintenance under long-term availability agreements.
Aircraft MRO Market Segmentation

MRO procurement patterns diverge sharply across operator types, with low-cost carriers prioritizing rapid turnaround over comprehensive overhaul while cargo fleets emphasize engine reliability metrics. Service providers must configure distinct capability portfolios for each segment cluster.
Service Type:
Cost structure and margin profile separate buyers, with engine-intensive operators accepting premium pricing for guaranteed availability while narrowbody fleets minimize line maintenance expenditure.
- Engine Overhaul:Material-intensive restoration of turbine modules, combustion systems, and life-limited rotating components using specialized hot section tooling. Demand concentrates among Southeast Asian low-cost carriers as Lion Air and Cebu Pacific consolidate under power-by-the-hour contracts with GE Aerospace and Pratt & Whitney service networks.
- Component Repair:OEM-approved restoration of avionics, hydraulics, and pneumatic systems where manufacturer technical data rights create structural barriers to independent competition. European operators face margin pressure from EASA documentation mandates for predictive maintenance credit applications, forcing dual audit trail investments.
- Line Maintenance:Daily transit checks and minor defect rectification at airport ramps.
- Avionics Upgrades:Cockpit system modernization for navigation compliance and connectivity mandates.
- Structural Inspection:Fuselage and wing integrity assessment per manufacturer maintenance planning documents.
Engine Overhaul leads volumes today; Predictive Maintenance within Maintenance Stage is gaining share fastest.
Aircraft Type:
Application mission dictates maintenance intensity, with high-cycle narrowbodies requiring frequent line intervention versus low-utilization business jets on extended inspection intervals.
- Fixed-Wing:Commercial transport aircraft spanning single-aisle narrowbodies to twin-aisle widebodies. Fleet renewal patterns concentrate demand in Indonesia and Vietnam as archipelagic geography forces dispersed maintenance infrastructure investments.
- Business Jets:Corporate and private aviation platforms with customized cabin configurations and specialized avionics suites. Demand clusters in Singapore and Hong Kong where centralized digital MRO platform procurement accesses harmonized FAA-EASA certification support.
- Rotary-Wing:Helicopter platforms for offshore, emergency medical, and utility operations.
- Regional Aircraft:Turboprop and small jet equipment serving thin-route connectivity.
- Cargo Aircraft:Dedicated freighter and converted passenger-to-cargo platforms.
Fixed-Wing dominates current spend; Business Jets show steepest expansion trajectory as Asia-Pacific wealth concentration accelerates.
End User:
Ownership structure determines risk allocation, with airlines internalizing operational reliability versus leasing companies emphasizing residual value preservation through documentation rigor.
- Airlines:Scheduled and charter operators maintaining fleet airworthiness under direct operational control. Full-service carriers in Europe anchor widebody overhaul demand through Lufthansa Technik's Hamburg and Malta facilities.
- Leasing Companies:Asset owners requiring transition inspections and redelivery certification between operator contracts. Documentation burdens intensify under EU Green Deal emissions trading pressure to extend engine on-wing time and optimize maintenance events.
- Military Operators:Defense and government aviation units with classified system requirements.
- Private Owners:Individual aircraft proprietors with discretionary maintenance scheduling.
- Government Agencies:State aviation departments and special mission platforms.
Airlines represent the largest contract value; Leasing Companies are expanding procurement most quickly as fleet ownership concentrates.
Maintenance Stage:
Technology maturity separates adopters, with sensor-enabled operators capturing inspection interval extensions while legacy fleets remain on hard-time schedules.
- Predictive Maintenance:Condition-based intervention using real-time sensor analytics and machine learning algorithms to forecast component degradation. Robotic non-destructive testing systems at Lufthansa Technik and Delta-serving providers automate fuselage inspection, compressing A-check intervals.
- Scheduled Maintenance:Calendar and flight hour-based inspections per manufacturer maintenance planning documents. FAA airworthiness directives and EASA continuing airworthiness program instructions govern mandatory compliance timing.
- Unscheduled Maintenance:Reactive defect rectification following in-service failures.
- Preventive Maintenance:Proactive component replacement before predicted failure.
- Retrofit:Post-production modification for sustainable aviation fuel compatibility and emissions compliance.
Scheduled Maintenance retains volume leadership; Predictive Maintenance climbs the fastest as digital thread technologies compress flight-to-shop floor latency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore anchors regional MRO infrastructure through its regulatory hub status and specialized hangar capacity. FAA-EASA harmonization efforts concentrate certification expertise there. The city-state's Changi precinct hosts the densest cluster of engine overhaul facilities serving Southeast Asian low-cost carriers.
United States
Legacy carrier maintenance subsidiaries dominate widebody overhaul demand as Delta TechOps and United's in-house operations absorb domestic fleet requirements. FAA airworthiness directives on predictive maintenance credits shape platform development timelines. The Dallas-Fort Worth corridor concentrates independent component repair stations serving regional airline networks.
Germany
Lufthansa Technik's Hamburg and Malta facilities anchor European widebody capacity as EU Green Deal emissions trading pressures operators toward extended engine on-wing intervals. EASA continuing airworthiness program instructions mandate enhanced documentation for digital inspection credits. Bavaria hosts specialized tooling manufacturers supplying hot section restoration equipment.
Indonesia
Archipelagic geography fragments maintenance demand across dispersed airports as Lion Air and Garuda Indonesia expand narrowbody fleets. The national aviation regulator enforces documentation standards aligned with ICAO carbon offset requirements. Batam's free trade zone attracts greenfield hangar investments targeting first-mover positioning.
Vietnam
VietJet and Bamboo Airways accelerate fleet turnover rates, generating concentrated demand for line maintenance and rapid component turnaround. The civil aviation authority implements EASA-modeled continuing airworthiness regulations. Ho Chi Minh City's Tan Son Nhat precinct hosts emerging joint-venture facilities with Singaporean technical partners.
Aircraft MRO Market Key Industry Players
Capacity expansion dominates the current landscape as providers retool hangar configurations for next-generation narrowbody fleets. The vendor base separates into three tiers: OEM-affiliated engine specialists, full-service airline subsidiaries, and independent component repair stations. Two strategic archetypes define positioning: integrated carriers leveraging captive fleet demand, and technology licensors capturing recurring software revenue from predictive analytics platforms. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with providers seeking regulatory hub status in underpenetrated Southeast Asian markets.
Within the integrated carrier tier, Lufthansa Technik and Delta TechOps exemplify full-service airline subsidiaries that internalize widebody overhaul demand. GE Aerospace occupies a position as a technology licensor anchoring engine overhaul networks through power-by-the-hour contract structures. ST Engineering Aerospace represents the regulatory hub archetype, leveraging Singapore's certification infrastructure to serve Asia-Pacific operator procurement centralization.
| Leading Market Players |
|---|
| AAR Corp |
| Lufthansa Technik |
| Delta TechOps |
| ST Engineering Aerospace |
| Air France Industries KLM Engineering & Maintenance |
| GE Aerospace |
| HAECO |
| MTU Aero Engines |
| SAFRAN Aircraft Engines |
| Others |
Cost & Logistics Intelligence
Power-by-the-hour contract adoption among Southeast Asian low-cost carriers is compressing margin structures for engine overhaul providers, forcing suppliers to absorb operational risk while competing on guaranteed availability metrics rather than per-shop-visit pricing.
Pricing Analysis
Titanium and superalloy input costs pass through directly to engine overhaul pricing, with Russian and Chinese sponge titanium export restrictions creating margin unpredictability for hot section restoration work. Three-tier pricing structure across OEM-licensed, approved, and independent repair stations separates certified life-limited part work from non-critical component services. Cost compression in independent component repair is intensifying because manufacturer technical data rights limit competitive entry. Leasing companies demonstrate lowest price sensitivity due to residual value preservation priorities, while narrowbody LCCs negotiate aggressively on line maintenance rates.
Supply Chain Analysis
Regional distribution centers in Singapore, Hamburg, and Dallas-Fort Worth anchor hub-and-spoke parts provisioning for engine modules and rotable components. Hot section tooling manufacturers cluster in Germany and the United States, while Southeast Asian archipelagic markets depend on air freight for time-critical spares. Single-source vulnerability concentrates in specialized turbine blade casting facilities. Distribution runs through OEM-affiliated service networks and independent component repair stations serving airline subsidiaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as predictive maintenance credit applications under EASA continuing airworthiness instructions shift procurement toward documentation-intensive premium providers.
For Market Incumbents: Hedge exposure to titanium supply concentration through long-term offtake agreements with alternative sponge producers. Diversify technician certification pipelines across A350 and 787 type ratings to constrain independent facility capacity expansion. OEM technical data access remains the critical defensive lever against independent component repair encroachment. For New Entrants and Emerging Players: Underserved cargo operators seeking engine reliability metrics rather than rapid turnaround present white-space opportunity. Batam and Ho Chi Minh City offer greenfield hangar investment potential with first-mover regulatory positioning. Blockchain-enabled component provenance tracking provides differentiated go-to-market positioning for traceability-premium services. For Investors and Strategic Acquirers: Asymmetric upside sits with regulatory hub specialists possessing dual FAA-EASA certification infrastructure. Five-to-ten year viability favors platforms capturing recurring software revenue from predictive analytics rather than transactional overhaul dependency. Watch for harmonization agreements on predictive maintenance credits as inflection signal for digital MRO platform scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Sensor analytics contracts at ST Engineering Aerospace capture recurring revenue alongside physical servicing. |
| Greenfield Facility Investment | Batam free trade zone hangar construction targets Lion Air and Garuda Indonesia narrowbody demand concentration. |
| SAF Compatibility Retrofit Capability | Combustion chamber overhaul capacity addresses EU Green Deal engine modification mandates through 2030. |
| Blockchain Traceability Integration | Distributed ledger convergence with life-limited part databases enables premium pricing for certified provenance. |
| Dual Certification Infrastructure | Singapore and Hong Kong regulatory hub status supports harmonized FAA-EASA predictive maintenance credit applications. |
Research Approach
Bottom-up airline fleet modeling reconciled against top-down MRO provider capacity tracking forms the analytical core of this study. Primary interviews with maintenance planning executives, airworthiness regulatory specialists, component procurement managers, and hangar operations directors combined with secondary validation against FAA airworthiness directive filings, EASA continuing airworthiness program instructions, and ICAO carbon offset compliance databases. Triangulation across bottom-up operator demand projections and top-down service provider capacity assessments ensures cross-verified outputs.
Input-output matrices map engine overhaul material costs, technician labor availability, and hangar utilization rates against narrowbody fleet renewal patterns across the projection horizon. Segmentation dimensions include service type, aircraft platform, operator category, and maintenance stage maturity. CAGRs derive from regression analysis of historical fleet growth correlated with regulatory inspection interval modifications. Forecast inputs incorporate sensor analytics adoption curves and sustainable aviation fuel retrofit timelines.
Underlying measurement precision varies by segment; engine overhaul and predictive maintenance carry tighter precision than emerging blockchain traceability services. Forecasts reflect documented assumptions regarding regulatory harmonization progress and titanium supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market