
 Regional Turboprop Engine MRO Services Market | 2026-2036
Regional Turboprop Engine MRO Services Market Size, Share, and Industry Trends Forecast 2026-2036
Regional Turboprop Engine MRO Services Market Insights
REACH compliance is rebalancing the cost-of-entry calculus for European MRO providers serving regional turboprop operators. Pratt & Whitney Canada leverages its dominant PT6A installed base to sustain aftermarket revenue through proprietary tooling networks. Safran Aircraft Engines anchors its position in the Ardiden and Makila powerplant segments with dedicated regional service centers in Toulouse and Casablanca. MTU Aero Engines competes through modular repair schemes that reduce turnaround times for operator fleets.
Regional turboprop engine MRO services encompass the inspection, repair, overhaul, and component replacement of gas turbine engines driving propeller aircraft in the sub-100 seat category, typically operating at power ratings between 1,000 and 5,000 shaft horsepower with free-turbine or single-spool architectures designed for short-haul and unimproved runway performance. These services restore airworthiness margins, hot-section durability, and fuel efficiency to powerplants accumulating high cycle-to-hour ratios in commuter and cargo operations. Overhaul and engine rebuild categories command the deepest margin pools due to core restoration complexity and proprietary parts scarcity, while line maintenance and inspection segments generate volume-driven recurring revenue from high-frequency regional schedules. Component replacement demand concentrates on hot-section superalloy parts and gearbox assemblies where OEM-controlled supply constrains third-party participation.
EASA's Part-145 certification requirements and the FAA's Airworthiness Directive enforcement framework shape technician training investments and spare parts traceability standards across North American and European maintenance networks. Transport Canada's CAR 573 approvals govern overhaul quality for Prairie-based operators serving Arctic routes. Stakeholders must monitor evolving emissions disclosure mandates and assess whether OEM digital fleet monitoring platforms will consolidate channel control or create openings for independent service providers.
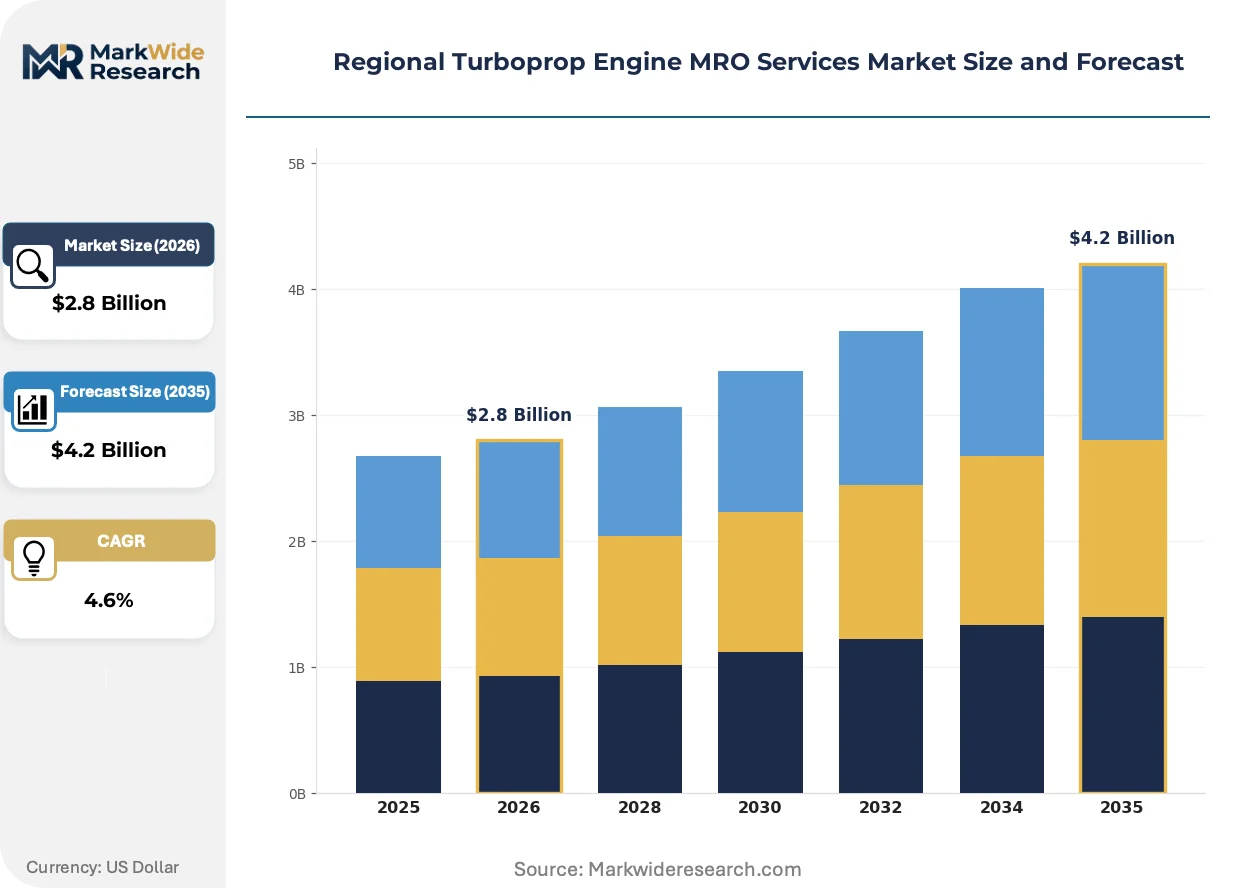
Market Dynamics
EASA's tightening emissions monitoring protocols for turboprop operations are elevating overhaul complexity and documentation burdens across regional maintenance networks. This regulatory compression is forcing MRO providers to restructure technician training programs and spare parts traceability systems.
Growth Catalysts
- Remote connectivity expansion:Feeder carriers serving resource extraction hubs and indigenous communities in Canada's Prairie provinces are extending fleet utilization rates and compressing maintenance intervals.
- REACH compliance rebalancing:European MRO providers face elevated cost-of-entry calculus as chemical substance restrictions reshape parts cleaning and surface treatment processes.
- Hot-section superalloy demand:Component replacement cycles are accelerating for turbine blades and combustor liners in high-cycle regional operations.
Market Restraints
- OEM-controlled supply chains:Proprietary parts scarcity for PT6A powerplants constrains third-party participation in core restoration activities.
- Technician certification bottlenecks:Transport Canada's CAR 573 approval timelines and EASA Part-145 requirements create workforce entry barriers.
- Substitution pressure from regional jets:Embraer E-Jet family encroachment on sub-100 seat routes threatens turboprop fleet renewal decisions.
Strategic Opportunities
- Digital fleet monitoring convergence:OEM platforms integrating predictive analytics with blockchain parts traceability are creating new service tier openings.
- Modular repair scheme adoption:Component-level refurbishment programs reduce turnaround times and enable inventory pooling across operator networks.
- Arctic route specialization:Cold-weather operation protocols and ice-protection system expertise differentiate providers serving northern Canadian and Scandinavian markets.
Industry Challenges
- Free-turbine architecture expertise scarcity:Aging technician populations with deep PT6A and PW100 experience are exiting the workforce faster than training pipelines replenish.
- Documentation burden inflation:EASA emissions disclosure mandates and FAA Airworthiness Directive enforcement frameworks multiply administrative overhead per overhaul event.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regional Turboprop Engine MRO Services Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overhaul, Repair, Component Replacement, Inspection, Testing Customer Type: Airlines, Charter Operators, Cargo Carriers, Government Agencies, Private Owners Maintenance Stage: Line Maintenance, Base Maintenance, Engine Rebuild, Scheduled Inspection Distribution Channel: Direct Sales, Authorized Dealers, Third-party Providers, Online Platforms |
| Companies Covered | Pratt & Whitney Canada, Safran Aircraft Engines, MTU Aero Engines, Rolls-Royce Holdings, GE Aerospace, Honeywell International, Lufthansa Technik, StandardAero, AAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regional Turboprop Engine MRO Services Market Trends and Innovations
Digital predictive maintenance platforms are compressing traditional scheduled overhaul intervals and enabling condition-based interventions. This shift is redistributing revenue from heavy maintenance events toward continuous monitoring subscriptions.
Additive manufacturing of hot-section superalloy components is rewriting spare parts availability economics for legacy turboprop fleets. Regional operators with aging PT6A and TPE331 installations are adopting printed turbine vanes and combustor segments to bypass OEM lead times. This distributed production model is eroding centralized foundry advantages and enabling independent MROs to capture margin previously captured by original equipment manufacturers.
EASA's F-Gas Regulation and evolving emissions disclosure mandates are tightening refrigerant and chemical handling protocols across European maintenance facilities. Overhaul providers must retrofit solvent recovery systems and substitute chromate-based surface treatments. Mediterranean and Eastern European MRO clusters are absorbing compliance costs faster than smaller independent shops, accelerating network consolidation.
Power-by-the-hour contracts are displacing traditional time-and-material billing for regional turboprop operators. Feeder carriers in Canada's Prairie provinces and Scandinavian point-to-point networks are transferring operational risk to maintenance providers. This unbundling of service from asset ownership concentrates buyer power among fleet-scale operators and compresses margins for transactional repair shops.
Regional Turboprop Engine MRO Services Market Segmentation
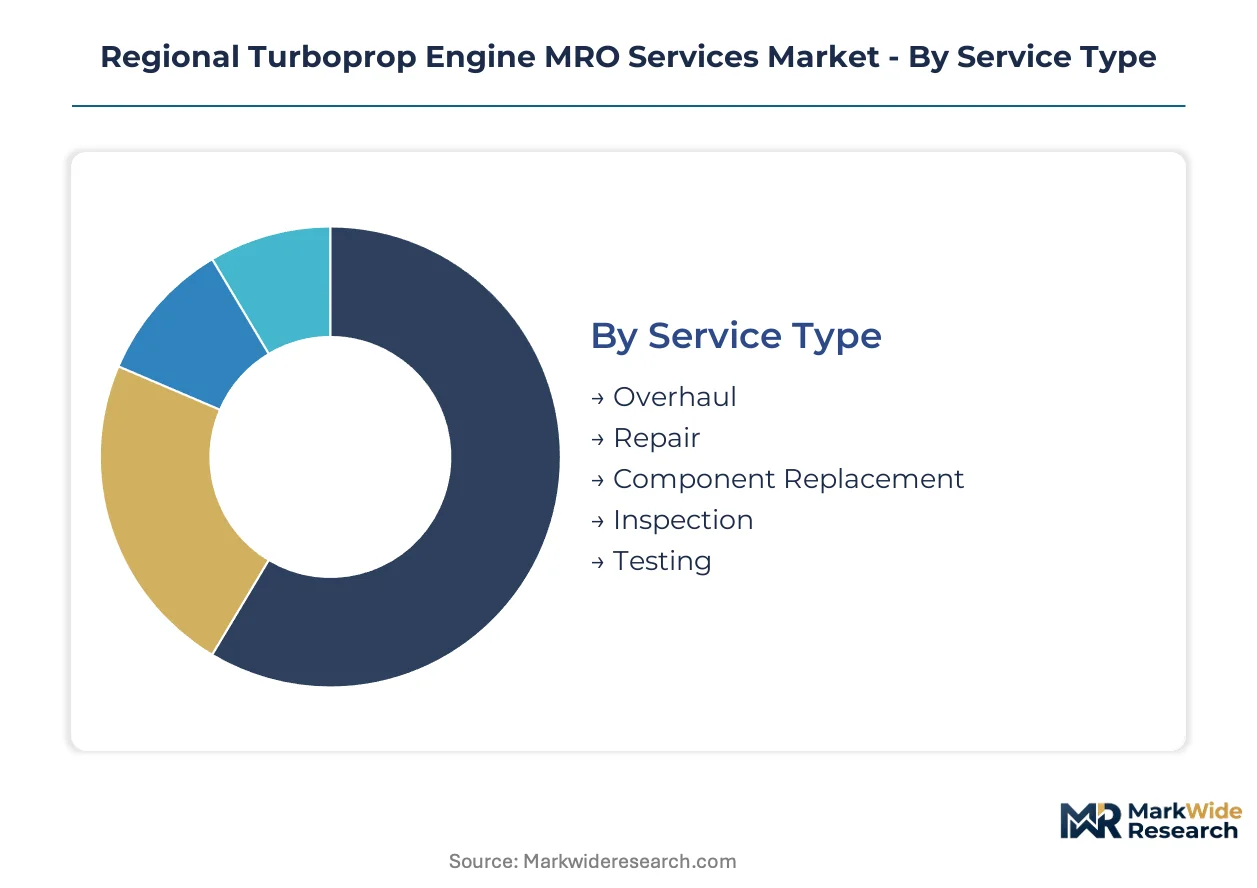
Turboprop engine MRO services fragment across service intensity, operator economics, and channel control. Each segmentation axis reveals distinct margin structures and competitive entry barriers that reshape provider positioning across regional aviation networks.
Service Type:
Technical complexity and proprietary parts access differentiate service tiers, with core restoration commanding premium pricing against commoditized inspection work.
- Overhaul:Complete disassembly, inspection, and restoration of engine modules to zero-time condition. Prairie-based feeder carriers serving Arctic routes compress intervals due to high cycle accumulation from short-haul resource extraction missions.
- Component Replacement:Hot-section superalloy part substitution for turbine blades, combustor liners, and gearbox assemblies. EASA's tightening emissions documentation elevates traceability requirements for replacement events across European maintenance networks.
- Repair:Defect remediation within on-wing or module-level scopes without full teardown.
- Inspection:Scheduled borescope and visual assessments per flight hour or cycle thresholds.
- Testing:Power assurance runs and vibration analysis for post-maintenance airworthiness verification.
Mature deployment sits with Overhaul. Newer deployment is concentrated in Component Replacement as additive manufacturing bypasses traditional foundry lead times.
Customer Type:
Operator scale and mission profile determine contract structure preferences, from transactional repair orders to long-term power-by-the-hour arrangements.
- Airlines:Scheduled regional carriers with fleet-scale maintenance programs leveraging volume pricing and dedicated line stations. Scandinavian point-to-point operators and Prairie province feeders dominate contract value concentration.
- Cargo Carriers:Dedicated freight operators with high-utilization schedules and night-flight cycle accumulation. Remote hub distribution networks in northern Canada drive demand for rapid turnaround capabilities.
- Charter Operators:On-demand service providers with irregular utilization patterns and seasonal maintenance windows.
- Government Agencies:Military and parapublic fleets with specialized mission equipment and security-cleared facility requirements.
- Private Owners:Individual aircraft operators with cost-sensitive maintenance preferences and extended interval stretching.
Volume concentration clusters with Airlines. Margin expansion is fastest with Cargo Carriers transferring operational risk through bundled service contracts.
Maintenance Stage:
Facility infrastructure and technician certification requirements escalate with maintenance depth, filtering provider participation across the value chain.
- Engine Rebuild:Zero-time restoration requiring CAR 573 or EASA Part-145 approved facilities with specialized free-turbine architecture expertise. Arctic route operators prioritize cold-weather protocol capabilities in provider selection.
- Base Maintenance:Heavy checks and modular exchanges performed at fixed maintenance bases with full tooling and test cell access.
- Scheduled Inspection:Calendar or flight hour-driven assessments with predictable demand patterns.
- Line Maintenance:Rapid-response services at outstations with limited tooling and AOG recovery focus.
Certification intensity peaks with Engine Rebuild. Frequency scaling is steepest with Line Maintenance as digital predictive platforms compress traditional interval structures.
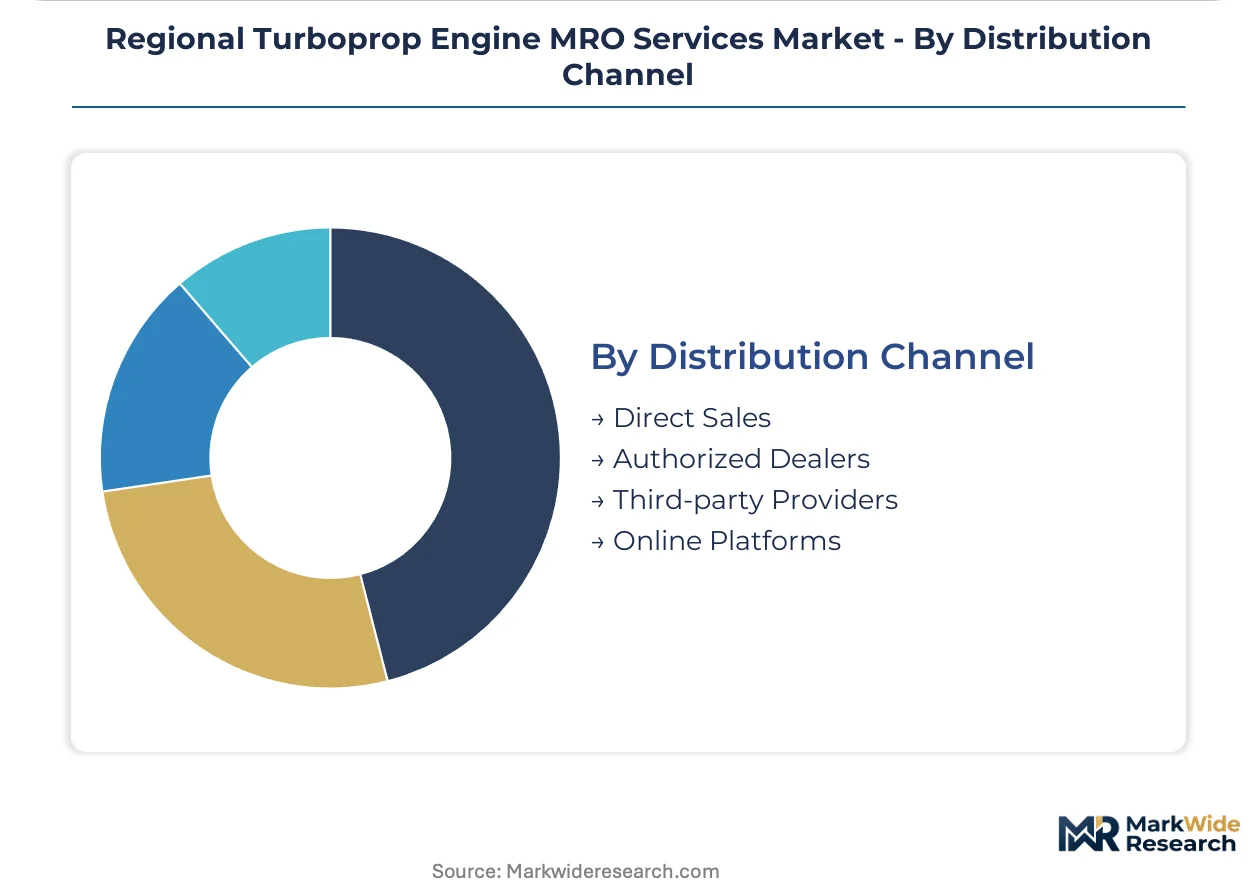
Distribution Channel:
Channel selection reflects trust architecture and parts provenance guarantees, with OEM-controlled networks defending against independent encroachment.
- Direct Sales:OEM-affiliated service centers with proprietary tooling and exclusive parts access. Pratt & Whitney Canada's PT6A network anchors this channel through captive customer relationships.
- Third-party Providers:Independent MROs competing on turnaround time and modular repair schemes. Mediterranean and Eastern European clusters absorb REACH compliance costs faster than smaller shops.
- Authorized Dealers:Regionally licensed facilities with OEM parts access but limited technical scope.
- Online Platforms:Emerging digital marketplaces for standard parts and documentation services.
Channel control consolidates with Direct Sales. Independent growth is accelerating through Third-party Providers as additive manufacturing erodes centralized supply advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Prairie provinces anchor regional turboprop MRO concentration through Transport Canada's designated Arctic route maintenance corridors and CAR 573-approved facilities serving resource extraction hubs.
Canada
Feeder carriers operating from Calgary and Edmonton maintain dense turboprop schedules connecting indigenous communities to resource extraction sites. Transport Canada's CAR 573 certification requirements govern overhaul quality standards for Arctic route operators. Winnipeg and Saskatoon host specialized maintenance clusters where cold-weather protocol expertise differentiates service providers.
United States
Alaska-based operators and Great Lakes commuter networks drive demand for rapid turnaround capabilities in remote connectivity markets. FAA Airworthiness Directive enforcement frameworks shape technician training investments and spare parts traceability standards across maintenance networks. Minneapolis and Anchorage anchor MRO clusters where independent providers compete with OEM-affiliated service centers.
France
Toulouse anchors Safran's dedicated regional service center network for Ardiden and Makila powerplant segments. EASA's F-Gas Regulation and tightening emissions disclosure mandates elevate refrigerant handling protocols across overhaul facilities. The Occitanie region concentrates specialized tooling infrastructure serving Mediterranean and North African operator networks.
Germany
MTU Aero Engines competes through modular repair schemes that reduce turnaround times for operator fleets serving Central European point-to-point routes. EASA Part-145 certification requirements filter provider participation across the maintenance value chain. Munich and Hannover host test cell facilities where power assurance runs verify post-maintenance airworthiness.
Morocco
Casablanca anchors Safran's dedicated regional service center serving North African and Mediterranean turboprop operators. REACH compliance rebalances cost-of-entry calculus for European MRO providers outsourcing surface treatment processes. The Nouaceur industrial zone concentrates chemical handling infrastructure for chromate substitution in parts cleaning operations.
Regional Turboprop Engine MRO Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor landscape. OEM-affiliated service centers leverage proprietary tooling networks and exclusive parts access to defend channel control. Independent MROs compete on turnaround velocity and modular repair scheme adoption. Consolidation pressures concentrate buyer power among fleet-scale operators while REACH compliance costs accelerate network consolidation.
Within the OEM-controlled tier, Pratt & Whitney Canada and Safran Aircraft Engines exemplify archetypes leveraging installed base dominance. Pratt & Whitney Canada sustains aftermarket revenue through PT6A proprietary tooling networks. Safran anchors position through dedicated regional service centers in Toulouse and Casablanca. MTU Aero Engines occupies a position competing through modular repair schemes.
| Leading Market Players |
|---|
| Pratt & Whitney Canada |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Rolls-Royce Holdings |
| GE Aerospace |
| Honeywell International |
| Lufthansa Technik |
| StandardAero |
| AAR |
| Others |
Pricing and Supply Chain Analysis
Additive manufacturing of hot-section superalloy components is simultaneously collapsing traditional foundry cost structures and redistributing supply leverage toward distributed production networks, compressing OEM pricing power while elevating independent MRO margins.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency AOG repairs commanding premium rates from scheduled overhaul slots offered at contracted discounts. Three-tier pricing structure across premium expedited, standard scheduled, and economy deferred tiers reflects certification intensity and parts provenance guarantees. Cost compression in the economy tier is intensifying because additive manufacturing bypasses OEM-controlled supply bottlenecks. Cargo carriers transferring operational risk through power-by-the-hour contracts exhibit lowest price sensitivity; private owners stretching maintenance intervals show highest.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-scale operator demand through proprietary tooling networks and exclusive parts access, while third-party distributors serve independent MROs competing on turnaround velocity. Geographic concentration centers on Canada, France, and Germany for specialized free-turbine expertise and EASA Part-145 certification infrastructure. Raw material dependencies include nickel-based superalloys, cobalt-chrome turbine blade substrates, and specialized chromate-free surface treatment chemicals. Single-source vulnerability persists for PT6A proprietary castings and gearbox assemblies. Distribution runs through OEM-affiliated service centers, authorized dealer networks, and emerging digital parts marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
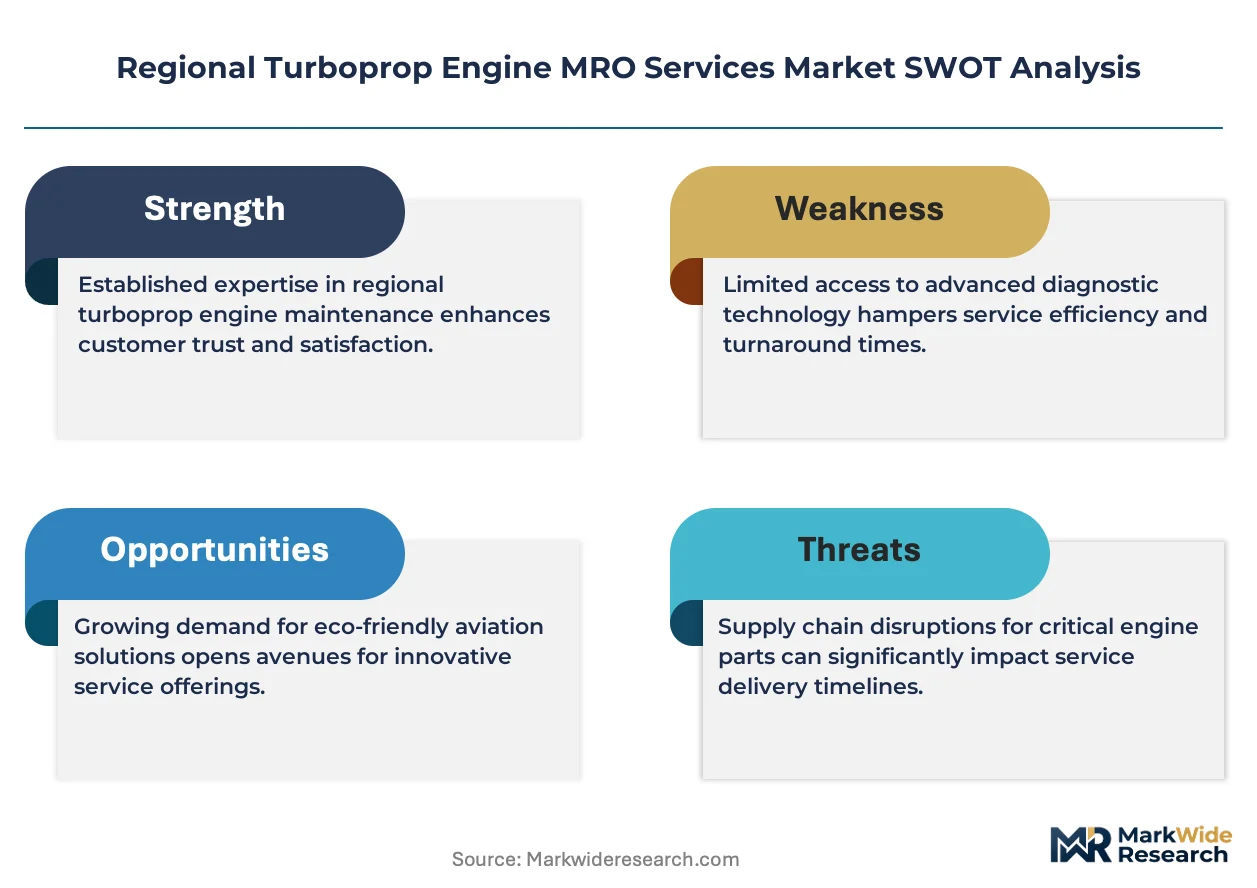
This market reads as a cost-of-compliance story where EASA's tightening emissions disclosure mandates and REACH chemical restrictions construct barrier-to-entry moats favoring capitalized incumbents with solvent recovery infrastructure and certified surface treatment capabilities.
For Market Incumbents: Acquire additive manufacturing capabilities for hot-section superalloy components to capture margin erosion from traditional foundry supply. Secure Transport Canada CAR 573 and EASA Part-145 certification expansions in Prairie province and Mediterranean clusters to defend against independent encroachment. Threat substitution from regional jet fleet renewal decisions demands proactive turboprop operator retention through bundled digital monitoring subscriptions. For New Entrants and Emerging Players: Predictive maintenance platform integration offers entry wedge into operator fleets seeking condition-based intervention capabilities. White-space targets concentrate on Arctic route specialization serving indigenous community connectivity networks in northern Canada and Scandinavian point-to-point markets. Go-to-market positioning should emphasize modular repair schemes reducing turnaround times against incumbent heavy maintenance models. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified aerospace conglomerates seeking aftermarket service network expansion. Long-term viability framing favors providers with demonstrated cold-weather protocol expertise and established relationships with feeder carriers in resource extraction corridors. Acquisition target archetype: independent MROs with additive manufacturing adoption and EASA certification infrastructure. Signal to watch: power-by-the-hour contract penetration rates among Prairie province operators as indicator of buyer power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Adoption | Enables independent MROs to bypass OEM lead times for PT6A hot-section components. |
| REACH Compliance Infrastructure | Positions European providers to capture market share as smaller shops exit. |
| Digital Fleet Monitoring Integration | Redistributes revenue from heavy events toward continuous subscription services. |
| Arctic Route Specialization | Differentiates providers serving cold-weather operations in northern Canada. |
| Power-by-the-Hour Contract Expansion | Transfers operational risk from fleet-scale operators to maintenance providers. |
Research Methodology
Document review covered EASA regulatory filings, Transport Canada CAR 573 approval databases, and FAA Airworthiness Directive enforcement records, complemented by interviews with MRO operations directors, fleet maintenance managers at Prairie province feeders, and aftermarket procurement leads at regional turboprop OEMs. Secondary validation drew from customs trade data for superalloy component flows, EASA Part-145 facility certification registries, and airline fleet utilization disclosures. Bottom-up triangulation across operator maintenance spend patterns converged with top-down market sizing from engine installed base projections.
Historical maintenance event frequency was cross-referenced against panel input from MRO executives regarding interval compression trends and additive manufacturing adoption timelines. The analytical framework segmented by service type intensity, operator scale, maintenance stage depth, and channel control structure across the projection horizon. CAGRs were derived from engine cycle accumulation models and fleet renewal decision patterns. Forecast inputs included EASA emissions mandate implementation schedules and REACH chemical substitution cost curves.
Several conditions sit outside the modeled scope, including unannounced OEM platform discontinuations, abrupt Arctic route subsidy policy shifts, and breakthrough propulsion technologies displacing turboprop architectures. Forecasts reflect assumptions regarding regulatory enforcement consistency and additive manufacturing quality certification acceptance. Periodic stress-testing of base assumptions is recommended against technician workforce attrition rates and regional jet substitution acceleration indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market