
 Aerospace and Defense MRO Market | 2026-2036
Aerospace and Defense MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense MRO Market Intelligence
The substitution of legacy aluminum alloys with advanced carbon composites in new aircraft designs is restructuring MRO service economics and repair methodologies. This shift creates new opportunities for service providers. RTX Corporation leverages its avionics repair portfolio for modern platforms, while Lockheed Martin Corporation dominates the military MRO segment. HEICO Corporation differentiates by providing FAA-approved alternative parts.
Aerospace and defense maintenance, repair, and overhaul (MRO) encompasses all activities required to ensure an aircraft's continuing airworthiness. These services, governed by strict regulatory standards, include component repairs and complete airframe inspections. Engine overhaul represents the highest value component segment due to its complexity. The commercial aviation end-user segment is the largest, though military aviation provides more stable, long-term contracts.
The market operates under a regulatory framework enforced by bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). These agencies mandate certified repair procedures and parts traceability, influencing MRO costs. Defense contracts often add another layer of security requirements. Stakeholders must balance investments in predictive analytics against the need for highly skilled human technicians.
Market Dynamics
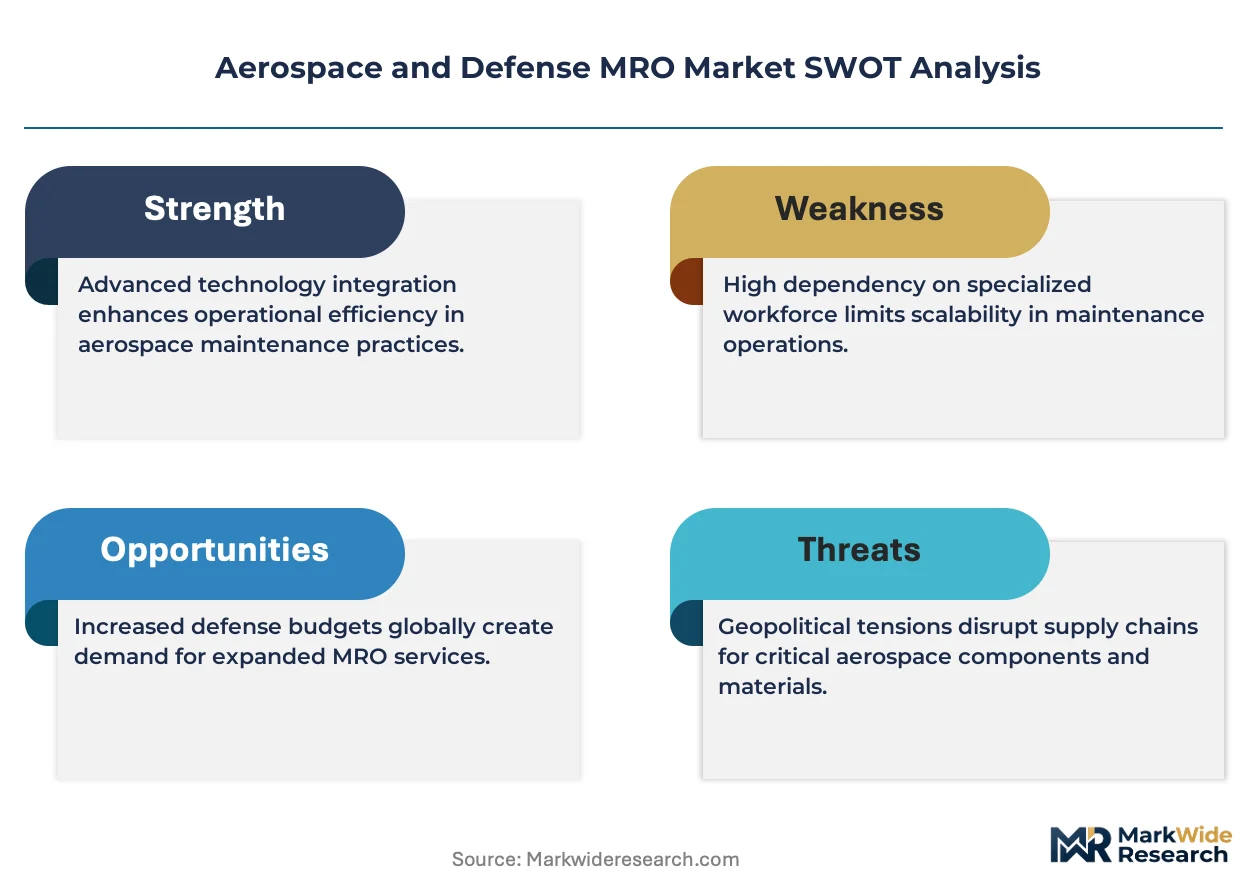
The central dynamic in the aerospace and defense MRO market is the tension between maintaining aging airframes with established repair protocols and integrating digital, predictive technologies that fundamentally alter service economics and technician workflows for newer platforms.
Growth Catalysts
- Predictive Analytics Adoption:The integration of AI and machine learning algorithms to analyze flight data and forecast component failures enables a shift from scheduled to condition-based maintenance, optimizing fleet availability.
- Aging Commercial Fleets:A significant portion of the global commercial aircraft fleet is approaching the end of its typical service life, requiring more frequent and intensive heavy maintenance checks and structural repairs.
- Regulatory Mandates:Stricter airworthiness directives issued by regulators like the US Federal Aviation Administration and the European Union Aviation Safety Agency compel operators to perform more rigorous inspections and component replacements.
Market Restraints
- Material Cost Volatility:MRO providers face margin pressure from unpredictable price fluctuations in essential aerospace materials, including titanium and nickel-based superalloys required for high-performance engine parts.
- Composite Repair Bottlenecks:Specialized knowledge and equipment for repairing advanced carbon composite structures are concentrated in a few regions, creating supply chain vulnerabilities and longer turnaround times for new-generation aircraft.
- Certification Barriers for Alternatives:The lengthy and costly process to achieve FAA Parts Manufacturer Approval (PMA) for non-OEM components limits the availability of lower-cost options and can stifle competition in the aftermarket.
Strategic Opportunities
- Southeast Asia MRO Hubs:Establishing MRO facilities in countries like Vietnam and Indonesia presents an opportunity to serve the region's burgeoning low-cost carriers and capture long-term service contracts.
- Remote Assistance Technologies:The convergence of augmented reality (AR) headsets with digital work instructions allows experienced technicians to remotely guide and supervise junior mechanics, addressing skill shortages and improving repair quality.
- Subscription-Based Service Models:MRO providers can develop power-by-the-hour or other subscription-based contracts for business and regional jet operators, offering predictable maintenance costs and maximizing aircraft uptime.
Industry Challenges
- Skilled Technician Scarcity:The industry faces a persistent shortage of certified airframe and powerplant (A&P) mechanics, particularly those with the dual expertise needed for both legacy metal aircraft and modern composite airframes.
- Legacy System Integration:MROs struggle with the complexity and cost of integrating new digital maintenance platforms with the disparate and often outdated IT and enterprise resource planning systems used by airlines.
- Capital-Intensive Tooling:The investment required for specialized equipment, such as autoclaves and automated fiber placement machines for composite repairs, represents a significant capital barrier for smaller MRO providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense MRO Market |
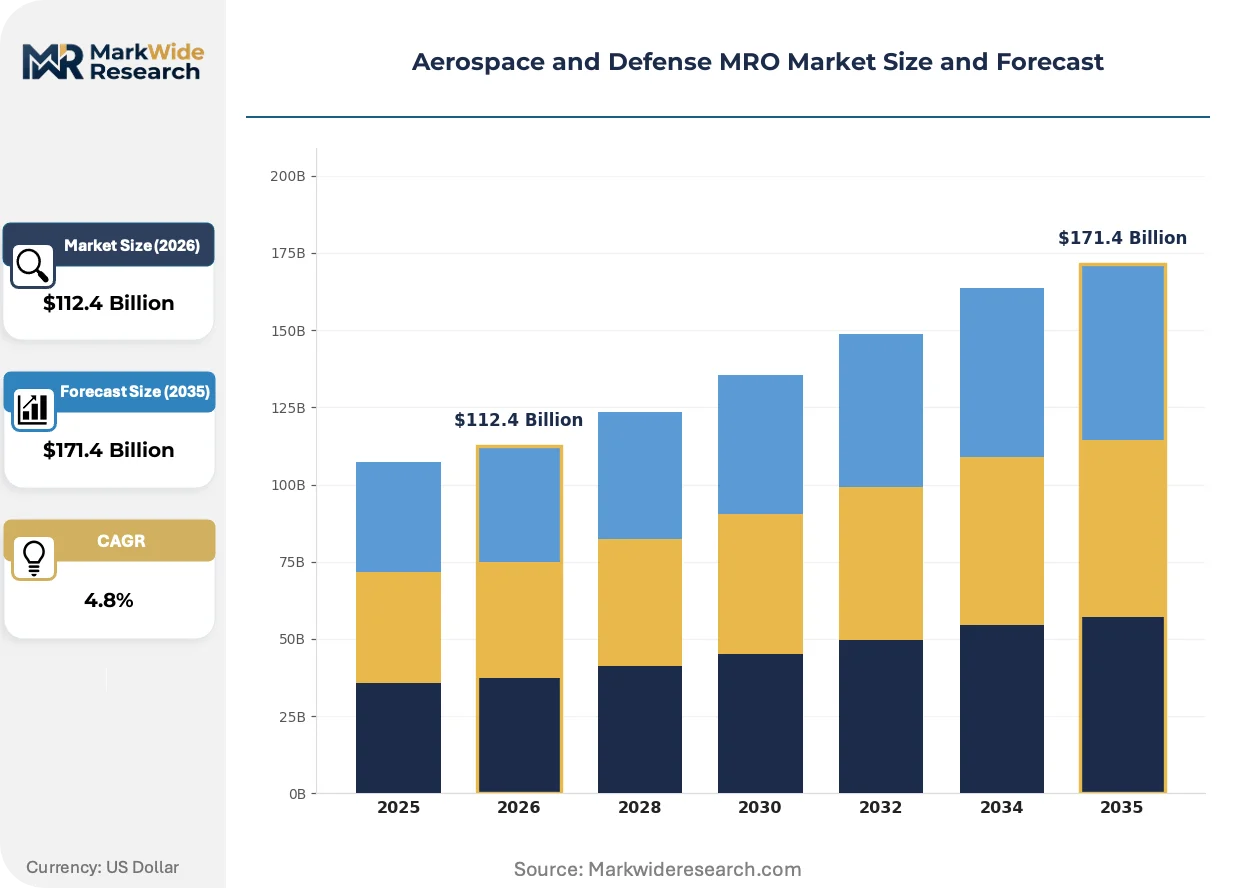
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Inspection End User: Commercial Aviation, Military Aviation, Space Agencies, Defense Contractors Component: Avionics, Engines, Airframes, Landing Gear Technology: Advanced Materials, Predictive Maintenance, Robotics, 3D Printing |
| Companies Covered | General Dynamics Corporation, L3Harris Technologies, RTX Corporation, HEICO Corporation, TransDigm Group, Lockheed Martin Corporation, Northrop Grumman Corporation, Woodward Inc., Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense MRO Market Strategic Shifts & Innovations
Digitalization is fundamentally transforming MRO from a reactive, break-fix model to a proactive, data-driven discipline. This evolution prioritizes aircraft availability and total lifecycle cost management over simple component repair, creating new value streams and competitive differentiators for service providers.
Technology and Product Evolution
Advanced digital twin technology creates a high-fidelity virtual model of a physical aircraft engine or airframe, updated in real-time with sensor data. Defense agencies and major commercial airlines are adopting this for their most critical and expensive assets to simulate operational stress and predict failures. This technology is absorbing traditional, calendar-based inspection schedules into a dynamic, condition-based maintenance paradigm that optimizes service intervals and extends component life.
Regulatory and Policy Shifts
European Union Aviation Safety Agency (EASA) mandates for enhanced parts traceability and sustainability are compelling changes in MRO operations. These rules require robust digital records, often using blockchain, to track a component's entire history and push for the use of greener repair processes. The engine overhaul segment is particularly affected, now needing to document material circularity and invest in technologies that reduce the environmental impact of engine test cells.
Demand-Side and Behavioral Shifts
Airlines are increasingly moving away from single-source, comprehensive MRO contracts in favor of unbundling services. This approach allows them to source specific work, such as engine overhauls or landing gear repairs, from specialized, best-in-class vendors to optimize cost and turnaround time. This shift disrupts the business model of large, integrated MROs and is most prominent in the mature aviation markets of North America and Europe.
Aerospace and Defense MRO Market Segmentation
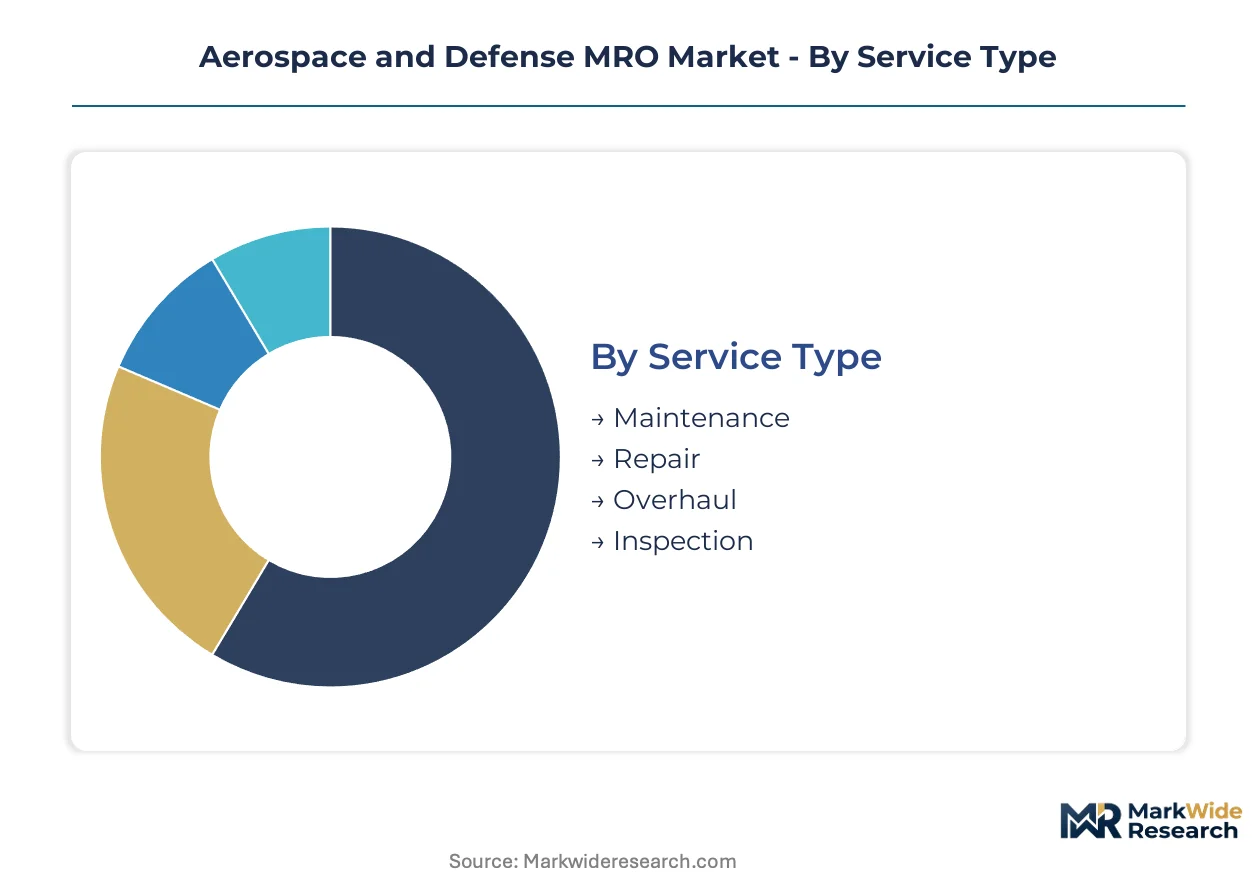
The Aerospace and Defense MRO market is structured across several key dimensions, each reflecting distinct operational requirements and value propositions. Understanding these segments is crucial for stakeholders to tailor service offerings and optimize resource allocation within this complex industry.
Service Type:
The Service Type category delineates the spectrum of activities from routine upkeep to complex structural interventions, reflecting varying levels of customization and standardization required for aircraft airworthiness.
- Maintenance:Encompasses routine checks, servicing, and minor repairs performed to ensure an aircraft's continued operational fitness and compliance with flight regulations. Commercial aviation operators in Europe increasingly prioritize preventative maintenance schedules to maximize fleet availability and reduce unexpected downtime.
- Overhaul:Involves comprehensive disassembly, inspection, repair, and reassembly of major components such as engines or landing gear, demanding specialized facilities and expertise. Demand for engine overhaul services in the United States remains strong, propelled by military and commercial airline requirements for extending asset lifecycles.
- Repair:Focuses on restoring damaged or malfunctioning parts and structures to their specified operational condition, often involving component-level work.
- Inspection:Involves detailed examinations of aircraft systems and structures to detect defects, wear, or damage, ensuring compliance with airworthiness directives.
Leading the category by volume: Maintenance. Growing fastest: Overhaul.
End User:
The End User segment differentiates MRO demand based on operational mission and contractual stability, influencing service delivery models.
- Commercial Aviation:Represents the largest segment, encompassing passenger and cargo airlines that require MRO services to maintain flight schedules and adhere to strict regulatory standards. The aging commercial fleet globally necessitates more frequent heavy maintenance checks, driving sustained demand for these services.
- Military Aviation:Involves MRO for defense aircraft, characterized by long-term contracts and stringent security protocols, often prioritizing mission readiness over cost optimization. US defense contracts frequently include extensive MRO provisions, ensuring operational readiness for critical military platforms.
- Space Agencies:Requires highly specialized MRO for spacecraft, launch vehicles, and related ground support equipment, focusing on mission-critical reliability and unique material requirements.
- Defense Contractors:Provides MRO services for government agencies, often managing complex weapon systems and offering integrated logistics support for military operations.
Strategic importance within this category centers on Military Aviation for long-term stability, while Commercial Aviation dominates the overall market volume.
Component:
The Component category highlights the varying technical complexity and value contribution of different aircraft parts to the overall MRO market.
- Engines:Represents the highest value component segment due to intricate design, advanced materials, and critical role in aircraft propulsion, demanding specialized overhaul capabilities. The integration of predictive maintenance for engine health monitoring is optimizing service intervals for these high-cost assets.
- Airframes:Encompasses the structural body of the aircraft, requiring extensive inspection and repair, especially for aging fleets, to address fatigue and corrosion. The shift to carbon composites in new aircraft designs is reshaping repair methodologies and technician skill requirements for airframe maintenance.
- Avionics:Includes the electronic systems for flight control, navigation, and communication, necessitating specialized diagnostic and repair expertise for complex digital platforms.
- Landing Gear:Involves the MRO of aircraft undercarriages, requiring robust maintenance schedules due to high stress and cyclical loading during takeoffs and landings.
Investment in specialized tooling is most pronounced for Engines, while Airframes drive significant labor hours in heavy maintenance.
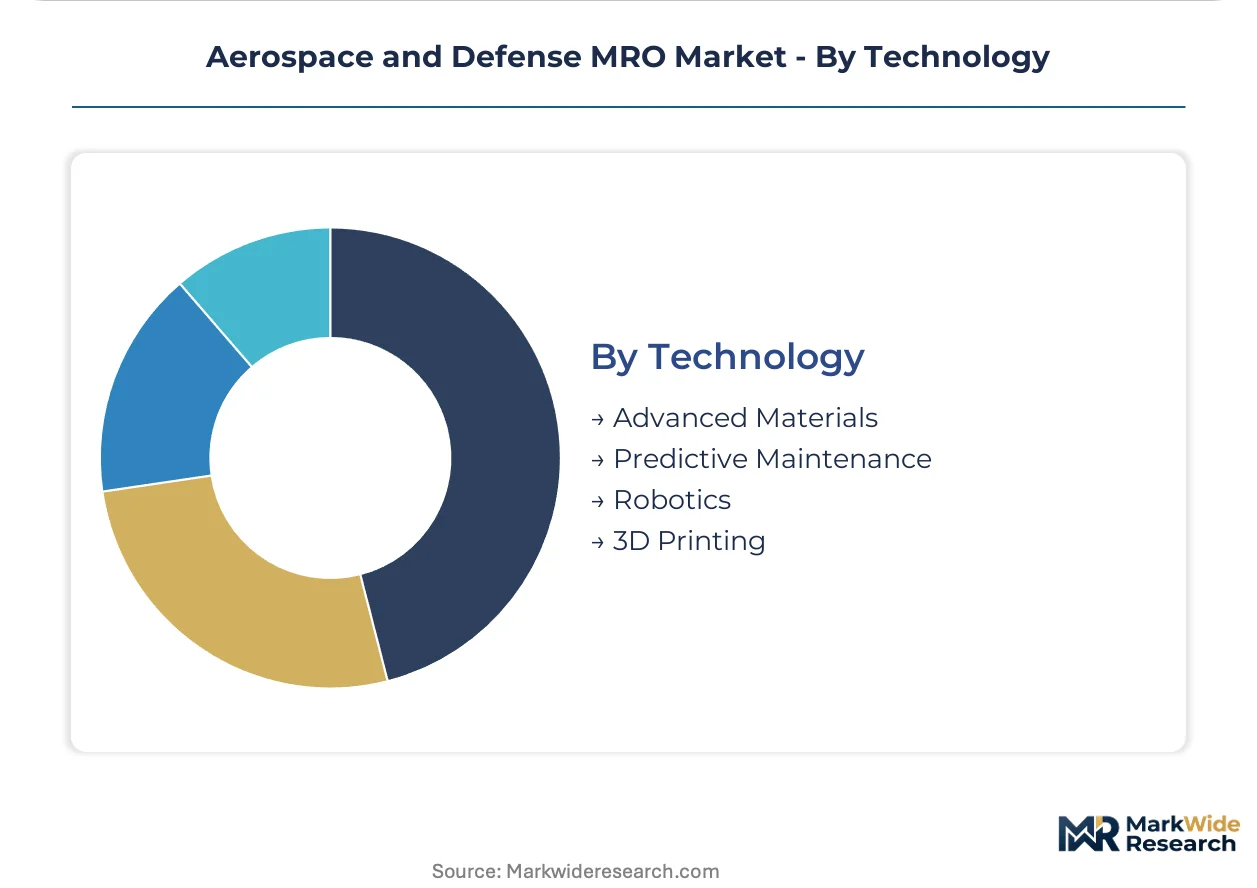
Technology:
The Technology segment illustrates how digital and material innovations are transforming MRO operational paradigms and service delivery models.
- Predictive Maintenance:Utilizes AI and machine learning to analyze flight data and forecast component failures, enabling a shift from scheduled to condition-based maintenance. This technology optimizes fleet availability and reduces unscheduled downtime for commercial airline operators.
- Advanced Materials:Involves MRO techniques for new-generation materials like carbon composites, requiring specialized knowledge and equipment for repair and structural integrity assessment. The substitution of legacy aluminum alloys with these materials is restructuring MRO service economics.
- Robotics:Employs automated systems for tasks such as inspection, painting, and drilling, enhancing efficiency and precision in repetitive MRO processes.
- 3D Printing:Allows for on-demand production of replacement parts and specialized tooling, offering potential for supply chain optimization and cost reduction in MRO operations.
Future potential within this category is highest for Predictive Maintenance in optimizing operational efficiency, with Advanced Materials driving innovation in repair methodologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Changi Aviation Park, a designated aerospace hub, drives significant MRO activity across Southeast Asia. This specialized zone attracts global service providers due to its strategic location and advanced infrastructure. It fosters regional collaboration and capacity building for complex aircraft maintenance operations.
United States
Demand for engine overhaul services in the United States remains strong, propelled by military and commercial airline requirements. The US Federal Aviation Administration (FAA) mandates rigorous certification for MRO facilities and parts. Wichita, Kansas, known as the "Air Capital of the World," hosts numerous MRO providers supporting both legacy and new aircraft.
France
European commercial aviation operators in France increasingly prioritize preventative maintenance schedules to maximize fleet availability. The European Union Aviation Safety Agency (EASA) enforces stringent airworthiness directives influencing MRO costs. Toulouse, a major aerospace center, supports extensive MRO activities for Airbus fleets and their components.
United Kingdom
Aging commercial fleets in the United Kingdom require more frequent heavy maintenance checks and structural repairs. The UK Civil Aviation Authority (CAA) oversees MRO regulatory compliance and parts traceability. London Gatwick Airport's surrounding industrial areas host specialized MRO companies serving numerous European airlines.
Germany
Stricter airworthiness directives from the EASA compel German operators to perform more rigorous inspections. Germany's defense sector also contributes to stable, long-term MRO contracts for military platforms. Hamburg, a key aerospace cluster, focuses on airframe modifications and cabin refurbishment for commercial aircraft.
Singapore
Southeast Asia's burgeoning low-cost carriers create substantial MRO demand for airframe and engine services in Singapore. The Civil Aviation Authority of Singapore (CAAS) ensures adherence to international MRO standards. Seletar Aerospace Park serves as a dedicated MRO hub, attracting major engine and component overhaul specialists.
Aerospace and Defense MRO Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the Aerospace and Defense MRO market, influencing service delivery models. The market structure exhibits a tiered consolidation, with large aerospace primes at the apex and numerous specialized component repair shops forming the base. Strategic archetypes encompass integrated OEM service providers, independent third-party MROs, and innovative alternative parts suppliers. Capacity expansion, often through targeted acquisitions, and strategic partnerships are dominant competitive moves among these diverse players, aiming to secure long-term contracts and enhance service capabilities.
Among the integrated OEM service providers, Lockheed Martin Corporation anchors the military MRO segment, offering extensive support for defense platforms. RTX Corporation occupies a significant position as a diversified technology and defense company, leveraging its avionics repair portfolio for modern aircraft. HEICO Corporation exemplifies the alternative parts supplier archetype, differentiating its offerings through FAA-approved components that provide cost-effective solutions. These companies reflect distinct strategies for capturing value across the complex MRO lifecycle and maintaining competitive positioning within their respective niches.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| L3Harris Technologies |
| RTX Corporation |
| HEICO Corporation |
| TransDigm Group |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Woodward Inc. |
| Boeing |
Cost & Logistics Intelligence
Nickel-based superalloy futures and composite resin prices cascade through the MRO supply chain, directly influencing the cost structures for engine overhaul and advanced airframe repairs. This volatility impacts pricing tiers across different service segments.
Pricing Analysis
Lead-time-driven pricing offers a premium for rapid turnaround times on critical component repairs, while standard lead times provide more cost-effective options. Contract-based long-term agreements dominate for major airlines and military MRO, offering predictable costs. Pricing differentiation stems from certification levels, such as FAA Parts Manufacturer Approval, and the degree of customization required for specialized repairs. Margin pressure stems from unpredictable material cost fluctuations for high-performance alloys. Commercial aviation operators exhibit higher price sensitivity compared to military clients, who prioritize mission readiness.
Supply Chain Analysis
Titanium and nickel-based superalloy supply largely draws from a concentrated base of global refiners and specialized manufacturers. OEM-specific parts for engines and avionics often depend on captive supply channels, limiting alternative sourcing. A structural risk involves composite repair bottlenecks, as specialized knowledge and equipment remain concentrated in specific regions, leading to longer turnaround times. Distribution for MRO parts and services runs through a mix of OEM-authorized service centers, independent MROs, and specialized third-party component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aerospace and Defense MRO market presents a supply-constrained environment, primarily due to the persistent scarcity of certified airframe and powerplant mechanics, which props up service pricing.
For Market Incumbents: Cement long-term service agreements with major airlines and defense departments to secure stable revenue streams against margin pressure from alternative parts suppliers. Invest in advanced composite repair capabilities and FAA-approved alternative parts certification to broaden service offerings. Expand capacity in strategic MRO hubs like Singapore to address regional demand. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks.
For New Entrants and Emerging Players: Digital twin technology integration offers a technology-first wedge into optimizing maintenance schedules for business and regional jet fleets. Target the underpenetrated Southeast Asia MRO market with specialized airframe and engine services for low-cost carriers. Develop subscription-based service models for predictable maintenance costs. Focus on remote assistance technologies for skill transfer and improved repair quality in emerging markets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor acquirers with strong balance sheets seeking specialized MRO capabilities in mature markets like the United States. Long-term viability rests on essential airworthiness mandates for aging fleets, ensuring sustained demand over a 5-10 year window. Target independent MROs with strong digital integration capabilities or unique composite repair expertise. A shift in regulatory mandates towards enhanced parts traceability and sustainability warrants ongoing watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Establishes a regional footprint to serve burgeoning low-cost carriers and capture long-term service contracts. |
| Predictive Maintenance Platform Investment | Optimizes fleet availability and reduces unscheduled downtime for commercial airline operators. |
| Advanced Composite Repair Certification | Addresses the growing demand for specialized maintenance of new-generation aircraft structures. |
| Subscription-Based Service Model Launch | Offers business and regional jet operators predictable maintenance costs and maximizes aircraft uptime. |
| Digital Twin Technology Adoption | Enables real-time monitoring and failure prediction for critical aircraft engines and airframes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews with MRO executives, airline fleet managers, defense procurement officers, and FAA officials. This approach combined bottom-up data aggregation with top-down market validation, ensuring a comprehensive view of the Aerospace and Defense MRO market.
Data-stream reconciliation integrated historical growth trends, expert interviews, and macroeconomic indicators to project market expansion across the analysis window. The analytical framework modeled market dynamics across service type, end-user, component, technology, and aircraft generation. Compound annual growth rates were derived from a synthesis of these data points, incorporating aircraft delivery forecasts and fleet retirement schedules as key industry-specific inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts or major global pandemics, which could significantly alter market trajectories. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market