
 Biomedical Warming and Thawing Devices Market | 2026-2036
Biomedical Warming and Thawing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Biomedical Warming and Thawing Devices Market Analysis
The EU Green Deal is pivoting procurement criteria across European healthcare systems toward energy-efficient thermal processing equipment. Thermo Fisher Scientific leverages its global distribution network to sustain leadership in integrated warming systems for cell therapy workflows. Helmer Scientific anchors its position through specialized engineering of plasma thawing devices with precise temperature control algorithms. Sartorius AG competes by dominating bioprocessing applications where single-use compatibility determines device selection.
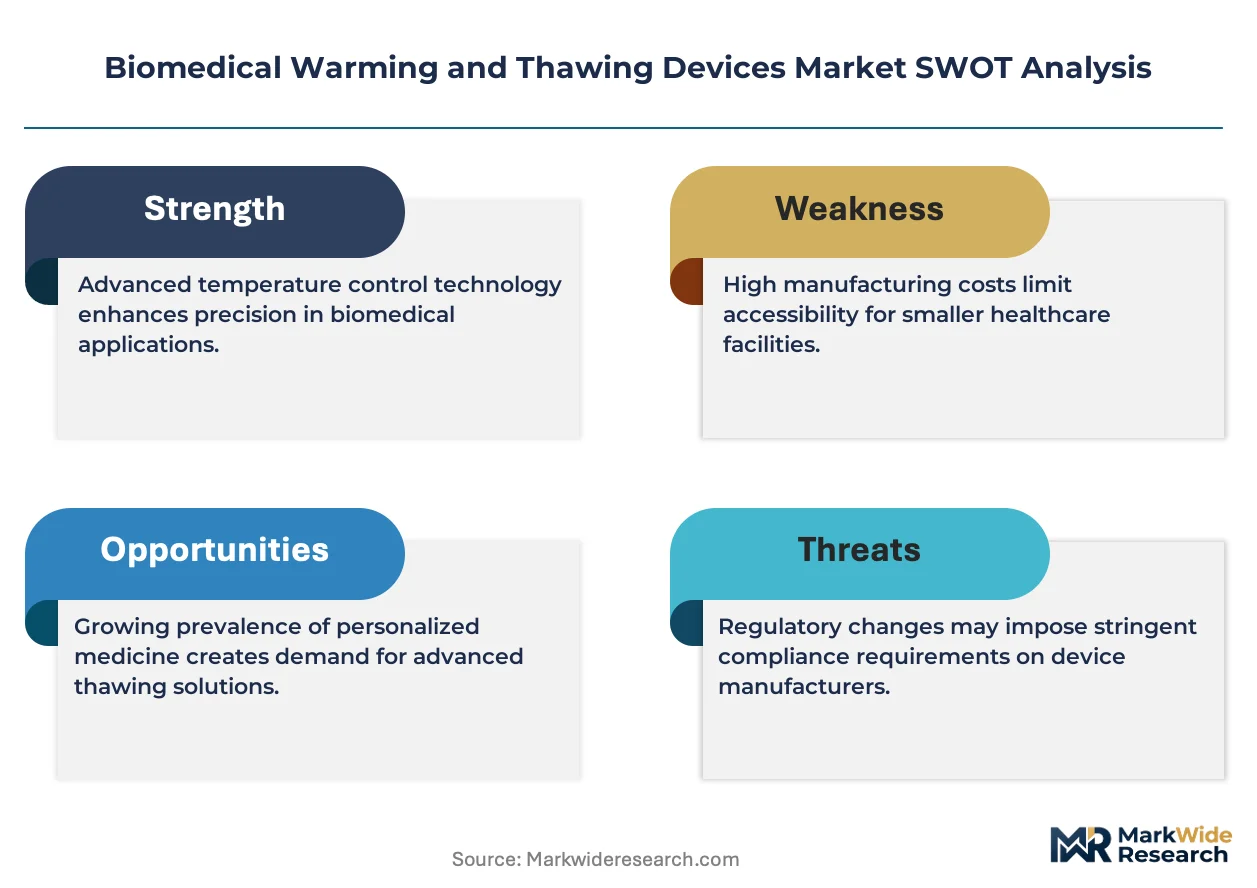
Biomedical warming and thawing devices are electromechanical systems designed to elevate frozen biological specimens from cryogenic or sub-zero states to controlled temperatures between 4°C and 37°C, utilizing conductive, convective, or radiant heat transfer mechanisms with programmable ramp rates to preserve cellular viability. These instruments serve critical functions in transfusion medicine, regenerative therapy manufacturing, and clinical diagnostics where thermal uniformity and traceability prevent hemolysis, protein denaturation, or loss of stem cell potency. Water bath systems retain the largest installed base across blood banking infrastructure due to established protocols and lower capital requirements, though dry heat block technology is displacing legacy methods in research laboratories where contamination risk and maintenance burden drive substitution. Integrated systems command premium positioning within cell and gene therapy manufacturing suites, where connectivity to manufacturing execution systems and batch record automation justify higher acquisition costs against regulatory audit demands.
FDA 21 CFR Part 820 quality system regulations, EU MDR technical documentation requirements, and ISO 13485 medical device quality management standards collectively shape product development timelines, clinical validation obligations, and market access pathways for device manufacturers. The FDA's Center for Biologics Evaluation and Research maintains specific thermal validation expectations for blood warming applications, while EU MDR reclassification pressures are forcing portfolio rationalization among smaller device firms unable to absorb notified body conformity assessment costs. Stakeholders must monitor evolving harmonization between FDA and EMA guidance documents on automated thawing processes for advanced therapy medicinal products, as divergent validation requirements threaten to fragment product development roadmaps and complicate global launch strategies.
Market Dynamics
Cell therapy manufacturing scale-up is compressing equipment procurement cycles and forcing thermal device suppliers to embed connectivity features that satisfy FDA 21 CFR Part 11 electronic record requirements.
Growth Catalysts
- EU MDR reclassification:Blood warming device manufacturers face elevated conformity assessment obligations that favor established engineering firms with notified body relationships.
- Plasma fractionation expansion:CSL Behring and Grifols facility investments in the United States are expanding demand for validated thawing protocols.
- Cryopreservation protocol standardization:ISO 20387 biobanking guidelines are mandating temperature traceability that drives replacement of unlogged water bath systems.
Market Restraints
- Stainless steel input volatility:316L grade price swings compress margin on precision-engineered heat blocks used in cell therapy suites.
- Notified body capacity bottleneck:EU MDR technical documentation backlogs extend time-to-market for novel thawing algorithms by 14-22 months.
- Dry heat substitution ceiling:Water bath thermal mass advantages in high-volume blood banking limit displacement rates despite contamination risks.
Strategic Opportunities
- India CDSCO pathway acceleration:Streamlined Class C medical device registration is opening access to government hospital blood center modernization programs.
- Closed-system bag-to-device interface standardization:Single-use supply chain partnerships with cell therapy media vendors create integrated workflow bundles.
- EU Green Deal procurement criteria:Energy-efficient thermal processing equipment specifications are rewriting tender evaluation scoring across German and French hospital networks.
Industry Challenges
- Multi-jurisdictional validation documentation:Divergent FDA and EMA thermal mapping requirements for automated thawing processes force redundant engineering cycles.
- Legacy LIMS integration complexity:Manufacturing execution system connectivity protocols vary across Thermo Fisher, Sartorius, and custom bioprocessing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomedical Warming and Thawing Devices Market |
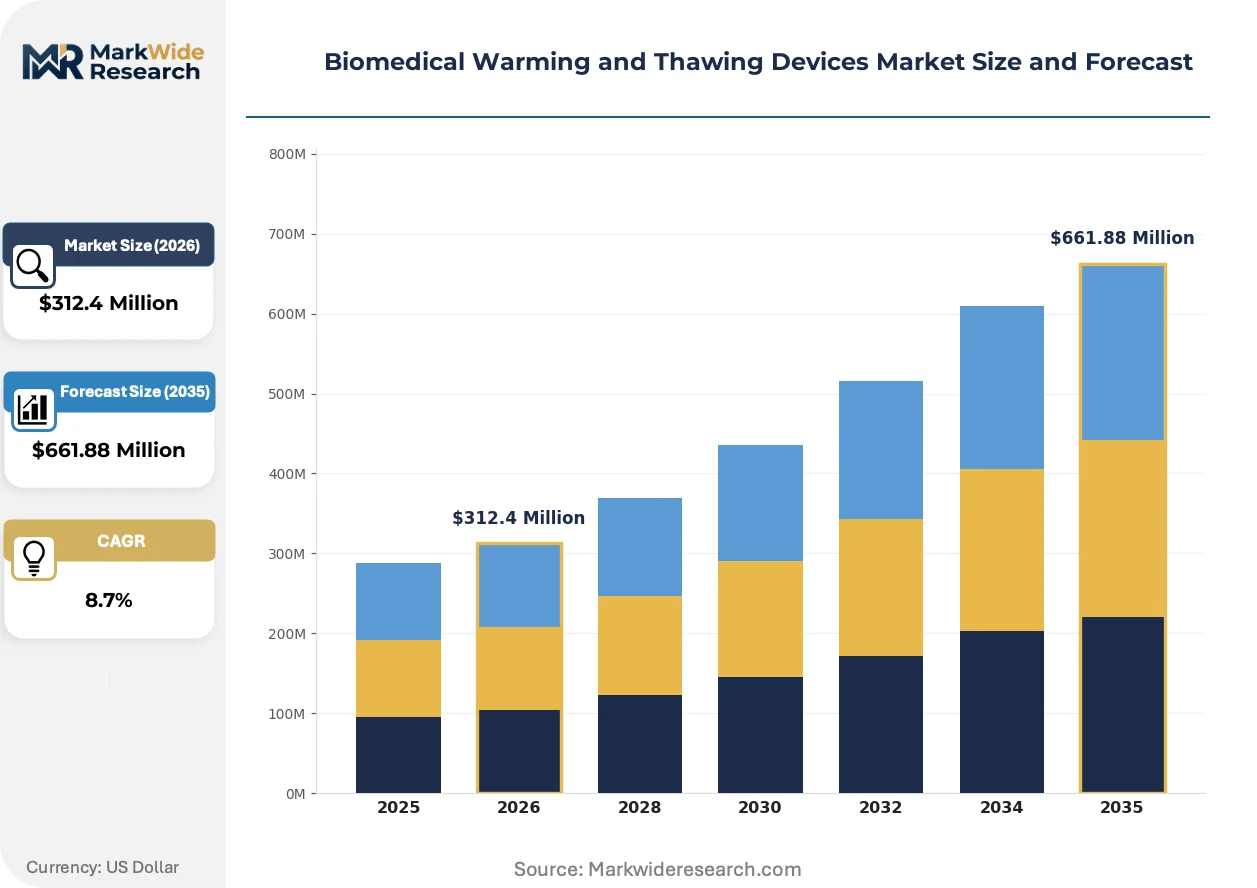
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
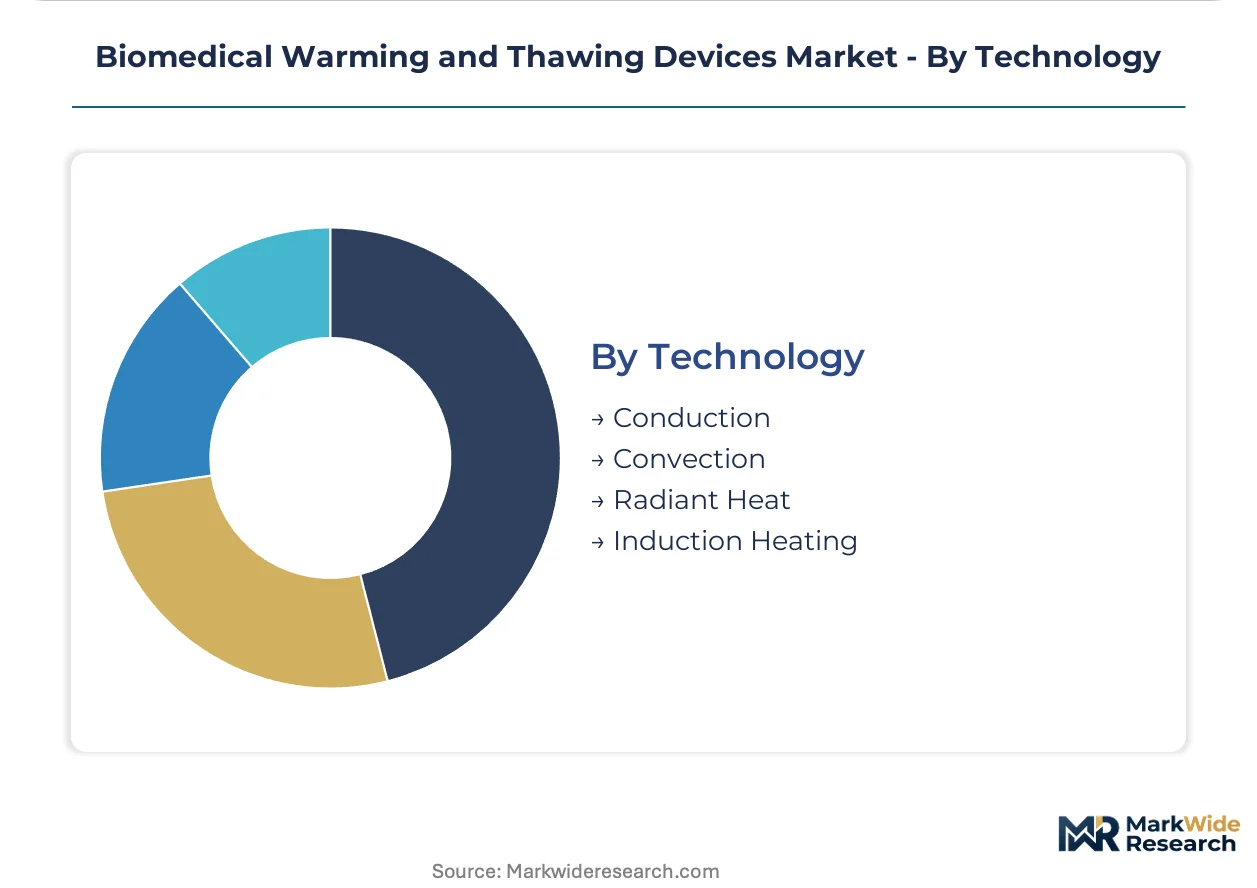
| Segmentation | Product Type: Water Bath, Dry Heat Block, Microwave Device, Heating Blanket Installation: Standalone Unit, Countertop Model, Integrated System, Mobile Device End User: Hospitals, Blood Banks, Research Laboratories, Clinics Technology: Conduction, Convection, Radiant Heat, Induction Heating |
| Companies Covered | Thermo Fisher Scientific, Helmer Scientific, Boekel Scientific, BioCision, Barkey GmbH & Co. KG, Sartorius AG, Cytiva, Cardinal Health, BioLife Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomedical Warming and Thawing Devices Market Emerging Trajectories
Dry heat block technology with programmable ramp rate control is displacing conductive water bath methods across research and clinical applications where contamination elimination and maintenance reduction justify capital premiums.
Radio frequency thawing systems using electromagnetic energy transfer at 13.56 MHz is decentralizing cell therapy manufacturing by enabling point-of-care thawing without water infrastructure. Academic medical centers in the United States are piloting these systems for chimeric antigen receptor T-cell workflows. The technology is decentralizing supply chain requirements and compressing cold chain dependencies for time-critical therapeutic administration.
EMA guidance on advanced therapy medicinal product handling is tightening thermal validation documentation for automated thawing equipment used in commercial manufacturing. Manufacturers must now submit batch record automation protocols alongside device technical files. Cell therapy contract development and manufacturing organizations in the Netherlands and Germany are absorbing these compliance costs through extended equipment qualification timelines.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases and negotiating preventive maintenance on utilization-based terms. Blood banking supervisors in the United States are driving this shift through group purchasing organization leverage. The model is most visible in multi-site hospital systems where centralized biomedical engineering teams perform first-line device maintenance internally.
Biomedical Warming and Thawing Devices Market Segmentation
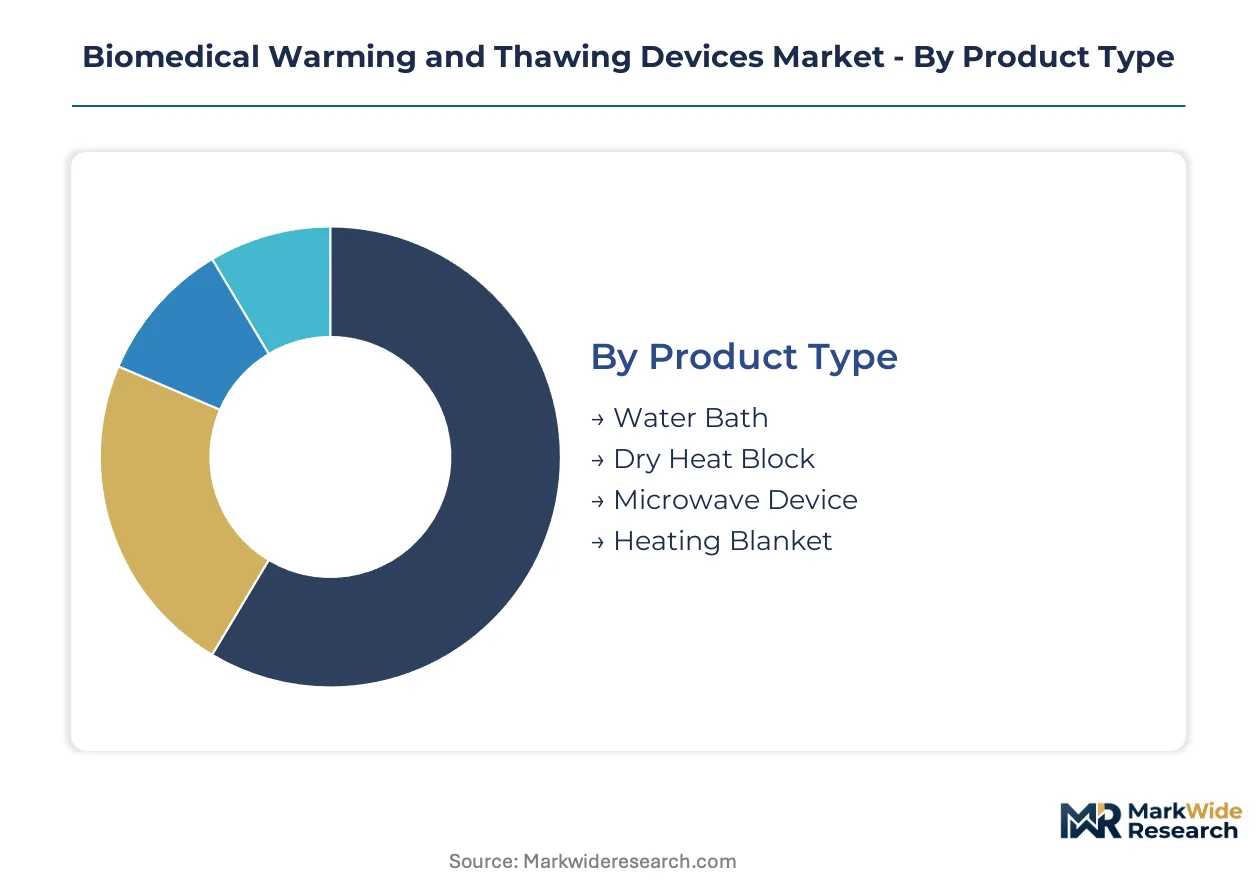
Thermal processing requirements diverge sharply between high-volume transfusion workflows and precision cell therapy manufacturing. Device specification, connectivity architecture, and validation documentation intensity vary across each segment boundary, forcing suppliers to maintain parallel product development tracks.
Product Type:
Standalone warming systems dominate blood banking infrastructure where protocol standardization outweighs integration demands, while embedded modules penetrate cell therapy suites requiring manufacturing execution system connectivity.
- Water Bath:Conductive immersion systems utilizing circulating heated fluid maintain thermal mass advantages for high-throughput plasma thawing. Blood banks across the United States retain these units for established AABB protocols despite contamination risks from open-water reservoirs.
- Dry Heat Block:Aluminum or ceramic block systems with programmable ramp rates eliminate waterborne contamination pathways. Research laboratories in Germany and the Netherlands are displacing legacy water baths where maintenance burden and sterility requirements drive substitution.
- Microwave Device:Electromagnetic energy transfer at controlled frequencies enables rapid thawing for emergency transfusion scenarios.
- Heating Blanket:Flexible conductive elements wrap around specimen containers for gentle temperature elevation in transport settings.
Volume placements concentrate in water bath systems; the faster expansion belongs to dry heat block technology.
Installation:
Capital deployment patterns split between facility-integrated infrastructure and portable units serving decentralized clinical workflows.
- Standalone Unit:Floor-mounted systems with independent power and control architecture serve dedicated blood processing rooms. Hospital transfusion services in France specify these configurations for 24/7 operational reliability.
- Countertop Model:Compact benchtop units occupy minimal laboratory real estate while maintaining precision temperature control. Research institutions in Japan favor these formats for multi-user core facility environments.
- Integrated System:Modular components embedded within larger bioprocessing platforms enable automated batch record generation.
- Mobile Device:Battery-powered or cart-mounted units facilitate point-of-care thawing outside centralized processing centers.
Standalone units absorb the largest capital allocation; integrated systems command the steepest expansion trajectory as cell therapy manufacturing scales.
End User:
Regulatory validation intensity and procurement authority structures reshape competitive access across institutional categories.
- Hospitals:Acute care facilities with transfusion medicine departments drive standardized equipment specifications through group purchasing organization contracts. FDA thermal validation requirements for blood warming applications constrain vendor qualification to established engineering firms.
- Blood Banks:Dedicated collection and processing centers maintain the highest installed base density per facility. EU MDR reclassification pressures are forcing portfolio consolidation among suppliers serving these accounts.
- Research Laboratories:Academic and commercial R&D settings prioritize flexibility over regulatory documentation.
- Clinics:Outpatient and specialty care settings with limited processing volumes favor simplified operational protocols.
Procurement volume clusters with blood banks; hospitals are gaining share fastest as cell therapy administration decentralizes to academic medical centers.
Technology:
Heat transfer mechanism selection determines thermal uniformity, ramp rate precision, and contamination risk profiles.
- Conduction:Direct surface-to-surface thermal transfer through metal blocks or water immersion delivers predictable temperature profiles. Blood banking supervisors in the United States specify conductive systems for compliance with established hemolysis prevention protocols.
- Convection:Forced air circulation enables non-contact warming with reduced contamination exposure. Cell therapy manufacturing suites in Switzerland are adopting convective systems where closed-system bag interfaces eliminate fluid contact.
- Radiant Heat:Infrared energy transfer provides rapid surface warming for emergency applications.
- Induction Heating:Electromagnetic field generation enables contactless energy transfer to metallic specimen containers.
Conduction retains the dominant installed base; convection is climbing the fastest as dry heat adoption accelerates in research and clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors North American demand for precision thermal processing equipment, with academic medical centers and contract manufacturing organizations driving specification standards for cell therapy workflows.
United States
FDA 21 CFR Part 820 quality system regulations and CBER thermal validation expectations shape procurement decisions across blood banking and cell therapy manufacturing. The Research Triangle Park in North Carolina hosts concentrated contract development and manufacturing organization activity where automated thawing system qualification timelines extend equipment replacement cycles.
Germany
EU MDR reclassification pressures and notified body conformity assessment backlogs favor established engineering firms with documented quality management systems. The Rhine-Main region around Frankfurt clusters pharmaceutical manufacturing facilities where energy-efficient thermal processing equipment procurement criteria are rewriting tender evaluation scoring.
Netherlands
EMA guidance on advanced therapy medicinal product handling tightens thermal validation documentation requirements for commercial manufacturing equipment. The Leiden bio science park concentrates cell therapy contract manufacturing organizations absorbing extended qualification timelines through batch record automation investments.
India
CDSCO streamlined Class C medical device registration opens government hospital blood center modernization programs to international suppliers. The Mumbai-Pune pharmaceutical corridor drives demand for validated thawing protocols as plasma fractionation capacity expands.
Switzerland
Swissmedic medical device regulations and ISO 13485 quality management standards support precision engineering specialization in thermal control algorithms. The Basel biotech cluster hosts cell therapy manufacturing suites adopting convective warming systems with closed-system bag interfaces.
Biomedical Warming and Thawing Devices Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory documentation depth and manufacturing execution system connectivity capabilities. The vendor base stratifies between integrated platform suppliers serving cell therapy workflows and standalone device specialists anchored in blood banking infrastructure. Three archetypes dominate: diversified life science conglomerates with global distribution networks, precision engineering specialists with notified body relationships, and bioprocessing-focused firms emphasizing single-use compatibility. Competitive moves concentrate on strategic partnerships with cell therapy media vendors for closed-system workflow bundles, and geographic expansion through streamlined regulatory pathways in emerging markets.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Sartorius AG exemplify platform-scale positioning through global distribution infrastructure and bioprocessing integration capabilities. Among precision engineering specialists, Helmer Scientific and Barkey GmbH & Co. KG occupy positions anchored in specialized thermal control algorithms and European regulatory compliance depth. BioLife Solutions represents the bioprocessing-focused archetype emphasizing cryopreservation media and thermal processing workflow integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Helmer Scientific |
| Boekel Scientific |
| BioCision |
| Barkey GmbH & Co. KG |
| Sartorius AG |
| Cytiva |
| Cardinal Health |
| BioLife Solutions |
| Others |
Supply Flow & Price Mechanics
316L stainless steel price volatility propagates through precision heat block manufacturing into three-tier pricing structures across premium, standard, and economy levels, with German and Swiss engineering firms commanding premiums for thermal control algorithms while Asian contract manufacturers absorb commodity swings in economy-tier water bath assemblies.
Pricing Analysis
Throughput-based value pricing anchors premium tiers where cell therapy manufacturers pay for validated ramp rate precision and FDA 21 CFR Part 11 electronic record integration. Price differentiation separates ISO 13485-certified systems with notified body documentation from uncertified laboratory units. Cost compression in mid-tier dry heat blocks is intensifying because research laboratories prioritize contamination elimination over regulatory depth. Blood banks exhibit highest price sensitivity due to group purchasing organization leverage, while cell therapy CDMOs show least sensitivity given qualification timeline costs.
Supply Chain Analysis
Dual-sourcing requirements for heating elements and temperature sensors mandate multi-supplier qualification across German, Japanese, and South Korean component vendors. Precision thermal control modules draw from Swiss and German engineering clusters, while commodity metal housings feed from Chinese and Indian fabrication. Single-source vulnerability concentrates in proprietary firmware for ramp rate algorithms. Distribution runs through specialized laboratory equipment distributors serving hospital systems and direct OEM relationships with cell therapy platform integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry heat block technology with programmable ramp rate control is displacing legacy water bath infrastructure, compressing equipment replacement cycles and rewriting procurement specifications across blood banking and cell therapy manufacturing.
For Market Incumbents: Extend connectivity architecture investments to defend against emerging radio frequency thawing entrants piloting point-of-care workflows in United States academic medical centers. Deepen backward integration into proprietary temperature sensor supply to offset 316L stainless steel margin compression. Prioritize notified body relationship expansion ahead of EU MDR technical documentation backlogs. For New Entrants and Emerging Players: Direct-to-research-laboratory digital channels bypass entrenched distributor relationships dominating hospital procurement. Target India CDSCO Class C registration pathway for government hospital blood center modernization programs. White-space exists in closed-system bag-to-device interface standardization partnerships with cell therapy media vendors. For Investors and Strategic Acquirers: EMA guidance publication on advanced therapy medicinal product thermal validation is the leading indicator that automated thawing equipment qualification timelines will extend materially. Long-term viability favors precision engineering specialists with documented ISO 13485 quality management systems and existing notified body relationships. Acquisition target archetype: European dry heat block specialists with proprietary ramp rate firmware and cell therapy manufacturing customer concentration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR reclassification demands elevated technical documentation for blood warming device market access. |
| Hospital System Partnership | Group purchasing organization contracts consolidate procurement authority across multi-site United States networks. |
| Software Companion Development | FDA 21 CFR Part 11 electronic record integration differentiates premium integrated warming systems. |
| Reimbursement Strategy | Cell therapy administration coding alignment accelerates point-of-care thawing device adoption. |
| Strategic Partnership | Single-use supply chain alliances with cell therapy media vendors create integrated workflow bundles. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, and ISO 13485 quality management audit records, complemented by interviews with blood bank supervisors, biomedical engineers, cell therapy manufacturing directors, and group purchasing organization contract managers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and CDSCO medical device registration filings. Bottom-up equipment installation estimates triangulated against top-down market sizing from thermal processing platform supplier disclosures.
Segment-level value and volume outputs across the analysis window reflect disaggregated modeling by product type, installation configuration, end-user institution, and heat transfer technology. CAGRs derived from logistic growth curve fitting to replacement cycle data and cell therapy manufacturing capacity expansion announcements. Industry-specific forecast inputs incorporated EU Green Deal energy efficiency procurement criteria and FDA CBER thermal validation expectation updates.
Inputs from notified body conformity assessment databases and cell therapy CDMO qualification timelines were available through the study window; gaps in proprietary ramp rate algorithm performance data introduce uncertainty bands around dry heat block adoption velocity. Forecasts reflect assumptions regarding EU MDR implementation pacing and plasma fractionation facility investment continuity. Deviation in FDA-EMA harmonization on automated thawing validation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Toe Fixation System Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Digital Phoropter Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Portable OT Light Market