
 Tissue Expanders Market | 2026-2036
Tissue Expanders Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Expanders Market Intelligence
Direct sales channels to large hospital networks are tilting the competitive balance away from smaller, independent distributors. Mentor Worldwide LLC leverages its established relationships within reconstructive surgery departments to secure supply contracts. AbbVie Inc., through its Allergan Aesthetics portfolio, competes on brand recognition and extensive clinical data. Meanwhile, Polytech Health & Aesthetics GmbH differentiates through a broad portfolio of anatomically shaped expanders for specialized procedures.
A tissue expander is an implantable medical device designed to stretch skin and underlying soft tissue to generate new tissue for reconstructive purposes. These devices typically consist of a silicone elastomer shell connected to a port that allows for the gradual injection of saline. Their primary function is to create sufficient skin coverage for procedures like breast reconstruction after mastectomy or for repairing large defects from trauma or burns. Breast reconstruction remains the dominant application, driving demand for both saline and silicone expanders. Hospitals represent the largest end-user segment, though ambulatory surgical centers are showing increased procedural volume.
Market access hinges on stringent regulatory approvals, such as the FDA's Premarket Approval (PMA) process in the United States and compliance with the EU's Medical Device Regulation (MDR). These frameworks, along with standards from bodies like China's NMPA, mandate extensive biocompatibility and clinical performance data for all implantable devices. Future material innovation and the development of expanders with integrated biosensors are critical areas for strategic investment.
Market Dynamics
The central tension shaping the tissue expanders market is the conflict between the clinical demand for greater product customization and the escalating costs and timelines of regulatory compliance. Stringent frameworks, especially the EU's MDR, demand extensive clinical data, which tempers the pace of innovation even as surgeons seek more patient-specific solutions.
Growth Catalysts
- Increased Post-Mastectomy Reconstruction:A higher rate of patients opting for breast reconstruction following mastectomies, particularly in developed economies, creates a consistent demand stream for both saline and silicone-based expanders.
- Favorable Reimbursement Policies:Strong reimbursement codes for reconstructive procedures in countries like the United States and Germany financially enable hospitals and ambulatory surgical centers to offer these services more widely.
- Advanced Biocompatible Materials:Innovations in silicone elastomer shells that minimize tissue irritation and capsular contracture are improving surgical outcomes, which in turn encourages broader clinical acceptance for complex reconstructions.
Market Restraints
- High Procedural Costs:The total cost, including the implantable device, surgery, and multiple follow-up appointments for saline inflation, can be a barrier in healthcare systems with limited insurance coverage for reconstructive surgery.
- Stringent Regulatory Hurdles:The FDA's Premarket Approval (PMA) process and the EU's Medical Device Regulation (MDR) create long and costly pathways to market, acting as a significant barrier for new entrants and product iterations.
- Risk of Complications:Potential complications such as infection, device deflation, or capsular contracture remain a clinical concern, requiring careful patient selection and sometimes leading to costly revision surgeries.
Strategic Opportunities
- Integrated Biosensors:Developing expanders with embedded sensors to monitor tissue pressure and oxygenation in real-time offers a pathway to personalized expansion protocols and reduced complication rates.
- Specialized Pediatric Devices:Designing smaller, anatomically specific expanders for congenital defect repair or pediatric trauma cases represents a high-value niche market segment with distinct, unmet clinical needs.
- Emerging Market Penetration:Untapped demand in countries like Brazil and South Korea, where aesthetic surgery is common but advanced reconstructive techniques are less saturated, presents a significant growth avenue.
Industry Challenges
- Silicone Supply Concentration:A heavy reliance on a few specialized suppliers for medical-grade silicone elastomer creates supply chain vulnerabilities and exposes manufacturers to price volatility for a critical raw material.
- MDR Compliance Burden:The transition to and ongoing compliance with the EU's MDR requires extensive investment in clinical data generation and technical documentation, straining the resources of many device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Expanders Market |
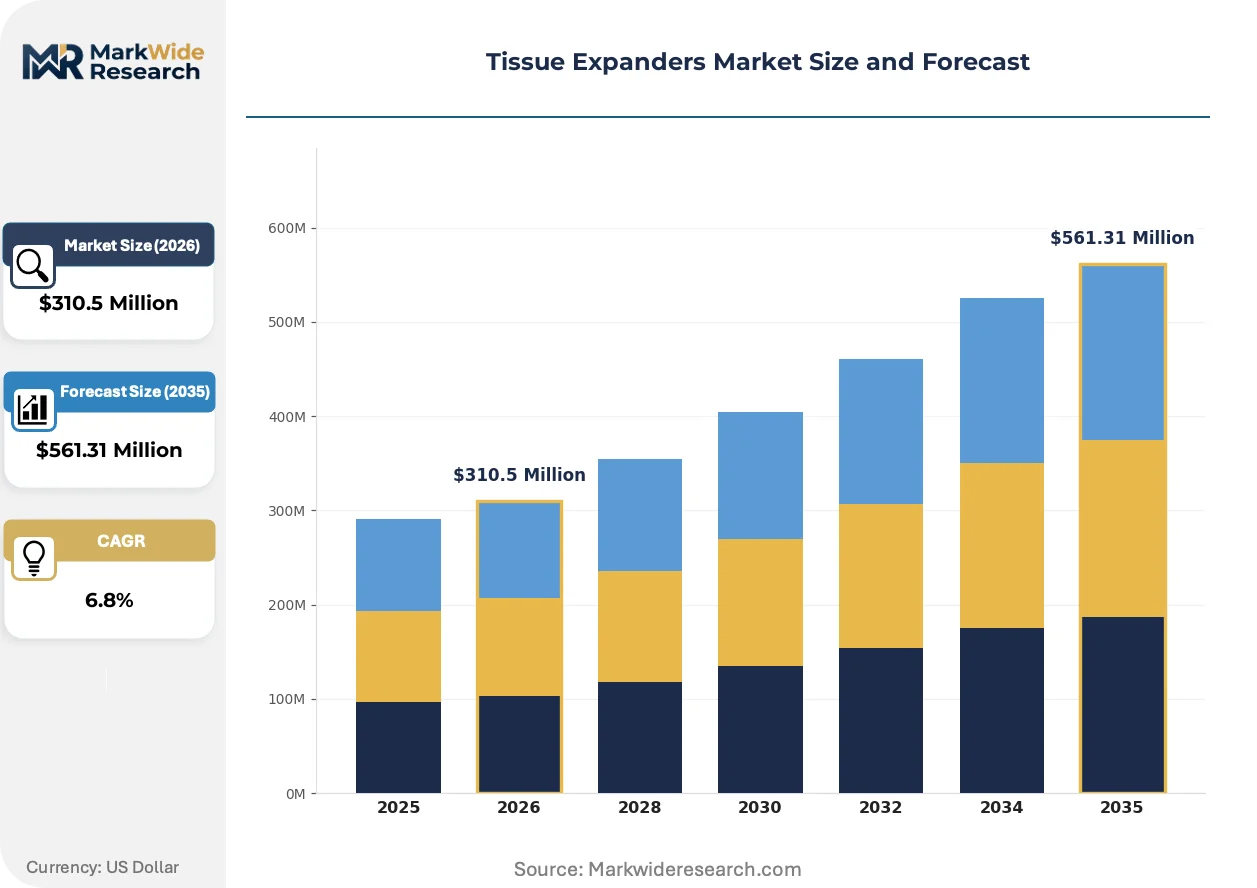
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $561.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
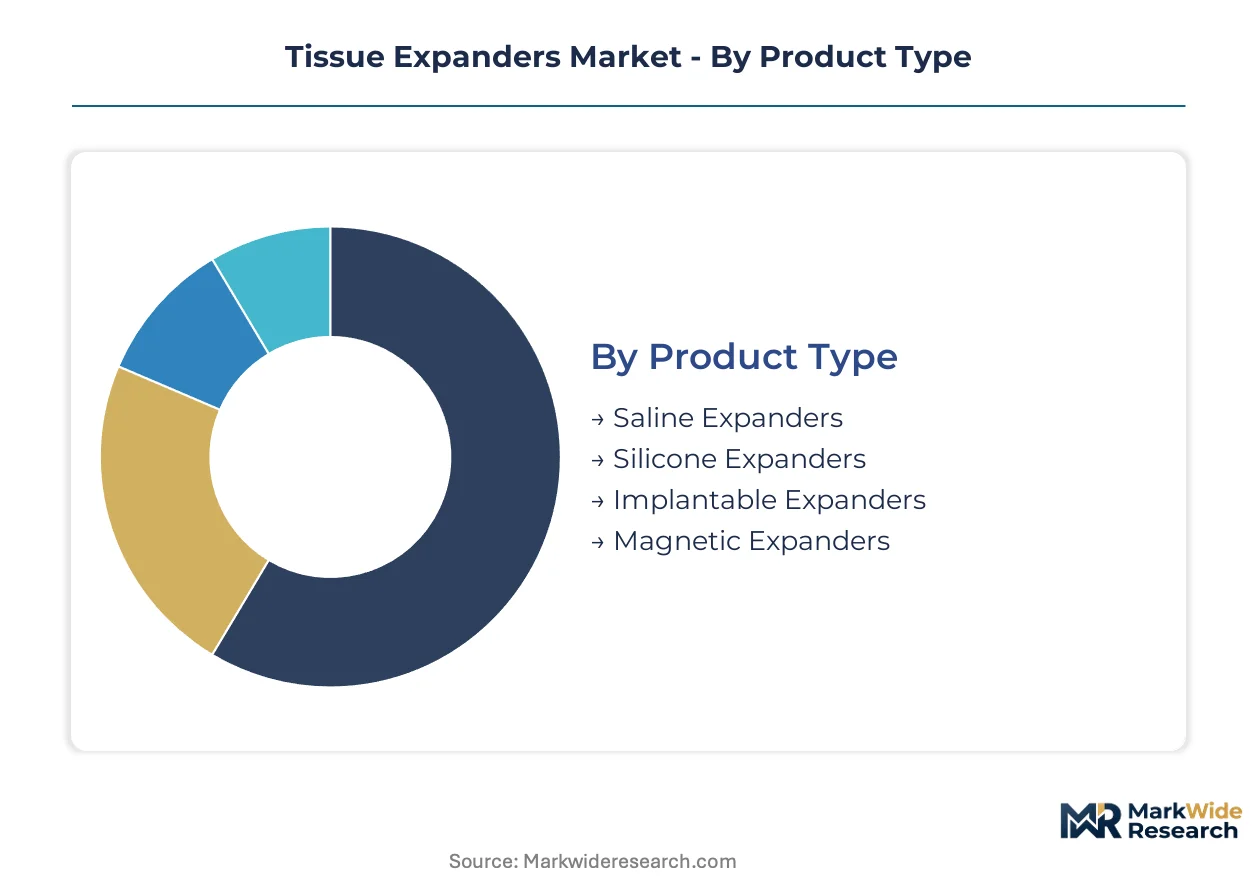
| Segmentation | Product Type: Saline Expanders, Silicone Expanders, Implantable Expanders, Magnetic Expanders End User: Hospitals, Ambulatory Surgical Centers, Dermatology Clinics, Cosmetic Surgery Centers Application: Breast Reconstruction, Tissue Regeneration, Cleft Palate Repair, Scarring Treatment Material: Silicone, Polyurethane, Polyethylene, Others |
| Companies Covered | Mentor Worldwide LLC, PMT Corporation, AbbVie Inc., Sientra, Inc., Sebbin, Guangzhou Wanhe Plastic Material Co.,Ltd, KOKEN CO., LTD., GC Aesthetics, Polytech Health & Aesthetics GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Expanders Market Strategic Shifts & Innovations
Product development is pivoting from standardized device shapes toward patient-specific solutions and data-informed expansion protocols. This evolution prioritizes superior clinical outcomes and reduced complication rates over historical one-size-fits-all approaches, influencing both design and regulatory strategy.
Anatomical Shaping and 3D Modeling
Anatomically shaped expanders utilize 3D modeling and varied silicone gel cohesivity to better match a patient's specific thoracic anatomy. Reconstructive surgeons are adopting these for complex and aesthetic-focused breast reconstruction cases. The market is migrating from generic, round expanders toward these customized forms that promise superior aesthetic results and better final implant matching.
Stricter Clinical Evidence Requirements
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all implantable devices. This regulation elevates the burden of proof for safety and performance, forcing manufacturers to generate more comprehensive long-term patient data. Devices with novel materials or anatomical designs are most affected, requiring fresh clinical investigations to secure or maintain CE marking.
Shift in Procedural Settings
A discernible shift in procedural settings is occurring for certain reconstructive surgeries. While hospitals remain the dominant end-user, ambulatory surgical centers (ASCs) are capturing a greater share of first-stage tissue expansion procedures due to efficiency and lower overhead. This trend is most prominent in the United States, driven by reimbursement models that favor outpatient settings for appropriate, non-emergency procedures.
Tissue Expanders Market Segmentation
Understanding the segmentation of the tissue expanders market reveals critical pathways for product development and market penetration. Each category highlights distinct clinical needs and technological preferences that influence purchasing decisions and adoption rates.
Product Type:
Product types are differentiated by their operational mechanics and turnover rates, with some devices seeing faster clinical cycles than others.
- Saline Expanders:These devices feature a silicone elastomer shell connected to a remote port, allowing for gradual, controlled inflation with sterile saline. Demand is particularly strong for breast reconstruction procedures in the United States, driven by established surgical protocols and favorable reimbursement.
- Silicone Expanders:Pre-filled with a cohesive silicone gel, these expanders are often anatomically shaped to better conform to a patient's natural contours. They are increasingly chosen for aesthetic-focused breast reconstruction in developed economies, offering superior cosmetic outcomes.
- Implantable Expanders:Designed for longer-term placement, these devices often incorporate integrated valves for inflation without a separate remote port.
- Magnetic Expanders:These innovative expanders utilize external magnetic fields for non-invasive, controlled tissue expansion, reducing the need for repeated needle punctures.
Saline Expanders dominate the installed base for initial tissue expansion. Silicone Expanders represent where expansion concentrates for aesthetic refinement.
End User:
End-user segments are differentiated by the complexity and scale of procedures performed.
- Hospitals:These facilities handle the largest volume of complex reconstructive cases, including extensive breast reconstruction and trauma-related tissue expansion. Hospitals in countries like Germany maintain significant procedural volume due to their comprehensive care capabilities.
- Ambulatory Surgical Centers:Specialized outpatient settings are increasingly capturing first-stage tissue expansion procedures due to their operational efficiency and lower overhead. This shift is pronounced in the United States, supported by evolving reimbursement models.
- Dermatology Clinics:These clinics primarily address minor skin defects and cosmetic enhancements, utilizing tissue expanders for smaller-scale reconstructive needs.
- Cosmetic Surgery Centers:Facilities focused on aesthetic procedures employ tissue expanders for body contouring and reconstructive work aiming for enhanced appearance.
Hospitals maintain the largest share of procedural volume. Ambulatory Surgical Centers are gaining procedural share most quickly.
Application:
Application segments reflect varying procedural volumes and clinical complexities.
- Breast Reconstruction:This remains the primary application for tissue expanders, particularly following mastectomies to create sufficient skin for permanent implant placement. High rates of post-mastectomy reconstruction in the United States drive significant demand.
- Tissue Regeneration:Expanders are crucial for generating new skin and soft tissue to repair large defects resulting from severe burns or traumatic injuries. This application is critical for complex wound management and reconstructive surgery globally.
- Cleft Palate Repair:Pediatric surgeons utilize tissue expanders to create adequate local tissue for the intricate reconstruction required in cleft palate cases.
- Scarring Treatment:Expanders help stretch healthy skin adjacent to severe burn scars or contractures, providing donor tissue for coverage and improving functionality.
Breast Reconstruction drives the majority of demand. Tissue Regeneration offers expanding opportunities in complex cases.
Material:
Material types influence device performance and regulatory compliance.
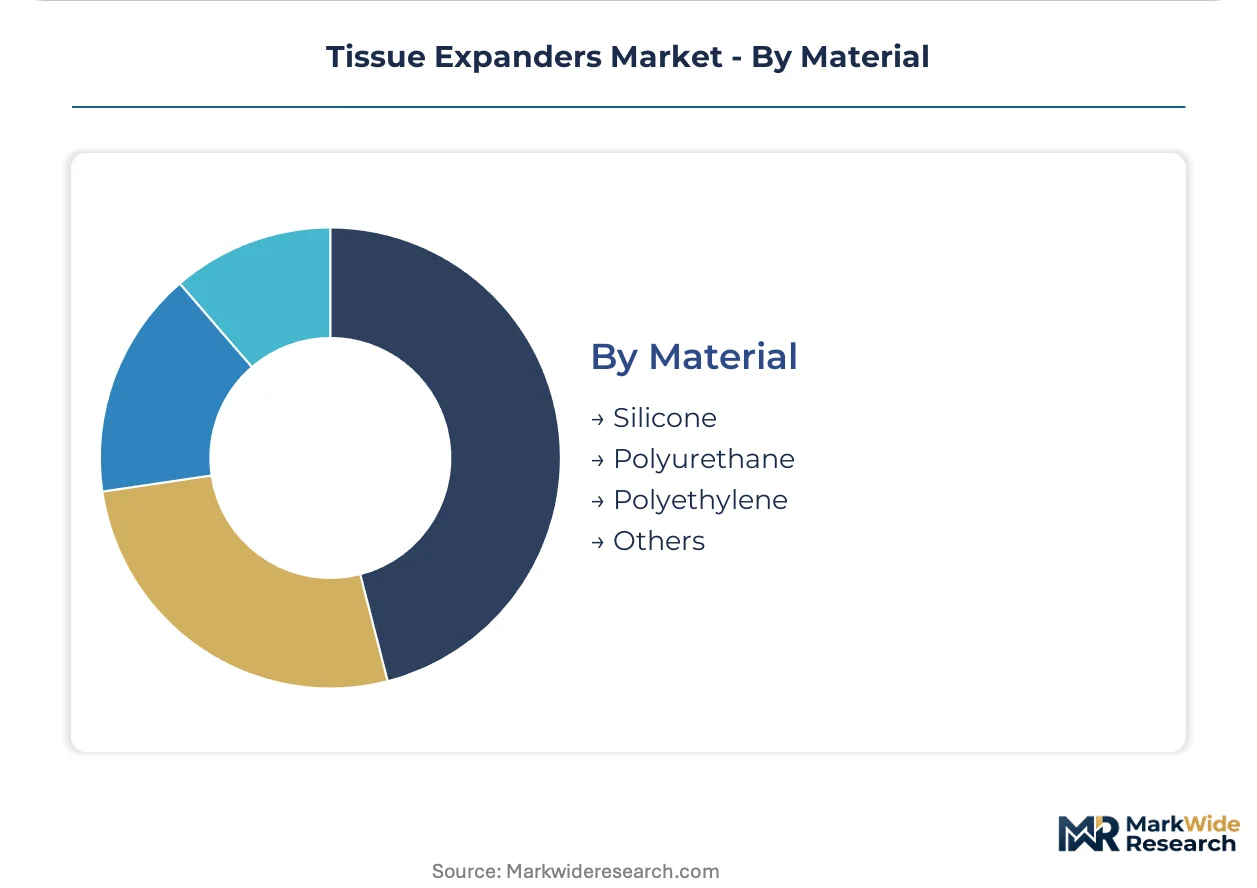
- Silicone:This is the predominant material for tissue expander shells due to its excellent biocompatibility, flexibility, and established safety profile. High acceptance for breast reconstruction is driven by extensive clinical data.
- Polyurethane:Used as a coating on some expanders, polyurethane may help reduce the incidence of capsular contracture, a common complication. Niche applications in Europe seek its benefits for improved patient outcomes.
- Polyethylene:While less common for expander shells, polyethylene is explored for certain implantable devices requiring greater rigidity or specific structural properties.
- Others:This category encompasses various experimental or less frequently used biocompatible polymers, including advanced hydrogels and bioresorbable materials for specialized applications.
Silicone remains the foundational material for tissue expanders. Innovations in Polyurethane and other advanced polymers are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's stringent approval processes in the United States ensure high standards for tissue expanders, anchoring significant market demand. Favorable reimbursement policies and a high rate of post-mastectomy reconstruction procedures drive consistent product uptake. This robust regulatory environment influences global market dynamics.
United States
High rates of breast reconstruction following mastectomies drive demand for tissue expanders across the United States. Favorable reimbursement policies, particularly from Medicare, support widespread access to these procedures. Medical device manufacturing hubs in states like California focus on developing advanced biocompatible materials for expander shells.
Germany
Patients in Germany increasingly opt for reconstructive surgeries, boosting demand for saline and silicone expanders. The EU's Medical Device Regulation (MDR) sets strict compliance requirements for all implantable devices sold within the country. Medical technology clusters in regions like Bavaria are centers for innovation in anatomically shaped expander designs.
China
Expanding healthcare infrastructure and a rising middle class in China contribute to growing demand for reconstructive aesthetic procedures. The NMPA's rigorous approval process for medical devices ensures product safety and efficacy. Manufacturing zones in cities like Guangzhou are developing domestic production capabilities for silicone-based expanders.
Brazil
Significant demand for aesthetic and reconstructive surgeries fuels the tissue expanders market in Brazil. ANVISA regulates the import and sale of all medical devices, including expanders, ensuring patient safety. Sao Paulo's medical tourism sector and private clinics drive high procedural volumes for specialized expander applications.
South Korea
A strong cultural emphasis on aesthetic appearance drives demand for advanced reconstructive techniques and specialized tissue expanders in South Korea. The MFDS enforces strict regulatory standards for medical devices, requiring extensive clinical data. Seoul's advanced medical facilities are at the forefront of developing innovative expander technologies.
Tissue Expanders Market Key Industry Players
Established multinational conglomerates and specialized device manufacturers split the tissue expanders market, creating a tiered competitive structure. Larger entities leverage extensive direct sales channels to hospital networks, securing market share through established relationships and brand recognition. Smaller, agile firms differentiate through product specialization and targeted market penetration, often focusing on niche applications. Competitive moves include strategic partnerships for material innovation, geographic expansion into emerging economies, and the generation of extensive clinical data for regulatory compliance.
On the established global player front, Mentor Worldwide LLC, a Johnson & Johnson company, represents a dominant force, leveraging its deep relationships within reconstructive surgery departments for supply contracts. AbbVie Inc., through its Allergan Aesthetics portfolio, exemplifies a strategy centered on brand recognition and extensive clinical data to maintain its market position. Polytech Health & Aesthetics GmbH, a German-based company, occupies a niche by offering a broad portfolio of anatomically shaped expanders for specialized procedures, anchoring the segment for customizable solutions.
| Leading Market Players |
|---|
| Mentor Worldwide LLC |
| PMT Corporation |
| AbbVie Inc. |
| Sientra, Inc. |
| Sebbin |
| Guangzhou Wanhe Plastic Material Co.,Ltd |
| KOKEN CO., LTD. |
| GC Aesthetics |
| Polytech Health & Aesthetics GmbH |
| Others |
Cost & Logistics Intelligence
A heavy reliance on a few specialized suppliers for medical-grade silicone elastomer creates supply chain vulnerabilities and exposes manufacturers to price volatility, impacting downstream margins across the tissue expanders market.
Pricing Analysis
Significant price variations for tissue expanders exist across different geographies, reflecting diverse healthcare system structures and reimbursement policies. The dominant pricing model is per-unit transactional, often structured through long-term contracts with large hospital networks. Price differentiation stems from brand premium and the level of customization, particularly for anatomically shaped expanders with specific certifications like FDA or CE marking. Pricing pressure stems from the increasing influence of group purchasing organizations and cost-conscious ambulatory surgical centers. Ambulatory surgical centers are generally more price-sensitive than large, comprehensive hospital systems.
Supply Chain Analysis
Price volatility for medical-grade silicone elastomer dominates the tissue expanders supply chain, posing a significant challenge for manufacturers. Key geographic supply concentration for specialized silicone components includes China, Germany, and the United States. The market relies heavily on medical-grade silicone and sterile saline as critical raw material inputs. Single-source vulnerability for highly specialized components represents a structural risk. Distribution runs through direct sales channels to large hospital networks, while independent distributors serve smaller clinics and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue expanders market is experiencing a cyclical recovery, driven by increasing rates of post-mastectomy breast reconstruction procedures.
For Market Incumbents: Build regulatory moat by investing heavily in clinical data generation for new product iterations and post-market surveillance adherence. Deepen relationships with large hospital networks through comprehensive service offerings and expand product portfolios to include specialized anatomical shapes. This strategy counters the threat from emerging entrants offering novel material innovations. Investing in R&D for integrated biosensors acts as a key lever for future differentiation.
For New Entrants and Emerging Players: Specialized pediatric devices for congenital defect repair represent a high-value, under-addressed niche market segment. Target emerging markets like Brazil and South Korea, where aesthetic surgery is common but advanced reconstructive techniques are less saturated. Capturing first-stage procedures in ambulatory surgical centers also offers a penetrable entry point. A go-to-market angle focusing on differentiated product features like magnetic expansion or advanced biocompatible materials offers a competitive edge.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, specialized device manufacturers focusing on niche applications or specific anatomical designs. Long-term demand for reconstructive surgery ensures sustained market viability over the next 5-10 years. Acquisition targets include companies with strong intellectual property in material science or patient-specific solutions. Increased M&A activity involving smaller firms with novel expander technologies serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Generation | Secures CE marking under EU MDR, reinforcing market access and trust. |
| Anatomical Expander Development | Meets surgeon demand for patient-specific aesthetic outcomes and better fit. |
| Direct Hospital Channel Expansion | Leverages established relationships for secure supply contracts and market share. |
| Emerging Market Entry | Captures growing demand for reconstructive procedures in regions like Brazil. |
| Biosensor Integration R&D | Offers pathway to personalized expansion protocols and reduced complications. |
Research Approach
A standing panel of reconstructive surgeons, hospital procurement specialists, and medical device engineers provided ongoing calibration for market trends and product adoption rates. Primary interviews with these stakeholders were combined with secondary validation from FDA filings, EU MDR documentation, and industry association reports. Bottom-up and top-down triangulation ensured data consistency and comprehensive market understanding.
Scenario-bracketing around regulatory shifts and material innovation defined the forecast framework, accounting for potential high and low growth trajectories across the analysis window. Segmentation dimensions modeled included product type, end-user, application, material, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected procedural volumes. Mastectomy rates and evolving reimbursement policies served as key forecast inputs.
Practitioners should monitor significant changes in medical device regulations and material supply chain stability for early signals impacting market projections. Forecasts reflect documented assumptions regarding clinical acceptance and technological advancements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Plethysmograph Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
3D Printed Medical Devices Market