
 AI Colonoscopy Withdrawal Quality Monitoring System Market | 2026-2036
AI Colonoscopy Withdrawal Quality Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
AI Colonoscopy Withdrawal Quality Monitoring System Market Insights
Gastroenterologist training capacity is unwinding as a bottleneck, with fellowship programs struggling to produce sufficient procedural specialists for expanding screening volumes. Medtronic leverages its integrated endoscopy hardware ecosystem to bundle AI analytics with scope sales. Olympus sustains dominance in optical imaging platforms while building software partnerships for quality analytics. FUJIFILM competes through dual strength in endoscope manufacturing and AI algorithm development.
An AI colonoscopy withdrawal quality monitoring system is a computer-vision platform that analyzes real-time or recorded colonoscope video feeds to measure withdrawal time, mucosal inspection completeness, and procedural technique against clinical benchmarks such as the 6-minute minimum withdrawal standard. These systems generate automated quality scores that feed into physician credentialing, pay-for-performance contracts, and population health reporting. Software-based solutions capture expanding share as hospitals prioritize interoperability with existing PACS and EHR infrastructure, while hardware-based systems retain traction in ambulatory surgery centers seeking turnkey installations. Cloud-enabled platforms represent the fastest-growing deployment architecture, though edge computing variants gain preference where latency constraints or institutional data governance policies limit external data transmission.
The FDA regulates these systems as Software as a Medical Device under 21 CFR 820 quality system requirements, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for AI diagnostic aids. Japan's PMDA has streamlined approval pathways for AI-enabled endoscopy tools, creating regulatory arbitrage that shapes manufacturer market entry sequencing. Stakeholders must monitor evolving reimbursement codes for AI-assisted procedures and the convergence of quality monitoring data with malpractice risk assessment frameworks.
Market Dynamics
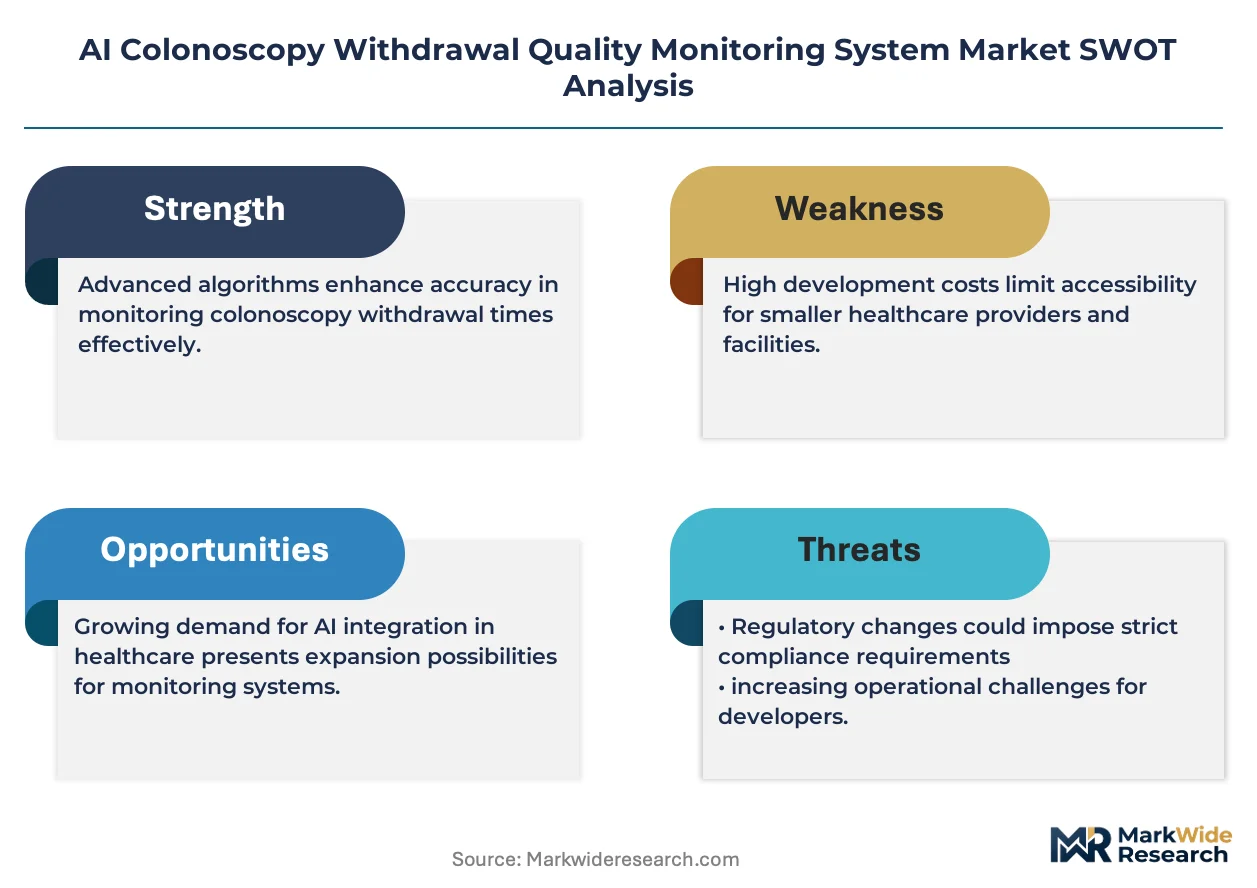
The embedding of colonoscopy quality metrics into Medicare reimbursement frameworks is restructuring purchasing priorities across hospital systems and ambulatory surgery centers, forcing capital allocation toward validated AI analytics platforms over unvalidated software tools.
Growth Catalysts
- Screening Program Expansion:National colorectal cancer screening initiatives in Germany and Japan are mandating quality documentation, creating procurement pull for automated monitoring systems in gastroenterology clinics.
- FDA Breakthrough Device Pathway:Accelerated regulatory timelines for AI-enabled endoscopy tools are compressing commercialization cycles and reducing capital recovery periods for developers.
- Cloud Infrastructure Maturation:HIPAA-compliant cloud deployments are enabling real-time quality analytics without on-premise hardware investments, lowering adoption barriers for mid-sized hospital networks.
Market Restraints
- GPU Supply Concentration:Dependence on NVIDIA and AMD for specialized inference chips creates input cost volatility and allocation risk for hardware-integrated system manufacturers.
- Clinical Validation Burden:The EU Medical Device Regulation imposes prospective clinical evidence requirements that extend approval timelines and inflate development costs for algorithm developers.
- Physician Workflow Disruption:Real-time video analysis systems introduce alert fatigue and cognitive load that gastroenterologists resist without demonstrated malpractice risk reduction.
Strategic Opportunities
- Rural Health Network Penetration:Federally Qualified Health Centers in the United States lack on-site gastroenterology expertise, creating demand for telemedicine-integrated quality monitoring that enables remote procedure oversight.
- AI-EMR Convergence:Native integration with Epic and Cerner workflows is displacing standalone quality reporting tools, rewarding vendors with existing health system EHR relationships.
- Pay-for-Performance Contracts:Commercial insurers in Japan are piloting quality-adjusted reimbursement models that directly tie physician compensation to automated inspection completeness scores.
Industry Challenges
- Gastroenterologist Fellowship Shortage:Training program capacity constraints are limiting the procedural specialist pipeline needed to operate installed base expansion and justify quality monitoring infrastructure.
- Interoperability Certification Complexity:DICOM conformance testing and IHE integration profiles require 18-24 month validation cycles that delay product launches and strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Colonoscopy Withdrawal Quality Monitoring System Market |
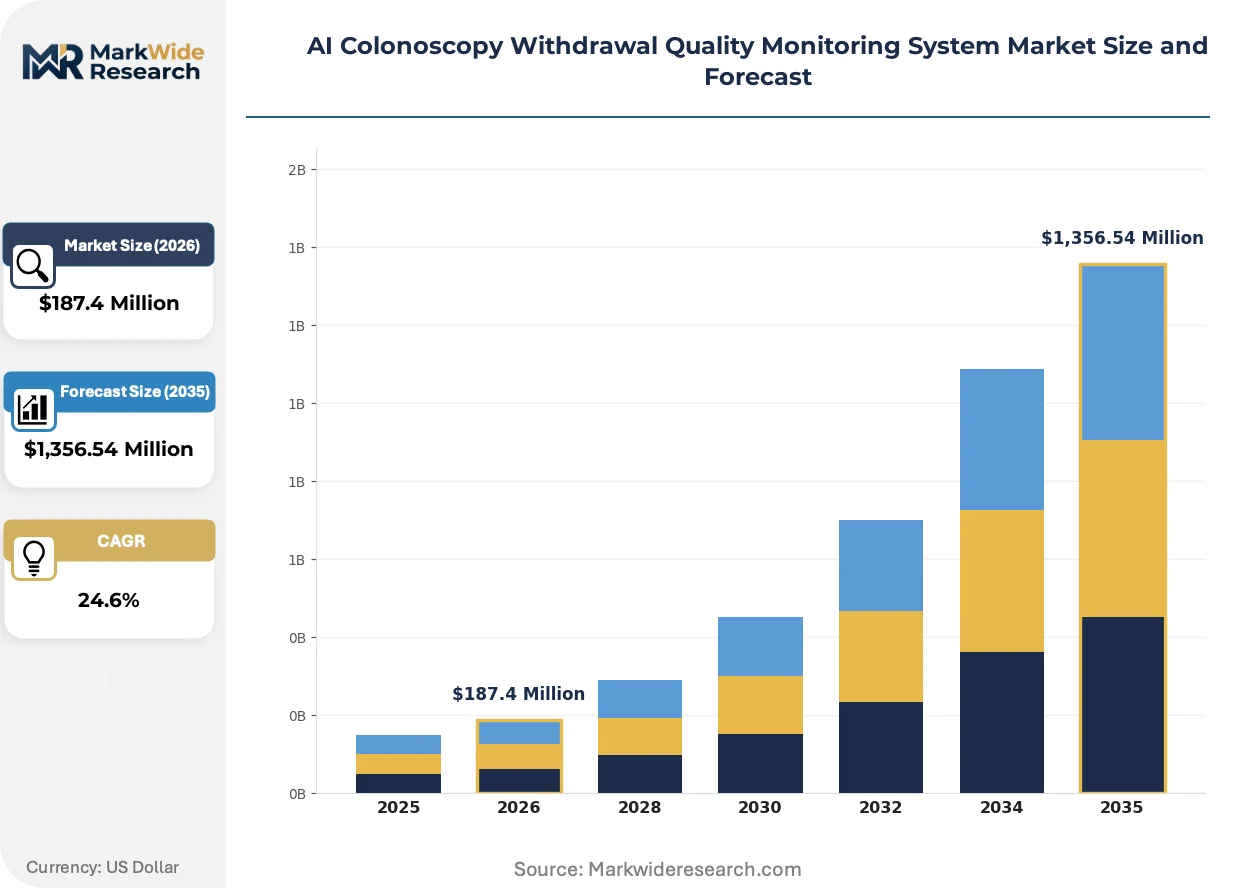
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,356.54 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware-Based Systems, Software-Based Solutions, Hybrid Systems, Cloud-Enabled Platforms Deployment: On-Premise, Cloud-Based, Edge Computing, Hybrid Deployment Application: Colorectal Cancer Screening, Polyp Detection and Classification, Therapeutic Procedure Assistance, Quality Assurance Monitoring End User: Gastroenterology Clinics, Ambulatory Surgery Centers, Diagnostic Laboratories, Research Institutes |
| Companies Covered | Medtronic, Olympus, FUJIFILM, PENTAX Medical, Wuhan ENDOANGEL Medical Technology, Chengdu Wision Medical Device, NEC Corporation, MAGENTIQ EYE, Iterative Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Colonoscopy Withdrawal Quality Monitoring System Market Trends and Innovations
Real-time computer vision architectures are displacing retrospective video review, embedding quality measurement directly into procedure workflow rather than post-hoc audit processes.
Edge computing deployments are decomposing the traditional cloud-centric architecture for latency-sensitive applications. Ambulatory surgery centers in Texas and Florida are adopting on-device inference to eliminate network dependency during procedures. This shift is compressing infrastructure requirements and enabling quality monitoring in bandwidth-constrained environments.
Japan's PMDA has streamlined software-as-medical-device approval pathways for AI endoscopy tools, reducing clinical evidence thresholds for algorithm updates. Domestic manufacturers are exploiting this regulatory arbitrage to accelerate iterative model improvements. European developers are sequencing market entry through Tokyo to leverage accelerated timelines before pursuing CE marking under MDR.
Hospital procurement committees are consolidating vendor relationships around integrated endoscopy platforms rather than point solutions. Gastroenterology departments in academic medical centers are bundling AI analytics with scope replacement cycles, displacing standalone software purchases. This concentration is visible most acutely in the United States, where IDN purchasing power is compressing the vendor landscape.
AI Colonoscopy Withdrawal Quality Monitoring System Market Segmentation
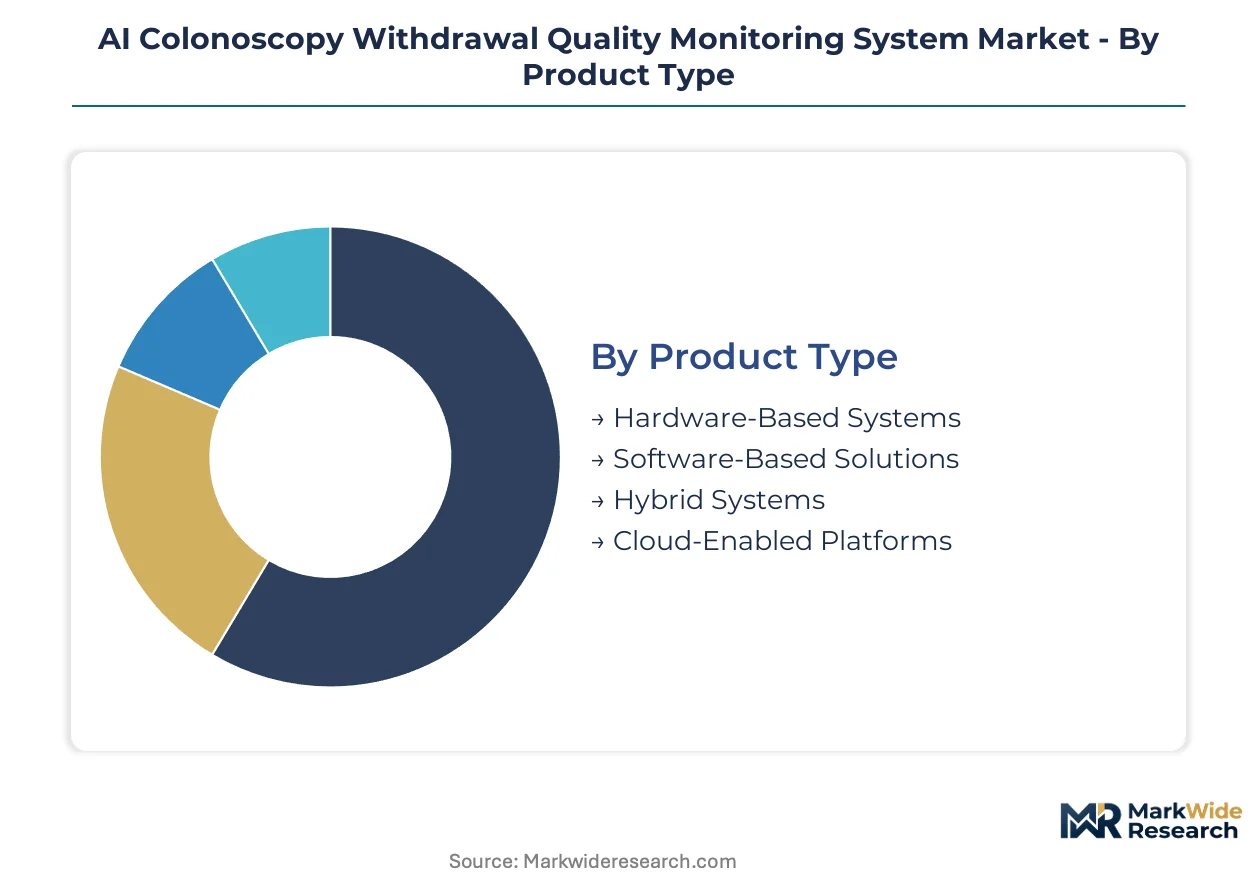
Segmentation reveals how procurement priorities diverge across healthcare delivery settings. Hospital systems prioritize interoperability, while ambulatory surgery centers favor turnkey installations with minimal IT overhead.
Product Type:
Hardware-based systems face substitution pressure from software-only alternatives as hospitals seek to leverage existing endoscope fleets.
- Hardware-Based Systems:Integrated camera-processor units with embedded inference engines deliver sub-100ms latency for real-time polyp annotation. Demand concentrates in ambulatory surgery centers across Texas and Florida where network reliability cannot be guaranteed.
- Software-Based Solutions:Platform-agnostic algorithms deployed on hospital servers or virtualized environments. German hospital networks are prioritizing these for seamless PACS integration and lower capital expenditure profiles.
- Hybrid Systems:Modular architectures combining on-device preprocessing with cloud-based model refinement.
- Cloud-Enabled Platforms:Centralized inference with automatic algorithm updates and multi-site quality dashboards.
Hardware-based systems retain volume leadership; cloud-enabled platforms hold the steepest expansion curve.
Deployment:
Cost tier differentiation separates enterprise hospital deployments from resource-constrained outpatient facilities.
- Cloud-Based:HIPAA-compliant multi-tenant architectures eliminate on-premise server investments. Mid-sized US hospital networks are adopting these to centralize quality analytics across dispersed gastroenterology sites without dedicated IT infrastructure.
- Edge Computing:On-device inference eliminates network dependency during procedures. Japanese clinics in bandwidth-constrained rural prefectures are deploying these variants to maintain real-time performance without fiber connectivity.
- On-Premise:Air-gapped installations for institutions with restrictive data governance policies.
- Hybrid Deployment:Sensitive preprocessing at the edge with aggregated analytics in cloud environments.
Cloud-based deployments dominate new installations; edge computing is gaining share fastest in rural penetration strategies.
Application:
Application maturity correlates with reimbursement code availability and clinical guideline endorsement.
- Quality Assurance Monitoring:Automated withdrawal time measurement and mucosal inspection completeness scoring against the 6-minute benchmark. US hospital outpatient departments are embedding these metrics into physician credentialing cycles as Medicare quality reporting requirements tighten.
- Polyp Detection and Classification:Real-time computer vision for adenomatous tissue identification with size and morphology annotation. Japanese screening programs are mandating these capabilities for program accreditation, driving procurement in Tokyo and Osaka metropolitan areas.
- Colorectal Cancer Screening:Population-scale workflow optimization for high-throughput screening colonoscopy.
- Therapeutic Procedure Assistance:Polyp resection margin assessment and complication risk prediction.
Quality assurance monitoring commands the largest installed base; polyp detection is climbing the fastest as regulatory frameworks mature.
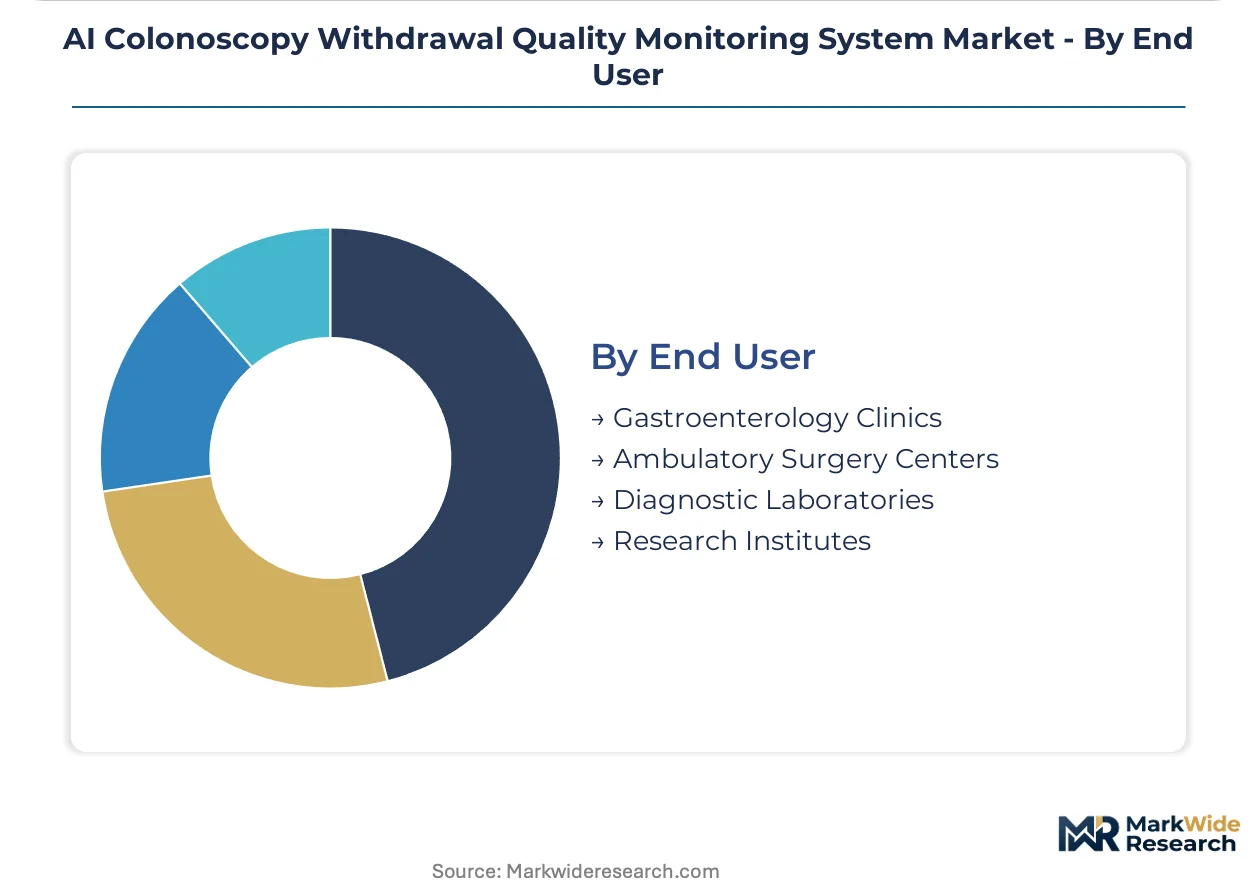
End User:
Customer type determines purchasing committee composition and sales cycle duration.
- Gastroenterology Clinics:Physician-owned practices with 3-15 proceduralists seeking standalone quality improvement tools. These facilities in Germany's statutory health insurance system are adopting cloud platforms to meet documentation mandates without hospital IT support.
- Ambulatory Surgery Centers:High-volume procedural facilities with consolidated vendor relationships and rapid capital replacement cycles. US ASCs in the Southeast are bundling AI analytics with Olympus and Medtronic scope purchases to streamline procurement.
- Diagnostic Laboratories:Pathology-integrated workflows for histopathological correlation.
- Research Institutes:Academic medical centers generating training data and validating novel algorithms.
Gastroenterology clinics represent the broadest addressable base; ambulatory surgery centers show the steepest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German hospital networks prioritize software-only platforms for PACS integration, while Japanese clinics favor edge-computing hardware for rural deployment. US health systems concentrate procurement around bundled endoscopy platform renewals.
United States
Medicare quality reporting mandates and pay-for-performance contracts drive hospital outpatient department adoption. The FDA breakthrough device pathway accelerates commercial timelines for AI-enabled tools. Texas and Florida ambulatory surgery centers deploy edge-computing variants where network reliability remains uncertain.
Germany
Statutory health insurance documentation requirements create procurement pull among physician-owned gastroenterology practices. The EU Medical Device Regulation imposes stringent clinical evidence thresholds for algorithm validation. Bavarian hospital networks prioritize cloud-enabled platforms for centralized multi-site quality dashboards.
Japan
National colorectal cancer screening program accreditation mandates automated quality monitoring capabilities. The PMDA has streamlined software-as-medical-device approval pathways, reducing evidence thresholds for algorithm updates. Tokyo and Osaka metropolitan clinics drive volume for polyp detection systems.
United Kingdom
NHS bowel cancer screening program quality assurance frameworks embed automated withdrawal time measurement into service specifications. MHRA convergence with EU MDR standards maintains rigorous clinical validation requirements. London academic medical centers generate training data for novel algorithm development.
China
Expanding colorectal cancer screening coverage in urban health insurance schemes creates addressable demand. The NMPA regulates AI diagnostic software under Class III medical device pathways with substantial clinical trial requirements. Chengdu and Wuhan host domestic manufacturers developing localized algorithm variants.
AI Colonoscopy Withdrawal Quality Monitoring System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Medtronic, Olympus, and FUJIFILM leverage endoscope manufacturing scale to bundle AI analytics with hardware replacement cycles. Strategic archetypes include integrated platform vendors, standalone algorithm developers, and regional specialists targeting price-sensitive procurement. Competitive dynamics center on EHR integration depth and regulatory approval sequencing across FDA, PMDA, and EMA jurisdictions.
Among integrated platform vendors, Medtronic and Olympus occupy positions defined by captive installed bases of endoscopy hardware. FUJIFILM represents the dual-capability archetype combining optical manufacturing with in-house algorithm development. Wuhan ENDOANGEL Medical Technology and Chengdu Wision Medical Device exemplify regional specialists leveraging domestic regulatory pathways and localized clinical validation to capture share in price-sensitive procurement environments.
| Leading Market Players |
|---|
| Medtronic |
| Olympus |
| FUJIFILM |
| PENTAX Medical |
| Wuhan ENDOANGEL Medical Technology |
| Chengdu Wision Medical Device |
| NEC Corporation |
| MAGENTIQ EYE |
| Iterative Health |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month DICOM conformance testing cycles concentrate pricing power with vendors possessing pre-certified interoperability stacks, while GPU allocation queues stretching six to nine months force hardware-integrated system manufacturers toward premium tier positioning. Contract structures favor multi-year SaaS subscriptions bundled with endoscope replacement cycles over transactional software licensing.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with three-year SaaS subscriptions bundled into IDN endoscopy platform renewals commanding premium positioning against standalone per-procedure licensing. Price differentiation rests on FDA breakthrough device designation status and native Epic or Cerner integration depth. Pricing pressure stems from physician-owned gastroenterology practices in Germany's statutory health insurance system demanding cloud-only deployments without capital expenditure. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity due to consolidated vendor relationships and rapid capital replacement cycles.
Supply Chain Analysis
Inventory buffers for NVIDIA A100 and H100 inference chips currently stretch four to six months, forcing hardware-integrated system manufacturers toward dual-sourcing strategies with AMD MI300 accelerators. Component sourcing concentrates in Taiwan for GPU fabrication, the United States for FDA-regulated software validation services, and Japan for optical sensor assemblies. Raw material dependencies include specialized CMOS image sensors, high-bandwidth memory modules, and medical-grade aluminum housings. Single-source vulnerability around NVIDIA's CUDA ecosystem creates allocation risk during semiconductor demand surges. Distribution runs through integrated endoscopy equipment distributors and direct hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as Medicare quality reporting mandates and Japanese screening program accreditation requirements create divergent procurement specifications across geographies. Demand-side specialization rewards vendors with jurisdiction-specific regulatory expertise over generalized platform approaches.
For Market Incumbents: Secure EHR integration depth through native Epic and Cerner workflow embedding before standalone algorithm developers achieve hospital system penetration. Defend against software-only entrants by bundling AI analytics with captive endoscope installed base renewal cycles. Prioritize PMDA approval sequencing to exploit Japan's streamlined software-as-medical-device pathway ahead of EU MDR clinical validation burdens. For New Entrants and Emerging Players: Anchor in Federally Qualified Health Centers across the United States rural health network, where telemedicine-integrated quality monitoring demand outstrips incumbent coverage. Target edge-computing deployments in bandwidth-constrained Japanese prefectures where Olympus and FUJIFILM cloud-centric architectures face latency limitations. Pursue pay-for-performance pilot partnerships with Japanese commercial insurers as the fastest reimbursement validation pathway. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA breakthrough device pathway acceleration and PMDA streamlined approvals compress commercialization timelines for algorithm developers against EU MDR burdened competitors. Acquisition targets should demonstrate multi-jurisdiction approval sequencing capability and existing GPO or IDN purchasing committee relationships. Monitor Japanese screening program accreditation mandate expansion as the signal indicating inflection toward mandatory automated quality monitoring procurement.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated regulatory timelines compress commercialization cycles for AI-enabled endoscopy tools. |
| Hospital System Partnership | Native Epic and Cerner integration displaces standalone quality reporting tools in IDN procurement. |
| Software Companion Development | Cloud-enabled platforms enable real-time quality analytics without on-premise hardware investments. |
| Reimbursement Strategy | Pay-for-performance contracts in Japan tie physician compensation to automated inspection completeness scores. |
| CE Marking Pathway | EU MDR clinical evidence thresholds extend approval timelines for algorithm developers seeking European access. |
Research Methodology
A standing panel of gastroenterology department heads, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement code updates, and hospital procurement database extracts. Bottom-up modeling of installed base expansion and top-down triangulation against screening program volume mandates ensured cross-verification of demand estimates.
Consistency checks validated volume and value outputs against external benchmarks including endoscope manufacturer shipment disclosures, cloud infrastructure capex reports from HIPAA-compliant hosting providers, and academic medical center AI deployment surveys. Segmentation modeling spanned product type, deployment architecture, application maturity, and end-user facility class across the projection horizon. CAGRs derived from procedure volume growth rates, reimbursement code expansion schedules, and regulatory approval pipeline velocity.
Decision-makers should treat outputs as directional under assumptions of sustained Medicare quality reporting mandate enforcement and Japanese screening program accreditation continuity; material deviation in regulatory timelines or GPU supply allocation would warrant model refresh. Specific risk factors include EU MDR clinical evidence requirement inflation, gastroenterologist fellowship shortage constraints on installed base utilization, and NVIDIA chip allocation disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Focused Ultrasound System Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Indonesia Devices Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Artificial Disc Market
Medical Devices
Recanalization System Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Ultrasound Skin Tightening Devices Market