
 Mucus Clearance Devices Market | 2026-2036
Mucus Clearance Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mucus Clearance Devices Market Outlook
Single-source reliance on high-volume contract manufacturers is decoupling as device makers diversify supply footprints. Koninklijke Philips N.V. anchors European production capacity for oscillating positive expiratory pressure systems. Electromed Inc. specializes in high-frequency chest wall oscillation technology for home-based therapy. Hill-Rom Holdings, Inc. dominates hospital-installed base expansion through direct clinical sales teams.
Mucus clearance devices are mechanical or electro-mechanical systems designed to mobilize airway secretions through oscillating airflow, positive expiratory pressure, or percussive chest wall compression, typically operating at frequencies between 5 and 20 Hz and pressure thresholds calibrated to patient lung mechanics. These devices serve patients with impaired mucociliary clearance by reducing infection risk and hospitalization frequency. Vest-based high-frequency chest wall oscillation captures the largest installed base among device types, while PEP devices and flutter valves are gaining fastest in homecare due to portability and lower per-unit cost. Application demand clusters in cystic fibrosis and COPD, where bronchiectasis represents an underaddressed expansion segment with rising diagnostic detection.
FDA 510(k) premarket notification and ISO 13485 quality management systems govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for oscillating and percussive modalities entering European markets. The EPA regulates antimicrobial coatings used in device surfaces, creating compliance cost layers for manufacturers pursuing multi-regional approval. Stakeholders must monitor reimbursement code stability for home-use devices as payors recalibrate coverage for preventive respiratory management.
Market Dynamics
Homecare migration is restructuring mucus clearance device economics as reimbursement codes shift toward preventive outpatient management and patients demand portable, self-administered therapy systems.
Growth Catalysts
- COPD prevalence expansion:Aging populations in the United States and Germany are amplifying chronic respiratory disease burdens, expanding the addressable patient base for oscillating positive expiratory pressure systems.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for Class II respiratory devices accelerates commercialization timelines for oscillating and percussive clearance technologies.
- High-frequency chest wall oscillation miniaturization:Vest system portability improvements are enabling hospital-grade therapy deployment in residential settings without clinical supervision.
Market Restraints
- Medical-grade polymer cost volatility:Specialized biocompatible materials for device housings and oscillation bladders face petrochemical input price instability, compressing gross margins on mid-tier products.
- Contract manufacturer concentration in Southeast Asia:Single-region dependence for electromechanical assembly creates geopolitical exposure and quality audit complexity for device makers.
- EU MDR clinical evidence requirements:Stricter post-market surveillance and notified body capacity constraints are extending approval timelines for oscillating modalities entering European markets.
Strategic Opportunities
- Bronchiectasis underdiagnosis:Rising high-resolution CT detection rates in Japan and South Korea are revealing untreated patient populations beyond traditional cystic fibrosis targeting.
- Telehealth-integrated remote monitoring:Bluetooth-enabled adherence tracking and cloud-based lung function data transmission are creating subscription revenue layers alongside hardware sales.
- Antimicrobial surface coating differentiation:EPA-registered silver-ion or copper-alloy treatments on mouthpieces and vest linings are commanding premium positioning in infection-sensitive care settings.
Industry Challenges
- Respiratory therapist certification bottlenecks:Specialized training requirements for high-frequency chest wall oscillation prescription and fitting limit prescriber pool expansion in rural United States markets.
- ISO 13485 quality management system maintenance:Annual surveillance audits and documentation burdens for multi-site manufacturing create ongoing compliance overhead that favors larger device portfolios.
- Legacy pneumatic system integration:Hospital-installed base of compressor-driven airway clearance equipment creates upgrade friction against newer battery-powered alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mucus Clearance Devices Market |
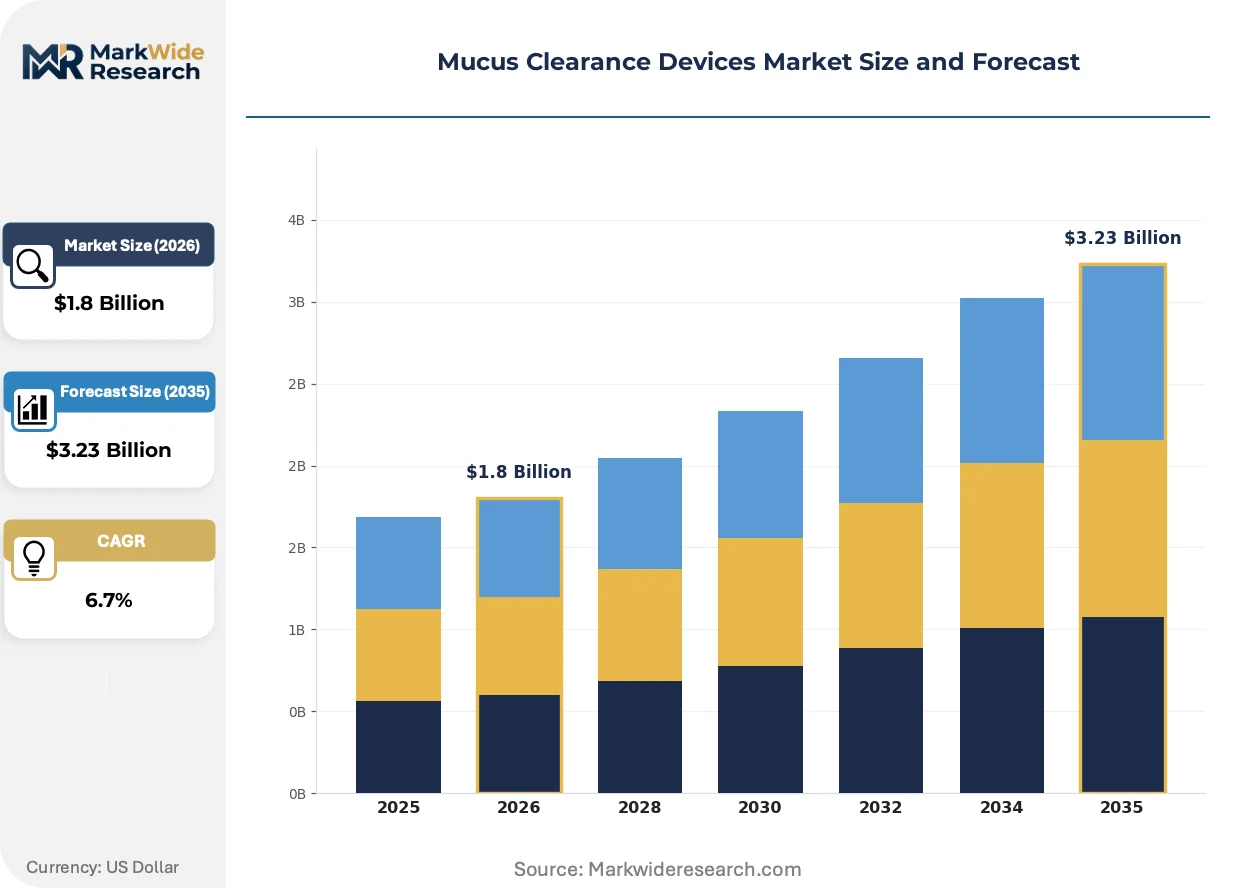
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Acapella, Flutter, Vest, PEP Device Application: Cystic Fibrosis, COPD, Bronchiectasis, Asthma End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Distribution Channel: Online Retail, Pharmacy, Distributors, Direct Sales |
| Companies Covered | Hill-Rom Holdings, Inc., Koninklijke Philips N.V., Electromed Inc., Thayer Medical, PARI GmbH, Medtronic plc, Smiths Medical, Monaghan Medical Corporation, VORTRAN Medical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mucus Clearance Devices Market Strategic Shifts
Digital connectivity and materials science are converging to transform mucus clearance from episodic clinical intervention into continuous, data-driven respiratory management.
Smart pressure sensors with real-time airflow feedback are integrating into handheld oscillating devices, enabling algorithm-adjusted vibration frequencies matched to individual lung mechanics. Homecare providers in the United States are piloting these systems for remote adherence verification. The technology is integrating spirometry-grade diagnostic capability into previously passive mechanical devices, compressing the distinction between clearance and monitoring functions.
EU Medical Device Regulation post-market clinical follow-up requirements are mandating longitudinal outcome data collection for high-frequency chest wall oscillation systems. Manufacturers must now fund registry studies or face certificate suspension. Vest-based modalities with existing European installed bases are responding by embedding cellular connectivity for automated data transmission to notified bodies.
Direct-to-patient subscription models are displacing durable medical equipment distributor channels for portable positive expiratory pressure devices. COPD patients in Germany and the Netherlands are purchasing flutter valves and oscillating systems through manufacturer-owned e-commerce platforms with video-guided onboarding. This channel shift is most visible in markets with established home oxygen therapy infrastructure where patients already self-manage respiratory equipment.
Mucus Clearance Devices Market Segmentation
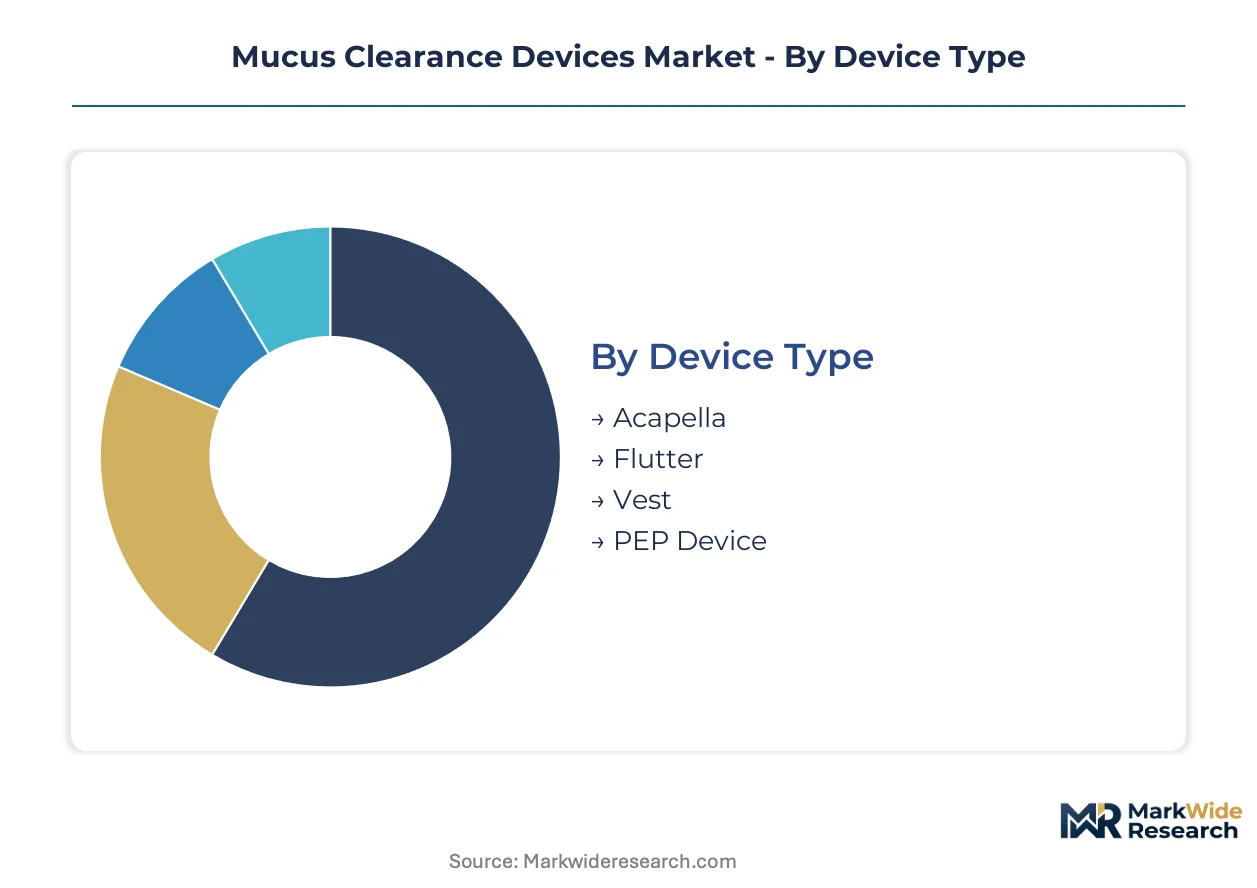
Segmentation in mucus clearance devices separates clinically intensive hospital systems from patient-managed homecare alternatives. Each category reflects divergent reimbursement pathways, technical complexity thresholds, and prescriber certification requirements that shape commercial strategy.
Device Type:
Customization spans from disposable mechanical flutter valves to programmable electromechanical vest systems with patient-specific pressure algorithms.
- Vest:High-frequency chest wall oscillation systems deliver percussive compression through inflatable garment arrays operating at 5-20 Hz. Demand concentrates in United States cystic fibrosis centers where FDA-cleared systems qualify for durable medical equipment reimbursement.
- PEP Device:Oscillating positive expiratory pressure systems combine airflow resistance with vibratory mechanics to mobilize distal airway secretions. German and Dutch home oxygen therapy patients are driving fastest adoption through direct-to-patient subscription channels.
- Acapella:Counterweighted flutter mechanism with adjustable frequency dial for personalized oscillation calibration.
- Flutter:Pipe-shaped mechanical valve using steel ball oscillation, lowest per-unit cost for emerging market access.
Leading the category by volume: Vest systems. Growing fastest: PEP devices.
Application:
Volume concentrates in diagnosed chronic conditions with established reimbursement codes, while expansion targets underdetected bronchiectasis populations.
- COPD:Chronic obstructive pulmonary disease represents the largest addressable base as aging demographics in the United States and Germany amplify disease burden. Homecare migration is restructuring device economics toward portable, self-administered PEP and oscillating systems.
- Bronchiectasis:Irreversible airway dilation with impaired mucociliary clearance is gaining diagnostic visibility through high-resolution CT deployment in Japan and South Korea. Rising detection rates are revealing untreated patient populations beyond traditional cystic fibrosis targeting.
- Cystic Fibrosis:Genetic disorder with established vest-based therapy protocols in North American and European specialist centers.
- Asthma:Reactive airway disease with intermittent clearance needs, typically addressed through lower-cost mechanical alternatives.
Primary volume driver: COPD. Steepest expansion trajectory: Bronchiectasis detection.
End User:
Site-of-care economics favor home deployment where reimbursement codes support preventive outpatient management and remote monitoring integration.
- Homecare:Residential therapy settings are capturing fastest growth as patients demand portable, self-administered systems and payors shift toward preventive respiratory management. Bluetooth-enabled adherence tracking is creating subscription revenue layers alongside hardware sales.
- Hospitals:Acute and subacute inpatient facilities maintain installed bases of compressor-driven vest systems through direct clinical sales team relationships. Legacy pneumatic equipment creates upgrade friction against battery-powered alternatives.
- Clinics:Outpatient respiratory therapy centers with certified staff for device fitting and patient training.
- Rehabilitation Centers:Post-acute facilities integrating clearance therapy into pulmonary rehabilitation protocols.
Revenue concentration: Homecare. Fastest volume gains: Hospitals converting to portable systems.
Distribution Channel:
Channel strategy bifurcates between established durable medical equipment infrastructure and emerging direct-to-patient digital platforms.
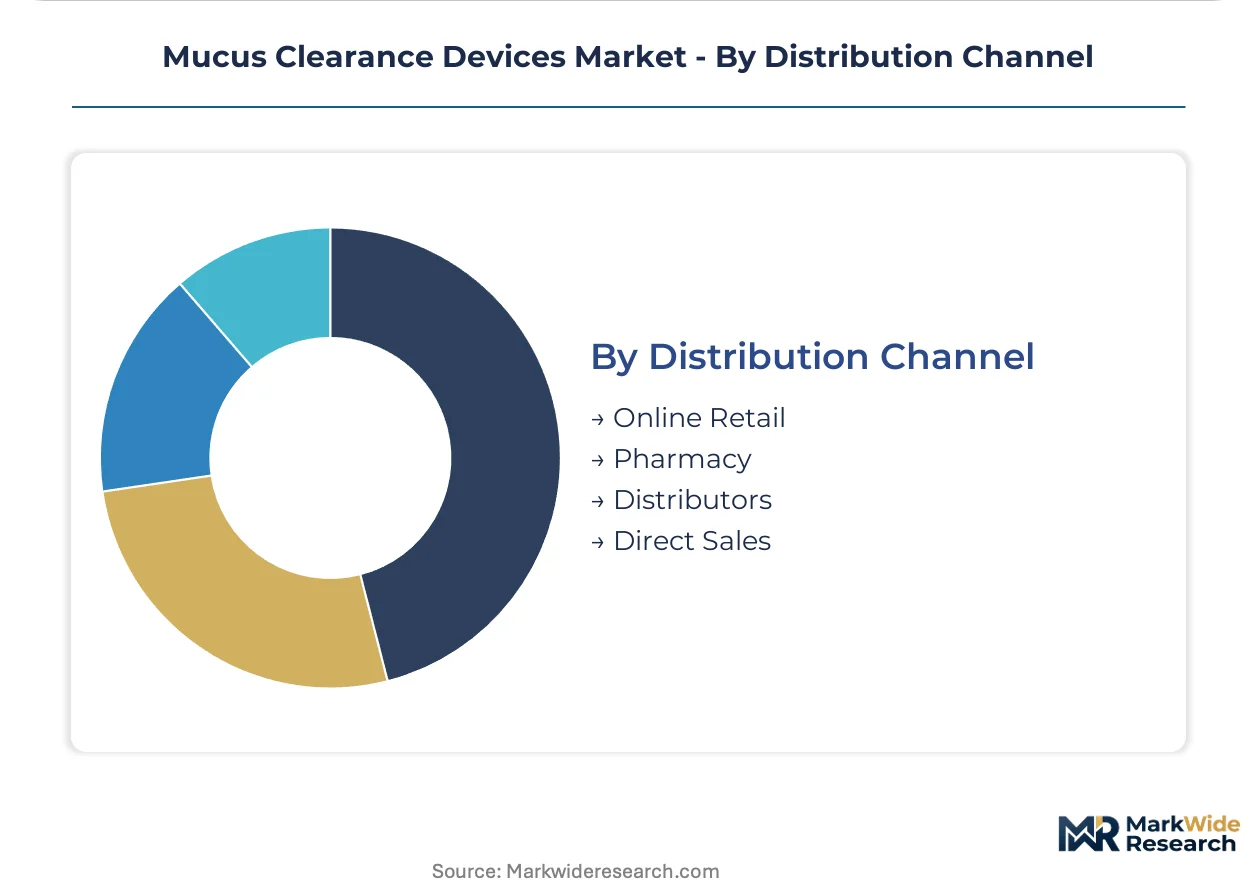
- Direct Sales:Manufacturer clinical specialist teams target hospital procurement committees and respiratory therapy departments with high-value vest system installations. Hill-Rom Holdings and Electromed deploy dedicated field organizations for institutional account management.
- Online Retail:Manufacturer-owned e-commerce platforms with video-guided onboarding are displacing traditional distributor channels for portable PEP devices. Koninklijke Philips anchors European production capacity for direct patient access.
- Pharmacy:Retail and specialty pharmacy networks for prescription-linked mechanical device dispensing.
- Distributors:Regional durable medical equipment wholesalers with logistics infrastructure for insurance-verified fulfillment.
Dominant channel by value: Direct sales. Expanding most quickly: Online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer feedstock availability in the United States Gulf Coast anchors North American device manufacturing, while German chemical clusters supply European oscillation bladder production. Asian contract manufacturing concentrates in South Korea and Japan where precision electromechanical assembly serves both domestic demand and export markets.
United States
Cystic fibrosis center density in Boston and Philadelphia drives vest system procurement, while COPD prevalence in Florida and Arizona expands homecare PEP device demand. FDA 510(k) premarket notification streamlines Class II respiratory device approvals, accelerating commercialization timelines for oscillating modalities. Minneapolis-St. Paul hosts Electromed's production facility for high-frequency chest wall oscillation systems serving the domestic installed base.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia amplify chronic respiratory disease burdens, restructuring device economics toward portable self-administered therapy. EU Medical Device Regulation imposes stricter clinical evidence requirements for oscillating modalities, extending approval timelines through notified body capacity constraints. Stuttgart's precision engineering cluster supplies electromechanical components for PEP device miniaturization programs targeting home oxygen therapy patients.
Japan
High-resolution CT deployment in Tokyo and Osaka diagnostic centers reveals underdetected bronchiectasis populations beyond traditional cystic fibrosis targeting. PMDA marketing authorization requirements govern device commercialization, with post-market surveillance mandates for high-frequency systems. Osaka's medical device manufacturing corridor concentrates oscillating positive expiratory pressure production for domestic and Asia-Pacific export markets.
South Korea
Rising bronchiectasis detection rates in Seoul and Busan create expansion opportunities for vest-based therapy protocols previously concentrated in cystic fibrosis. MFDS medical device registration requires quality management system certification aligned with ISO 13485 standards. Songdo's biocluster hosts contract manufacturing facilities serving global device makers seeking electromechanical assembly diversification beyond Southeast Asia concentration.
United Kingdom
NHS respiratory therapy procurement in London and Manchester favors homecare migration for preventive outpatient management of COPD populations. MHRA device regulation maintains alignment with EU MDR requirements post-Brexit, preserving clinical evidence standards for oscillating modalities. Cambridge's medtech corridor develops Bluetooth-enabled adherence tracking systems for telehealth-integrated remote monitoring deployment.
Mucus Clearance Devices Market Competitive Environment
Global majors compete with regional champions across institutional sales channels and direct-to-patient digital platforms, producing a tiered structure where hospital-installed base dominance contrasts with homecare subscription velocity. Consolidation pressures favor larger device portfolios capable of absorbing ISO 13485 surveillance audit overhead across multi-site manufacturing. Three archetypes dominate: diversified medtech conglomerates with respiratory divisions, pure-play airway clearance specialists, and contract manufacturers with vertical integration into electromechanical assembly. Competitive moves concentrate on M&A for regulatory certificate portfolios and strategic partnerships for telehealth integration capabilities.
Within the diversified medtech tier, Koninklijke Philips N.V. and Medtronic plc occupy positions spanning hospital and homecare channels, while Hill-Rom Holdings, Inc. anchors institutional account management through dedicated clinical specialist teams. Among pure-play specialists, Electromed Inc. exemplifies the high-frequency chest wall oscillation archetype with concentrated expertise in vest-based systems. Thayer Medical and PARI GmbH represent regional champions with geographic origin embedded in their naming, sitting within the mechanical PEP device segment where portability and lower per-unit cost drive homecare penetration.
| Leading Market Players |
|---|
| Hill-Rom Holdings, Inc. |
| Koninklijke Philips N.V. |
| Electromed Inc. |
| Thayer Medical |
| PARI GmbH |
| Medtronic plc |
| Smiths Medical |
| Monaghan Medical Corporation |
| VORTRAN Medical Technology |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FDA-cleared vest systems and unregulated mechanical flutter valves creates divergent margin architectures that ripple backward into raw material sourcing and contract manufacturer selection. Premium electromechanical devices command reimbursement-linked pricing power through ISO 13485-certified supply chains, while commodity PEP devices compete on polymer cost efficiency sourced from dispersed injection molding networks.
Pricing Analysis
Warranty and service bundling separate institutional vest system sales from direct-to-patient PEP device transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, Bluetooth connectivity inclusion, and antimicrobial coating registration. Pricing pressure stems from medical-grade polymer cost volatility compressing mid-tier product margins. Hospital procurement committees demonstrate lowest price sensitivity due to durable medical equipment reimbursement codes, while uninsured COPD patients in direct-pay channels exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle institutional vest system demand through dedicated clinical sales teams, while online retail platforms serve homecare PEP device volume. Electromechanical assembly concentrates in South Korea, Japan, and Songdo's biocluster, drawing from precision polymer feedstocks in the United States Gulf Coast and German chemical clusters. Supply chain risk centers on single-region dependence for oscillation bladder manufacturing. Distribution runs through durable medical equipment wholesalers with insurance-verified fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue backward control over electromechanical component production to secure ISO 13485 audit continuity and margin defense against polymer cost volatility.
For Market Incumbents: Extend vest system subscription revenue through Bluetooth-enabled adherence tracking and cloud-based lung function data transmission. Deepen backward integration into oscillation bladder manufacturing to reduce exposure to medical-grade polymer price instability. Defend against direct-to-patient channel displacement by embedding video-guided onboarding capabilities that match emerging digital-native competitors.
For New Entrants and Emerging Players: Enter via bronchiectasis detection corridors in Japan and South Korea where high-resolution CT deployment reveals untreated populations beyond established cystic fibrosis targeting. Target portable PEP device segments in German and Dutch home oxygen therapy markets where patients already self-manage respiratory equipment. Pursue telehealth-integrated remote monitoring partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in regulatory certificate portfolios and telehealth integration capabilities that larger device makers require for EU MDR compliance and homecare channel expansion. Long-term viability favors targets with multi-site ISO 13485 certification capable of absorbing surveillance audit overhead. Watch notified body capacity constraints as the signal for approval timeline inflection and valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates oscillating device commercialization timelines in the United States. |
| CE Marking Pathway | EU MDR clinical evidence requirements demand longitudinal registry studies for vest system certificate maintenance. |
| Hospital System Partnership | Direct clinical sales team relationships secure institutional installed base expansion against portable alternatives. |
| Software Companion Development | Bluetooth-enabled adherence tracking creates subscription revenue layers alongside hardware sales in homecare. |
| Reimbursement Strategy | CMS durable medical equipment code stability determines patient out-of-pocket exposure for vest system adoption. |
Study Parameters
FDA 510(k) filings, ISO 13485 surveillance audit records, and CMS reimbursement code databases formed the secondary backbone, cross-referenced with primary interviews involving respiratory therapists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Bottom-up device shipment estimates from South Korean and Japanese contract manufacturers were triangulated against top-down COPD prevalence projections and cystic fibrosis center density mapping.
Historical trendline analysis of vest system installed base expansion and PEP device direct-to-patient subscription velocity informed growth trajectory modeling across the analysis window. Segmentation dimensions included device type, application condition, end-user site of care, and distribution channel structure. CAGRs were derived from elasticity-adjusted price-volume relationships and reimbursement code stability assumptions, with bronchiectasis detection rates and telehealth integration penetration serving as industry-specific forecast inputs.
Revisions become necessary when EU notified body capacity constraints intensify, FDA 510(k) review timelines extend, or medical-grade polymer feedstock disruptions materialize. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laser Resurfacing Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Photopheresis Products Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
China Aesthetic Devices Market