
 US Continuous Renal Replacement Therapy Market | 2026-2036
US Continuous Renal Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
US Continuous Renal Replacement Therapy Market Intelligence
Market Context
Multi-source procurement for CRRT disposables is shifting toward consolidated supply agreements with single-platform vendors. Baxter International Inc leverages its integrated fluid-delivery ecosystem to lock in long-term hospital contracts. Fresenius Medical Care sustains manufacturing scale through captive filter production in North Carolina facilities. Medtronic competes on software-integrated alarm systems that reduce nursing workload in ICU settings.
Technical Definition and Segment Structure
Continuous Renal Replacement Therapy is an extracorporeal blood purification method operating at ultrafiltration rates of 20-35 mL/kg/hour, designed to manage fluid overload and uremia in hemodynamically unstable patients who cannot tolerate conventional hemodialysis. CRRT Machines command the largest revenue share due to capital replacement cycles and software upgrade paths, while Blood Tubing Sets generate recurring revenue streams that anchor supplier profitability. Among Solution segments, Acute Kidney Injury applications dominate procedure volume, though Sepsis-driven protocols are expanding fastest as early-initiation protocols gain clinical acceptance.
Regulatory Environment
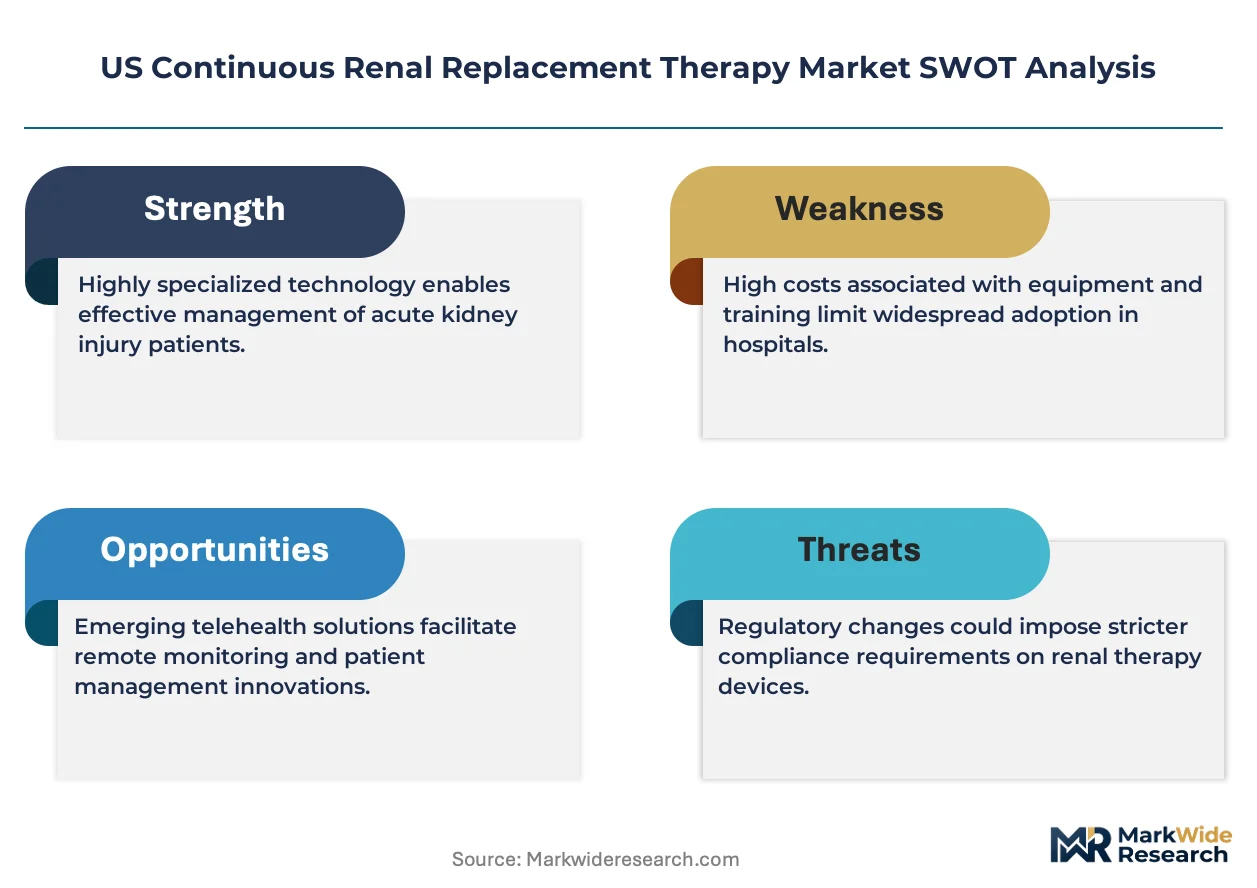
FDA Class III premarket approval requirements govern CRRT machine safety, while CMS reimbursement codes directly shape hospital adoption economics for prolonged ICU therapies. The Joint Commission's infection control standards for extracorporeal circuits influence disposable design specifications and change-out protocols. Stakeholders must monitor whether FDA digital health guidance for AI-integrated alarm systems will create new compliance thresholds for next-generation platforms.
Market Dynamics
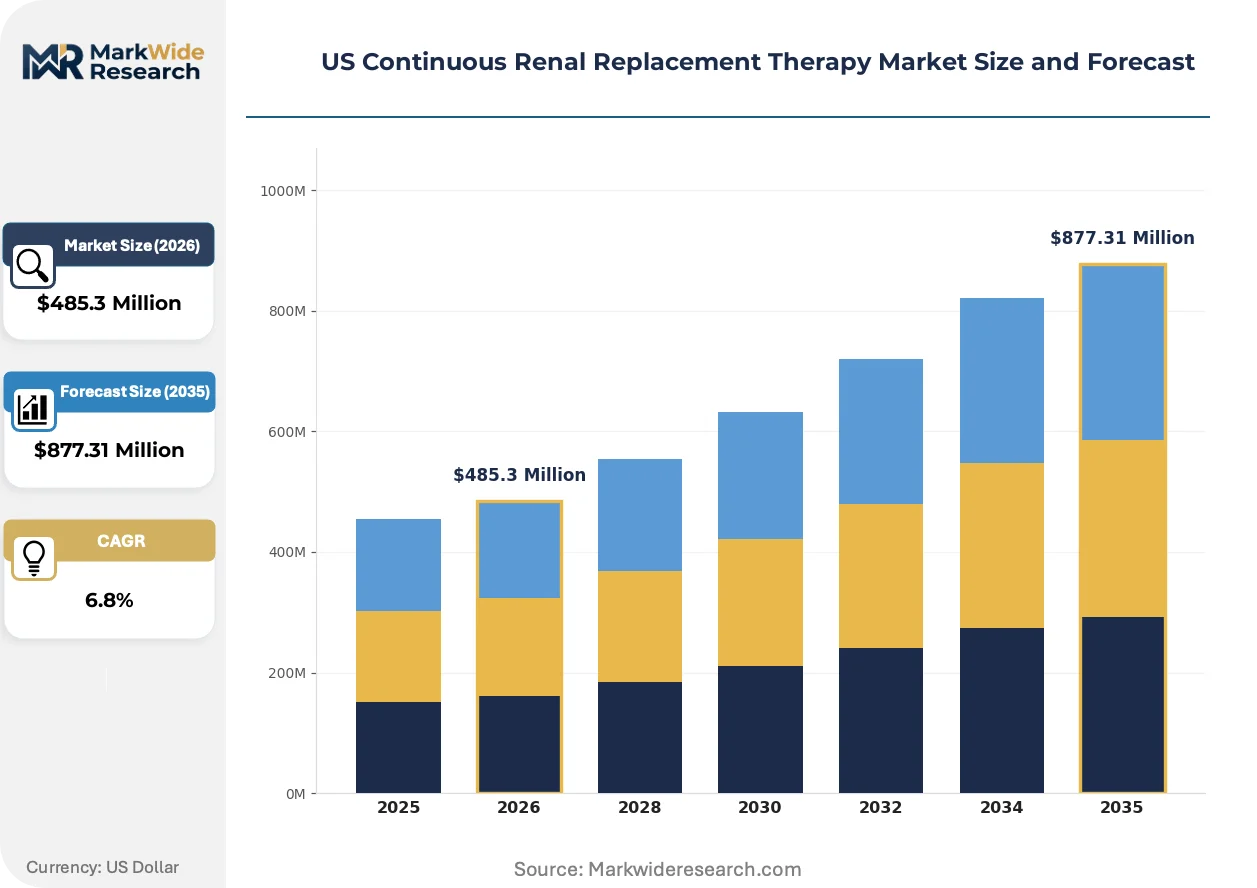
ICU consolidation across US health systems is concentrating purchasing power into fewer procurement departments, forcing CRRT vendors to restructure contract terms around total-cost-of-ownership metrics rather than per-procedure pricing.
Growth Catalysts
- CMS reimbursement expansion:New billing codes for prolonged ICU therapies reduce hospital cost barriers to CRRT initiation. Texas and California facilities report faster adoption curves where these codes apply.
- Acute kidney injury protocols:Evidence-based early-initiation guidelines from critical care societies are embedding CRRT into sepsis bundles. Level I trauma centers in Florida now mandate 24-hour CRRT availability.
- Software-integrated platforms:Machine learning alarm systems reduce nursing workload and false-positive rates. ICU directors prioritize these capabilities in capital equipment requests.
Market Restraints
- Single-source filter supply:Captive production concentrates in North Carolina facilities, creating geographic vulnerability to weather-related disruptions or capacity constraints.
- Specialized nursing requirements:CRRT operation demands certified extracorporeal therapy training that fewer than 40% of ICU nurses currently hold, limiting deployment speed.
- Capital replacement cycles:Five-to-seven-year machine lifespans delay revenue recognition for vendors and freeze hospital budgets during economic uncertainty.
Strategic Opportunities
- Remote monitoring integration:Cloud-based telemetry platforms enable centralized CRRT oversight across rural hospital networks. Texas health systems pilot these models to extend specialist coverage.
- Sepsis protocol embedding:Early-CRRT initiation in septic shock represents underpenetrated application space. Critical care guidelines increasingly recommend this timing.
- Disposable standardization:Cross-platform tubing sets could unlock multi-vendor flexibility for hospital systems currently locked into single-platform agreements.
Industry Challenges
- Training pipeline gaps:Extracorporeal certification programs produce insufficient CRRT-capable nurses to match ICU expansion rates, particularly in Florida and California markets.
- FDA digital health uncertainty:Pending guidance on AI-integrated alarm systems creates compliance timeline risk for next-generation platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Continuous Renal Replacement Therapy Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRRT Machines, Blood Tubing Sets, Filters, Dialysate End User: Hospitals, Clinics, Home Care, Dialysis Centers Solution: Acute Kidney Injury, Chronic Kidney Disease, Sepsis, Electrolyte Imbalance Technology: Convective Therapy, Sustained Low Efficiency Dialysis, Hybrid Systems, Continuous Hemofiltration |
| Companies Covered | Baxter International Inc, Fresenius Medical Care, B. Braun Melsungen AG, Medtronic, Nipro Corporation, Asahi Kasei Medical Co., Ltd., Terumo Corporation, Toray Industries Inc, ICU Medical, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Continuous Renal Replacement Therapy Market Strategic Shifts & Innovations
Machine learning, disposable chemistry, and procurement restructuring are simultaneously reshaping how CRRT platforms deliver clinical value and capture commercial margin across US hospital systems.
Real-time hemodynamic monitoring is converging with CRRT software architectures to enable automated ultrafiltration rate adjustments. ICU departments at academic medical centers in California and Texas are piloting these closed-loop systems. The technology is compressing nursing labor requirements per treatment session while reducing fluid balance errors.
FDA digital health guidance for AI-integrated medical devices is tightening validation requirements for next-generation alarm systems. Manufacturers must now submit algorithm performance data across diverse patient populations before premarket approval. Blood tubing set suppliers face secondary compliance burdens as machine software updates trigger disposable recertification requirements.
Consolidated supply agreements are displacing multi-vendor procurement strategies that dominated the 2010s. Hospital systems in Florida now negotiate single-platform contracts spanning machines, disposables, and technical service. Purchasing departments extract volume discounts while sacrificing flexibility to switch vendors mid-contract.
US Continuous Renal Replacement Therapy Market Segmentation
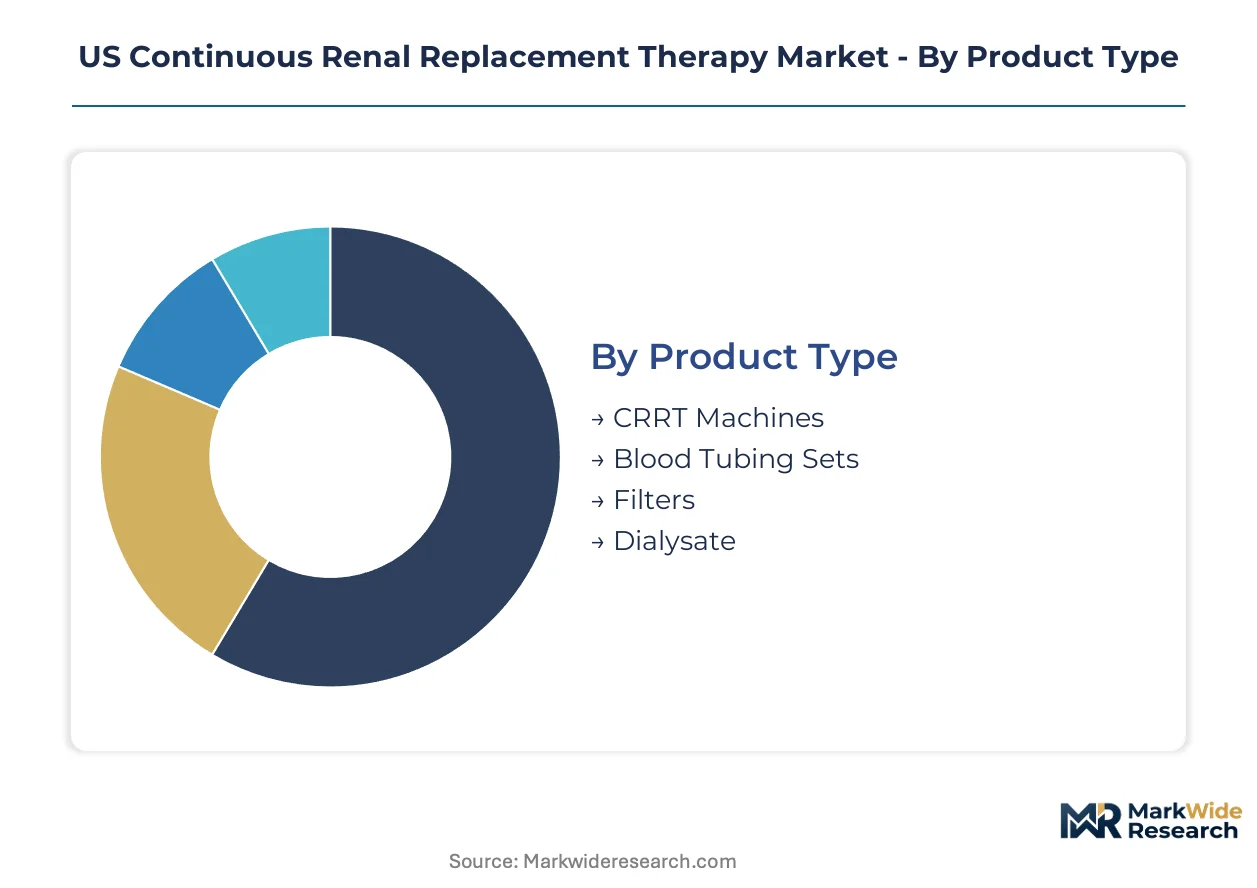
CRRT market segmentation reveals how capital equipment, consumables, and clinical applications interconnect across ICU procurement decisions. Understanding these splits exposes where vendor lock-in occurs and where multi-source flexibility remains possible.
Product Type:
Standalone capital platforms anchor initial purchasing decisions, while embedded consumable ecosystems determine lifetime supplier relationships.
- CRRT Machines:Capital platforms integrate fluid pumps, heating systems, and software architectures for 24-hour continuous operation. Texas and California Level I trauma centers drive replacement demand as five-to-seven-year lifespans expire.
- Blood Tubing Sets:Single-use extracorporeal circuits incorporate arterial and venous lines with pressure monitoring ports. Recurring revenue concentration in Florida hospital networks sustains supplier profitability across contract terms.
- Filters:Hollow-fiber membranes provide solute clearance at specified ultrafiltration rates. Captive North Carolina production creates geographic supply vulnerability.
- Dialysate:Electrolyte-balanced solutions enable diffusive clearance in hemodiafiltration modes. Standard fluid chemistry limits differentiation among suppliers.
Volume placements concentrate in CRRT Machines; the faster expansion belongs to Blood Tubing Sets.
End User:
Customer concentration in high-acuity settings shapes pricing power and service requirements across the supply base.
- Hospitals:Integrated health systems with ICU expansion programs generate the dominant procedure volume. CMS reimbursement codes for prolonged therapies reduce cost barriers at these facilities.
- Clinics:Outpatient settings occasionally extend CRRT for stabilized patients transitioning from acute care. Limited nursing certification availability constrains deployment.
- Home Care:Rare application limited to stable chronic patients with family caregiver training. Regulatory and liability concerns suppress expansion.
- Dialysis Centers:Chronic facilities occasionally absorb acute overflow during hospital capacity constraints. Equipment compatibility with existing infrastructure determines participation.
Revenue concentration sits with Hospitals; Clinics are climbing the fastest as step-down protocols proliferate.
Solution:
Clinical indication segmentation tracks how evidence-based protocols reshape procedure timing and reimbursement eligibility.
- Acute Kidney Injury:Fluid overload and uremia in hemodynamically unstable patients constitute the foundational application. Early-initiation guidelines from critical care societies embed CRRT into standard AKI bundles.
- Sepsis:Septic shock protocols increasingly mandate CRRT within hours of ICU admission. Florida trauma centers now require 24-hour availability for this indication.
- Chronic Kidney Disease:Acute-on-chronic presentations occasionally require continuous rather than intermittent therapy. Hospital readmission patterns influence utilization.
- Electrolyte Imbalance:Refractory acid-base disturbances and severe hyperkalemia drive emergency CRRT initiation. Procedure volume fluctuates with seasonal critical illness patterns.
Procedure volume dominates in Acute Kidney Injury; Sepsis applications are gaining share fastest as bundle protocols tighten.
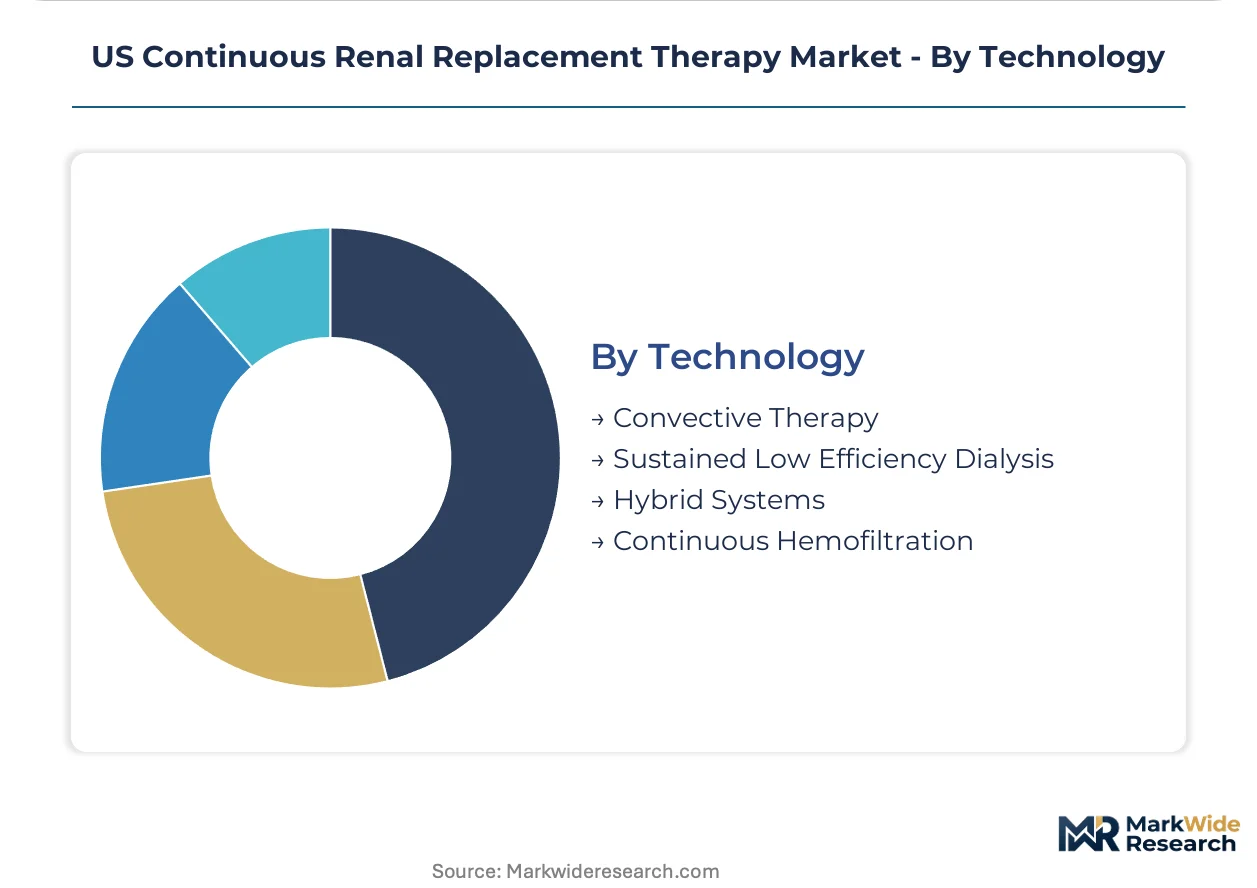
Technology:
Technical modality selection determines nursing workload, solute clearance efficiency, and machine software requirements.
- Convective Therapy:Hemofiltration and hemodiafiltration modes rely on hydrostatic pressure-driven ultrafiltration. Academic medical centers in California pilot automated rate adjustments.
- Sustained Low Efficiency Dialysis:Extended intermittent treatments bridge continuous and conventional dialysis. Lower complexity reduces certification barriers at smaller facilities.
- Hybrid Systems:Platforms switch between continuous and intermittent modes based on patient stability. Flexibility commands premium pricing in consolidated supply agreements.
- Continuous Hemofiltration:Pure convective clearance without dialysate flow simplifies circuit management. Solute removal efficiency tradeoffs limit adoption at tertiary centers.
Installed base concentrates in Convective Therapy; Hybrid Systems are expanding most quickly as procurement prioritizes flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Carolina's hollow-fiber membrane manufacturing cluster anchors domestic filter supply for the US CRRT market, with Texas, California, and Florida health networks consuming the highest procedure volumes.
Texas
Level I trauma centers in Houston and Dallas drive CRRT machine replacement demand as five-to-seven-year capital cycles expire. FDA Class III premarket approval requirements govern new platform introductions at these facilities. The Texas Medical Center cluster pilots cloud-based telemetry for rural network oversight.
California
Academic medical centers in Los Angeles and San Francisco adopt software-integrated alarm systems to reduce ICU nursing workload. CMS reimbursement codes for prolonged therapies lower hospital cost barriers in this high-wage market. The Stanford-UC San Francisco corridor tests automated ultrafiltration rate adjustments.
Florida
Sepsis bundle protocols mandate 24-hour CRRT availability at Miami and Tampa Bay trauma centers. The Joint Commission's infection control standards shape disposable change-out protocols statewide. Orlando health networks report the fastest adoption curves for early-initiation guidelines.
Southeast (Georgia/North Carolina)
Fresenius Medical Care's captive filter production in North Carolina creates geographic supply concentration for the eastern seaboard. OSHA workplace safety standards apply to manufacturing facilities in this region. Atlanta's Emory-Grady hospital system anchors procurement volume for the broader Southeast.
Northeast Corridor
New York and Boston academic centers concentrate CRRT training certification programs for ICU nursing staff. HIPAA compliance requirements shape remote monitoring platform deployments. The Massachusetts General-Brigham network influences vendor selection criteria for hybrid system flexibility.
US Continuous Renal Replacement Therapy Market Key Industry Players
Consolidated supply agreements dominate the current landscape as ICU purchasing power concentrates into fewer procurement departments. The vendor base structures around three tiers: integrated platform vendors with captive disposable ecosystems, standalone machine manufacturers competing on software capabilities, and specialized filter suppliers with manufacturing scale. Strategic archetypes include full-stack integrators pursuing total-cost-of-ownership contracts, software-focused challengers differentiating on alarm system performance, and component specialists securing long-term supply relationships. M&A activity and capacity expansion in filter production represent the dominant competitive moves.
Among integrated platform vendors, Baxter International Inc and Fresenius Medical Care exemplify the full-stack archetype through their combined machine-disposable-service offerings. Medtronic occupies a position on the software-differentiation vector, representing challengers that compete through integrated alarm systems rather than captive manufacturing. These three companies anchor the competitive structure that shapes hospital procurement decisions and contract negotiation dynamics across US health systems.
| Leading Market Players |
|---|
| Baxter International Inc |
| Fresenius Medical Care |
| B. Braun Melsungen AG |
| Medtronic |
| Nipro Corporation |
| Asahi Kasei Medical Co., Ltd. |
| Terumo Corporation |
| Toray Industries Inc |
| ICU Medical, Inc. |
| Others |
Cost & Logistics Intelligence
Captive filter production in North Carolina facilities anchors supplier pricing power by eliminating third-party margin stacking while creating geographic concentration risk that hospital procurement departments must price into total-cost-of-ownership negotiations. Baxter International and Fresenius Medical Care leverage this backward integration to bundle machines, disposables, and technical service into multi-year contracts that resist price erosion.
Pricing Analysis
Warranty and preventive service bundling separates premium-tier contracts from unbundled equipment-only transactions that leave hospitals absorbing maintenance cost volatility. Three-tier pricing structure across premium, standard, and economy levels reflects software capability gradients and disposable compatibility breadth rather than hardware performance alone. Cost compression in standard-tier machine sales is intensifying because ICU consolidation concentrates purchasing power into fewer procurement departments with standardized specifications. Price sensitivity peaks at mid-tier community hospitals expanding CRRT capability; academic medical centers exhibit lowest sensitivity due to research funding offsets and training program requirements.
Supply Chain Analysis
FDA Class III premarket approval and The Joint Commission's infection control standards gate hollow-fiber membrane supply by disqualifying uncertified producers from hospital vendor pools. Manufacturing concentrates in the United States, Germany, and Japan for finished machines; hollow-fiber membranes draw from captive North Carolina production and specialized Japanese polymer facilities. Polysulfone resin, precision pump components, and medical-grade tubing constitute critical input dependencies. Single-source vulnerability in North Carolina filter production creates weather-related disruption exposure. Distribution runs through integrated health system procurement departments and group purchasing organizations that negotiate consolidated supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over hollow-fiber membrane production determines margin capture and contract lock-in duration. Players pursue upstream manufacturing scale to displace component suppliers and defend against software-focused challengers.
For Market Incumbents: Deepen captive filter capacity in North Carolina to eliminate geographic supply vulnerability and accelerate response to weather-related disruptions. Secure long-term polysulfone resin offtake agreements before commodity volatility compresses margins. Software-integrated alarm systems from Medtronic threaten hardware commoditization; counter by embedding proprietary disposable chemistry that resists cross-platform substitution.
For New Entrants and Emerging Players: Capture remote monitoring integration white space in Texas rural hospital networks where cloud-based telemetry platforms extend specialist coverage without capital-intensive machine manufacturing. Target sepsis protocol embedding as the most penetrable application segment where early-initiation guidelines create new purchasing triggers. Pursue disposable standardization angle—cross-platform tubing sets unlock multi-vendor flexibility that consolidated supply agreements currently suppress.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated medtech rollups seeking ICU device portfolios; strategic acquirers prioritize software-alarm capabilities and disposable recurring revenue concentration. Long-term viability hinges on FDA digital health guidance resolution for AI-integrated systems. Acquisition target archetype: mid-cap filter manufacturers with North Carolina manufacturing footprint and uncommitted capacity. Watch FDA premarket approval timelines for next-generation alarm systems as inflection indicator for competitive repositioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III device clearance validates safety benchmarks before CMS reimbursement eligibility. |
| Hospital System Partnership | Texas Medical Center pilots create reference sites for cloud-based telemetry expansion. |
| Backward Integration into Membrane Production | Captive hollow-fiber manufacturing eliminates supplier margin extraction in North Carolina. |
| Software Companion Development | Machine learning alarm systems reduce nursing workload and differentiate capital platforms. |
| Reimbursement Strategy | CMS code expansion for prolonged ICU therapies accelerates hospital adoption curves. |
Research Approach
Independent corroboration across ICU nursing directors, biomedical engineering leads, hospital procurement committees, and GPO contracts managers underwrites the qualitative findings in this study. Primary fieldwork with these stakeholders combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and The Joint Commission accreditation standards. Bottom-up procedure volume estimates triangulated against top-down health system capital expenditure disclosures.
Comparable-period anchoring to historical capital replacement cycles and CMS reimbursement code implementation dates structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, end user, clinical indication, and technology modality. CAGRs derived from installed base turnover rates, ICU expansion trajectories, and protocol penetration curves. Forecast inputs incorporated nursing certification pipeline constraints and FDA digital health guidance timeline uncertainty.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA AI-integrated device validation requirements and hollow-fiber membrane supply disruptions. Forecasts reflect documented assumptions regarding ICU consolidation velocity and sepsis bundle protocol adoption rates. A model refresh is warranted upon material change in FDA digital health guidance publication or North Carolina manufacturing capacity events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Dialysis Centers Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Kidney Transplant Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Proteinuria Treatment Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Dialysis Service Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Nephrology Stents and Catheters Market