
 Global Dialysis Market | 2026-2036
Global Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dialysis Market Analysis
Portable dialysis technology is rewriting how renal care reaches patients outside traditional clinical infrastructure. Fresenius Medical Care AG & Co. KGaA leverages its manufacturing scale to dominate hemodialysis supply chains across multiple continents. DaVita Inc. anchors its position through vertical integration into kidney clinic operations and care coordination networks. Baxter International Inc. differentiates via specialization in peritoneal dialysis systems that enable patient-managed home therapy.
Dialysis encompasses the mechanical filtration of blood to substitute failed renal function, typically operating through semipermeable membranes with specified pore sizes that remove urea, creatinine, and excess electrolytes while preserving essential proteins. Hemodialysis commands the largest installed base due to decades of clinical validation and reimbursement familiarity, though peritoneal dialysis represents the fastest-expanding modality as catheter technology and remote monitoring tools reduce infection risk and clinical oversight burdens. Home care settings now attract disproportionate investment as payers and patients prioritize cost containment and quality-of-life outcomes over facility-based treatment frequency.
The FDA governs device safety and 510(k) clearance pathways for artificial kidney systems in the United States, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for European market access. Japan's PMDA maintains rigorous post-market surveillance that shapes product lifecycle obligations for manufacturers serving its aging demographic. Stakeholders must monitor how reimbursement recalibration for remote monitoring tools and portable systems alters capital deployment priorities across dialysis modalities.
Market Dynamics
Portable dialysis systems are redistributing clinical capacity from fixed facilities toward patient-controlled environments, forcing incumbents to reconfigure service revenue models around remote monitoring subscriptions rather than per-treatment reimbursement.
Growth Catalysts
- Japan's PMDA fast-track pathway:Accelerated approval timelines for home-use dialysis devices reduce manufacturer time-to-market by compressing clinical trial requirements for established safety profiles.
- Peritoneal catheter biofilm-resistant coatings:Polymer surface modifications cut peritonitis incidence rates, expanding patient eligibility for unsupervised home therapy beyond current clinical screening thresholds.
- Germany's EBM reimbursement expansion:The uniform evaluation standard now covers remote patient monitoring for dialysis, aligning physician compensation with telemedicine adoption incentives.
Market Restraints
- Concentrated dialyzer membrane supply:Three Asian polymer suppliers control polysulfone hollow-fiber precursor availability, creating single-source vulnerability for Western device manufacturers.
- EU MDR clinical evidence burdens:Stricter post-market surveillance requirements for Class III devices extend recertification cycles and inflate regulatory compliance costs disproportionately for smaller entrants.
- Water purification infrastructure gaps:Hemodialysis dependency on ultrapure water systems limits deployment in rural India and sub-Saharan Africa where reverse osmosis capacity remains underdeveloped.
Strategic Opportunities
- Brazil's ANVISA home therapy framework:Pending regulatory clarification for patient-trained peritoneal dialysis creates first-mover advantage for manufacturers establishing local training infrastructure.
- Wearable artificial kidney convergence:Integration of sorbent-based regeneration cartridges with continuous-flow microfluidics enables 24-hour ambulatory filtration without fixed plumbing connections.
- Direct-to-patient consumable distribution:Bypassing clinic procurement committees through e-commerce channels captures margin compression from group purchasing organization consolidation.
Industry Challenges
- Biomedical technician specialization shortages:Portable system maintenance demands cross-training in electronics, fluid dynamics, and software diagnostics that existing dialysis clinic workforces rarely possess.
- FDA 510(k) predicate device limitations:Novel wearable form factors lack established comparator products, triggering de novo review pathways that extend clearance timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dialysis Market |
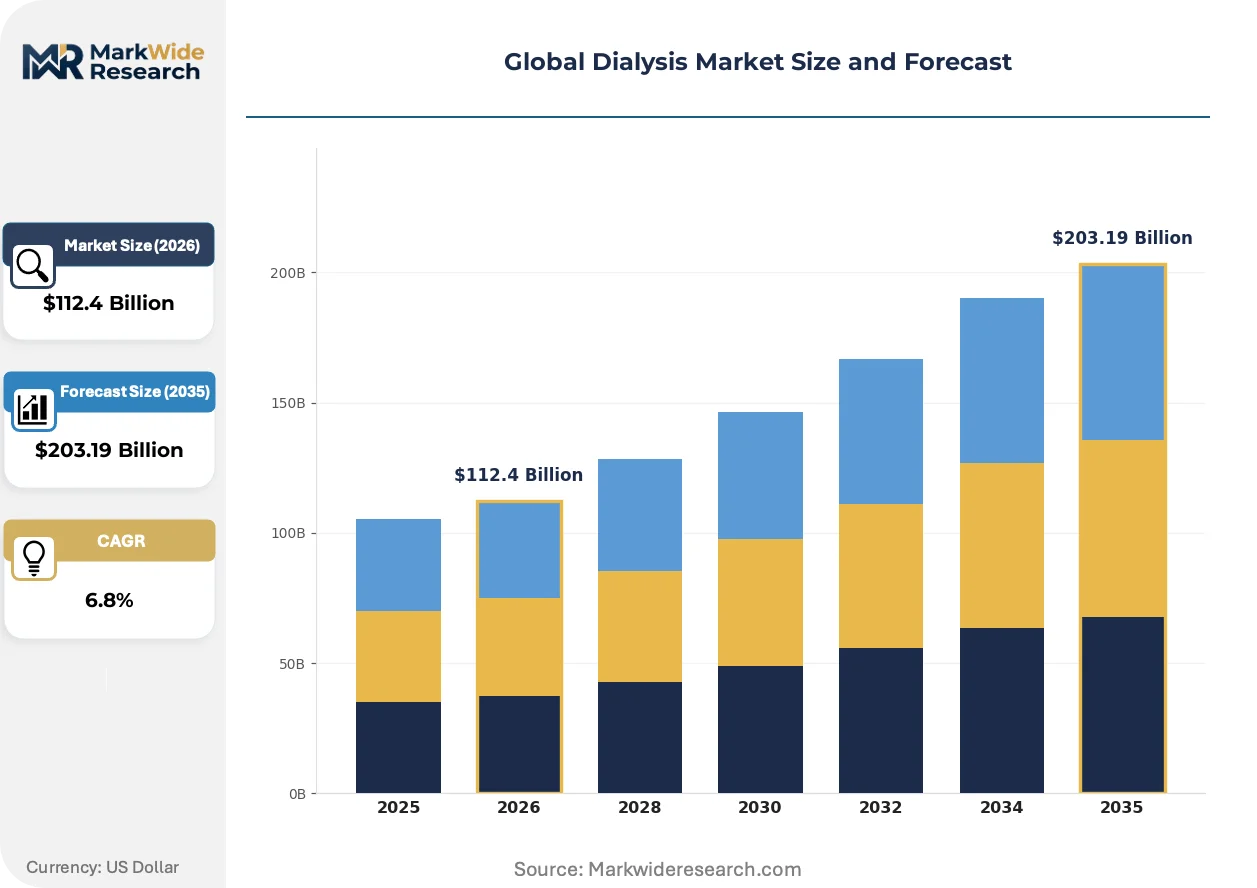
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis, Peritoneal Dialysis, Continuous Renal Replacement Therapy, Dialysis Kits End User: Hospitals, Kidney Clinics, Home Care Settings, Nursing Facilities Technology: Artificial Kidney, Portable Dialysis Machines, Chronic Care Systems, Remote Monitoring Tools Distribution Channel: Direct Sales, Online Retailing, Distributors, Wholesalers |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, DaVita Inc., Baxter International Inc., B. Braun Melsungen AG, Asahi Kasei Corporation, Nipro Corporation, Nikkiso Co., Ltd., Becton, Dickinson and Company, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dialysis Market Emerging Trajectories
Sensor miniaturization and cloud connectivity are converging to enable real-time treatment optimization outside clinical supervision, redefining the boundary between professional and patient-managed care.
Implantable blood glucose and potassium ion sensors paired with automated dialysis dosing algorithms enable closed-loop ultrafiltration adjustments. Home dialysis patients in the United States and Germany are piloting these integrated systems through insurer-sponsored remote monitoring programs. The technology is digitizing clinical decision-making, compressing the interval between physiological fluctuation and therapeutic response from hours to minutes.
The EU Medical Device Regulation's Article 10 clinical evaluation requirements now mandate post-market performance follow-up for all active implantable devices, including emerging implantable dialysis access ports. Manufacturers must maintain systematic data collection infrastructure throughout product lifecycles. Hemodialysis catheter producers serving European markets are restructuring quality management systems to accommodate this surveillance obligation.
Hospital procurement committees are unbundling device acquisition from multiyear service contracts, shifting toward per-treatment leasing arrangements with performance guarantees. German and Japanese hospital networks now specify uptime thresholds and infection rate ceilings as contract terms. This purchasing transformation concentrates vendor selection power among national group purchasing organizations while marginalizing regional distributors.
Global Dialysis Market Segmentation
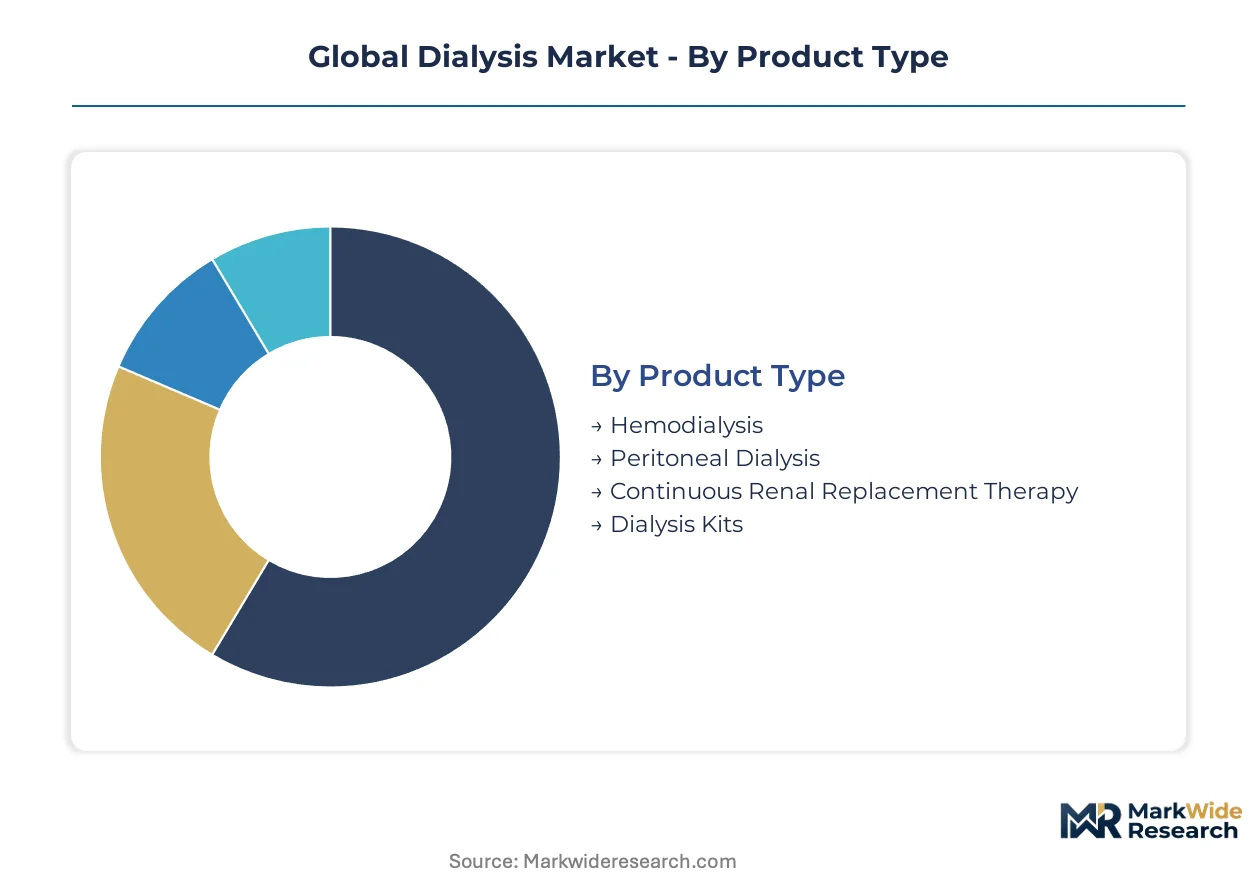
Segmentation in dialysis markets reveals how technology maturity, care setting economics, and supply chain configuration allocate revenue across distinct commercial battlegrounds. Understanding these partitions exposes where capital deployment and regulatory lobbying concentrate.
Product Type:
Cost tier stratification separates capital-intensive installed systems from consumable-dependent modalities with radically different margin profiles and replacement cycles.
- Hemodialysis:Blood filtration through external dialyzers with synthetic membrane cartridges requires clinic-based infrastructure and trained technician oversight. Demand concentrates in the United States and Germany where reimbursement frameworks sustain high-frequency treatment schedules and aging demographics expand eligible patient pools.
- Peritoneal Dialysis:Intraperitoneal catheter-based fluid exchange leverages the patient's own membrane for toxin removal, enabling self-administered home therapy without vascular access surgery. Japan's PMDA fast-track pathway accelerates device approvals for home-use configurations, compressing manufacturer time-to-market.
- Continuous Renal Replacement Therapy:Slow, continuous filtration for hemodynamically unstable ICU patients replaces intermittent batch processing.
- Dialysis Kits:Pre-packaged consumable bundles streamline inventory management for high-volume treatment centers.
Hemodialysis holds installed capacity. Peritoneal Dialysis is rotating up the share rankings.
End User:
Application setting determines capital intensity, regulatory jurisdiction, and reimbursement negotiation leverage for device manufacturers.
- Hospitals:Acute dialysis services for emergency renal failure and surgical complications require rapid-response capability and 24-hour staffing. German hospital networks now specify uptime thresholds and infection rate ceilings as contract terms, concentrating vendor selection power among national group purchasing organizations.
- Kidney Clinics:Dedicated outpatient facilities optimize throughput for stable chronic patients through scheduled treatment slots and standardized protocols. DaVita Inc. anchors its position through clinic operations and care coordination networks across multiple states.
- Home Care Settings:Patient-managed therapy eliminates facility overhead and transportation burden for mobile-capable individuals.
- Nursing Facilities:Skilled nursing environments serve patients with functional limitations preventing independent self-care.
Kidney Clinics hold installed capacity. Home Care Settings are rotating up the share rankings.
Technology:
Volume scalability differentiates between established platforms with manufacturing scale and emerging modalities requiring clinical evidence accumulation.
- Artificial Kidney:Implantable or wearable filtration devices with sorbent-based regeneration cartridges enable continuous ambulatory treatment without fixed plumbing connections. The FDA's 510(k) pathway faces predicate device limitations for novel wearable form factors, triggering de novo review timelines extending 18-24 months.
- Portable Dialysis Machines:Compact, transportable systems with battery power and reduced water requirements redistribute clinical capacity toward patient-controlled environments. Fresenius Medical Care AG leverages manufacturing scale to dominate supply chains across multiple continents.
- Chronic Care Systems:Stationary equipment optimized for repetitive long-term use in fixed installations.
- Remote Monitoring Tools:Cloud-connected sensors and automated dosing algorithms digitize clinical decision-making.
Chronic Care Systems hold installed capacity. Portable Dialysis Machines are rotating up the share rankings.
Distribution Channel:
Customer type and procurement scale determine margin capture and relationship intensity across channel configurations.
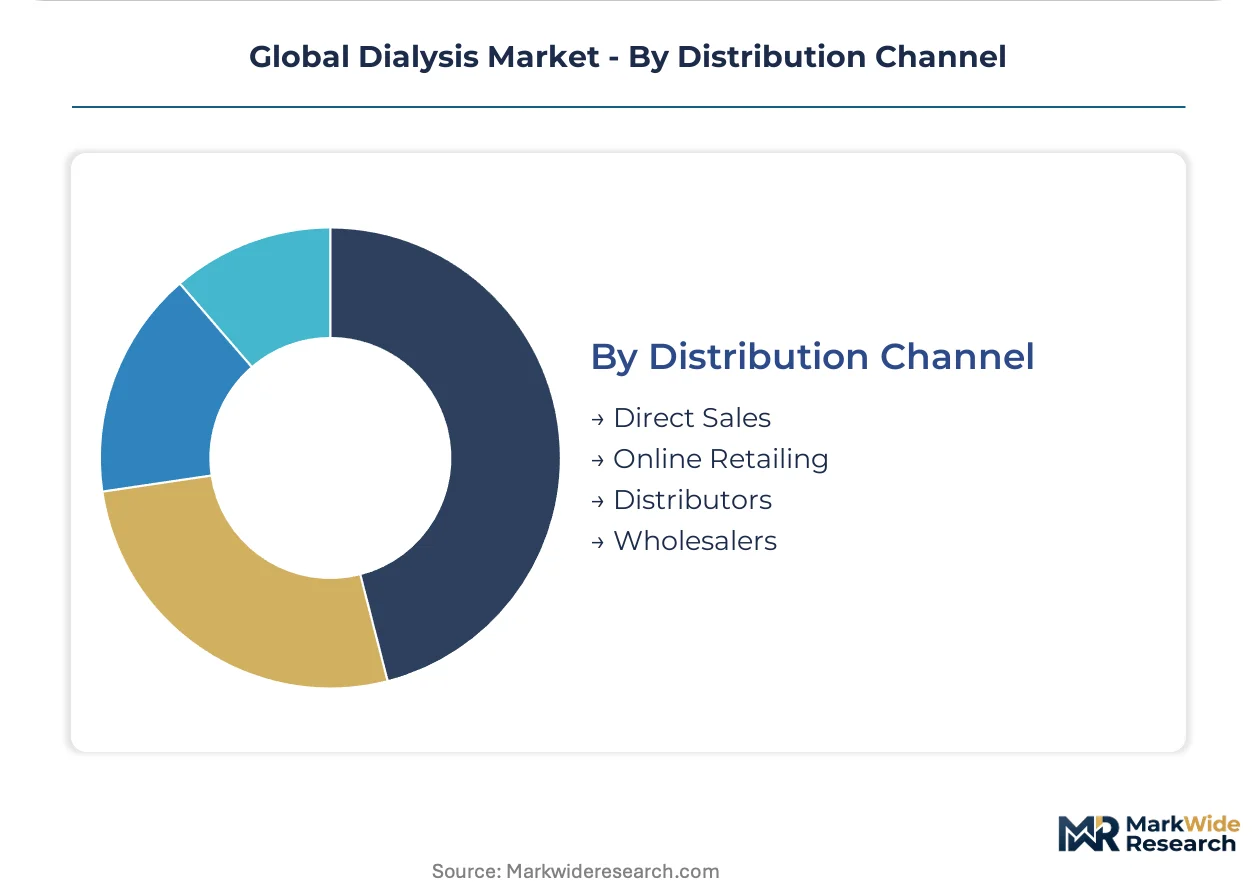
- Direct Sales:Manufacturer-to-provider relationships for high-value capital equipment with installation, training, and service bundling. Hospital procurement committees are unbundling device acquisition from multiyear service contracts, shifting toward per-treatment leasing arrangements with performance guarantees.
- Online Retailing:E-commerce platforms for consumable replenishment bypass clinic procurement committees and capture margin compression from group purchasing organization consolidation. Direct-to-patient distribution channels expand as patients assume greater cost-sharing responsibility.
- Distributors:Regional intermediaries provide inventory buffering and local technical support for mid-size accounts.
- Wholesalers:High-volume, low-touch fulfillment for standardized consumables with price-driven selection criteria.
Direct Sales holds installed capacity. Online Retailing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports dialysis equipment and consumables to the United States and Japan, forming the dominant trade-flow corridor in renal care technology. This cross-border supply chain shapes regulatory harmonization pressures and manufacturing location decisions across the triad.
United States
Medicare's End-Stage Renal Disease Prospective Payment System sustains treatment volume for aging populations with diabetes-related kidney failure. The FDA's 510(k) clearance pathway governs artificial kidney device approvals, though novel wearable form factors increasingly trigger de novo review timelines. DaVita Inc. operates concentrated clinic networks across Texas and Florida, optimizing throughput through standardized treatment protocols.
Germany
The uniform evaluation standard now reimburses remote patient monitoring for dialysis, aligning physician compensation with telemedicine adoption. EMA's Medical Device Regulation imposes stricter clinical evidence requirements for Class III device recertification. Fresenius Medical Care AG maintains manufacturing scale in Bad Homburg, supplying hemodialysis membranes across multiple continents.
Japan
PMDA's fast-track pathway accelerates home-use dialysis device approvals, compressing clinical trial requirements for established safety profiles. METI's healthcare technology export initiatives promote domestic device manufacturers in Asian markets. Nikkiso Co., Ltd. anchors production in Tokyo, serving the world's oldest population with peritoneal dialysis systems.
Brazil
ANVISA's pending regulatory clarification for patient-trained peritoneal dialysis creates first-mover opportunities for manufacturers establishing local training infrastructure. The Sistema Único de Saúde expansion targets universal chronic disease coverage. São Paulo's hospital procurement committees are unbundling device acquisition from multiyear service contracts, shifting toward per-treatment leasing arrangements.
India
CDSCO's medical device rules classify dialysis equipment under regulated imports, requiring registration for foreign manufacturers. The Pradhan Mantri National Dialysis Program subsidizes treatment for below-poverty-line patients. Maharashtra's Mumbai-Pune corridor concentrates private kidney clinic chains, though water purification infrastructure gaps limit hemodialysis deployment in rural districts.
Global Dialysis Market Vendor Landscape
On the supply side, the industry is consolidated around integrated manufacturers with captive membrane production and vertically organized clinic operators. Three strategic archetypes dominate: diversified healthcare conglomerates with dialysis divisions, pure-play renal care service networks, and specialized device manufacturers focused on single modalities. Competitive moves concentrate on backward integration into polymer supply and geographic expansion through local training infrastructure partnerships.
Among German and Japanese manufacturers, Fresenius Medical Care AG & Co. KGaA and Asahi Kasei Corporation exemplify the integrated production archetype, combining membrane manufacturing with device assembly. DaVita Inc. occupies a distinct position as a service-heavy operator anchoring clinic networks. These three entities represent the primary competitive vectors shaping procurement committee negotiations and reimbursement lobbying strategies.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| DaVita Inc. |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Asahi Kasei Corporation |
| Nipro Corporation |
| Nikkiso Co., Ltd. |
| Becton, Dickinson and Company |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Polysulfone hollow-fiber precursor production concentrates among three Asian polymer suppliers, anchoring margin capture at the membrane-manufacturing tier and forcing Western device assemblers into long-term offtake commitments or captive capacity investments.
Pricing Analysis
Current-generation hemodialysis systems, prior-generation peritoneal cycler platforms, and next-generation wearable artificial kidneys occupy distinct price bands shaped by clinical validation maturity and reimbursement coding status. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wearable devices from CE-marked portable systems and basic home-use cyclers. Pricing pressure stems from group purchasing organization consolidation in the United States and Germany, compressing margins on consumable bundles. Dialysis clinics exhibit highest price sensitivity due to fixed Medicare reimbursement rates, while hospital procurement committees prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced polymer extrusion equipment limit technology transfer to emerging manufacturing hubs, constraining membrane production capacity expansion outside established bases. Manufacturing concentrates in Germany, Japan, and the United States for finished devices, with China and South Korea supplying precision electronics and battery systems. Raw material dependencies center on medical-grade polysulfone, polyethersulfone, and specialized sterilization packaging films. Single-source vulnerability pervades the dialyzer membrane tier where precursor synthesis requires pharmaceutical-grade solvent handling capabilities. Distribution runs through national group purchasing organizations in North America and Europe, with direct-to-patient e-commerce channels gaining share for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent dialysis manufacturers face substitution pressure from bioartificial kidney implants and xenotransplantation advances that could displace mechanical filtration entirely within the clinical planning horizon.
For Market Incumbents: Insulate core hemodialysis revenue by securing captive polysulfone membrane supply through backward integration or exclusive offtake agreements with Japanese and German polymer producers. Accelerate FDA de novo pathway preparation for wearable artificial kidney submissions to preempt predicate device limitations that delay clearance timelines. Threat exposure concentrates in peritoneal dialysis where biofilm-resistant catheter coatings from specialized materials firms erode modality-specific margins. For New Entrants and Emerging Players: Home care settings in Brazil and India represent the most penetrable entry points where regulatory frameworks remain unsettled and local training infrastructure gaps favor first-mover establishment. Portable dialysis machines for rural deployment with reduced water purification requirements address infrastructure constraints that exclude conventional hemodialysis. Go-to-market execution should prioritize direct-to-patient consumable distribution via e-commerce platforms, bypassing entrenched group purchasing organization relationships that lock incumbent supply contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional dialysis clinic chains in the United States and Western Europe that require technology refresh capital and care coordination platform integration. Long-term viability hinges on positioning against bioartificial kidney commercialization timelines and xenotransplantation regulatory pathways. The signal to watch is CMS reimbursement recalibration for remote monitoring tools, which would validate home-based therapy economics and trigger consolidation premiums for clinic networks with established patient training infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Novel wearable form factors require extended review timelines that shape competitive entry sequencing. |
| CE Marking Pathway | EU MDR Article 10 surveillance obligations restructure quality management investments for European market access. |
| Hospital System Partnership | Per-treatment leasing arrangements with uptime guarantees concentrate vendor selection among national GPOs. |
| Software Companion Development | Cloud-connected dosing algorithms enable closed-loop ultrafiltration adjustments outside clinical supervision. |
| Reimbursement Strategy | Germany's EBM expansion for remote monitoring aligns physician compensation with telemedicine adoption incentives. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, dialysis clinic operations directors, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up patient population modeling triangulated with top-down manufacturer revenue aggregation across product type, end user, technology, and distribution channel segmentation dimensions.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segment-level CAGRs derived from treatment prevalence trajectories, modality shift assumptions, and reimbursement policy sensitivity analysis. Modeled dimensions encompassed hemodialysis versus peritoneal dialysis modality splits, home care versus facility-based setting migration, portable versus chronic care system technology transitions, and direct sales versus online retailing channel evolution. Forecast inputs incorporated PMDA fast-track approval velocity, EBM reimbursement expansion scope, and water purification infrastructure development timelines in priority emerging markets.
Practitioners should monitor regulatory recalibration for remote monitoring reimbursement, bioartificial kidney clinical trial readouts, and xenotransplantation regulatory pathway announcements for early signals of structural market transformation. Forecasts reflect assumptions regarding modality substitution rates, reimbursement stability, and supply chain concentration persistence. Material shifts in CMS prospective payment system restructuring, EU MDR enforcement intensity, or polysulfone precursor supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Renal Artery Embolization Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
US Dialysis Market
Nephrology
Dialysis Service Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Hemodialyzer Market
Nephrology
Global Hemodialysis Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market