
 Home Care Service Market | 2026-2036
Home Care Service Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Service Market Outlook
CMS Conditions of Participation is reorganizing the competitive landscape for Medicare-certified home health providers. Amedisys Inc. leverages its geographic density across southeastern states to sustain referral network advantages. Kindred Healthcare LLC anchors its position through hospital-at-home partnerships that control discharge planning channels. Fresenius Medical Care AG differentiates via integrated renal care protocols that extend dialysis-to-home transitions.
Home care service encompasses skilled nursing, therapeutic intervention, personal assistance, and companionship delivered in residential settings rather than institutional facilities, with service intensity measured in hourly visit increments and acuity-adjusted care plans. The primary commercial purpose centers on substituting lower-cost domiciliary care for acute readmissions and extended hospital stays. Nursing Care commands the deepest margin pools due to reimbursement premiums for skilled clinical tasks, while Telehealth within the Delivery Model segment represents the fastest structural expansion as remote patient monitoring platforms achieve parity with in-person assessments. Personal Care remains the volume anchor but faces compression from direct-hire arrangements that bypass agency markups.
CMS Conditions of Participation and state Medicaid waiver programs jointly determine market access thresholds through survey-and-certification cycles and benefit authorization protocols. HIPAA privacy frameworks shape telehealth platform architecture and data exchange protocols between caregivers and physicians. Stakeholders must monitor CMS innovation center demonstrations and state Medicaid managed care procurement timelines to anticipate reimbursement model shifts.
Market Dynamics
CMS Conditions of Participation compliance cycles are forcing Medicare-certified home health agencies to restructure staffing ratios and clinical documentation workflows, compressing operating margins while elevating quality-of-care thresholds.
Growth Catalysts
- Medicaid 1915(c) Waivers:State-level home and community-based services authorizations expand benefit eligibility for personal care and skilled nursing, unlocking demand pools in managed care territories.
- Remote Patient Monitoring Platforms:Bluetooth-enabled biometric devices and AI-powered triage algorithms reduce in-person visit frequency while maintaining reimbursement parity under CMS telehealth flexibilities.
- Hospital-at-Home Partnerships:Acute care systems in Florida, Texas, and California are embedding home health agencies into discharge planning protocols, securing referral volume through exclusive network contracts.
Market Restraints
- CMS Reimbursement Compression:The Patient-Driven Groupings Model reduces per-episode payments for home health episodes, squeezing margin pools for agencies dependent on Medicare fee-for-service revenue.
- Direct-Hire Substitution:Families in high-wage metropolitan areas increasingly bypass agency markups by hiring caregivers through digital matching platforms, eroding personal care volume.
- Clinician Supply Constraints:Registered nurse vacancy rates exceed 15% in rural service territories, limiting geographic expansion for skilled nursing-dependent providers.
Strategic Opportunities
- Behavioral Health Integration:CMS innovation center demonstrations covering depression screening and medication management in home settings create new reimbursement codes for dual-eligible populations.
- Value-Based Insurance Design:Medicare Advantage plans in Arizona and Pennsylvania are piloting capitated home care bundles that reward reduced hospitalization rates with shared savings distributions.
- Voice-First Care Coordination:Smart speaker ecosystems paired with natural language processing enable hands-free medication reminders and emergency alerts for mobility-limited patients.
Industry Challenges
- EVV Compliance Complexity:Electronic visit verification mandates in 27 states require real-time GPS and biometric validation, forcing legacy scheduling system overhauls and caregiver training investments.
- Interoperability Fragmentation:Home health agencies struggle to integrate point-of-care documentation with hospital EHR networks, delaying care transitions and risking readmission penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Service Market |
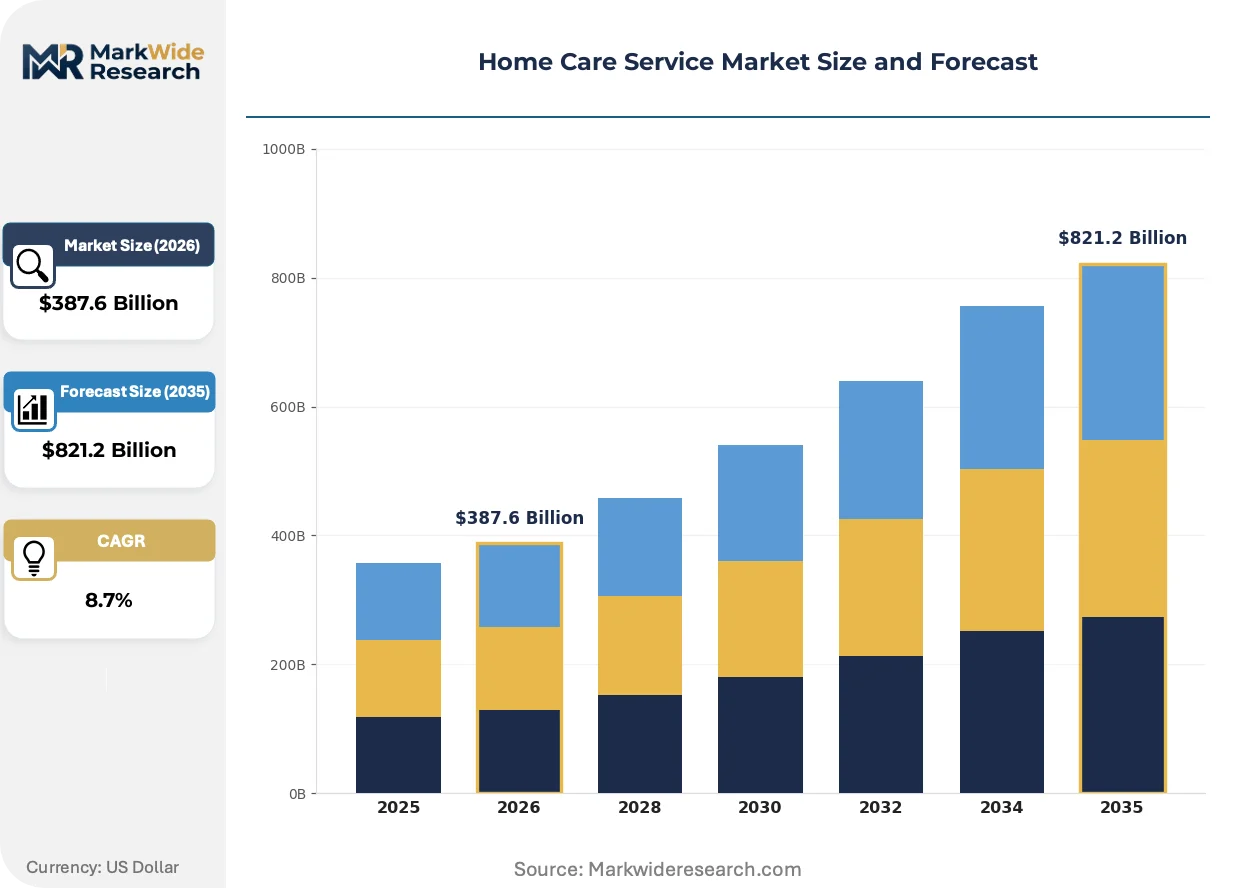
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Care, Companionship, Nursing Care, Therapy Services End User: Senior Citizens, Disabled Individuals, Patients Post-Surgery, Families Delivery Model: In-Home Services, Facility-Based Services, Telehealth, Hybrid Services Payment Model: Private Pay, Medicare, Medicaid, Long-Term Care Insurance |
| Companies Covered | Amedisys Inc., Kindred Healthcare LLC, LHC Group Inc., Fresenius Medical Care AG, Abbott, ResMed Inc., Koninklijke Philips N.V., BAYADA Home Health Care, Addus HomeCare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Service Market Strategic Shifts
Technology convergence and regulatory redesign are dismantling traditional service boundaries, enabling new care delivery archetypes that blend clinical oversight with consumer-directed autonomy.
Remote physiological monitoring is fragmenting the traditional home visit model. Continuous glucose monitors, pulse oximeters, and blood pressure cuffs transmit real-time data to centralized nursing stations, enabling early intervention before acute decompensation. Medicare Advantage plans in Ohio and Michigan are deploying these devices to high-risk cardiac patients, reducing emergency department utilization while maintaining HEDIS quality scores.
HIPAA privacy frameworks are reshaping telehealth platform architecture. The 2023 enforcement guidance on audio-only telehealth and third-party app integrations forces vendors to reconfigure data exchange protocols between caregivers, physicians, and family members. Home health agencies serving dual-eligible populations in New York and Illinois face the steepest compliance investments as they integrate behavioral health and medical records across disparate systems.
Family-directed care arrangements are displacing agency-mediated relationships in high-acuity segments. Spouses and adult children increasingly manage medication administration and wound care with virtual RN supervision, bypassing traditional skilled nursing visits. This pattern concentrates in suburban counties surrounding Atlanta, Dallas, and Phoenix where digital literacy rates support remote clinical support models.
Home Care Service Market Segmentation
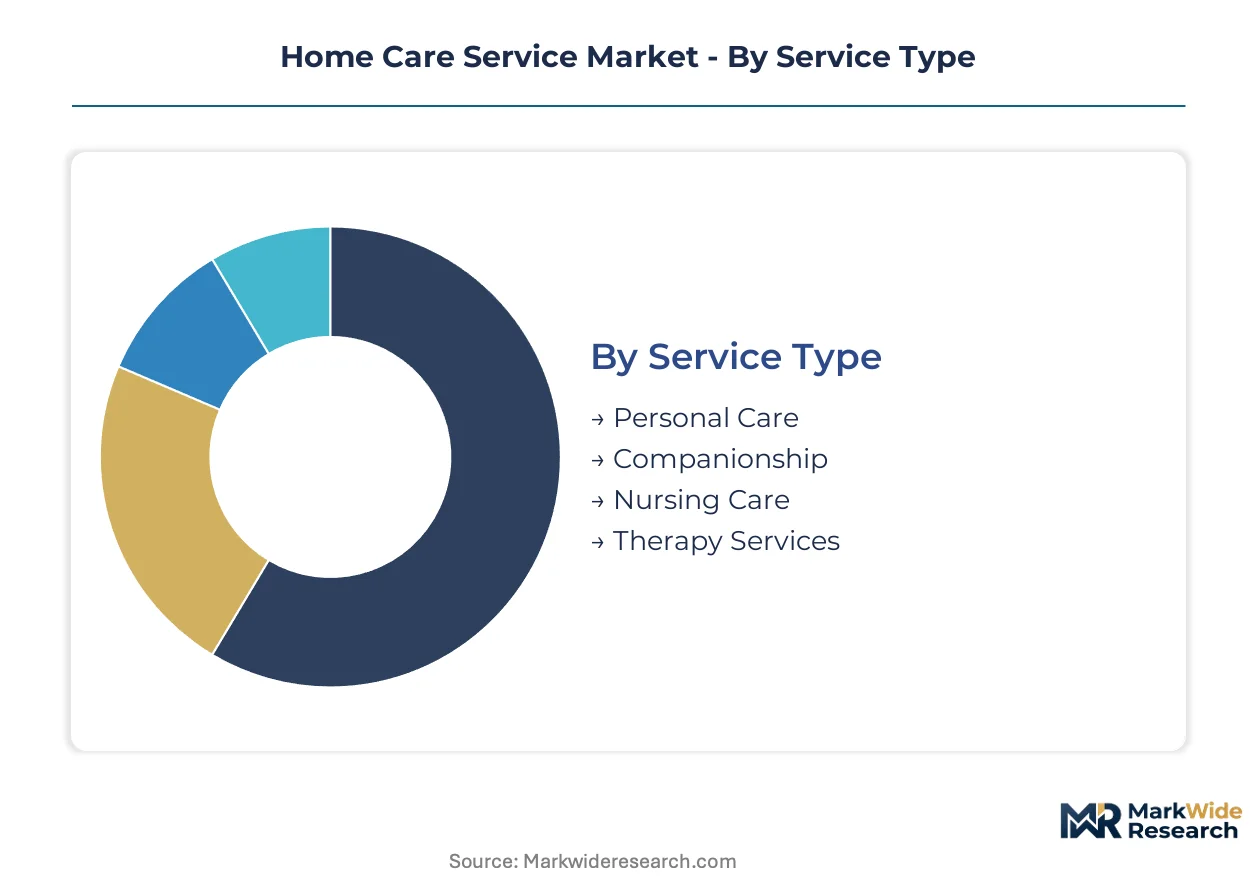
Service segmentation in home care determines reimbursement pathways, staffing requirements, and regulatory compliance obligations. Medicare-certified nursing visits command premium rates compared to personal care hours, while telehealth delivery models reshape capital intensity and geographic reach.
Service Type:
Margin pools concentrate in clinical tasks that qualify for skilled nursing reimbursement premiums under CMS fee schedules.
- Nursing Care:Licensed clinical services including wound management, medication administration, and post-acute monitoring. Demand clusters around metropolitan hospital referral networks in Florida, Texas, and California where discharge planning partnerships secure volume.
- Personal Care:Assistance with activities of daily living—bathing, dressing, meal preparation—delivered by home health aides. Families in suburban Atlanta and Dallas increasingly direct-hire to bypass agency markups, compressing traditional volume.
- Therapy Services:Physical, occupational, and speech rehabilitation delivered in residential settings.
- Companionship:Non-clinical social engagement and supervision, typically the lowest-reimbursed category with minimal regulatory oversight.
The dominant share belongs to Personal Care, while Nursing Care is closing the gap fastest through Medicare Advantage bundling.
End User:
Customer concentration varies sharply by acuity level and payment source reliability across patient populations.
- Senior Citizens:Adults aged 65 and older requiring chronic disease management, mobility assistance, and medication oversight. Dual-eligible populations in New York and Illinois drive behavioral health integration investments.
- Patients Post-Surgery:Individuals discharged from acute care needing transitional wound care, infusion therapy, and rehabilitation. Hospital-at-home programs in Ohio and Michigan prioritize this cohort for readmission reduction.
- Disabled Individuals:Working-age adults with physical or cognitive impairments requiring long-term support.
- Families:Household units arranging care for multiple members, often mixing private-pay and insurance sources.
Senior Citizens retain the largest addressable base, though Patients Post-Surgery are expanding most quickly through surgical volume growth and shortened inpatient stays.
Delivery Model:
Capital deployment and regulatory burden diverge substantially across care settings and technology integration levels.
- Telehealth:Remote patient monitoring via Bluetooth-enabled devices and video consultations. Medicare Advantage plans deploy continuous glucose monitors and pulse oximeters to cardiac patients in Michigan, reducing emergency department utilization.
- Hybrid Services:Blended models combining scheduled in-person visits with remote monitoring between encounters. Arizona and Pennsylvania pilot capitated bundles that reward reduced hospitalization rates.
- In-Home Services:Traditional face-to-face care delivery by traveling clinicians and aides.
- Facility-Based Services:Care provided in residential care communities and assisted living settings rather than private homes.
In-Home Services still accounts for the greatest visit volume, yet Telehealth is gaining share fastest as reimbursement parity solidifies and rural clinician shortages persist.
Payment Model:
Revenue stability and collection complexity vary dramatically across payer categories.
- Medicare:Federal fee-for-service and Advantage plan reimbursements for skilled nursing and therapy. The Patient-Driven Groupings Model compresses per-episode payments, forcing documentation workflow investments.
- Medicaid:State-administered programs including 1915(c) waivers for home and community-based services. Expansion decisions in managed care territories unlock demand pools for personal care.
- Private Pay:Direct household expenditure for non-covered services, concentrated in high-income metropolitan areas.
- Long-Term Care Insurance:Policy-triggered benefits for qualified care needs, subject to claims adjudication delays and benefit caps.
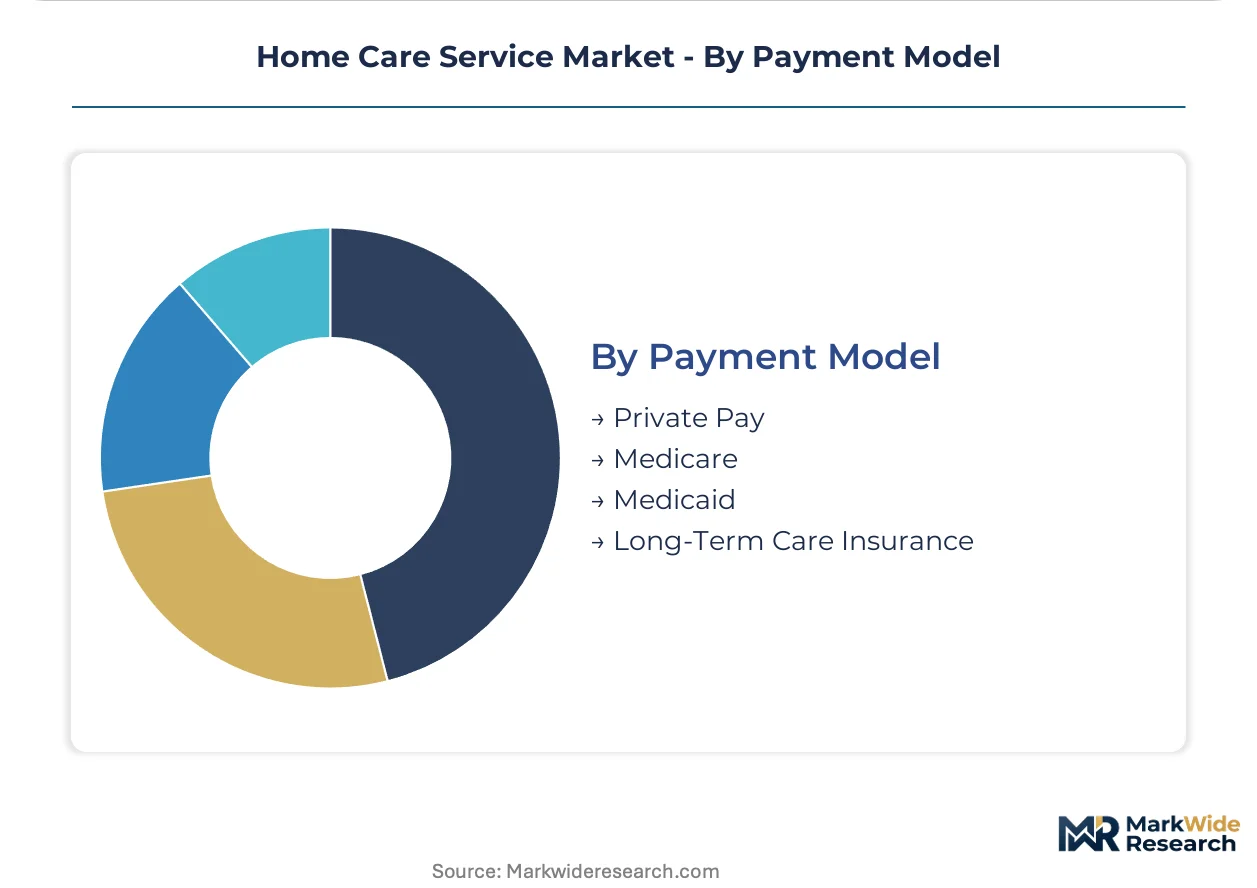
Medicare holds the dominant reimbursement position, while Medicaid is climbing fastest through state waiver expansions and managed care procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European distribution networks for medical device imports that supply home care providers across the continent. Rail corridors connecting the Rhine-Ruhr industrial cluster to Mediterranean ports enable rapid equipment replenishment for remote patient monitoring deployments.
United States
Medicare Advantage penetration in Florida and Texas drives demand for hospital-at-home transitions. CMS Conditions of Participation compliance cycles force staffing ratio restructuring across southeastern states. The Dallas-Fort Worth metroplex concentrates personal care agency density as direct-hire substitution accelerates in suburban counties.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia expand long-term care insurance claims for skilled nursing visits. The country's national healthcare regulator enforces medical device standards for Bluetooth-enabled monitoring equipment. The Rhine-Main region around Frankfurt hosts telehealth platform development clusters serving cross-border home care networks.
Japan
Metropolitan Tokyo's super-aged population sustains demand for integrated nursing and personal care services. METI guidelines on AI-powered health monitoring shape remote patient triage algorithm deployment. The Kansai region surrounding Osaka concentrates hospital-at-home pilot programs reducing acute readmission rates.
United Kingdom
NHS continuing healthcare budgets in Greater London and the Southeast prioritize domiciliary care over institutional placements. Care Quality Commission inspection regimes enforce staffing qualification standards across home health agencies. The Midlands corridor between Birmingham and Manchester hosts technology-enabled care coordination startups.
Australia
Home Care Package waiting list reductions in New South Wales and Victoria unlock personal care service volume. The country's national aged care quality regulator mandates consumer-directed care arrangements empowering family-managed support. Melbourne's health technology precinct develops voice-first care coordination platforms for mobility-limited patients.
Home Care Service Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The market structure tilts toward consolidation among Medicare-certified providers while fragmentation persists in personal care segments. Three archetypes dominate: integrated health systems controlling discharge channels, specialized home health agencies leveraging regional density, and technology vendors supplying remote monitoring infrastructure. Competitive moves center on exclusive hospital partnerships and telehealth platform acquisitions that extend service reach without proportional staff expansion.
Within the integrated care tier, Amedisys Inc. and Kindred Healthcare LLC exemplify geographic density strategies that secure referral network advantages through southeastern state concentration. Fresenius Medical Care AG occupies a specialized position bridging renal care protocols with dialysis-to-home transitions, representing the clinical specialization archetype that commands reimbursement premiums through disease-specific expertise rather than broad service portfolios.
| Leading Market Players |
|---|
| Amedisys Inc. |
| Kindred Healthcare LLC |
| LHC Group Inc. |
| Fresenius Medical Care AG |
| Abbott |
| ResMed Inc. |
| Koninklijke Philips N.V. |
| BAYADA Home Health Care |
| Addus HomeCare Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with Medicare Advantage plans lock in skilled nursing visit volumes while capping rate escalation exposure for home health agencies operating across southeastern states. These multi-year agreements tether reimbursement visibility to geographic exclusivity commitments, forcing providers to consolidate service territories around hospital referral networks.
Pricing Analysis
Certification level (Medicare-certified vs non-certified) creates the primary spread in home care service pricing, with CMS Conditions of Participation compliance adding margin premiums of 15-25% over state-licensed-only competitors. Three-tier pricing structure across premium skilled nursing, standard personal care, and economy companionship segments stratifies buyer access, with direct-hire substitution intensifying price erosion in the personal care tier. Price sensitivity concentrates among Medicaid-dependent families in managed care territories, while private-pay households in metropolitan Dallas and Atlanta absorb premium rates for continuity guarantees.
Supply Chain Analysis
Just-in-time staffing models dominate home care service logistics, with agencies maintaining minimal bench depth and relying on per-diem networks to absorb demand spikes. Geographic supply concentration clusters in the Philippines, India, and Mexico for certified nursing assistant pipelines, while Bluetooth-enabled monitoring devices draw from Shenzhen and Taipei manufacturing hubs. Single-source vulnerability in remote patient monitoring chipsets creates procurement risk, with distribution running through regional medical device distributors serving hospital-at-home networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care service markets reward defensive moats built on regulatory entrenchment, where Medicare certification cycles create switching costs that lock hospital discharge planners into established referral relationships.
For Market Incumbents: Shield market position by deepening exclusive hospital-at-home partnerships in Florida and Texas, securing discharge volume through embedded care coordination teams. Pursue backward integration into remote patient monitoring device fleets to capture equipment rental margins and reduce third-party dependency. The Patient-Driven Groupings Model reimbursement compression threatens margin pools for agencies lacking scale economies in documentation workflows. For New Entrants and Emerging Players: Lead with behavioral health integration capabilities targeting dual-eligible populations in New York and Illinois, where CMS innovation center demonstrations unlock new reimbursement codes. White-space opportunity concentrates in voice-first care coordination platforms for mobility-limited patients, with Melbourne and Phoenix suburban counties showing highest digital literacy penetration. Go-to-market execution should anchor on Medicare Advantage plan capitated bundle pilots in Arizona and Pennsylvania. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors Medicare-certified regional density plays over fragmented personal care aggregators. Long-term viability hinges on telehealth platform assets that extend geographic reach without proportional clinician hiring. Acquisition targets should demonstrate hospital system partnership depth and EVV compliance infrastructure. Watch for Medicaid 1915(c) waiver expansion announcements as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Embedded discharge planning protocols in Florida and Texas secure exclusive referral volume through care coordination teams. |
| Remote Monitoring Platform Integration | Bluetooth-enabled biometric deployments in Ohio and Michigan reduce emergency department utilization for cardiac patients. |
| Medicare Certification Investment | CMS Conditions of Participation compliance creates 15-25% reimbursement premiums over state-licensed competitors. |
| Behavioral Health Capability Buildout | Depression screening and medication management reimbursement codes target dual-eligible populations in New York. |
| EVV System Overhaul | Real-time GPS and biometric validation mandates in 27 states force legacy scheduling infrastructure replacement. |
Study Parameters
Initial hypotheses were tested against primary input from home health agency executives, hospital discharge planners, Medicare Advantage contracting officers, and state Medicaid waiver administrators, then refined through secondary validation. Primary fieldwork combined structured interviews with agency operators in Florida, Texas, and California alongside GPO contract analysis and CMS Medicare cost report databases. Secondary sources encompassed state Medicaid managed care procurement filings, hospital referral pattern databases, and telehealth platform regulatory submissions. Bottom-up visit volume modeling triangulated against top-down reimbursement flow analysis across the analysis window.
Variance decomposition separated volume drivers (aging demographics, surgical discharge trends) from price drivers (reimbursement model shifts, direct-hire substitution). Segmentation modeling captured service type (nursing, personal care, therapy, companionship), delivery model (telehealth, hybrid, in-home, facility-based), and payment source (Medicare, Medicaid, private pay, long-term care insurance). CAGRs derived from visit volume projections adjusted for clinician supply constraints and regulatory compliance cost burdens. Industry-specific inputs included CMS innovation center demonstration timelines and state-level EVV mandate implementation schedules.
Underlying assumptions cover Medicare reimbursement parity maintenance for telehealth services and Medicaid waiver expansion continuity, with deviation risk concentrated in clinician vacancy rate spikes and direct-hire platform penetration acceleration. Revision becomes warranted when Medicare Advantage capitated bundle adoption crosses threshold penetration in pilot states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
House Call Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Europe Home Care Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Home Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Virtual Companion Care Market