
 Dialysis Device and Concentrates Market | 2026-2036
Dialysis Device and Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Dialysis Device and Concentrates Market Outlook
Multi-source procurement of dialyzers and concentrates is rebalancing toward vertically integrated supply chains as manufacturers seek buffer stock resilience. Fresenius Medical Care anchors its position through captive production of both devices and fluid formulations. Baxter International leverages its peritoneal dialysis portfolio to compete in home care channels. B. Braun Melsungen specializes in regional manufacturing footprints across European and Asian markets.
Dialysis devices and concentrates encompass hemodialysis machines, peritoneal dialysis units, dialyzers, blood tubing sets, and concentrated electrolyte solutions formulated to specific ionic compositions for extracorporeal blood purification. These systems remove metabolic waste and excess fluid from patients with compromised renal function through osmotic and diffusive exchange across semipermeable membranes. Hemodialysis machines and dialyzers occupy the largest installed base, while peritoneal dialysis units represent the fastest-expanding segment driven by patient preference for at-home therapy. High-flux dialysis technology commands premium positioning due to superior middle-molecule clearance rates and reduced treatment duration.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence standards for market access. The EPA oversees effluent discharge from dialysis centers, influencing concentrate formulation chemistry and waste handling protocols. Stakeholders must monitor reimbursement rate negotiations between dialysis center operators and public health programs, as these determine capital equipment refresh cycles and patient treatment modality selection.
Market Dynamics
Home-based dialysis is compressing treatment delivery from clinical settings to residential environments, forcing device manufacturers to redesign equipment for unsupervised patient operation and remote monitoring integration.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The FDA's updated clearance framework for dialysis equipment is reducing premarket review timelines. Device developers now face abbreviated clinical evidence requirements for predicate-based submissions.
- Chronic Kidney Disease Prevalence:United States patient volumes are expanding the addressable population for both hemodialysis and peritoneal modalities. Medicare reimbursement infrastructure sustains equipment deployment velocity across dialysis center networks.
- High-Flux Membrane Technology:Advanced dialyzer materials are shortening treatment duration while improving middle-molecule clearance. Patients and providers favor reduced session times that preserve clinical efficacy.
Market Restraints
- Concentrate Supply Concentration:Electrolyte solution production clusters among captive manufacturers, exposing buyers to single-source vulnerability during regional disruptions.
- EU Medical Device Regulation Compliance Costs:MDR clinical evidence requirements and notified body capacity constraints are extending certification timelines for new dialyzer introductions.
- Peritoneal Dialysis Catheter Infection Rates:Technical limitations in connection technology continue to drive peritonitis incidence, moderating patient conversion from hemodialysis despite home therapy preference.
Strategic Opportunities
- Remote Patient Monitoring Integration:Cloud-connected dialysis machines paired with wearable sensors are enabling real-time treatment parameter adjustment. Home therapy patients gain clinical oversight without facility visits.
- India Dialysis Infrastructure Expansion:Underpenetrated rural districts present whitespace for decentralized dialysis center deployment. Government health schemes are subsidizing equipment procurement for public hospital networks.
- Portable Wearable Artificial Kidney Development:Convergence of miniaturized filtration membranes with battery-powered pumping systems is advancing toward continuous ambulatory blood purification. Early-stage clinical trials are validating hemocompatibility profiles.
Industry Challenges
- Biomedical Technician Training Shortfalls:Specialized maintenance expertise for hemodialysis machine calibration and water treatment systems remains scarce in expanding home dialysis programs.
- Legacy Equipment Interoperability:Integration complexity with existing electronic health record systems and proprietary concentrate delivery formats is delaying unified data platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialysis Device and Concentrates Market |
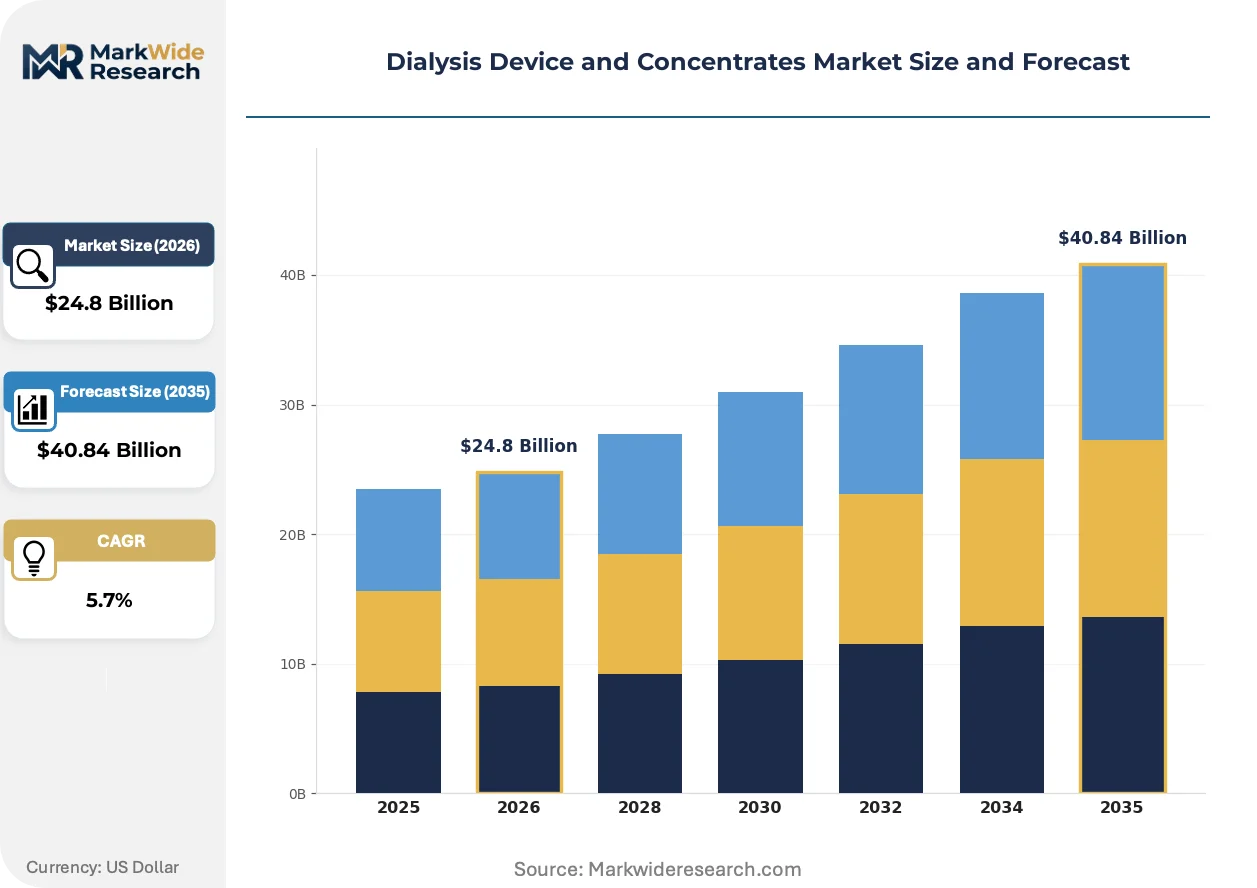
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Machines, Peritoneal Dialysis Units, Dialyzers, Blood Tubing Sets Technology: Conventional Dialysis, Continuous Ambulatory Dialysis, Online Hemodiafiltration, High-Flux Dialysis Application: Chronic Kidney Disease, Acute Kidney Injury, Renal Replacement Therapy, Pediatric Dialysis End User: Hospitals, Home Care, Dialysis Centers, Specialty Clinics |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen, Nipro Corporation, Nikkiso Co., Ltd., Asahi Kasei Medical, DaVita Healthcare Partners, Rockwell Medical, NxStage Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialysis Device and Concentrates Market Strategic Shifts
Automation and connectivity are redefining how dialysis therapy is delivered, monitored, and reimbursed, with implications spanning device design, regulatory strategy, and patient engagement models.
Closed-loop ultrafiltration control systems are automating real-time fluid removal rate adjustments based on continuous hematocrit monitoring. Dialysis center operators are adopting these systems to reduce intradialytic hypotension episodes and nursing intervention frequency. The technology is compressing staffing ratios per treatment station while maintaining safety margins.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for dialyzers and bloodlines. Manufacturers must now maintain updated safety profiles across product lifecycles. High-flux membrane categories face heightened scrutiny due to biocompatibility documentation gaps in legacy predicate devices.
Direct-to-patient concentrate delivery subscriptions are displacing traditional distributor intermediaries in home peritoneal dialysis segments. Patients now receive scheduled solution shipments synchronized with prescription adjustments. United States Medicare Advantage plans are piloting this model to reduce inventory carrying costs and improve therapy adherence metrics.
Dialysis Device and Concentrates Market Segmentation
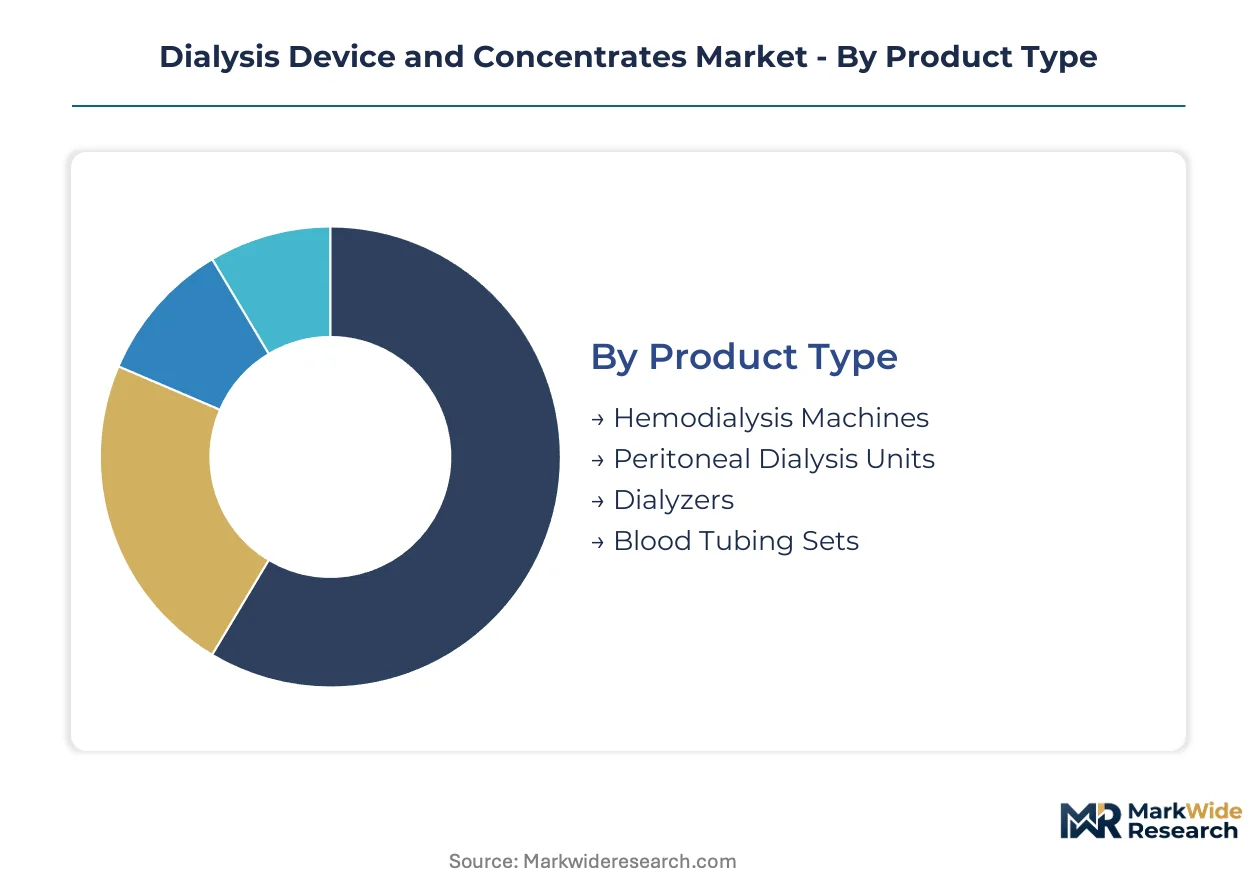
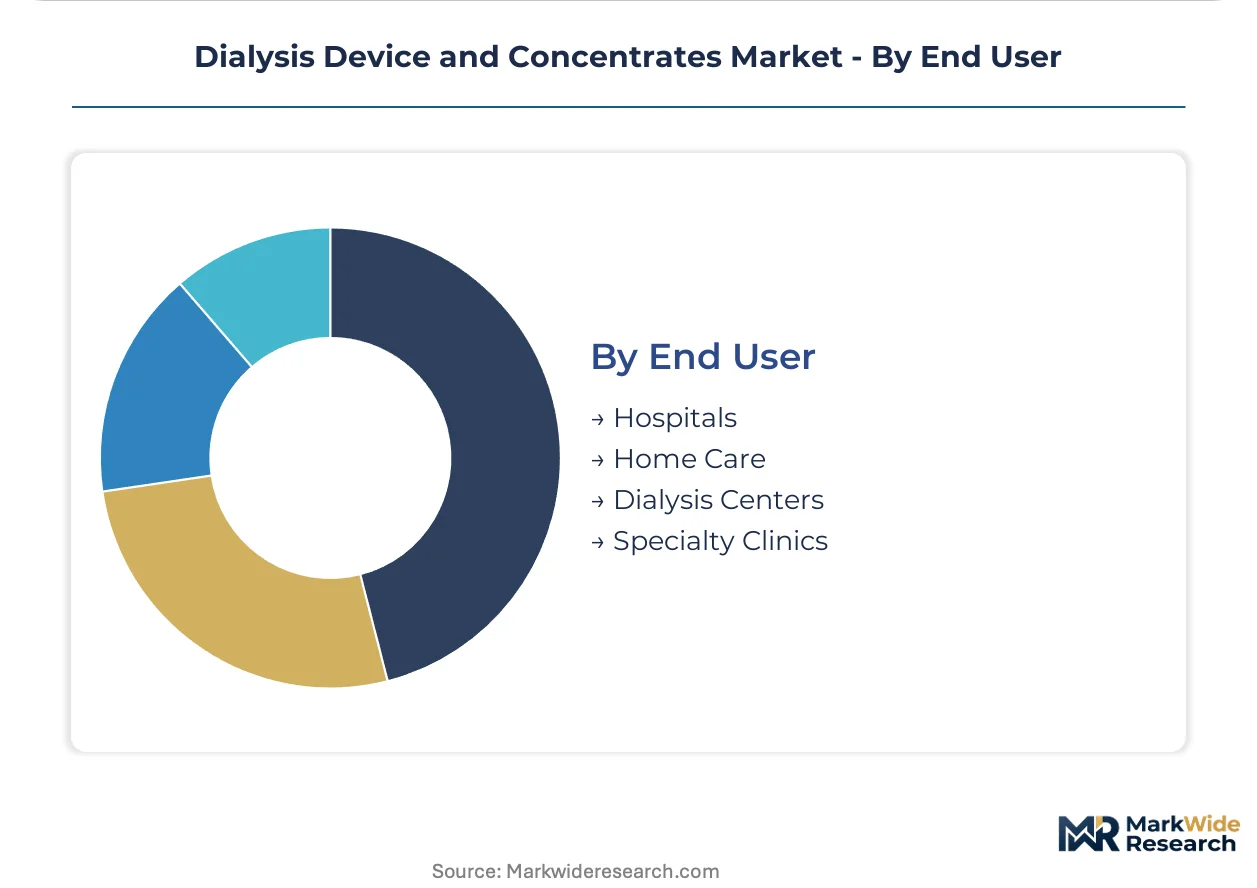
Segmentation in the Dialysis Device and Concentrates Market reveals how treatment modality, care setting, and patient acuity drive equipment specifications and procurement patterns. Manufacturers configure product portfolios around these divides to capture volume in institutional channels while building presence in home-based segments.
Product Type:
Customization intensity varies sharply across this category, from standardized concentrate formulations to patient-specific dialyzer membrane specifications.
- Hemodialysis Machines:These systems integrate blood pumps, dialysate delivery modules, and ultrafiltration controllers for extracorporeal purification. Demand concentrates in United States dialysis center networks where Medicare reimbursement sustains capital refresh cycles and multi-station deployments.
- Peritoneal Dialysis Units:Compact cycler devices automate dialysate exchange for home-based therapy. United States patient preference for residential treatment flexibility is accelerating unit placement outside clinical settings, though catheter infection risks moderate conversion velocity.
- Dialyzers:Hollow-fiber membrane cartridges perform diffusive and convective solute clearance.
- Blood Tubing Sets:Single-use extracorporeal circuits connect patients to hemodialysis machines.
Most installed capacity flows through Hemodialysis Machines. Expansion is steepest in Peritoneal Dialysis Units.
Technology:
Cost tier stratification separates premium high-flux systems from conventional equipment, with reimbursement differentials determining hospital procurement decisions.
- High-Flux Dialysis:Synthetic membrane geometries enable enhanced middle-molecule clearance and shortened treatment duration. United States providers favor reduced session times that preserve clinical outcomes while expanding daily patient throughput.
- Online Hemodiafiltration:Convective clearance mechanisms substitute ultrapure dialysate for substitution fluid. European adoption leads due to favorable reimbursement coding in Germany and France that recognizes superior toxin removal profiles.
- Conventional Dialysis:Standard diffusive clearance without convective augmentation dominates emerging market installations.
- Continuous Ambulatory Dialysis:Gravity-driven manual exchanges serve home peritoneal therapy patients without electromechanical dependency.
Volume concentration sits with Conventional Dialysis in cost-sensitive procurement environments. Technology leadership is expanding most quickly in Online Hemodiafiltration.
Application:
Patient acuity levels determine device complexity requirements, with chronic maintenance representing recurring revenue versus acute intervention episodes.
- Chronic Kidney Disease:Long-term maintenance dialysis for end-stage renal failure patients drives recurring consumable demand. United States prevalence expansion and Medicare entitlement structure sustain predictable equipment utilization across dialysis center networks.
- Acute Kidney Injury:Critical care dialysis for hemodynamically unstable patients requires continuous renal replacement modalities. ICU capacity expansion in India and Brazil is generating demand for portable acute systems.
- Renal Replacement Therapy:Encompasses both chronic and acute intervention modalities across care settings.
- Pediatric Dialysis:Specialized equipment scales for lower blood volumes and growth-adjusted clearance requirements.
Recurring revenue concentrates in Chronic Kidney Disease. Acute Kidney Injury is gaining share fastest among application segments.
End User:
Customer type shapes distribution architecture, with institutional procurement favoring capital lease structures and home care requiring direct-to-patient logistics.
- Home Care:Patients self-administer peritoneal dialysis or home hemodialysis with remote clinical oversight. United States Medicare Advantage plans are piloting concentrate subscription delivery to reduce inventory costs and improve adherence tracking.
- Dialysis Centers:Freestanding outpatient facilities operate high-throughput hemodialysis stations with centralized water treatment. United States network consolidation is standardizing equipment procurement across multi-site operators.
- Hospitals:Integrated health systems deploy acute and chronic dialysis within inpatient and outpatient departments.
- Specialty Clinics:Nephrology-focused practices offer limited dialysis services alongside consultation.
Patient volume flows predominantly through Dialysis Centers. Home Care is climbing the fastest among end user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresenius Medical Care's manufacturing complex in Schweinfurt anchors European dialyzer production capacity. United States dialysis center networks drive installed base concentration. German engineering clusters supply precision pump and membrane components to global equipment assemblers.
United States
Medicare entitlement structures sustain hemodialysis machine refresh cycles across outpatient networks. The FDA's 510(k) clearance pathway streamlines predicate-based submissions for dialyzer manufacturers. DaVita Healthcare Partners operates concentrated treatment stations across Texas and Florida metros.
Germany
Online hemodiafiltration reimbursement codes in Bavaria and Baden-Württemberg accelerate premium technology uptake. The EU Medical Device Regulation mandates systematic post-market surveillance for bloodline safety profiles. Fresenius Medical Care maintains captive concentrate formulation facilities in Schweinfurt.
Japan
Aging demographics expand end-stage renal disease patient pools in Tokyo and Osaka metropolitan corridors. PMDA clinical evidence standards shape dialyzer biocompatibility documentation requirements. Nikkiso Co., Ltd. anchors domestic equipment assembly in the Nagoya industrial zone.
India
Government health schemes subsidize hemodialysis machine procurement for public hospital networks in Maharashtra and Tamil Nadu. The Central Drugs Standard Control Organization regulates medical device import licensing and quality standards. Private dialysis center operators expand into underpenetrated districts across Karnataka and Telangana.
China
Domestic chronic kidney disease prevalence drives concentrate demand in Yangtze River Delta hospital systems. NMPA registration requirements govern dialysis equipment market access and clinical trial obligations. Local manufacturers scale membrane cartridge production in Jiangsu province manufacturing parks.
Dialysis Device and Concentrates Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue home-based therapy automation. The vendor base stratifies across integrated device-concentrate manufacturers, standalone dialyzer specialists, and dialysis service operators. Three archetypes dominate: captive supply chain operators, regional manufacturing footprint holders, and home care channel specialists. Competitive moves concentrate on vertical integration into concentrate production and remote monitoring platform development.
Among integrated German manufacturers, Fresenius Medical Care and B. Braun Melsungen exemplify captive production archetypes spanning devices and fluid formulations. Baxter International occupies a position within the home care specialist tier. These three anchors represent distinct strategic postures: dual-product manufacturing control, regional hub deployment, and peritoneal dialysis channel concentration.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen |
| Nipro Corporation |
| Nikkiso Co., Ltd. |
| Asahi Kasei Medical |
| DaVita Healthcare Partners |
| Rockwell Medical |
| NxStage Medical |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up dialysis center operators in the United States have consolidated procurement bargaining power, compressing equipment lease rates while simultaneously demanding captive concentrate supply commitments that lock in multi-year pricing floors.
Pricing Analysis
Input-cost pass-through from membrane polymers and medical-grade plastics flows into dialyzer pricing, though high-flux product tiers absorb volatility better through FDA 510(k) certification premiums. Pricing stratifies across premium high-flux membranes, standard synthetic dialyzers, and economy cellulose-based cartridges, with reimbursement differentials determining hospital procurement decisions. Cost compression in economy tiers is intensifying because of Indian and Chinese domestic manufacturing scale-up. Dialysis center networks exhibit highest price sensitivity due to Medicare reimbursement caps, while hospital systems with bundled payment contracts show lowest sensitivity.
Supply Chain Analysis
Direct-to-dialysis-center channels handle institutional demand, while direct-to-patient subscriptions serve home peritoneal therapy segments. Manufacturing concentrates in Germany, Japan, and the United States for precision pump and membrane components, with China scaling domestic dialyzer cartridge production. Raw material dependencies draw from polysulfone and polyethersulfone polymers, medical-grade PVC, and electrolyte salts. Single-source vulnerability pervades concentrated electrolyte formulation supply, where Fresenius Medical Care and Baxter International maintain captive production. Distribution runs through GPO contracts for United States hospital systems and specialized dialysis distributors for European outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through high-flux membrane premiumization and automated home therapy platforms that reduce per-treatment labor intensity.
For Market Incumbents: Extend remote monitoring platform capabilities to defend against software-enabled entrants seeking to disintermediate device manufacturers. Deepen backward integration into hollow-fiber membrane spinning to secure supply during polymer shortage cycles. Prioritize FDA 510(k) predicate expansions that accelerate clearance timelines for next-generation dialyzer geometries. For New Entrants and Emerging Players: Launch via direct-to-patient concentrate subscription models to bypass entrenched GPO contracting barriers in United States dialysis center networks. Target India's underpenetrated rural districts where government health scheme subsidies lower equipment procurement barriers. Pursue white-space in portable wearable artificial kidney development, leveraging miniaturized filtration advances validated through early-stage hemocompatibility trials. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone dialyzer specialists lacking concentrate formulation capabilities or home therapy channel presence. Long-term viability favors integrated device-fluid manufacturers with reimbursement strategy expertise and software companion development capacity. Watch FDA breakthrough device designations for wearable artificial kidney platforms as inflection indicators for technology disruption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens premarket review timelines for predicate-based dialyzer clearances under updated FDA pathways. |
| CE Marking Pathway Investment | Addresses EU MDR post-market surveillance mandates for bloodline safety documentation across product lifecycles. |
| Hospital System Partnership | Secures multi-station hemodialysis deployments through Medicare-sustained capital refresh cycles in United States networks. |
| Software Companion Development | Enables cloud-connected treatment parameter adjustment and real-time clinical oversight for home therapy patients. |
| Reimbursement Strategy Alignment | Captures Medicare Advantage pilot programs for direct-to-patient concentrate delivery subscription models. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining nephrologist consultations, biomedical engineering directors, dialysis center operations managers, and GPO contracts managers with secondary validation. Primary sources included FDA 510(k) clearance databases, CMS Medicare reimbursement filings, EU MDR notified body registries, and hospital procurement contract disclosures. Bottom-up equipment installation tracking and top-down concentrate consumption modeling were triangulated against manufacturer revenue segment disclosures.
Segment-weighting approaches distributed value across hemodialysis machines, peritoneal dialysis units, dialyzers, and concentrate formulations, with technology tiers and end-user channels as cross-cutting dimensions. CAGRs were derived from installed base evolution, replacement cycle assumptions, and modality shift elasticity across the projection horizon. Forecast inputs incorporated Medicare reimbursement rate negotiations, EU MDR certification timeline constraints, and home therapy patient conversion velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden reimbursement rate cuts or polymer supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Operating Room Integration Market
Medical Devices
Water Flosser Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Global Bioabsorbable Stents Market