
 Global Inflammatory Bowel Disease (IBD) Diagnostic Market | 2026-2036
Global Inflammatory Bowel Disease (IBD) Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inflammatory Bowel Disease (IBD) Diagnostic Market Foresight
Fecal calprotectin biomarker assays are pivoting toward replacing repeated colonoscopies in routine disease monitoring protocols. Thermo Fisher Scientific leverages its PCR platform scale to anchor molecular diagnostic supply chains across North America and Europe. DiaSorin specializes in chemiluminescence immunoassay formats that sustain margin pools in high-throughput laboratory settings.
Inflammatory Bowel Disease diagnostics encompass endoscopic, serological, imaging, and molecular methodologies designed to detect, classify, and monitor chronic intestinal inflammation with specificity thresholds exceeding 85 percent for distinguishing ulcerative colitis from Crohn's disease. Biomarker tests and endoscopy equipment command the largest revenue share, while polymerase chain reaction and enzyme-linked immunosorbent assay technologies capture accelerating volume as laboratories adopt automated platforms for calprotectin and ASCA antibody quantification. Crohn's disease detection and ulcerative colitis diagnosis applications concentrate the highest procedure volumes, though relapse prediction represents the fastest-expanding segment as payers demand evidence-based intervention timing.
The FDA maintains stringent premarket review pathways for IVD devices targeting IBD, while the EMA's IVDR transition reshapes conformity requirements for European market access and the PMDA enforces Japan's QMS standards for imported diagnostic reagents. These frameworks elevate compliance costs but simultaneously filter out lower-accuracy competitors, concentrating procurement authority among laboratories with dedicated regulatory affairs capabilities. Stakeholders must monitor reimbursement policy evolution for pharmacogenomic companion diagnostics, as coverage determinations will dictate whether molecular stratification becomes standard-of-care or remains confined to academic medical centers.
Market Dynamics
The FDA's breakthrough device pathway is compressing validation timelines for novel IBD biomarker assays, while gastroenterology clinics pivot from repeated endoscopies toward non-invasive monitoring panels. This regulatory acceleration collides with supply chain concentration in PCR platform manufacturing.
Growth Catalysts
- Biomarker Panel Adoption:Fecal calprotectin quantification is replacing colonoscopy intervals in routine Crohn's disease surveillance across United States academic medical centers.
- Pharmacogenomic Integration:Germany's statutory health insurers now reimburse molecular stratification tests preceding anti-TNF therapy selection.
- EMA IVDR Transition:The In Vitro Diagnostic Regulation's 2022 enforcement is filtering lower-accuracy competitors from European laboratory procurement pools.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction consumables depend on three North American contract manufacturers, creating single-source vulnerability.
- Specialist Workforce Scarcity:Gastrointestinal pathologist training programs in Japan produce insufficient diagnostic interpreters for expanded ASCA antibody testing volume.
- Endoscopy Equipment Substitution:Capsule endoscopy systems threaten conventional colonoscope refurbishment revenue in outpatient clinic networks.
Strategic Opportunities
- Relapse Prediction Algorithms:Machine learning integration with longitudinal calprotectin datasets offers payers evidence-based intervention timing in ulcerative colitis populations.
- India's Diagnostic Infrastructure:Tier-2 city laboratory networks remain underpenetrated for chemiluminescence immunoassay platforms serving inflammatory bowel disease differentiation.
- PMDA Streamlined Review:Japan's priority review designation for companion diagnostics accelerates market entry for pharmacogenomic assays targeting thiopurine metabolism.
Industry Challenges
- Cross-Platform Standardization:Fecal calprotectin results vary 40% between ELISA and quantitative lateral flow methods, complicating multi-site clinical trial enrollment.
- Laboratory Information System Integration:Automated biomarker reporting requires middleware development for legacy hospital electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inflammatory Bowel Disease (IBD) Diagnostic Market |
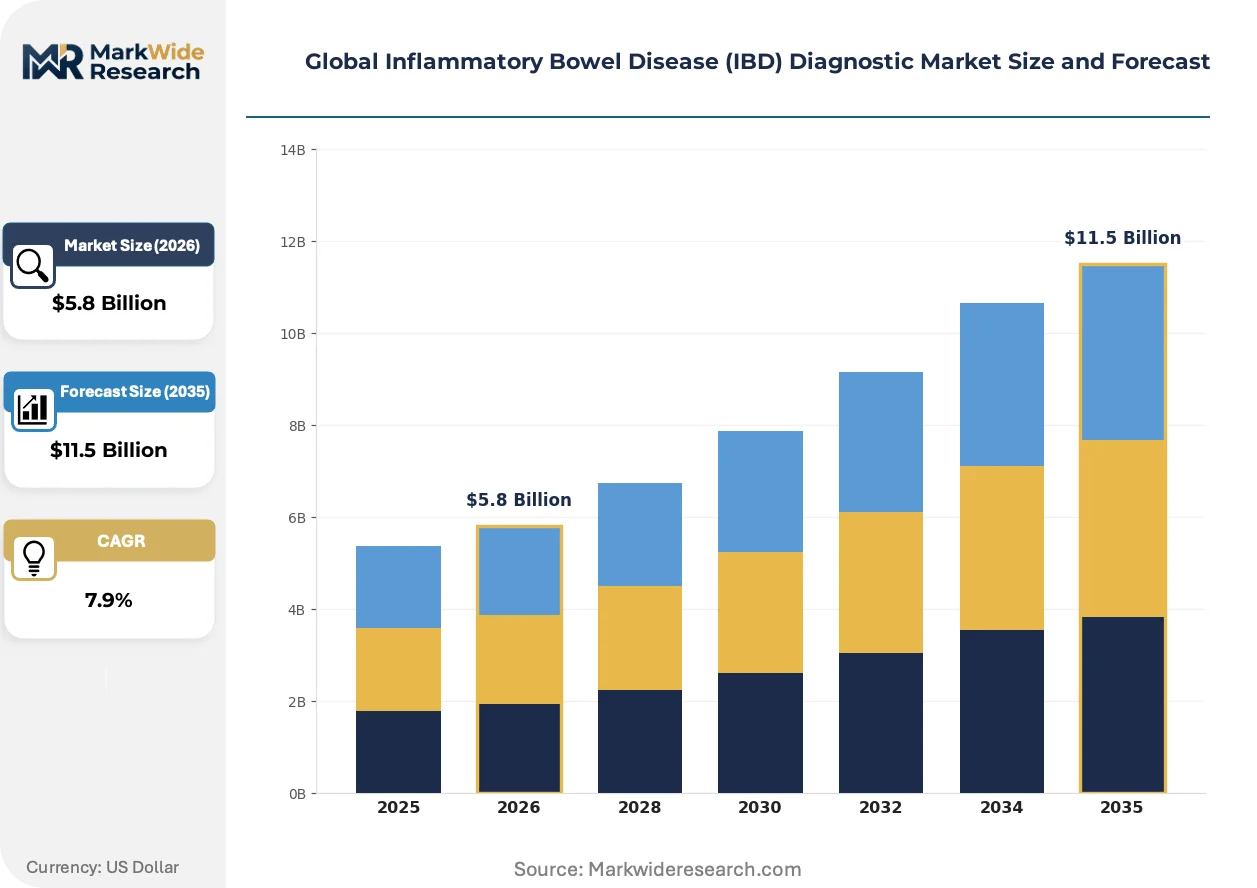
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopy Equipment, Biomarker Tests, Imaging Devices, Laboratory Reagents, Histopathology Kits Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Magnetic Resonance Imaging, Computed Tomography, Ultrasound Application: Ulcerative Colitis Diagnosis, Crohn’s Disease Detection, Disease Monitoring, Treatment Evaluation, Relapse Prediction End User: Gastroenterology Clinics, Diagnostic Laboratories, Research Institutions, Specialized Hospitals, Ambulatory Care Centers |
| Companies Covered | CerTest Biotec, Thermo Fisher Scientific, DiaSorin, Biosystems, Inova Diagnostics, BUHLMANN Laboratories, American Laboratories, Epitope Diagnostics, Quidel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inflammatory Bowel Disease (IBD) Diagnostic Market Shifts & Advancements
Non-invasive biomarker quantification is overtaking anatomical imaging as the primary modality for IBD disease monitoring, compressing the role of repeated endoscopic procedures in longitudinal patient management.
Quantitative lateral flow immunoassays for fecal calprotectin is overtaking enzyme-linked immunosorbent assay formats in point-of-care settings. Community gastroenterology practices in the United States deploy these devices during same-day consultations. The technology is overtaking centralized laboratory referral patterns by enabling immediate therapeutic adjustment decisions without 48-hour turnaround delays.
The EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements on legacy assays previously grandfathered under the IVDD framework. Manufacturers must now submit prospective performance studies for calprotectin devices seeking CE marking renewal. High-throughput laboratory segments in Germany and France are consolidating procurement around suppliers with dedicated regulatory affairs capabilities.
Integrated service contracts bundling assay supply with instrument placement are displacing transactional reagent purchasing in hospital networks. Procurement departments in Japan's prefectural medical centers negotiate multi-year agreements covering maintenance, calibration, and consumable replenishment. This shift concentrates vendor relationships among diagnostics firms offering captive financing for automated platform installation.
Global Inflammatory Bowel Disease (IBD) Diagnostic Market Segmentation
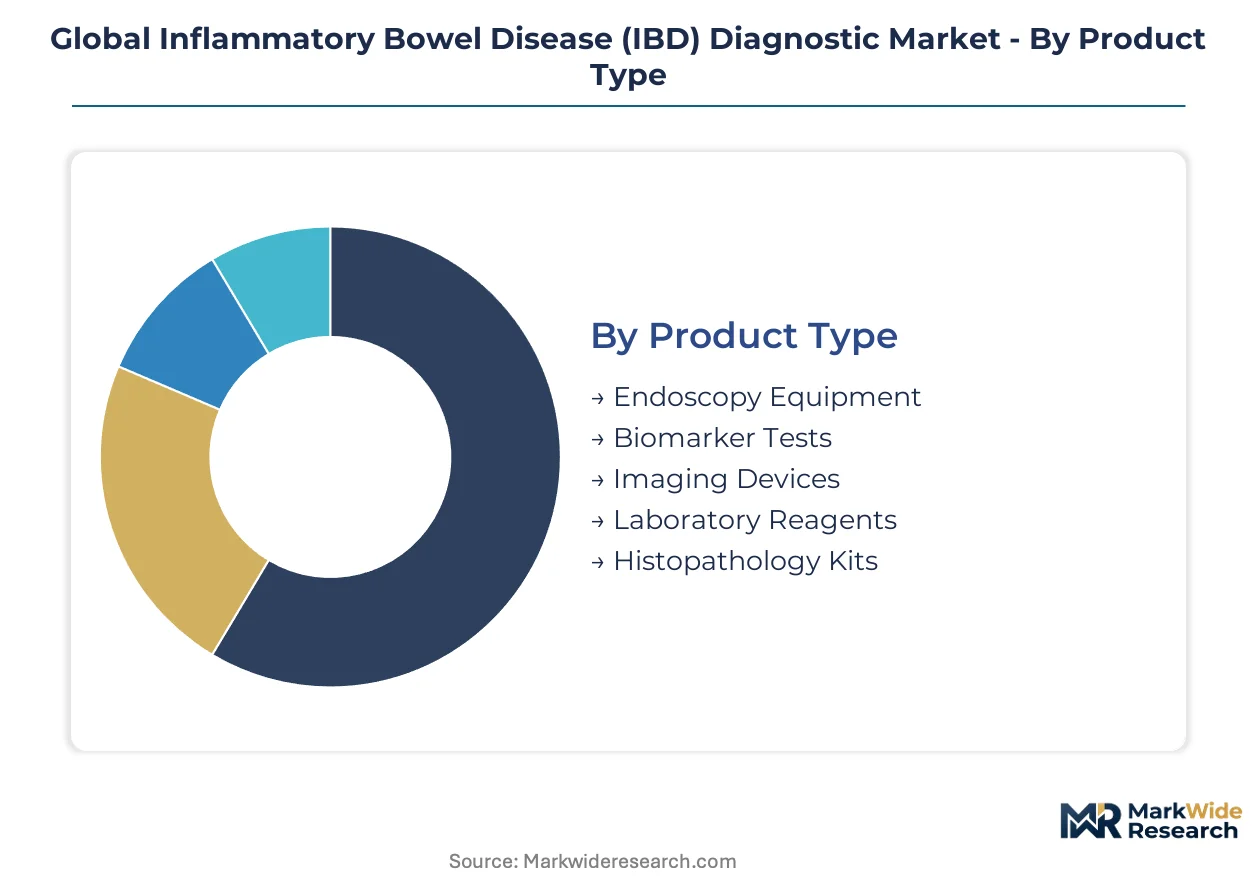
IBD diagnostic procurement patterns diverge sharply across clinical settings, with academic medical centers prioritizing molecular stratification platforms while community practices favor rapid point-of-care biomarker formats. Understanding these segment boundaries reveals where substitution effects between endoscopy and non-invasive testing concentrate revenue risk and opportunity.
Product Type:
Replacement cycles for automated platforms are compressing as laboratories pursue integrated workflow solutions that bundle instrumentation with reagent supply commitments.
- Biomarker Tests:Fecal calprotectin and ASCA antibody quantification assays dominate routine disease surveillance protocols. Demand clusters in United States academic medical centers replacing colonoscopy intervals with non-invasive monitoring panels, driven by payer pressure for evidence-based intervention timing.
- Endoscopy Equipment:High-definition colonoscopes with narrow-band imaging capability anchor definitive diagnosis and dysplasia surveillance. Procurement concentrates in Germany's statutory hospital networks as dedicated IBD diagnostic centers expand, though capsule endoscopy substitution threatens refurbishment revenue in outpatient settings.
- Imaging Devices:Magnetic resonance enterography systems enable small-bowel Crohn's disease assessment without radiation exposure.
- Laboratory Reagents:PCR master mixes and chemiluminescence substrates sustain high-throughput automated platform operations.
- Histopathology Kits:Specialized staining reagents support differential diagnosis between ulcerative colitis and Crohn's disease phenotypes.
Volume placements concentrate in Biomarker Tests; the faster expansion belongs to Endoscopy Equipment as narrow-band imaging upgrades penetrate Japan's prefectural medical centers.
Technology:
Cost tiers separate centralized laboratory automation from distributed point-of-care deployment, with reimbursement differentials determining which molecular formats achieve standard-of-care status.
- Polymerase Chain Reaction:Real-time quantitative PCR enables pharmacogenomic companion diagnostics for thiopurine metabolism and anti-TNF therapy selection. Adoption accelerates in German statutory health insurance networks following reimbursement approval for molecular stratification preceding biologic initiation.
- Enzyme-Linked Immunosorbent Assay:Established workhorse for ASCA and ANCA antibody detection with standardized protocols across reference laboratories. Volume persists in Japan's diagnostic laboratories despite chemiluminescence displacement in high-throughput segments, constrained by capital requirements for platform replacement.
- Magnetic Resonance Imaging:Radiation-free soft-tissue characterization for transmural Crohn's disease assessment.
- Computed Tomography:Emergency department triage for acute complications requiring rapid anatomical resolution.
- Ultrasound:Point-of-care intestinal wall thickness monitoring in pediatric and pregnancy populations.
Procurement volumes favor Polymerase Chain Reaction in pharmacogenomic-enabled markets; Ultrasound gains share fastest in pediatric-specialized centers seeking radiation-sparing alternatives.
Application:
Customer type stratification separates acute diagnostic confirmation from longitudinal management, with divergent margin structures between one-time procedures and recurring monitoring revenue.
- Relapse Prediction:Machine learning integration with longitudinal calprotectin trajectories enables payer-preferred intervention timing. Development concentrates in United States integrated delivery networks capturing value-based care bonuses for preventing hospitalization.
- Disease Monitoring:Scheduled biomarker quantification replaces endoscopic surveillance intervals in stable Crohn's disease populations. Germany's IBD diagnostic centers deploy automated platforms for high-frequency testing, supported by statutory insurer coverage for non-invasive monitoring.
- Ulcerative Colitis Diagnosis:Colonoscopy with histological confirmation remains definitive standard.
- Crohn's Disease Detection:Small-bowel capsule endoscopy and MR enterography address anatomical challenges.
- Treatment Evaluation:Biomarker response assessment guides biologic therapy escalation or de-escalation decisions.
Procedure volumes cluster in Disease Monitoring; Relapse Prediction climbs the fastest as United States payers tie reimbursement to hospitalization reduction metrics.
End User:
Supply concentration in automated platform manufacturing favors diagnostic laboratories with captive financing capabilities and dedicated regulatory affairs functions.
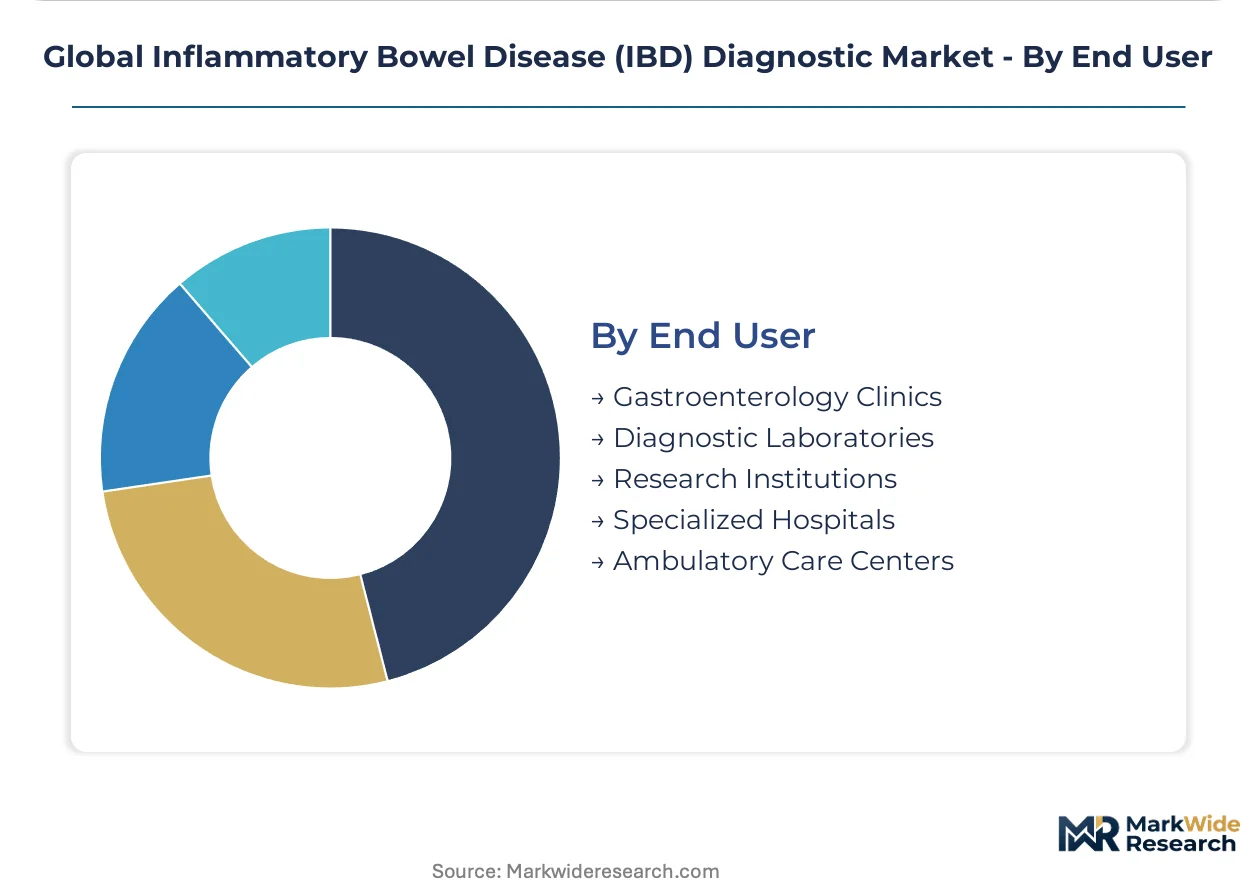
- Diagnostic Laboratories:High-throughput centralized facilities process calprotectin and antibody panels for regional hospital networks. Germany's laboratory consolidation creates procurement leverage for multi-year integrated service contracts bundling instrumentation, maintenance, and reagent supply.
- Gastroenterology Clinics:Community practices deploy quantitative lateral flow devices for same-day therapeutic adjustments. United States ambulatory networks adopt point-of-care formats to eliminate 48-hour reference laboratory turnaround delays.
- Specialized Hospitals:Academic medical centers integrate pharmacogenomic testing into biologic therapy pathways.
- Research Institutions:Prospective biomarker validation studies for novel assay regulatory submission.
- Ambulatory Care Centers:Freestanding endoscopy facilities performing screening colonoscopy with IBD incident detection.
Test volumes concentrate in Diagnostic Laboratories; Gastroenterology Clinics expand most quickly as point-of-care lateral flow deployment penetrates United States community practice networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States gastroenterology clinics are replacing repeated colonoscopies with fecal calprotectin monitoring panels, concentrating procedure demand in academic medical centers and integrated delivery networks. Germany and Japan follow as dedicated IBD diagnostic centers expand statutory coverage for molecular stratification testing.
United States
Academic medical centers in Boston and the Research Triangle Park are deploying automated calprotectin platforms for routine Crohn's disease surveillance. The FDA's breakthrough device pathway compresses validation timelines for novel biomarker assays seeking premarket approval. Gastroenterology clinic networks in Texas and California are adopting quantitative lateral flow devices for same-day therapeutic adjustments.
Germany
Statutory health insurers now reimburse molecular stratification tests preceding anti-TNF therapy selection, accelerating pharmacogenomic adoption in Berlin and Munich hospital networks. The EMA's IVDR transition filters lower-accuracy competitors from laboratory procurement pools. North Rhine-Westphalia's diagnostic laboratory consolidation creates leverage for multi-year integrated service contracts bundling instrumentation and reagent supply.
Japan
Prefectural medical centers in Kanto and Kansai regions negotiate bundled agreements covering maintenance, calibration, and consumable replenishment for automated platforms. The PMDA enforces QMS standards for imported diagnostic reagents while streamlining priority review for companion diagnostics. Tokyo's academic hospitals are integrating pharmacogenomic testing into standard biologic therapy pathways.
United Kingdom
NHS England's specialized commissioning frameworks concentrate IBD diagnostic capacity in London and Manchester tertiary centers. The MHRA's post-Brexit regulatory alignment with IVDR requirements reshapes conformity assessment for CE-marked devices. Cambridge and Oxford research clusters are validating machine learning algorithms for relapse prediction using longitudinal biomarker datasets.
India
Tier-2 city laboratory networks in Maharashtra and Karnataka remain underpenetrated for chemiluminescence immunoassay platforms serving inflammatory bowel disease differentiation. The CDSCO's medical device rules impose quality standards on imported diagnostic reagents while streamlining registration for novel biomarker assays. Hyderabad's diagnostic manufacturing corridor is attracting contract development partnerships for lateral flow device production.
Global Inflammatory Bowel Disease (IBD) Diagnostic Market Competitive Landscape
Strategic partnerships dominate the current landscape as diagnostics firms seek captive financing capabilities and regulatory affairs expertise. The vendor base clusters around three archetypes: multinational life science conglomerates with PCR platform scale, specialized immunoassay manufacturers with chemiluminescence expertise, and regional contract manufacturers serving point-of-care formats. Portfolio diversification and integrated service contracting represent the primary competitive vectors, with laboratories consolidating procurement around suppliers offering multi-year bundling arrangements.
Among the multinational tier, Thermo Fisher Scientific exemplifies platform-scale supply chain anchoring across North America and Europe. DiaSorin occupies a position within the specialized immunoassay segment, sustaining margin pools in high-throughput laboratory settings through chemiluminescence format dominance. CerTest Biotec represents the regional specialist archetype, with Zaragoza-based operations concentrated on lateral flow and molecular diagnostic formats for infectious and autoimmune disease applications.
| Leading Market Players |
|---|
| CerTest Biotec |
| Thermo Fisher Scientific |
| DiaSorin |
| Biosystems |
| Inova Diagnostics |
| BUHLMANN Laboratories |
| American Laboratories |
| Epitope Diagnostics |
| Quidel |
| Others |
Supply & Pricing Matrix
Academic medical center procurement consolidation in the United States and Germany anchors contract-based pricing for automated IBD diagnostic platforms. These buyers negotiate multi-year bundled agreements covering instrumentation, maintenance, and reagent supply, compressing margins for suppliers lacking captive financing capabilities.
Pricing Analysis
High-throughput laboratory segments capture volume-driven pricing, while point-of-care formats sustain premium margins through immediate-result value. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated assays from CE-marked alternatives and unregulated research-use-only products. Pricing pressure stems from Germany's statutory insurer reimbursement compression for routine calprotectin monitoring. Community gastroenterology clinics in the United States exhibit highest price sensitivity, whereas Japan's prefectural medical centers prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Specialist workforce scarcity in Japan's gastrointestinal pathology training programs constrains manufacturing expansion for ASCA antibody test kits. PCR master mix production concentrates in the United States, Germany, and Singapore, drawing from semiconductor-grade polymerase enzymes and fluorescence probe chemistries. Single-source vulnerability pervades North American contract manufacturers supplying thermocycler consumables. Distribution runs through diagnostic laboratory networks with integrated service contracting replacing transactional purchasing.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IBD diagnostic market functions as a vertical-integration race where platform manufacturers pursue captive reagent supply to lock in multi-year procurement relationships. Control over automated instrument placement determines downstream consumable revenue capture.
For Market Incumbents: Cement platform-scale advantage by acquiring regional lateral flow specialists before point-of-care formats displace centralized laboratory referral patterns. Expand dedicated regulatory affairs capabilities in Berlin and Tokyo to filter competitors during EMA IVDR and PMDA QMS transitions. Prioritize backward integration into fluorescence probe chemistry to secure PCR reagent margin pools against supply concentration risks. For New Entrants and Emerging Players: Capture India's tier-2 city laboratory networks before chemiluminescence immunoassay platforms achieve penetration in Maharashtra and Karnataka diagnostic corridors. Target community gastroenterology clinics in Texas and California with quantitative lateral flow devices enabling same-day therapeutic adjustments. Pursue CDSCO streamlined registration pathways for novel biomarker assays as Hyderabad's manufacturing corridor matures. For Investors and Strategic Acquirers: The window for entry favors specialized immunoassay manufacturers with chemiluminescence expertise and existing CE marking infrastructure. Long-term viability hinges on pharmacogenomic companion diagnostic positioning as standard-of-care integration accelerates in German statutory health networks. Watch for FDA breakthrough device designation announcements as inflection indicators for validation timeline compression and premium pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Multi-year bundling of instrumentation and reagent supply locks hospital procurement relationships in Germany. |
| Regulatory Affairs Expansion | Dedicated IVDR and QMS capabilities filter competitors from European and Japanese laboratory procurement pools. |
| Point-of-Care Platform Development | Quantitative lateral flow formats eliminate 48-hour turnaround delays in United States community gastroenterology practices. |
| Pharmacogenomic Assay Prioritization | Companion diagnostics for thiopurine metabolism secure reimbursement in German statutory health insurance networks. |
| Machine Learning Integration | Relapse prediction algorithms using longitudinal calprotectin datasets capture value-based care bonuses from United States payers. |
Research Methodology
FDA 510(k) filings, EMA IVDR technical documentation, and German statutory health insurance reimbursement databases formed the secondary backbone of this analysis. Primary interviews with gastroenterology clinic directors, hospital procurement committee members, diagnostic laboratory managers, and regulatory affairs specialists at IVD manufacturers were combined with secondary validation. Bottom-up and top-down triangulation cross-referenced instrument placement data with reagent consumption patterns.
Bottom-up modeling segmented the market by product type, technology platform, application purpose, and end-user setting across the analysis window. CAGRs were derived from procedure volume projections tied to payer coverage expansion for non-invasive monitoring protocols. Forecast inputs incorporated pharmacogenomic test adoption curves in German hospital networks and point-of-care lateral flow penetration rates in United States ambulatory settings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA breakthrough designation velocity and EMA IVDR enforcement consistency. Forecasts reflect documented assumptions regarding statutory reimbursement stability and PCR reagent supply continuity. Material deviation in PMDA priority review timelines or German laboratory consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Global Urinalysis Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Elisa Tests Market