
 Neurocutaneous Disorders Market | 2026-2036
Neurocutaneous Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Neurocutaneous Disorders Market Outlook
Market Context with Strategic Players
A capital-intensity divergence between large pharmaceutical conglomerates and mid-tier specialists is bifurcating competitive dynamics in neurocutaneous disorder therapeutics. Novartis AG leverages its established oncology infrastructure to anchor mTOR inhibitor development for tuberous sclerosis complex. Roche Holding AG sustains biomarker-driven diagnostic integration across its neurodevelopmental portfolio. Pfizer Inc. competes through scaled clinical trial networks that accelerate rare disease enrollment.
Technical Definition and Structural Segments
Neurocutaneous disorders constitute a heterogeneous group of congenital conditions characterized by simultaneous nervous system and skin manifestations, with diagnostic criteria requiring identification of characteristic hamartomatous lesions, cafe-au-lait spots, or vascular malformations alongside neurological dysfunction. These disorders primarily serve pediatric and adult neurology practices where early intervention prevents progressive complications including epilepsy, cognitive impairment, and malignant transformation. Systemic therapies command the deepest margin pools due to chronic administration requirements, while diagnostic tools represent the fastest-expanding segment as genetic testing panels broaden detection capabilities. Topical treatments occupy a mature position with limited innovation, whereas surgical interventions sustain premium positioning for lesion debulking and seizure focus resection in specialized epilepsy centers.
Regulatory Framework and Forward Outlook
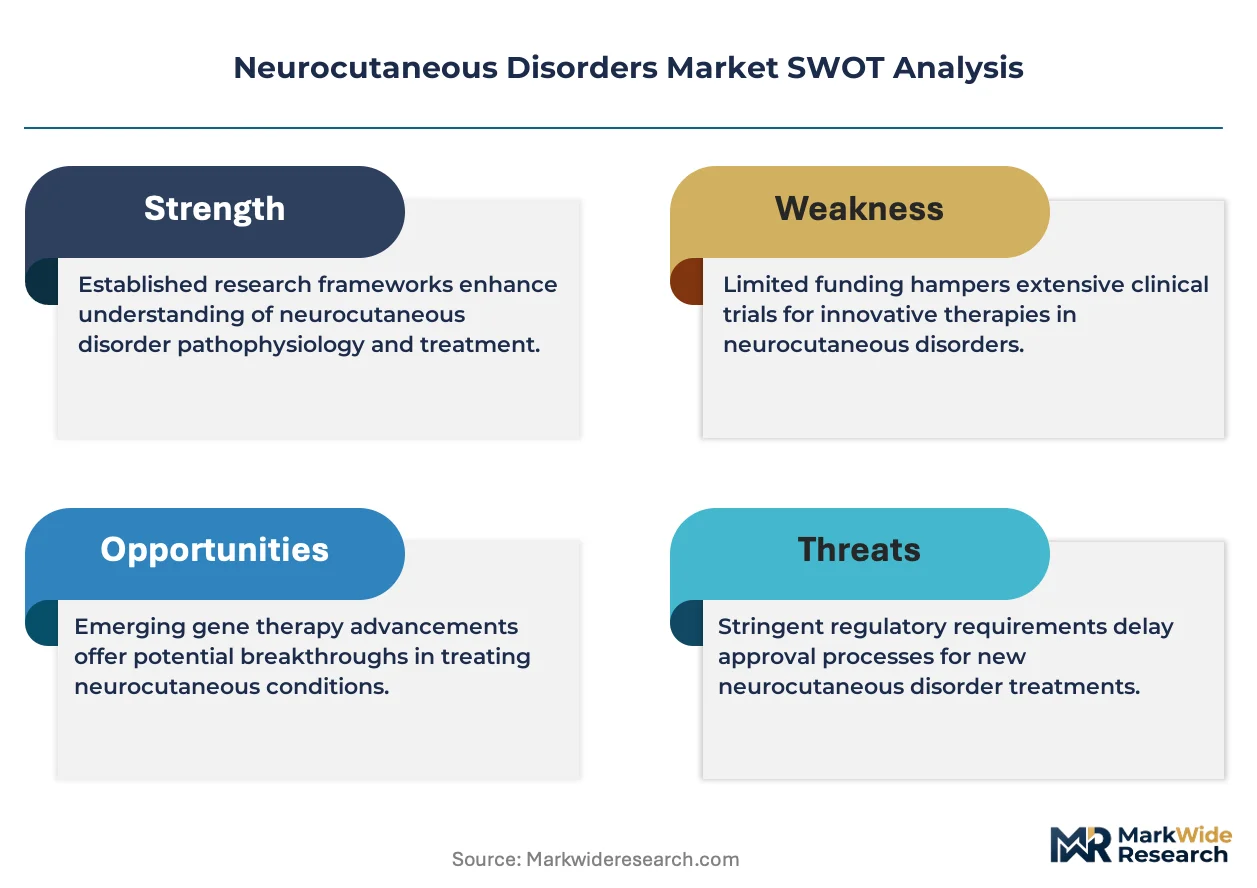
The FDA orphan drug program shapes neurocutaneous disorder development through seven-year market exclusivity incentives and waived regulatory fees, while the EMA's similar framework accelerates European access for tuberous sclerosis and neurofibromatosis therapies. Health Canada's Priority Review pathway and Japan's PMDA Sakigake designation collectively expand multinational trial feasibility for sponsors navigating divergent evidentiary standards. Stakeholders must monitor how emerging gene therapy platforms interact with existing small-molecule reimbursement benchmarks.
Market Dynamics
mTOR pathway inhibition is consolidating clinical protocols across tuberous sclerosis complex treatment centers, compressing trial timelines and reshaping competitive entry barriers for novel mechanistic classes.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market protection and waived regulatory fees accelerate sponsor commitment to rare neurocutaneous indications, particularly neurofibromatosis type 1 and Sturge-Weber syndrome programs.
- Pediatric Neurology Network Expansion:Academic medical centers in the United States are establishing dedicated neurocutaneous clinics that streamline referral pathways and concentrate eligible patient pools for interventional studies.
- Companion Diagnostic Integration:Next-generation sequencing panels for mosaicism detection are expanding addressable patient populations beyond classical diagnostic criteria, enabling earlier therapeutic intervention.
Market Restraints
- Specialized Manufacturing Concentration:Active pharmaceutical ingredient production for mTOR inhibitors concentrates among a limited cohort of contract manufacturers in Switzerland and Germany, creating supply vulnerability.
- Reimbursement Benchmark Rigidity:Payers in Germany and France apply reference pricing frameworks designed for small-molecule oncology, compressing margins for chronic rare disease administration.
- Natural History Data Scarcity:Incomplete longitudinal registries for tuberous sclerosis complex and neurofibromatosis type 2 complicate endpoint validation and prolong regulatory negotiation timelines.
Strategic Opportunities
- Gene Therapy Platform Convergence:Adeno-associated viral vector delivery combined with CRISPR-based editing is opening curative paradigms for neurofibromatosis type 1, with first-in-human trials anticipated in academic hospital networks.
- Telemedicine-Enabled Rural Access:Remote genetic counseling and dermatologic screening are penetrating underserved regions in Australia and Canada, expanding detection rates without brick-and-clinic infrastructure.
- Japan PMDA Sakigake Designation:Priority review and dedicated consultation pathways for regenerative medicines are attracting multinational sponsors to establish Japanese pivotal trial sites ahead of Western regulatory submissions.
Industry Challenges
- Neurogenetics Specialist Shortage:Fellowship-trained clinicians capable of interpreting complex mosaic presentations remain concentrated in major metropolitan academic centers, constraining diagnostic throughput.
- Multi-Site Trial Coordination:Harmonizing MRI acquisition protocols across epilepsy surgery centers and pediatric neurology departments demands substantial standardization investment before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurocutaneous Disorders Market |
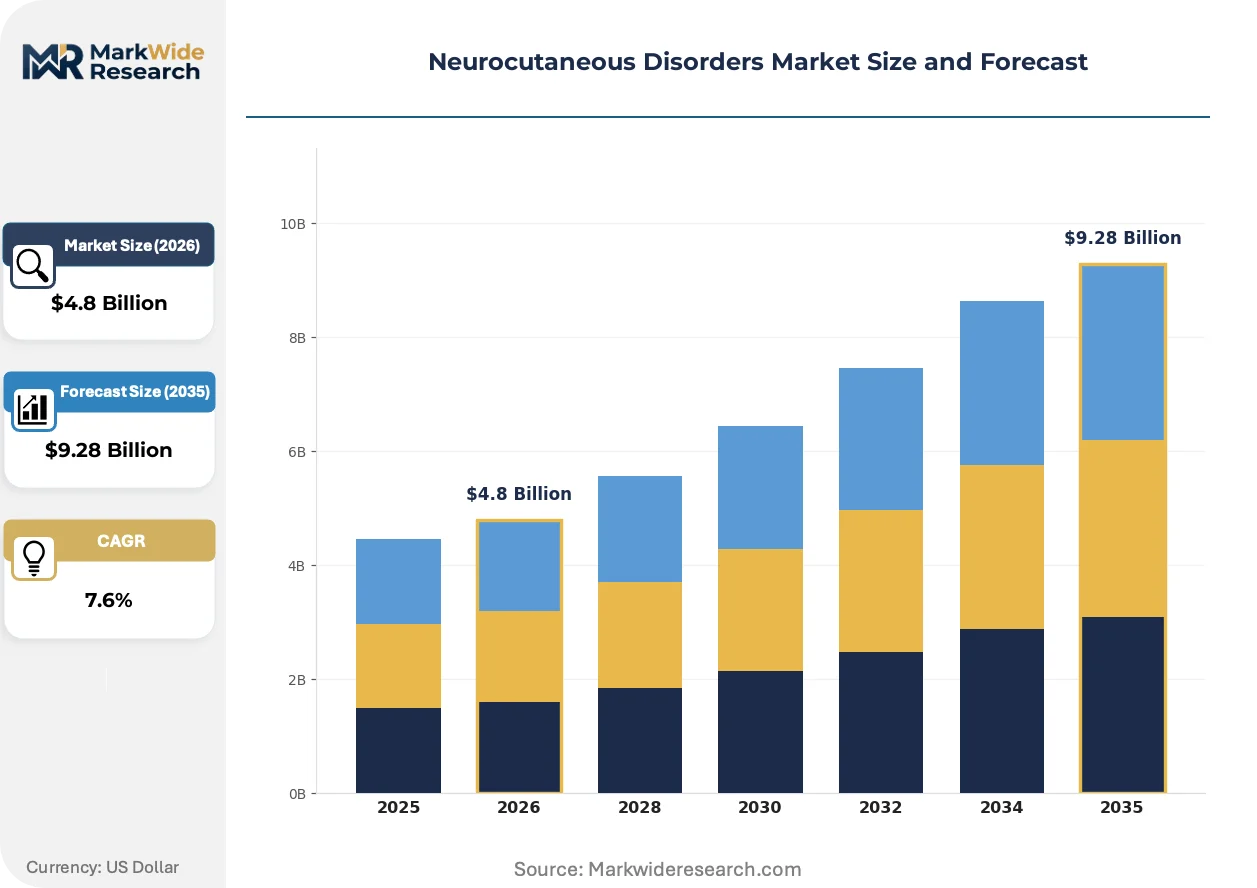
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Surgical Interventions, Systemic Therapies, Diagnostic Tools Therapy Area: Neurofibromatosis, Tuberous Sclerosis, Sturge-Weber Syndrome, Epidermal Nevus Syndrome End User: Hospitals, Clinics, Research Institutions, Home Healthcare Delivery Mode: Injectable, Oral, Transdermal, Inhalation |
| Companies Covered | Novartis AG, Pfizer Inc., Roche Holding AG, Sanofi S.A., Johnson & Johnson, AbbVie Inc., Merck & Co., Inc., Bristol-Myers Squibb, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurocutaneous Disorders Market Strategic Shifts
Wearable seizure detection devices and remote patient monitoring platforms are compressing the interval between symptom onset and clinical intervention, fundamentally altering how disease progression is tracked outside hospital settings.
Implantable intracranial pressure sensors paired with subcutaneous drug delivery pumps is miniaturizing the hardware footprint for tuberous sclerosis complex patients requiring chronic everolimus administration. Pediatric epilepsy centers at Boston Children's Hospital and Great Ormond Street Hospital are piloting these closed-loop systems, enabling real-time biomarker-adjusted dosing that reduces nephrotoxicity monitoring burdens.
EMA's 2023 revision to the orphan medicinal product regulation now mandates real-world evidence generation post-authorization, compelling sponsors to maintain active patient registries for neurofibromatosis therapies. This structural requirement is extending commercial infrastructure commitments beyond traditional launch phases, with German and French health technology assessment bodies incorporating registry data into renewal pricing negotiations.
Hospital procurement departments are unbundling diagnostic testing from therapeutic provision, creating separate vendor relationships for genetic counseling, imaging interpretation, and pharmaceutical distribution. This fragmentation is most pronounced in United States academic medical centers, where specialized neurocutaneous clinics now maintain independent contracts with reference laboratories rather than relying on integrated health system agreements.
Neurocutaneous Disorders Market Segmentation
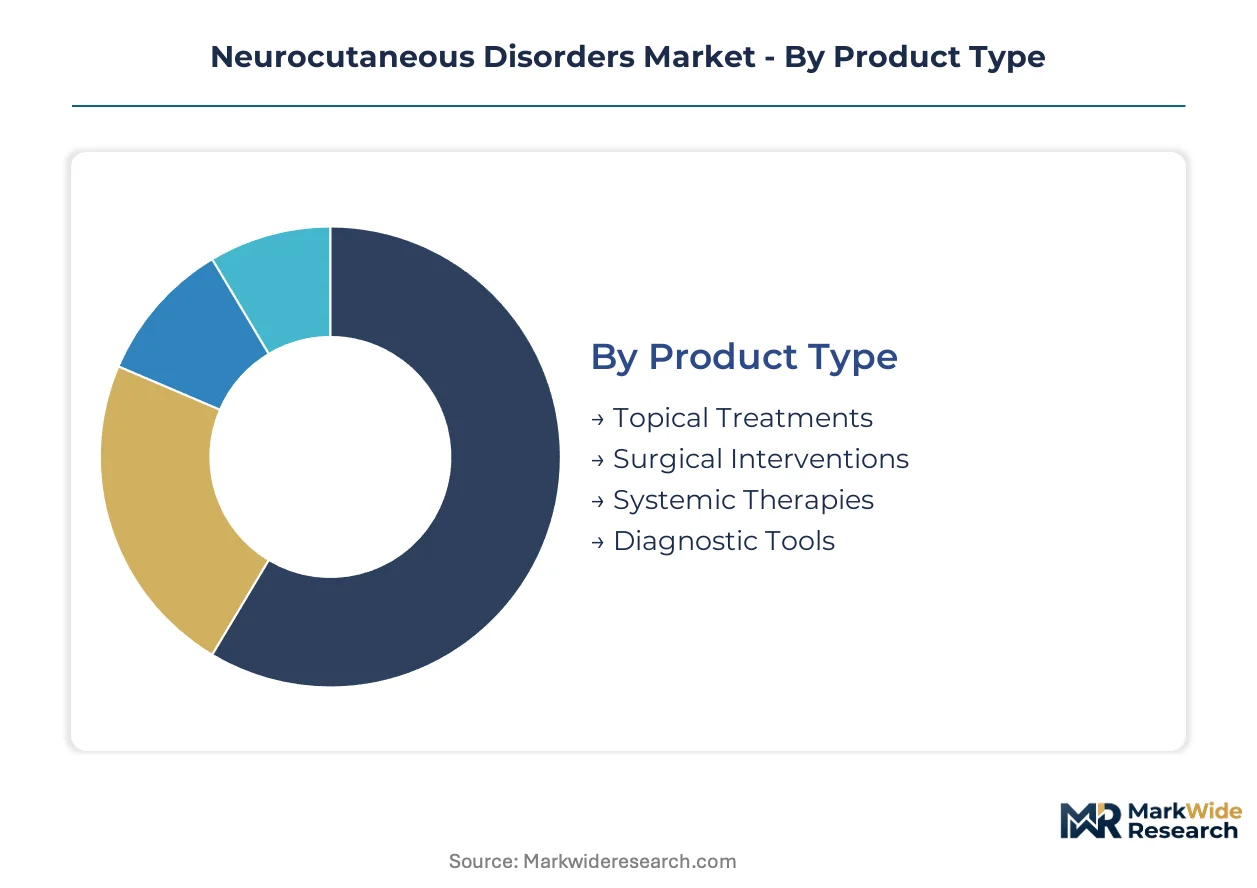
Segmentation in neurocutaneous disorders reveals how treatment complexity, chronicity, and diagnostic precision requirements fragment commercial pathways. Channel selection—hospital-based versus ambulatory versus home settings—determines which product configurations capture margin and which face commoditization.
Product Type:
Hospital pharmacies and specialty distributors handle high-complexity segments, while retail and mail-order channels manage chronic maintenance therapies.
- Systemic Therapies:Chronic oral mTOR inhibitors and emerging biologics require cold-chain logistics and specialty pharmacy networks. Demand concentrates in United States academic medical centers where prior authorization specialists navigate payer complexity for everolimus and sirolimus protocols.
- Diagnostic Tools:Next-generation sequencing panels and MRI protocols with neuroimaging biomarkers flow through reference laboratories and hospital radiology departments. Germany's university hospitals and France's rare disease centers anchor European adoption, driven by EMA orphan drug companion diagnostic mandates.
- Topical Treatments:Limited-innovation segment serving lesion management in outpatient dermatology.
- Surgical Interventions:Epilepsy surgery and lesion debulking delivered through specialized neurosurgical centers.
By volume, Systemic Therapies leads. By growth pace, Diagnostic Tools is expanding most quickly.
Therapy Area:
Cost tiers stratify sharply: orphan-designated indications command premium pricing, while larger patient pools face reference pricing pressure.
- Neurofibromatosis:Type 1 and Type 2 variants drive the deepest development pipelines, with MEK inhibitors and gene therapy platforms targeting plexiform neurofibroma progression. Pediatric oncology networks at Boston Children's Hospital and Great Ormond Street Hospital concentrate interventional trial enrollment.
- Tuberous Sclerosis:mTOR pathway inhibition has established clinical standard-of-care, compressing trial timelines for novel entrants. Patient advocacy organizations in the United States and Germany maintain active registries that accelerate natural history data collection.
- Sturge-Weber Syndrome:Vascular anomaly management with laser therapy and antiepileptic protocols.
- Epidermal Nevus Syndrome:Mosaic disorder with limited targeted therapeutic development to date.
By patient volume, Neurofibromatosis dominates. By pipeline velocity, Tuberous Sclerosis is gaining share fastest.
End User:
Procurement authority varies: integrated delivery networks centralize hospital purchasing, while clinic fragmentation sustains vendor diversification.
- Hospitals:Academic medical centers with dedicated neurocutaneous clinics anchor complex case management and surgical intervention. United States children's hospitals and German university hospitals maintain the deepest specialist concentrations.
- Clinics:Community neurology and dermatology practices handle stable patients and routine monitoring.
- Research Institutions:Natural history study coordination and early-phase trial execution.
- Home Healthcare:Subcutaneous drug delivery and remote patient monitoring for chronic therapy administration.
By revenue concentration, Hospitals leads. By expansion trajectory, Home Healthcare is climbing the fastest.
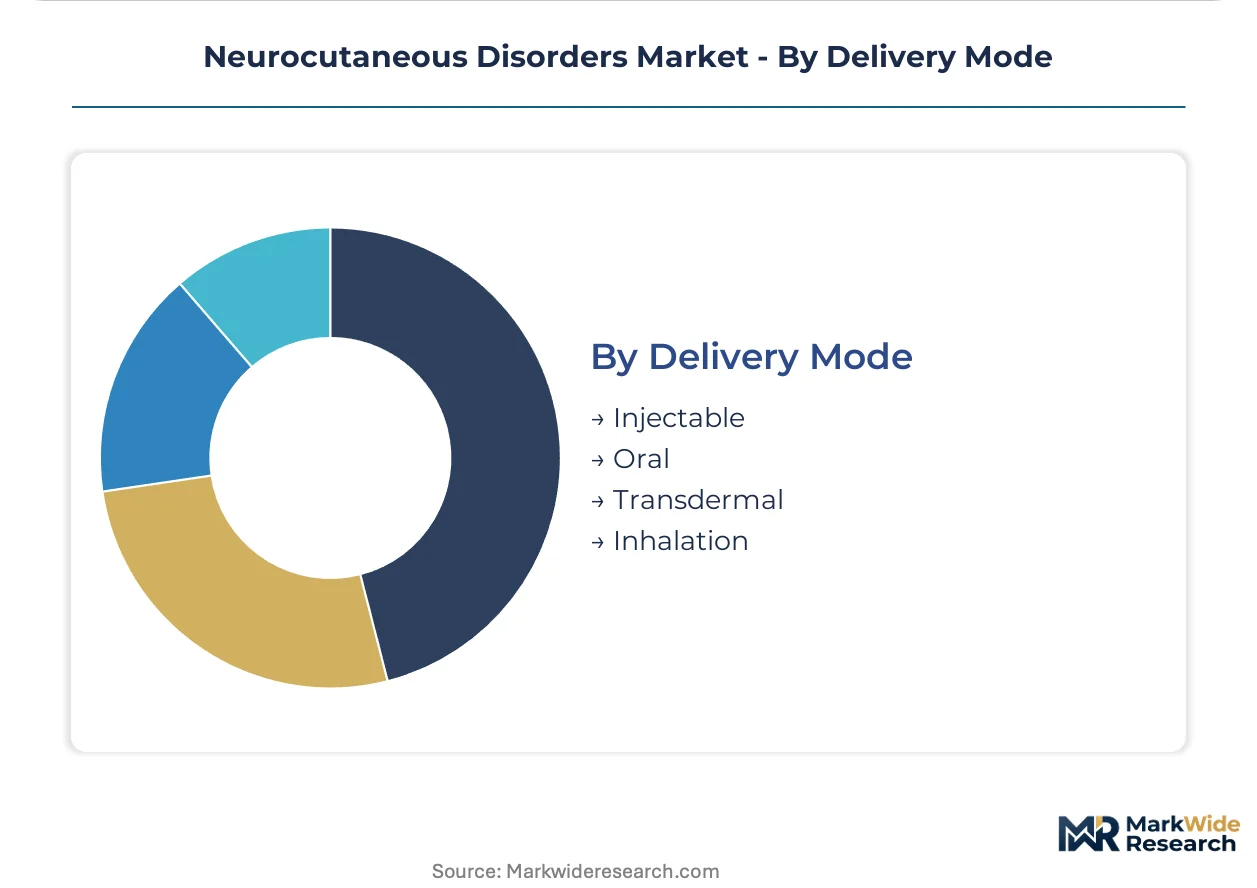
Delivery Mode:
Patient adherence requirements and caregiver burden shape formulation selection across pediatric and adult populations.
- Oral:Tablet and liquid formulations dominate chronic mTOR inhibitor administration, with taste-masked suspensions critical for pediatric compliance. Japan's PMDA Sakigake designation has accelerated modified-release development programs.
- Injectable:Subcutaneous depot formulations and intrathecal delivery for CNS-targeted therapy.
- Transdermal:Limited current application but explored for localized drug delivery to cutaneous lesions.
- Inhalation:Investigational route for pulmonary lymphangioleiomyomatosis manifestations in tuberous sclerosis.
By current utilization, Oral leads. By innovation investment, Injectable shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States academic medical centers while German reference pricing frameworks compress margins for chronic mTOR inhibitor administration. This asymmetry shapes regional investment priorities across the forecast horizon.
United States
Specialized neurofibromatosis clinics at Boston Children's Hospital and Cincinnati Children's anchor referral networks that concentrate eligible patient pools. FDA orphan drug exclusivity provides seven-year market protection for rare disease therapeutics. The NIH-funded Rare Diseases Clinical Research Network accelerates natural history data collection across multiple sites.
Germany
University hospitals in Munich and Heidelberg maintain Europe's deepest concentrations of neurogenetics specialists and epilepsy surgery capacity. EMA orphan medicinal product designation pairs with Germany's G-BA health technology assessment framework. The country's reference pricing system for small-molecule drugs compresses reimbursement rates for chronic everolimus protocols.
Japan
Pediatric neurology departments at Tokyo Women's Medical University and Osaka University Hospital drive clinical trial enrollment for tuberous sclerosis therapies. PMDA Sakigake designation offers priority review and dedicated consultation pathways for regenerative medicines. Modified-release formulation development programs target the country's aging caregiver population.
Switzerland
Contract manufacturing for mTOR inhibitor active pharmaceutical ingredients concentrates in Basel-region facilities serving global supply chains. Swissmedic maintains alignment with EMA regulatory standards while offering streamlined pediatric investigation plan consultations. The country's precision medicine clusters support biomarker-driven diagnostic integration for mosaicism detection.
United Kingdom
Great Ormond Street Hospital and Manchester University NHS Foundation Trust coordinate specialized neurocutaneous disorder services across England's regional networks. MHRA post-Brexit regulatory autonomy enables accelerated access partnerships for innovative medicines. NHS England's specialized commissioning framework concentrates funding for rare disease treatments at designated centers.
Neurocutaneous Disorders Market Competitive Environment
Concentration sits with large pharmaceutical conglomerates possessing established rare disease infrastructures and scaled clinical trial networks. Mid-tier specialists compete through targeted mechanistic expertise in mTOR pathway modulation. Three archetypes dominate: oncology-anchored diversified giants, neurology-focused biopharmaceutical developers, and emerging gene therapy platforms. Competitive moves center on diagnostic-therapeutic integration and pediatric network expansion.
Within the diversified pharmaceutical tier, Novartis AG and Roche Holding AG exemplify archetypes leveraging existing infrastructure for rare disease penetration. Novartis anchors mTOR inhibitor development through its established oncology footprint, while Roche sustains biomarker-driven diagnostic integration across neurodevelopmental portfolios. Pfizer Inc. occupies a scale-driven position competing through global clinical trial enrollment velocity for rare neurocutaneous indications.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Roche Holding AG |
| Sanofi S.A. |
| Johnson & Johnson |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day active pharmaceutical ingredient lead times for mTOR inhibitors tether pricing power to Swiss and German contract manufacturing capacity, compressing margins for sponsors unable to secure multi-year offtake agreements with Basel-region facilities.
Pricing Analysis
The customization-premium spread between standard everolimus formulations and patient-specific dosing protocols reaches its widest point in United States academic medical centers, where specialty pharmacy networks justify premium positioning through prior authorization navigation and adherence monitoring services. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and companion diagnostic bundling. Pricing pressure stems from German G-BA reference pricing frameworks that compress reimbursement for chronic small-molecule administration. Community neurology clinics exhibit highest price sensitivity due to thin formulary margins, while pediatric epilepsy centers at designated children's hospitals demonstrate lowest sensitivity given captive patient flows and specialized commissioning budgets.
Supply Chain Analysis
Switzerland and Germany anchor active pharmaceutical ingredient production for mTOR inhibitors, with Basel-region facilities supplying global everolimus and sirolimus programs. Raw material dependencies center on rapamycin fermentation feedstocks, specialized chromatography resins, and cold-chain packaging components. Single-source vulnerability concentrates in Swiss contract manufacturing organizations serving multiple competing sponsors simultaneously. Distribution runs through hospital-based specialty pharmacies in the United States and centralized university hospital procurement in Germany, with emerging direct-to-patient models penetrating home healthcare channels for chronic maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neurocutaneous disorders market sits at an inflection point where FDA orphan drug exclusivity and EMA real-world evidence mandates are reshaping commercial infrastructure requirements, creating asymmetric returns for sponsors with integrated diagnostic-therapeutic capabilities.
For Market Incumbents: Consolidate manufacturing relationships with Swiss API producers through captive capacity investments or long-term offtake structures, while deepening vertical integration into companion diagnostic development to satisfy EMA post-authorization registry requirements. Gene therapy platform entrants threaten mTOR inhibitor franchise durability, demanding proactive biomarker-driven patient segmentation to defend high-value chronic therapy segments. For New Entrants and Emerging Players: Anchor in Japan's PMDA Sakigake pathway for regenerative medicine designations, where priority review timelines and dedicated consultation channels compress regulatory negotiation cycles relative to Western submissions. Telemedicine-enabled rural access in Australia and Canada represents the most penetrable white-space target, with remote genetic counseling and dermatologic screening requiring minimal brick-and-clinic infrastructure. A direct-to-patient distribution model paired with wearable seizure detection hardware offers differentiated go-to-market positioning. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because gene therapy convergence with CRISPR editing platforms will eventually displace chronic small-molecule administration, compressing the window for returns on traditional mTOR inhibitor assets. Acquisition targets should display mechanistic expertise in neurogenetics, established pediatric neurology network relationships, and active natural history registry infrastructure. The signal to watch is first-in-human gene therapy trial readouts from academic hospital networks, which will reset competitive timelines and valuation benchmarks across the sector.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | EMA's 2023 orphan regulation mandates real-world evidence generation post-authorization, requiring active patient registries. |
| Pediatric Network Expansion | Boston Children's Hospital and Great Ormond Street Hospital anchor referral networks that concentrate eligible patient pools for interventional studies. |
| Gene Therapy Platform Development | Adeno-associated viral vector delivery combined with CRISPR-based editing opens curative paradigms for neurofibromatosis type 1. |
| Telemedicine-Enabled Rural Access | Remote genetic counseling penetrates underserved regions in Australia and Canada without brick-and-clinic infrastructure investment. |
| Japan PMDA Sakigake Designation | Priority review and dedicated consultation pathways attract multinational sponsors to establish Japanese pivotal trial sites. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric neurologists, genetic counselors, hospital formulary directors, and rare disease advocacy organization leadership. Secondary validation drew from FDA orphan drug designation filings, EMA orphan medicinal product submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient population estimates were triangulated against top-down pharmaceutical revenue attribution across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including therapy area, delivery mode, and regional regulatory cluster. CAGRs were derived from longitudinal revenue trajectory analysis and patient volume scaling assumptions. Forecast inputs incorporated natural history registry enrollment velocity, companion diagnostic penetration curves, and mTOR inhibitor treatment persistence rates.
Underlying assumptions cover regulatory pathway stability and reimbursement framework continuity, with deviation risk concentrated in gene therapy platform advancement timelines and neurogenetics specialist supply constraints. Recalibration cycles align with material shifts in orphan drug exclusivity policy, real-world evidence mandate enforcement, and pivotal trial readout announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
China Neurology Devices Market
Neurology
Labyrinthitis Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Global Neuroblastoma Market
Neurology
Acute Repetitive Seizures Market
Neurology
Neurology Digital Therapeutics Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Movement Disorder Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Cluster Headache Syndrome Market
Neurology
Arachnoiditis Treatment Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Sweden Neurology Devices Market
Neurology
US Optic Neuritis Market
Neurology
CNS Therapeutics Market