
 Creatinine Test Market | 2026-2036
Creatinine Test Market Size, Share, and Industry Trends Forecast 2026-2036
Creatinine Test Market Analysis
Reagent subscription models is pivoting how laboratories procure creatinine testing capacity, shifting capital expenditure into recurring operational contracts. Abbott Laboratories leverages its integrated diagnostics platform to lock in multi-year consumable agreements. Siemens Healthineers anchors its position through automated analyzer placements that bind customers to proprietary reagent streams. Thermo Fisher Scientific competes by extending its clinical chemistry menu breadth across hospital networks.
Creatinine testing measures nitrogenous waste concentration in biological specimens to estimate glomerular filtration rate, typically employing enzymatic or colorimetric detection with picric acid or creatinine amidohydrolase chemistry at wavelengths near 510 nm. The assay serves nephrology, drug toxicity monitoring, and perioperative risk stratification. Serum creatinine testing dominates routine clinical workflows, while point-of-care testing captures the fastest expansion as emergency departments and dialysis clinics prioritize turnaround speed over central lab precision. Enzymatic methods command premium positioning due to reduced bilirubin and protein interference, whereas colorimetric approaches retain cost-sensitive volume in developing health systems.
The US FDA and Clinical Laboratory Improvement Amendments framework govern assay precision and proficiency testing thresholds, while the EU In Vitro Diagnostic Regulation mandates stricter clinical evidence for creatinine reagent kits entering European markets. China's National Medical Products Administration accelerates domestic IVD registration timelines, reshaping competitive access for multinational manufacturers. Stakeholders must monitor evolving harmonization efforts between reference method standardization bodies and regional traceability requirements for isotope dilution mass spectrometry calibration.
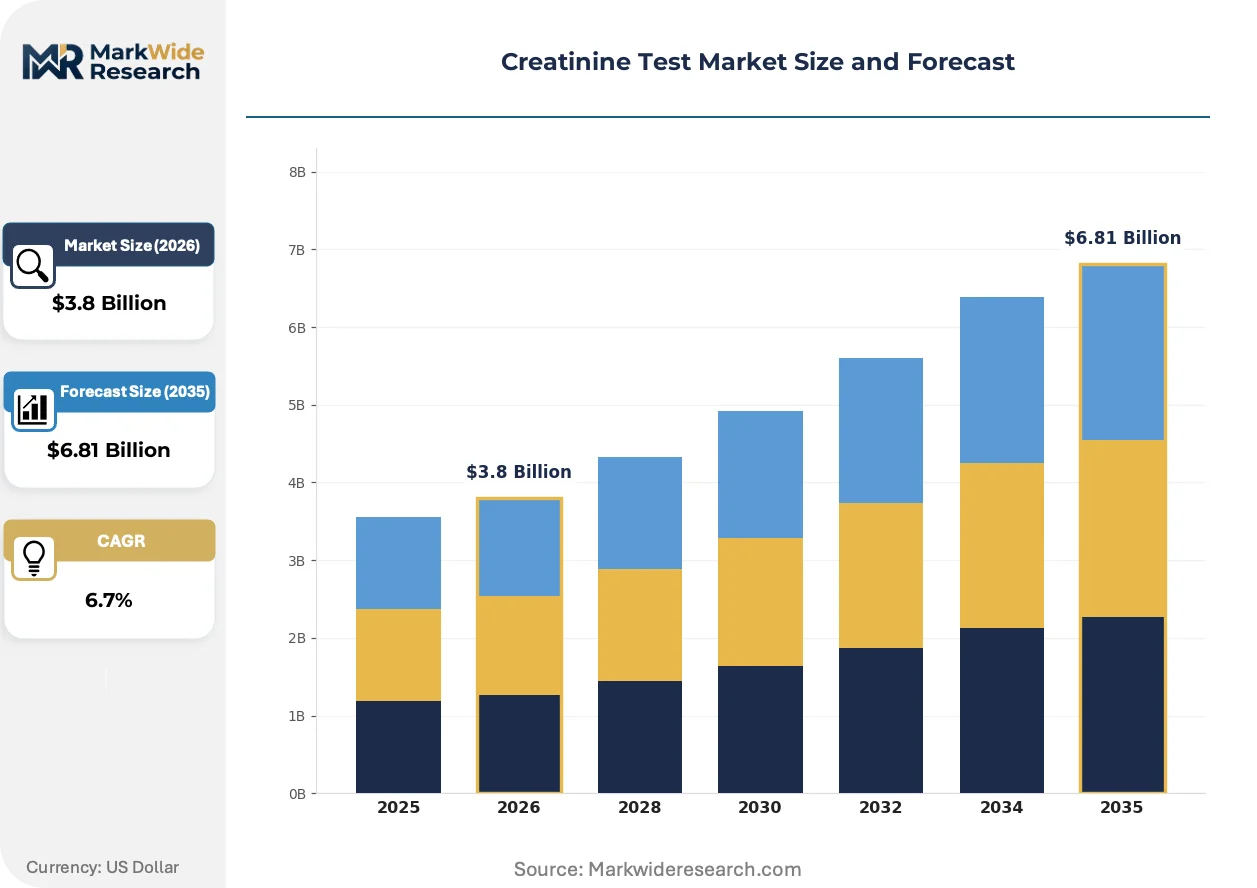
Market Dynamics
Automated analyzer placements are restructuring procurement economics across hospital networks, converting capital equipment decisions into decade-long reagent lock-in arrangements that reshape vendor-switching costs.
Growth Catalysts
- Chronic kidney disease screening mandates:China's tier-one hospital clusters are scaling population-wide creatinine testing protocols under national health system reforms, expanding installed base demand for compatible analyzers.
- CLIA proficiency testing thresholds:The US framework tightens precision requirements for enzymatic assays, driving replacement cycles toward higher-accuracy platforms in clinical laboratories.
- Point-of-care turnaround requirements:Emergency departments and dialysis clinics prioritize speed over central lab precision, accelerating decentralized testing infrastructure deployment.
Market Restraints
- Picric acid supply volatility:Colorimetric chemistry dependence on specialized chemical feedstocks exposes developing health systems to input cost swings and procurement instability.
- Isotope dilution mass spectrometry calibration scarcity:Reference method standardization concentrates in limited national metrology institutes, creating traceability bottlenecks for assay manufacturers.
- EU In Vitro Diagnostic Regulation clinical evidence requirements:Stricter documentation mandates for creatinine reagent kits entering European markets extend registration timelines and compliance expenditures.
Strategic Opportunities
- Underpenetrated dialysis clinic networks:Brazil's expanding chronic kidney disease treatment infrastructure lacks standardized point-of-care testing protocols, creating first-mover positioning for integrated platform vendors.
- Reagent subscription model conversion:Multi-year consumable agreements displace spot purchasing in US hospital procurement, locking in predictable revenue streams and raising competitor switching barriers.
- AI-assisted result interpretation:Machine learning integration with automated analyzers enables real-time glomerular filtration rate estimation, differentiating premium platform offerings in nephrology workflows.
Industry Challenges
- Enzymatic assay validation complexity:Bilirubin and protein interference reduction claims require extensive clinical correlation studies, stretching regulatory submission timelines for novel chemistry formulations.
- Legacy analyzer integration friction:Hospital networks with embedded installed bases face workflow disruption costs when migrating to automated platforms, slowing replacement cycle velocity despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatinine Test Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum Creatinine Test, Urine Creatinine Test, Creatinine Clearance Test, Point-of-Care Testing End User: Hospitals, Diagnostic Laboratories, Homecare Settings, Research Institutes Technology: Enzymatic Method, Colorimetric Method, High-Performance Liquid Chromatography, Immunoassay Application: Kidney Function Assessment, Drug Monitoring, Chronic Kidney Disease Screening, Research |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, Siemens Healthineers, Roche Diagnostics, Danaher Corporation, Nova Biomedical, Randox Laboratories, Sysmex Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatinine Test Market Emerging Trajectories
Creatinine testing is fragmenting across performance tiers as speed requirements diverge from precision demands, splitting vendor strategies between emergency department point-of-care and central laboratory automation.
Enzymatic creatinine amidohydrolase chemistry is automating interference reduction in high-volume hospital laboratories. Nephrology departments and perioperative surgical units are adopting these platforms at accelerated replacement cycles. The technology is automating the elimination of manual sample pre-treatment steps, compressing labor costs and error rates in routine workflows.
China's National Medical Products Administration accelerates domestic IVD registration timelines, compressing market access windows for multinational manufacturers. Domestic reagent kit producers gain competitive runway against established chemistry platforms. Multinational manufacturers are responding with localized production investments and joint venture structures to preserve hospital network relationships.
Hospital procurement departments are consolidating vendor relationships around integrated diagnostics platforms that bundle creatinine testing with broader clinical chemistry menus. Independent reagent suppliers and specialized assay manufacturers face exclusion from preferred vendor lists. This consolidation pattern is most visible in US hospital network purchasing cooperatives and German hospital procurement alliances.
Creatinine Test Market Segmentation
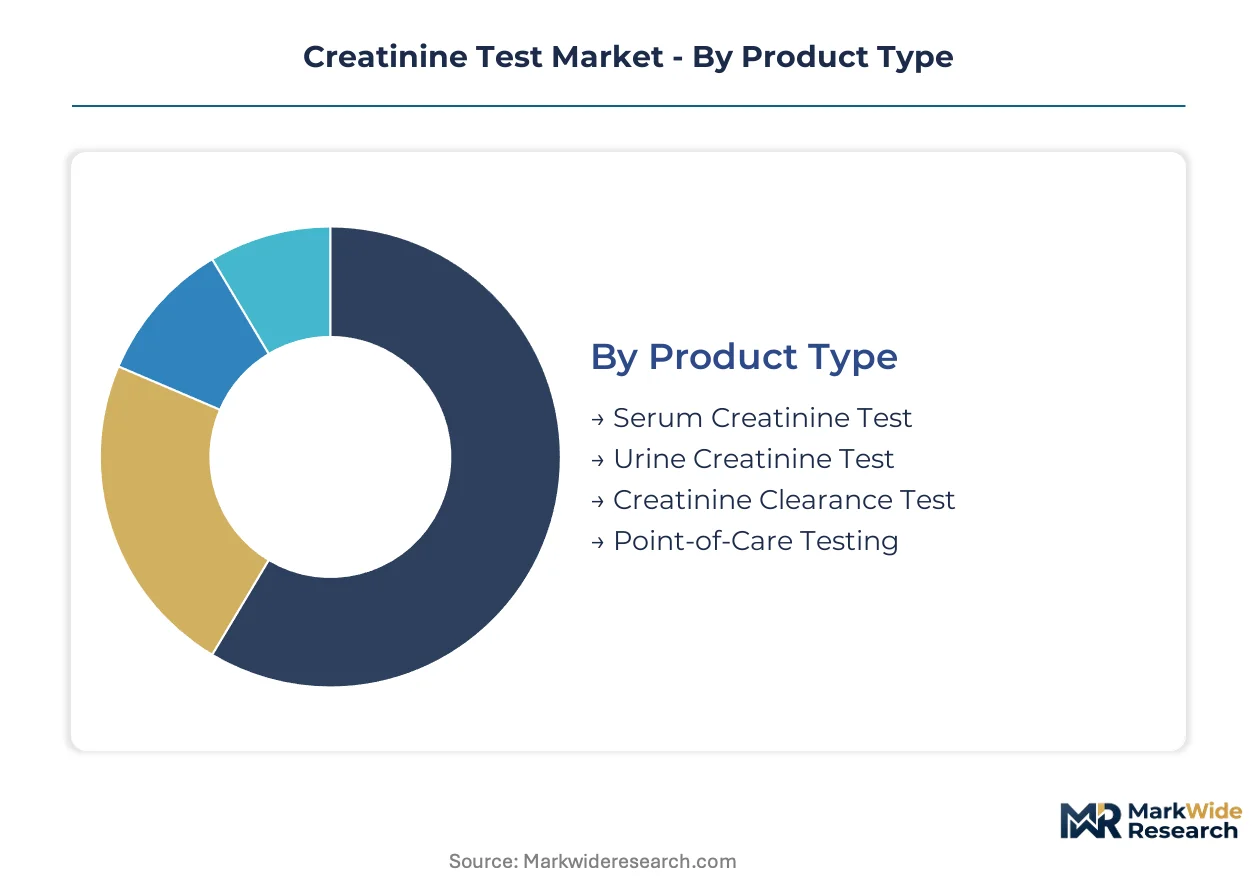
Creatinine testing fragments across performance tiers and procurement channels as speed requirements diverge from precision demands. Laboratories, emergency departments, and homecare settings each impose distinct technical specifications and workflow constraints that reshape vendor product portfolios.
Product Type:
Procurement economics separate buyers into capital-intensive central lab operators versus decentralized speed-focused facilities.
- Serum Creatinine Test:Blood-drawn specimens processed through automated clinical chemistry analyzers dominate routine nephrology workflows in hospital networks. US hospital purchasing cooperatives consolidate procurement around integrated platforms that bundle serum testing with broader metabolic panels, locking in multi-year reagent agreements.
- Point-of-Care Testing:Finger-stick or whole-blood assays deliver results within minutes for emergency departments and dialysis clinics prioritizing turnaround over central lab precision. China's tier-one city hospital clusters are scaling bedside testing protocols under national chronic kidney disease screening mandates, accelerating analyzer placements in acute care settings.
- Urine Creatinine Test:Spot urine or 24-hour collection specimens support creatinine clearance calculations and proteinuria assessment in nephrology departments.
- Creatinine Clearance Test:Timed urine collection combined with serum measurement estimates glomerular filtration rate for drug dosing adjustments in oncology and antimicrobial therapy.
Serum creatinine testing leads volumes today; point-of-care testing is gaining share fastest.
End User:
Facility scale and patient throughput determine whether buyers prioritize menu breadth, speed, or cost minimization.
- Hospitals:Acute care networks with embedded nephrology departments demand automated platforms integrating enzymatic interference reduction with high-throughput sample processing. German hospital procurement alliances are consolidating vendor relationships around diagnostics platforms bundling creatinine with comprehensive metabolic panels.
- Diagnostic Laboratories:Independent reference labs and hospital-affiliated central labs optimize for reagent cost per test and CLIA proficiency compliance. The US FDA's tightened assay validation requirements are driving replacement cycles toward higher-accuracy enzymatic platforms in clinical laboratory networks.
- Homecare Settings:Dialysis patients and chronic kidney disease cohorts use self-monitoring devices for creatinine trend tracking between clinical visits.
- Research Institutes:Academic medical centers and contract research organizations employ standardized assays for clinical trial biomarker validation and drug safety studies.
Hospital networks capture the largest procurement volumes; homecare settings are expanding most quickly as remote patient monitoring protocols proliferate.
Technology:
Interference tolerance and reagent stability separate premium chemistry from cost-optimized alternatives.
- Enzymatic Method:Creatinine amidohydrolase chemistry eliminates picric acid interference from bilirubin and protein, commanding premium positioning in high-volume laboratories. Nephrology departments and perioperative surgical units are adopting these platforms at accelerated replacement cycles as the US tightens precision requirements.
- Colorimetric Method:Jaffe reaction with picric acid retains cost-sensitive volume in developing health systems despite susceptibility to analytical interference. Brazil's expanding chronic kidney disease treatment infrastructure relies on colorimetric approaches where reagent supply chains face picric acid procurement volatility.
- High-Performance Liquid Chromatography:Reference-grade separation techniques support isotope dilution mass spectrometry traceability for assay standardization in national metrology institutes.
- Immunoassay:Antibody-based detection methods serve specialized research applications and alternative specimen matrices including saliva and dried blood spots.
Colorimetric chemistry leads test volumes globally; enzymatic methods are climbing the fastest as interference reduction automates manual pre-treatment steps.
Application:
Clinical urgency and reimbursement pathways reshape whether testing occurs in centralized laboratories or at the point of care.
- Kidney Function Assessment:Glomerular filtration rate estimation from serum creatinine underpins nephrology diagnosis, staging, and treatment monitoring across hospital networks and dialysis chains. China's national health system reforms are embedding population-wide screening protocols in tier-one city hospital clusters.
- Drug Monitoring:Pharmacokinetic dosing of renally cleared medications including chemotherapy agents, antibiotics, and contrast media requires rapid turnaround in oncology and perioperative units. Emergency departments prioritize point-of-care platforms for immediate dosing decisions.
- Chronic Kidney Disease Screening:Asymptomatic population testing programs in employer health plans and community health centers drive volume in diagnostic laboratories.
- Research:Biomarker discovery and clinical endpoint validation for renal therapeutics employ standardized creatinine assays across academic and contract research settings.
Kidney function assessment dominates current test volumes; drug monitoring applications are expanding most rapidly as precision dosing protocols proliferate in oncology and antimicrobial therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one hospital clusters deploy creatinine testing infrastructure faster than US clinical laboratories automate replacement cycles, reflecting divergent health system investment priorities between centralized screening mandates and precision-driven platform upgrades.
United States
Hospital purchasing cooperatives consolidate procurement around integrated diagnostics platforms that bundle creatinine testing with comprehensive metabolic panels. The FDA tightens assay validation requirements under CLIA proficiency testing frameworks, accelerating replacement cycles toward higher-accuracy enzymatic platforms. Boston and San Francisco medical centers anchor demand for automated analyzer placements with multi-year reagent lock-in arrangements.
Germany
Hospital procurement alliances consolidate vendor relationships around diagnostics platforms bundling creatinine with broader clinical chemistry menus. The EU In Vitro Diagnostic Regulation mandates stricter clinical evidence for reagent kits entering European markets, extending registration timelines. Munich and Heidelberg medical clusters drive demand for reference-grade isotope dilution mass spectrometry traceability in nephrology workflows.
China
Tier-one city hospital clusters scale population-wide creatinine testing protocols under national chronic kidney disease screening mandates. The National Medical Products Administration accelerates domestic IVD registration timelines, compressing market access windows for multinational manufacturers. Shanghai and Beijing hospital networks anchor installed base demand for compatible analyzers under health system reform programs.
Brazil
Expanding chronic kidney disease treatment infrastructure lacks standardized point-of-care testing protocols, creating positioning opportunities for integrated platform vendors. ANVISA governs IVD registration and quality standards for diagnostic reagents entering the market. São Paulo and Rio de Janeiro dialysis clinic networks drive demand for decentralized testing infrastructure with speed-focused specifications.
Japan
Nephrology departments and perioperative surgical units adopt enzymatic interference reduction platforms at accelerated replacement cycles. PMDA oversees clinical trial requirements and manufacturing standards for diagnostic devices and reagents. Tokyo and Osaka hospital networks concentrate demand for high-throughput automated analyzers integrating creatinine testing with renal function assessment panels.
Creatinine Test Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostics platforms commanding premium positioning in hospital networks while independent reagent suppliers retain cost-sensitive volume in developing health systems. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with clinical chemistry breadth, specialized diagnostics manufacturers with nephrology-focused portfolios, and point-of-care testing specialists with speed-optimized platforms. M&A activity targets automated analyzer technology assets, while strategic partnerships lock in multi-year consumable agreements that raise competitor switching barriers.
Among diversified diagnostics conglomerates, Abbott Laboratories, Siemens Healthineers, and Roche Diagnostics exemplify the integrated platform archetype that bundles creatinine testing with broader metabolic panels. These companies occupy positions where automated analyzer placements convert capital equipment decisions into decade-long reagent supply relationships. Their geographic footprints span North American, European, and Asia-Pacific hospital networks through localized production investments and joint venture structures.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Roche Diagnostics |
| Danaher Corporation |
| Nova Biomedical |
| Randox Laboratories |
| Sysmex Corporation |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Captive reagent production by Abbott Laboratories, Siemens Healthineers, and Roche Diagnostics anchors both supply security and pricing power across hospital networks. These vertically integrated diagnostics platforms convert analyzer placements into decade-long consumable lock-in arrangements that insulate premium pricing from spot-market volatility.
Pricing Analysis
Capacity additions in China's tier-one hospital clusters are reshaping price floors for enzymatic assay platforms as domestic IVD manufacturers gain regulatory runway under accelerated NMPA timelines. Three-tier pricing structure across premium, standard, and economy levels separates interference-reducing enzymatic chemistry from cost-optimized colorimetric alternatives. Pricing pressure stems from reagent subscription model conversion in US hospital purchasing cooperatives, where multi-year consumable agreements compress spot-purchasing premiums. Diagnostic laboratories in developing health systems exhibit highest price sensitivity, while nephrology departments in academic medical centers prioritize assay accuracy over per-test cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States operate hub-and-spoke patterns for reagent kit fulfillment to hospital networks and diagnostic laboratories. Manufacturing concentration rests on specialized chemical feedstocks including picric acid for colorimetric chemistry and purified creatinine amidohydrolase enzymes for enzymatic platforms. Single-source vulnerability runs through limited national metrology institutes supplying isotope dilution mass spectrometry calibration standards. Distribution runs through direct sales forces for integrated platform vendors and specialized diagnostics distributors for independent reagent suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where CLIA proficiency testing threshold tightening and EU In Vitro Diagnostic Regulation implementation create sustained demand for assay validation investments.
For Market Incumbents: Deepen reagent subscription model penetration through multi-year consumable agreements that raise competitor switching barriers in US hospital purchasing cooperatives. Expand enzymatic assay production capacity in China through localized joint venture structures that preserve network relationships against domestic IVD manufacturers. Vertical integration into picric acid and enzyme feedstock supply hedges procurement volatility exposure in developing health systems. For New Entrants and Emerging Players: AI-assisted result interpretation modules offer a technology-first wedge into nephrology workflow automation, differentiating against legacy analyzer platforms. Brazil's underpenetrated dialysis clinic networks present the most penetrable geography for point-of-care testing platforms with speed-optimized specifications. Partner with regional distribution specialists rather than building direct sales infrastructure to accelerate hospital procurement committee access. For Investors and Strategic Acquirers: Roll-up economics work for point-of-care testing specialists because fragmented dialysis clinic networks lack standardized procurement protocols and vendor consolidation runway. Target acquisition archetypes include enzymatic chemistry platform developers with FDA 510(k) clearance and installed base in academic medical centers. Watch for NMPA registration timeline compression as inflection indicator for multinational manufacturer repositioning urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Subscription Model Conversion | Multi-year consumable agreements lock in predictable revenue streams across US hospital networks. |
| Localized Production Investment | Joint venture structures in China preserve market access under compressed NMPA registration timelines. |
| AI-Assay Integration Development | Machine learning modules differentiate premium platforms in nephrology workflow automation. |
| Point-of-Care Platform Expansion | Brazil's dialysis clinic networks lack standardized testing protocols, creating first-mover positioning. |
| Enzymatic Chemistry R&D Scale-Up | Interference reduction capabilities command premium positioning as CLIA precision requirements tighten. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with clinical laboratory directors, hospital procurement managers, nephrology department heads, and IVD regulatory affairs specialists with secondary validation. Primary sources included FDA 510(k) filings, NMPA registration databases, EU MDR technical documentation, and hospital GPO contract disclosures. Secondary sources encompassed customs trade data for reagent kit imports, SEC filings from listed diagnostics manufacturers, and clinical chemistry proficiency testing reports. Bottom-up modeling of analyzer placements and reagent consumption triangulated against top-down market sizing from health system expenditure data.
Historical reference periods anchored the projection horizon through installed base analysis and replacement cycle velocity assessment across hospital networks. Segmentation dimensions modeled include product type, end-user facility scale, technology chemistry platform, and geographic regulatory cluster. CAGRs derived from regression analysis of analyzer placement trends, reagent consumption per installed unit, and pricing trajectory by platform tier. Industry-specific forecast inputs incorporated CLIA proficiency testing threshold evolution and chronic kidney disease screening program rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to picric acid supply disruptions, reference method standardization bottlenecks, and EU MDR clinical evidence requirement enforcement variability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Rapid Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Fungal Antigens Market
Diagnostics
Antigen Skin Test Market
Diagnostics
LDL Test Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market