
 Diabetes Monitors Market | 2026-2036
Diabetes Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Monitors Market Analysis
Hospital procurement consolidation is restructuring how diabetes monitoring devices reach end users, with integrated delivery networks negotiating enterprise-wide contracts that favor vendors with full product portfolios. Abbott Laboratories leverages its FreeStyle platform to anchor hospital system relationships across North America. Dexcom competes through specialization in real-time continuous glucose monitoring with embedded predictive algorithms. Medtronic sustains its position by extending insulin pump integration with proprietary sensor ecosystems.
Diabetes monitors encompass electrochemical biosensors, optical measurement systems, and minimally invasive interstitial fluid analyzers designed to quantify blood glucose concentration with clinical-grade accuracy, typically within a range of 20 to 600 mg/dL for regulatory clearance purposes. These devices serve the primary commercial purpose of enabling therapeutic decision-making for insulin dosing, dietary adjustment, and hypoglycemia prevention in ambulatory and acute care settings. Continuous glucose monitors lead the product type landscape by capturing recurring sensor revenue streams, while flash glucose monitors occupy the fastest-growing position as pharmacy-channel access broadens. Self-monitoring technology dominates unit volume through established blood glucose meter installed bases, though wireless technology segments attract disproportionate R&D investment for closed-loop artificial pancreas development.
The FDA's 510(k) and De Novo pathways govern market access for novel glucose monitoring technologies in the United States, requiring predicate device comparisons or clinical validation studies that extend development timelines. Europe's MDR and IVDR frameworks, administered by notified bodies under EMA coordination, impose stricter post-market surveillance obligations that favor manufacturers with established quality management systems. Stakeholders must monitor reimbursement code revisions by national health technology assessment bodies, as these determine patient out-of-pocket costs and manufacturer pricing power across key markets.
Market Dynamics
Hospital procurement consolidation in the United States is compressing vendor margins and favoring suppliers with integrated sensor-pump ecosystems capable of supporting value-based care metrics.
Growth Catalysts
- Statutory health insurance reimbursement:Germany's expanded coverage for real-time CGM systems has removed cost barriers for Type 1 diabetes patients, accelerating sensor replacement cycles.
- Flash glucose monitoring:Pharmacy-channel distribution of factory-calibrated sensors is capturing patients who resist traditional fingerstick routines.
- Closed-loop algorithm development:Predictive glucose forecasting embedded in continuous monitors is unifying insulin dosing decisions with real-time metabolic data.
Market Restraints
- Electrochemical sensor material costs:Platinum and glucose oxidase enzyme price volatility constrains disposable sensor margins for manufacturers without captive chemical supply.
- Notified body capacity:Europe's MDR transition has created bottlenecks in conformity assessment for new glucose monitoring submissions, delaying market access.
- Optical measurement accuracy:Non-invasive spectroscopic alternatives remain clinically insufficient for insulin dosing decisions, limiting substitution pressure.
Strategic Opportunities
- India's tier-two cities:Underpenetrated diagnostic infrastructure and rising diabetes prevalence create whitespace for affordable self-monitoring blood glucose meters with Bluetooth connectivity.
- Insulin pump convergence:Sensor-integrated closed-loop systems are capturing high-acuity patients previously managed through multiple disconnected devices.
- Remote patient monitoring mandates:US Medicare reimbursement for remote therapeutic monitoring codes is incentivizing health systems to deploy continuous glucose data in chronic care management programs.
Industry Challenges
- Biocompatibility engineering talent:Scarcity of specialists in subcutaneous sensor membrane design is elongating R&D timelines for next-generation interstitial fluid analyzers.
- 510(k) predicate pathway constraints:FDA's narrowing acceptance of substantial equivalence for novel glucose monitoring indications is forcing more resource-intensive De Novo submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Monitors Market |
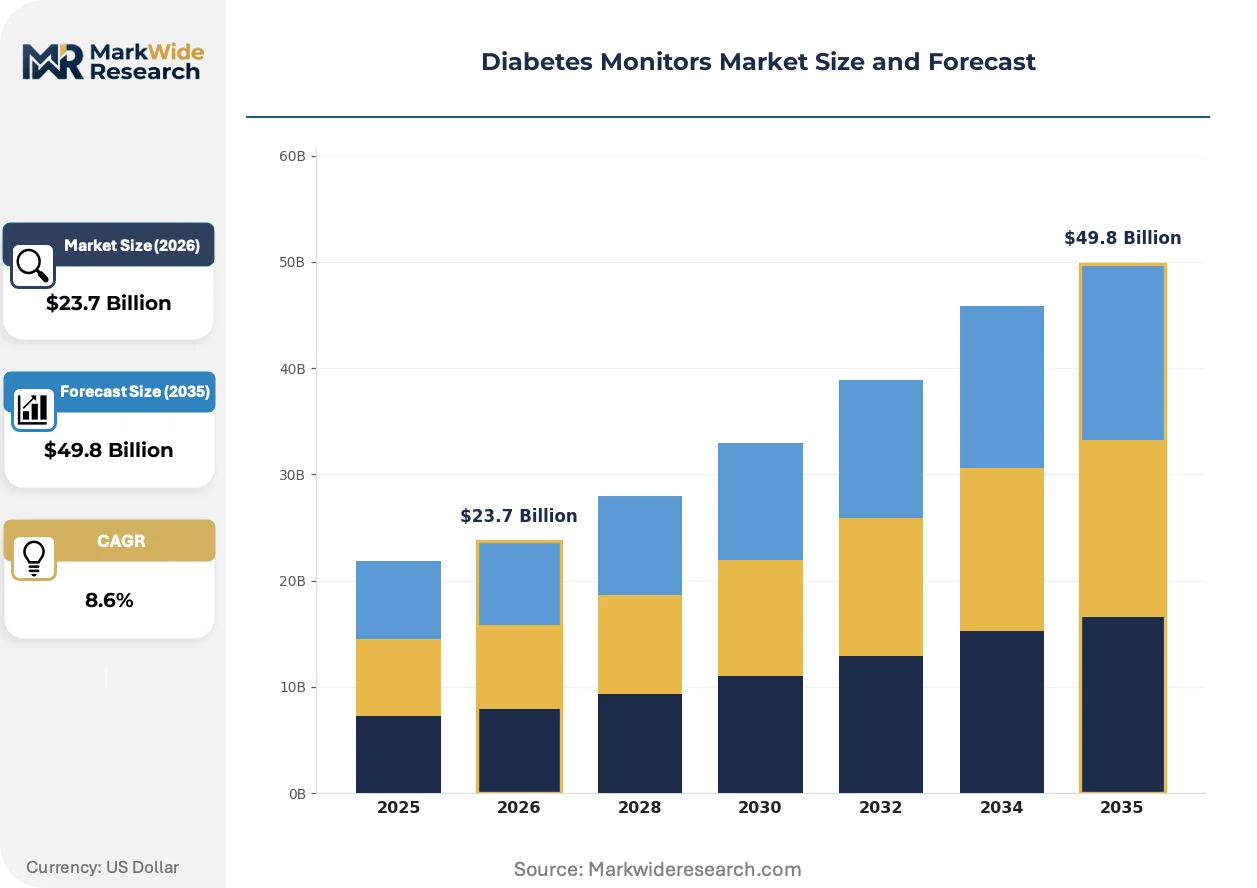
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitor, Blood Glucose Meter, Flash Glucose Monitor, Wearable Devices Technology: Self-Monitoring, Embedded Systems, Wireless Technology, Telemedicine Solutions End User: Home Care, Hospitals, Clinics, Diagnostic Laboratories Application: Personal Monitoring, Clinical Research, Diabetes Management, Health Management |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, F. Hoffmann-La Roche Ltd, Ascensia Diabetes Care Holdings AG, Lifescan, Sinocare, Senseonics Holdings, A. Menarini Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Monitors Market Emerging Trajectories
Algorithmic integration of glucose prediction with insulin delivery is compressing the gap between monitoring and therapeutic action, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements for artificial pancreas systems.
Factory-calibrated interstitial glucose sensors are unifying calibration-free operation with extended wear durations. Ambulatory patients in Germany and the Netherlands are adopting these systems at replacement rates exceeding traditional self-monitoring protocols. This unification is compressing the addressable market for blood glucose meter strips in insured populations.
Europe's MDR post-market surveillance obligations are intensifying clinical follow-up requirements for glucose monitoring manufacturers. Notified bodies under EMA coordination now demand systematic post-launch performance data that exceeds prior MEDDEV guidance. Class III continuous monitors face the steepest compliance burden, with several manufacturers restructuring quality management systems to accommodate periodic safety update reports.
Integrated delivery networks in the United States are consolidating diabetes device procurement under enterprise-wide value-based contracts. Hospital systems negotiate sensor and pump bundles that tie reimbursement to glycemic outcome metrics, displacing fragmented purchasing by individual endocrinology practices. This concentration is most visible in the Upper Midwest, where Catholic health initiatives and academic medical centers have pioneered risk-sharing arrangements with device vendors.
Diabetes Monitors Market Segmentation
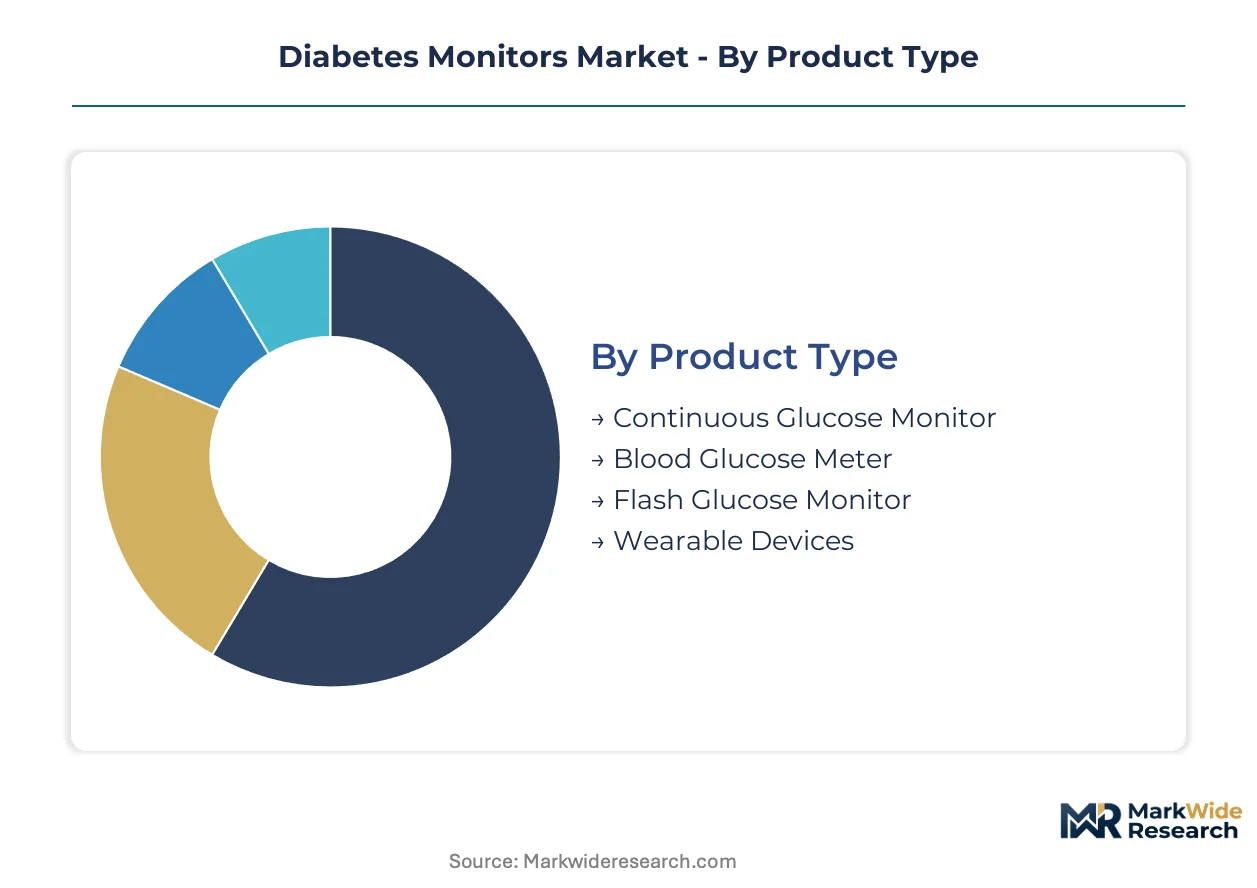
Diabetes monitor segmentation reveals divergent margin structures between high-acuity hospital systems and price-sensitive home care channels. Technology choices determine reimbursement eligibility and sensor replacement economics across patient populations.
Product Type:
Volume concentrates in legacy fingerstick devices while premium capture shifts toward sensor-based systems with recurring revenue models.
- Continuous Glucose Monitor:Interstitial fluid sensors with factory-calibrated algorithms transmit glucose readings every 1-5 minutes to receivers or smartphones. Demand clusters among Type 1 diabetes patients in Germany where statutory health insurance removed prior authorization requirements for real-time systems. Dexcom and Abbott anchor hospital procurement contracts through integrated sensor-pump bundles.
- Blood Glucose Meter:Electrochemical biosensors using glucose oxidase enzyme reactions on disposable test strips remain the installed base leader. Home care channels in India and Southeast Asia drive unit volume for affordable meters with basic Bluetooth connectivity. Platinum electrode material costs constrain manufacturer margins without captive chemical supply.
- Flash Glucose Monitor:Factory-calibrated factory sensors eliminate fingerstick calibration requirements. Pharmacy-channel distribution in the Netherlands and United Kingdom accelerates patient migration from traditional self-monitoring protocols.
- Wearable Devices:Non-invasive optical and thermal sensors target wellness-adjacent monitoring without insulin dosing claims. Consumer electronics distribution limits clinical reimbursement pathways.
Mature deployment sits with Blood Glucose Meter. Newer deployment is concentrated in Continuous Glucose Monitor.
Technology:
Connectivity architecture determines integration depth with electronic health records and remote patient monitoring platforms.
- Self-Monitoring:Patient-operated fingerstick devices with capillary blood sampling. Established reimbursement codes sustain volume in Medicare populations despite sensor competition.
- Embedded Systems:Microcontroller-based signal processing enables predictive glucose forecasting algorithms. FDA De Novo pathway requirements extend development timelines for novel algorithm submissions.
- Wireless Technology:Bluetooth Low Energy and proprietary radio protocols transmit data to insulin pumps and smartphone applications. Closed-loop artificial pancreas development attracts disproportionate R&D investment from sensor-integrated pump manufacturers.
- Telemedicine Solutions:Cloud-based glucose data aggregation supports remote therapeutic monitoring reimbursement under US Medicare. Health systems deploy these platforms for chronic care management program compliance.
Installed base dominance rests with Self-Monitoring. Steepest expansion trajectory belongs to Wireless Technology.
End User:
Procurement authority fragmentation shapes pricing power across acute care and ambulatory settings.
- Home Care:Direct-to-patient channels through retail pharmacy and durable medical equipment suppliers. Out-of-pocket cost sensitivity drives demand for flash glucose systems with simplified user interfaces.
- Hospitals:Integrated delivery networks consolidate enterprise-wide contracts under value-based glycemic outcome metrics. Upper Midwest Catholic health initiatives pioneered risk-sharing sensor procurement arrangements.
- Clinics:Endocrinology practices transition from fragmented device purchasing to health system-affiliated procurement. Reimbursement code alignment determines patient access to continuous monitor prescriptions.
- Diagnostic Laboratories:Centralized glucose testing for HbA1c and point-of-care validation. Laboratory-developed test regulations constrain direct competition with consumer monitoring devices.
Volume leadership belongs to Home Care. Margin expansion concentrates in Hospitals.
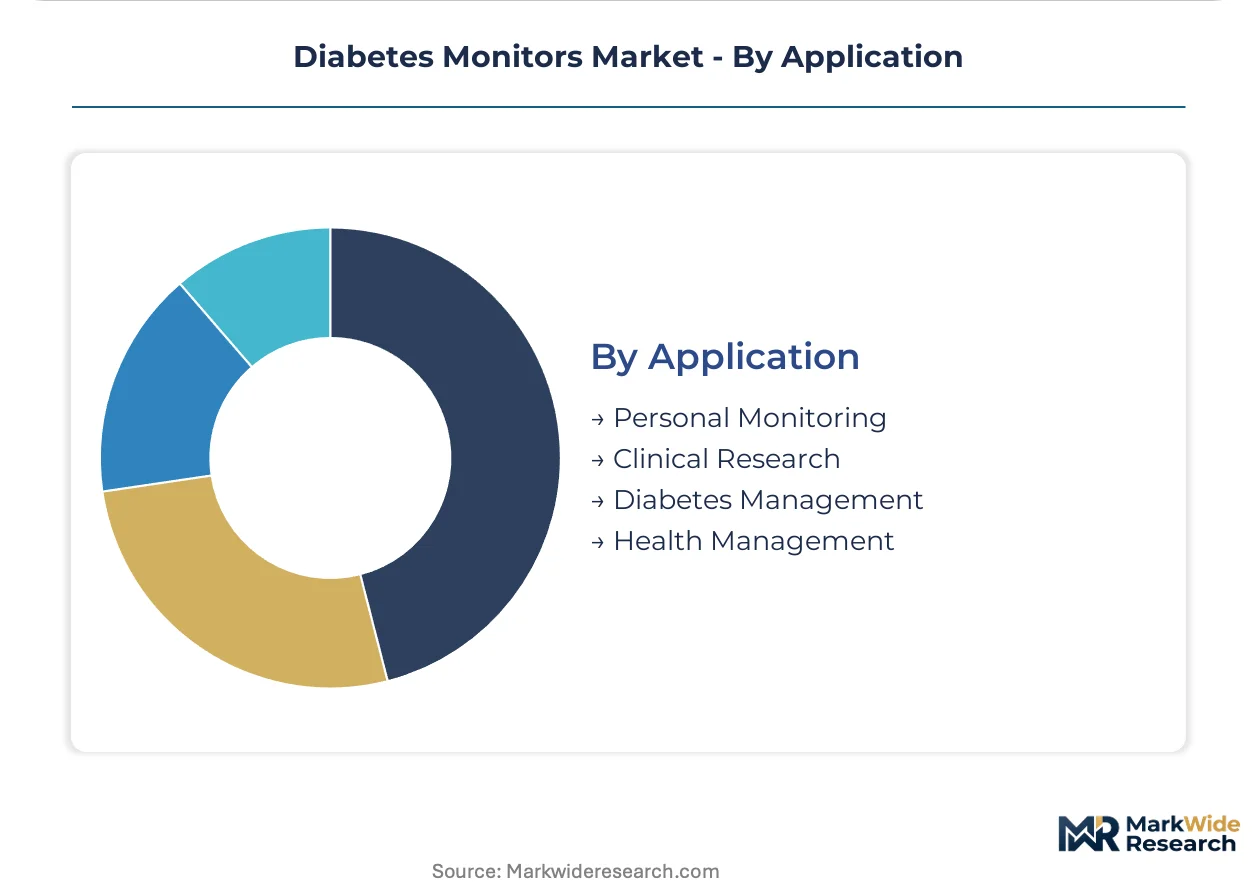
Application:
Clinical evidence requirements vary sharply between therapeutic decision support and wellness tracking use cases.
- Personal Monitoring:Individual glucose tracking for insulin dosing, dietary adjustment, and hypoglycemia prevention. Patient adherence to sensor replacement schedules determines commercial lifetime value.
- Clinical Research:Continuous glucose data collection for pharmaceutical trials and algorithm validation. FDA 510(k) predicate pathway narrowing forces more resource-intensive De Novo submissions for novel indications.
- Diabetes Management:Integrated care protocols combining monitoring with medication optimization. Germany's statutory health insurance expansion for real-time CGM accelerated patient access in this category.
- Health Management:Population-level glucose surveillance for prediabetes intervention and employer wellness programs. Limited reimbursement codes constrain commercial scale without clinical diagnosis.
Established revenue concentration sits with Diabetes Management. Emerging deployment clusters in Clinical Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where statutory health insurance reimbursement for real-time continuous glucose monitoring has expanded patient access significantly. Hospital procurement groups in the United States are consolidating purchasing decisions under value-based care contracts. Japan's aging population and reimbursement revisions are accelerating sensor adoption in ambulatory settings.
United States
Integrated delivery networks in the Upper Midwest and Catholic health initiatives are pioneering enterprise-wide sensor procurement contracts tied to glycemic outcome metrics. FDA's 510(k) and De Novo pathways govern market access, with narrowing predicate acceptance forcing more resource-intensive submissions. The Boston-Cambridge corridor anchors closed-loop artificial pancreas development through concentrated medical device R&D clusters.
Germany
Statutory health insurance removed prior authorization requirements for real-time CGM systems, accelerating sensor replacement cycles among Type 1 diabetes patients. The country's national pharmaceutical regulator, BfArM, coordinates with G-BA on health technology assessment for reimbursement eligibility. Medical device manufacturing concentrates in Baden-Württemberg and Bavaria, where sensor-integrated pump ecosystems reach insured populations through pharmacy-channel distribution.
Japan
PMDA reimbursement revisions for continuous glucose monitoring are expanding ambulatory patient access beyond hospital-bound acute care settings. METI industrial policy supports domestic sensor manufacturing capabilities through targeted medical device innovation programs. The Kanto region around Tokyo anchors pharmaceutical and device company headquarters managing diabetes care portfolios.
India
Tier-two cities present whitespace for affordable self-monitoring blood glucose meters with Bluetooth connectivity as diagnostic infrastructure expands. CDSCO medical device regulations are harmonizing with international standards to accelerate import approvals for multinational manufacturers. Manufacturing clusters in Gujarat and Maharashtra produce cost-competitive electrochemical biosensors for domestic and export markets.
United Kingdom
Pharmacy-channel distribution of flash glucose monitors is capturing patients migrating from traditional fingerstick protocols. NICE health technology assessments determine NHS reimbursement for continuous monitoring systems, constraining patient access without positive appraisal. The Oxford-Cambridge-London golden triangle anchors clinical research organizations validating glucose prediction algorithms for regulatory submission.
Diabetes Monitors Market Vendor Landscape
United States producers anchor one tier; European specialists hold differentiated positions in sensor-integrated systems. The vendor base concentrates around manufacturers with full product portfolios capable of supporting hospital procurement consolidation. Three archetypes dominate: diversified medical device conglomerates with sensor-pump ecosystems, pure-play continuous monitoring specialists with predictive algorithms, and regional self-monitoring manufacturers with cost-optimized strip production. Competitive moves center on strategic partnerships for closed-loop integration and geographic licensing to access pharmacy-channel distribution.
Within the diversified conglomerate tier, Abbott Laboratories and Medtronic exemplify integrated sensor-pump ecosystem strategies. Dexcom occupies a specialist position in real-time continuous glucose monitoring. Among European-based manufacturers, F. Hoffmann-La Roche Ltd and Ascensia Diabetes Care Holdings AG represent established diagnostic companies with glucose monitoring heritage. Chinese manufacturers including Sinocare exemplify cost-optimized production archetypes serving price-sensitive markets through scale-driven manufacturing.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| F. Hoffmann-La Roche Ltd |
| Ascensia Diabetes Care Holdings AG |
| Lifescan |
| Sinocare |
| Senseonics Holdings |
| A. Menarini Diagnostics |
| Others |
Supply Flow & Price Mechanics
Factory-calibrated sensor tiering against legacy electrochemical strips bifurcates the diabetes monitors landscape, with premium real-time systems commanding subscription-based pricing in Germany's reimbursed channels while commodity blood glucose meters compete on unit economics in India's retail pharmacies. This divergence concentrates manufacturing investment in Ireland and Malaysia for automated sensor assembly, while strip production gravitates toward cost-optimized electrochemical facilities in China and India.
Pricing Analysis
Volume concentrates in legacy fingerstick devices where platinum electrode material costs compress manufacturer margins, while margin capture shifts toward continuous glucose monitors with recurring sensor replacement revenue. Pricing stratifies across premium real-time systems with predictive algorithms, standard flash glucose monitors with factory calibration, and economy blood glucose meters for price-sensitive home care channels. Cost compression in the economy tier intensifies because Chinese manufacturers exploit scale-driven electrochemical production, though Germany's statutory health insurance reimbursement insulates premium sensor pricing from direct substitution pressure. Hospital procurement groups in the United States exhibit the least price sensitivity due to value-based glycemic outcome contracts, while uninsured populations in emerging markets drive extreme cost consciousness.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand in the Upper Midwest, while pharmacy-channel distribution serves flash glucose monitor adoption in the Netherlands and United Kingdom. Manufacturing concentrates in Ireland, Malaysia, and China for sensor assembly and electrochemical strip production. Raw material dependencies center on platinum for electrode fabrication, glucose oxidase enzymes for biosensor reactivity, and medical-grade polymers for subcutaneous membrane biocompatibility. Single-source vulnerability in glucose oxidase enzyme supply creates exposure to fermentation capacity constraints at specialty chemical producers. Distribution runs through group purchasing organizations for hospital systems and retail pharmacy chains for ambulatory patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's MDR post-market surveillance obligations have erected a cost-of-compliance barrier that favors manufacturers with established quality management systems and systematic clinical follow-up infrastructure, effectively moating compliant incumbents against undercapitalized entrants.
For Market Incumbents: Deepen sensor-pump ecosystem integration to anchor hospital procurement contracts against Abbott's FreeStyle platform dominance, while expanding captive glucose oxidase enzyme supply to buffer raw material volatility. Defensive consolidation should prioritize backward integration into biocompatible membrane manufacturing to offset talent scarcity in subcutaneous sensor design. For New Entrants and Emerging Players: Non-invasive optical sensing technologies offer a technology-first wedge into wellness-adjacent monitoring segments where clinical reimbursement constraints limit incumbent focus. India's tier-two cities present the most penetrable geography for affordable Bluetooth-enabled blood glucose meters as diagnostic infrastructure expands. A direct-to-patient pharmacy-channel go-to-market angle bypasses hospital procurement consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-integrated closed-loop specialists given FDA De Novo pathway acceleration for artificial pancreas systems. Long-term viability over a multi-year horizon favors manufacturers with demonstrated MDR compliance and established notified body relationships. Watch for Medicare remote therapeutic monitoring code expansion as an inflection signal for chronic care management platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery networks in the Upper Midwest consolidate enterprise-wide sensor procurement under glycemic outcome contracts. |
| FDA De Novo Submission | Predictive glucose forecasting algorithms require clinical validation studies that extend development timelines for novel indications. |
| CE Marking Pathway | Europe's MDR transition creates notified body bottlenecks favoring manufacturers with established quality management systems. |
| Software Companion Development | Bluetooth Low Energy connectivity enables insulin pump integration and smartphone data transmission for closed-loop systems. |
| Reimbursement Strategy | Germany's G-BA health technology assessment determines statutory health insurance eligibility for real-time CGM systems. |
Methodological Framework
Document review covered FDA 510(k) and De Novo filings, EMA MDR transition guidance, hospital procurement databases, and CMS Medicare reimbursement codes, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and endocrinology practice administrators. Secondary validation drew from BfArM reimbursement decisions, PMDA regulatory revisions, CDSCO import approval records, and NICE health technology assessments. Bottom-up sensor replacement rate modeling and top-down market sizing triangulation anchored volume and value estimates.
Historical shipment data cross-referenced against clinician panel input on prescription patterns and patient adherence behaviors across the projection horizon. Segmentation dimensions modeled include product type, connectivity architecture, end-user procurement authority, and application-specific clinical evidence requirements. CAGRs derived from algorithmic integration trends, reimbursement expansion trajectories, and hospital consolidation patterns. Forecast inputs incorporated platinum price volatility indices and notified body capacity constraints.
Several conditions sit outside the modeled scope, including speculative non-invasive spectroscopic technologies without insulin dosing clearance, regulatory harmonization outcomes between CDSCO and international standards, and unforeseen biocompatibility engineering breakthroughs. Forecasts reflect assumptions about MDR transition timelines, Medicare remote monitoring code stability, and statutory health insurance reimbursement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market