
 Global Type 2 Diabetes Treatment Market | 2026-2036
Global Type 2 Diabetes Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Type 2 Diabetes Treatment Market Foresight
Buyer concentration across hospital procurement networks is rebalancing toward specialty clinics and ambulatory care centers seeking differentiated therapy protocols. Novo Nordisk AS leverages its manufacturing scale to dominate the GLP-1 receptor agonist segment across North American and European channels. Eli Lilly and Co. sustains R&D intensity in next-generation incretin therapies. Sanofi SA anchors its position through backward integration into active pharmaceutical ingredient supply.
Type 2 diabetes treatment encompasses pharmacological interventions targeting insulin resistance and beta-cell dysfunction, with drug classes spanning small-molecule oral agents and biologic injectables formulated for sustained glycemic control. GLP-1 receptor agonists and SGLT2 inhibitors command the fastest-expanding share of the drug class landscape, while biguanides retain volume leadership as first-line oral therapy. Combination therapy protocols are displacing monotherapy in specialty clinic settings where payers reward HbA1c outcomes.
The FDA, EMA, and China's NMPA govern clinical trial endpoints, manufacturing standards, and post-market surveillance requirements that determine product access timelines across their respective jurisdictions. The FDA's Breakthrough Therapy designation accelerates review for novel mechanisms, while China's NMPA prioritizes local trial data for market authorization. Stakeholders must monitor evolving bioequivalence standards for biosimilar entry and payer formulary shifts toward outcome-based contracts.
Market Dynamics
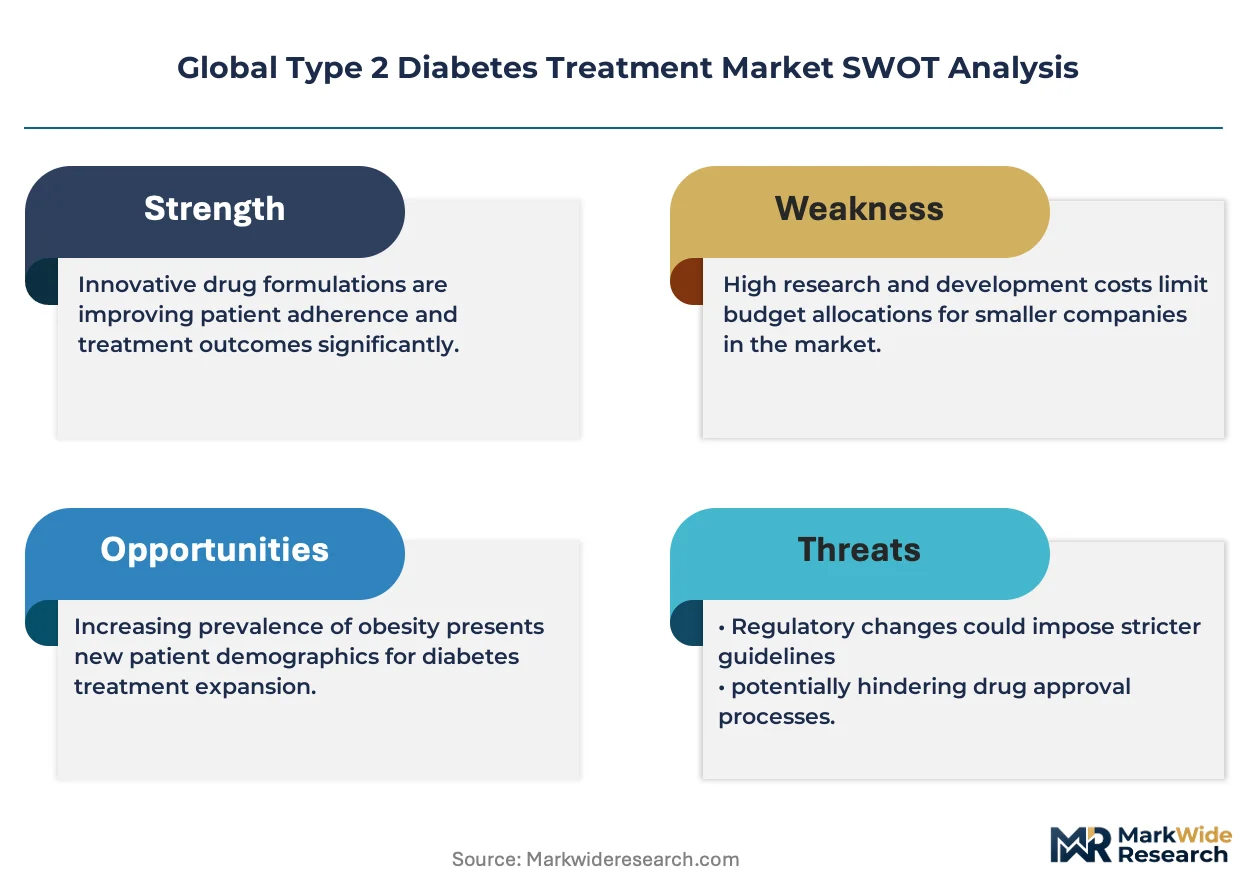
The FDA's accelerated approval pathways for novel incretin therapies are compressing development timelines and forcing incumbents to defend market position through manufacturing scale rather than patent duration alone. This regulatory velocity is redistributing competitive advantage toward biologics specialists with captive supply chains.
Growth Catalysts
- Specialty clinic expansion:Ambulatory care centers in the United States and Germany are adopting advanced injectable protocols that reward HbA1c outcomes over volume prescribing.
- EMA's PRIME designation:The European regulator's priority medicines scheme accelerates market access for novel SGLT2 inhibitor combinations targeting cardiovascular comorbidities.
- Dual-hormone agonist platforms:Next-generation molecules combining GLP-1 and GIP receptor activation are expanding the addressable patient population beyond conventional glycemic thresholds.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for biguanides concentrates in Chinese chemical manufacturing clusters, creating single-source vulnerability.
- Biosimilar entry barriers:The FDA's evolving immunogenicity standards for biologic copycats extend development timelines and elevate clinical trial costs for follow-on manufacturers.
- Oral peptide instability:Degradation in gastric environments limits bioavailability of non-injectable incretin mimetics, constraining patient preference capture.
Strategic Opportunities
- India's tier-two cities:Underpenetrated urban centers with rising diabetes prevalence present first-mover advantage for localized insulin analog production.
- Continuous glucose monitor integration:Closed-loop systems pairing real-time sensors with automated insulin delivery are opening premium pricing tiers in German and Japanese reimbursement frameworks.
- Japan's PMDA Sakigake pathway:The early approval system for regenerative medicines and innovative devices offers expedited entry for beta-cell replacement therapies.
Industry Challenges
- Biologics manufacturing talent scarcity:Purification and aseptic fill-finish expertise concentrates among a limited pool of specialists in North American and European contract manufacturing organizations.
- Cold chain integrity:Temperature excursions during last-mile distribution of GLP-1 receptor agonists degrade potency and trigger batch recalls in emerging market channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Type 2 Diabetes Treatment Market |
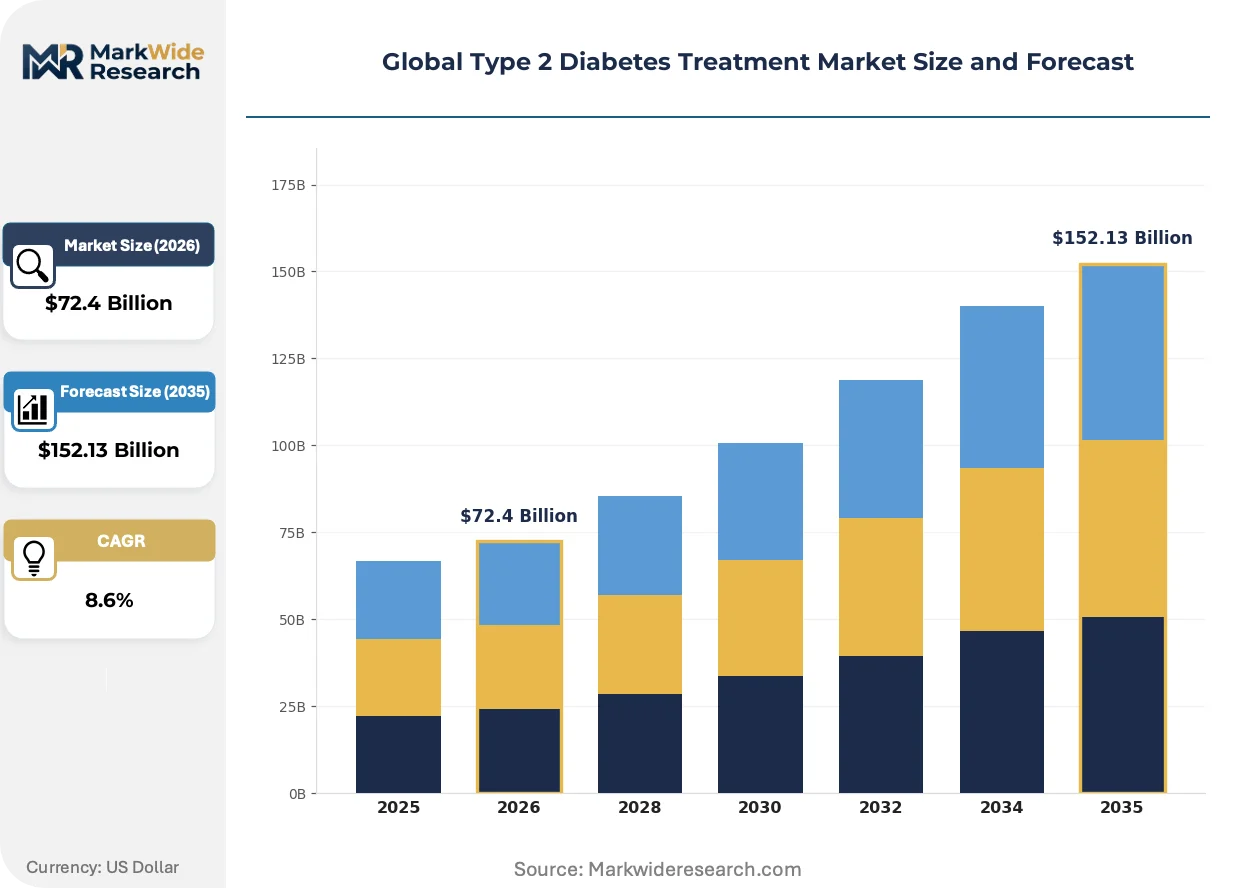
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $152.13 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Biguanides, Sulfonylureas, DPP-4 Inhibitors, GLP-1 Receptor Agonists, SGLT2 Inhibitors, Thiazolidinediones Therapy Type: Monotherapy, Combination Therapy, Insulin Therapy, Lifestyle Management End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Diagnostic Laboratories Distribution Channel: Pharmacies, Hospital Pharmacies, Online Retailers, Wholesale Distributors |
| Companies Covered | Novo Nordisk AS, Sanofi SA, Eli Lilly and Co., AstraZeneca PLC, Merck & Co. Inc, Boehringer Ingelheim International GmbH, Takeda Pharmaceutical Co. Ltd, Novartis AG, Daiichi Sankyo Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Type 2 Diabetes Treatment Market Shifts & Advancements
Injectable therapy administration is migrating from hospital infusion centers toward patient-managed settings, enabled by device miniaturization and connected health infrastructure. This shift is compressing the traditional care delivery stack and rewriting procurement hierarchies.
Dual-chamber injection devices combining lyophilized peptide with diluent are decentralizing administration authority from certified nurses to trained patients and caregivers. Specialty clinics in the United States are adopting these platforms at pace, reducing per-dose labor costs while expanding treatment access to rural geographies previously underserved by endocrinology specialists. The structural consequence is a compression of site-of-care revenue pools and a redistribution of margin toward device-drug combination manufacturers.
China's NMPA has implemented priority review pathways for innovative drugs addressing unmet medical needs, compressing regulatory review timelines from 200 to 130 days for qualifying submissions. This acceleration is pulling clinical trial investment toward domestic patient recruitment and biostatistical infrastructure. Multinational sponsors are responding by establishing standalone China development organizations with autonomous decision rights.
Hospital procurement networks are fragmenting as specialty clinics and employer-sponsored health programs negotiate direct purchasing agreements with manufacturers. This disintermediation is most visible in Germany's ambulatory care sector, where regional physician associations are consolidating purchasing volume to extract outcome-based rebates from incretin therapy suppliers. The traditional wholesaler margin is compressing as these direct channels capture preferential pricing and exclusive supply allocations.
Global Type 2 Diabetes Treatment Market Segmentation
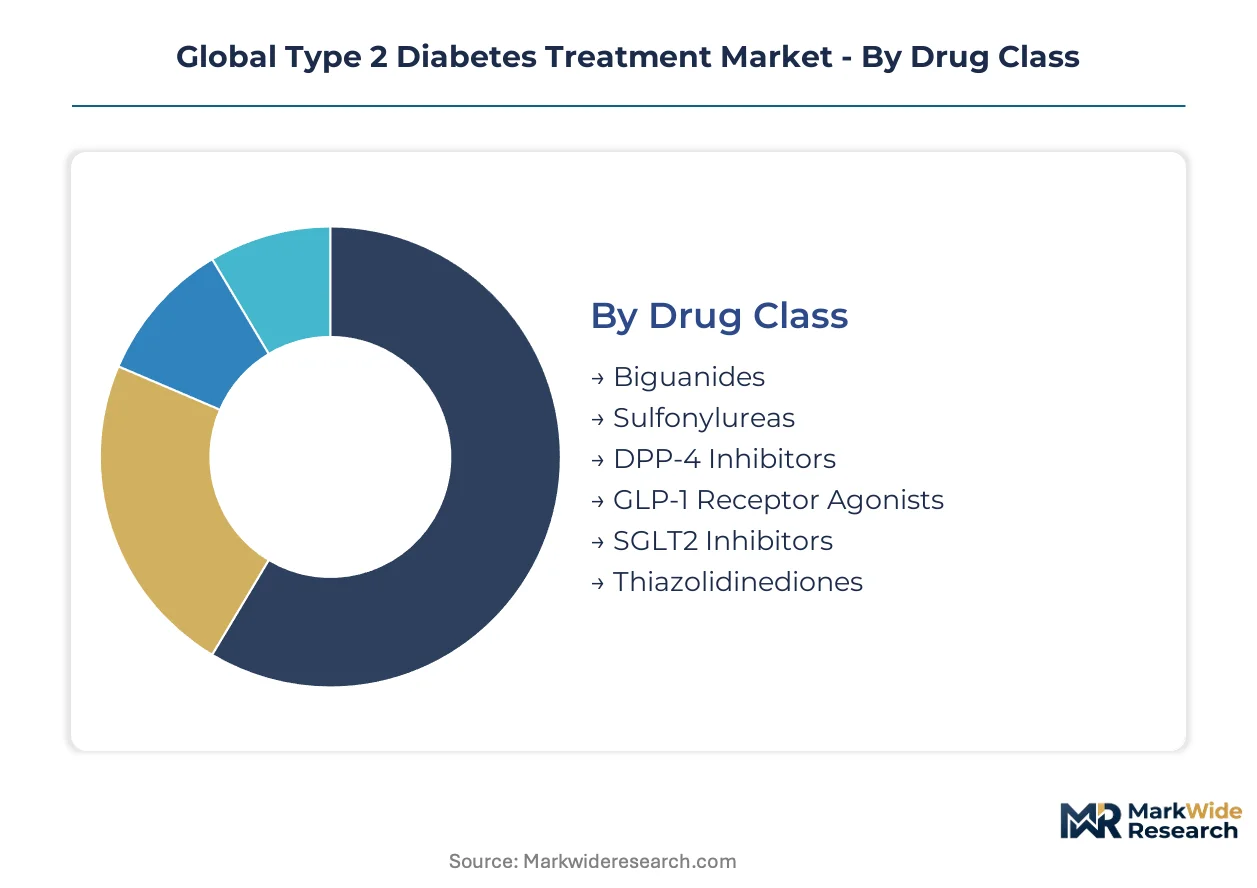
Type 2 diabetes treatment markets fragment across pharmacological mechanism, care delivery setting, and procurement pathway. Each axis carries distinct margin profiles, regulatory exposure, and competitive intensity that shape portfolio allocation decisions.
Drug Class:
Mechanism of action determines manufacturing complexity, patent exposure, and reimbursement tier across regulated markets.
- GLP-1 Receptor Agonists:Peptide-based injectables activating glucagon-like peptide-1 pathways to enhance glucose-dependent insulin secretion. Demand concentrates in United States specialty clinics where Medicare Advantage plans reward HbA1c reduction with outcome-based rebates. Cold chain requirements and biologics manufacturing expertise create supply barriers.
- SGLT2 Inhibitors:Small-molecule oral agents blocking sodium-glucose cotransporter-2 in renal tubules to promote glycosuric glucose excretion. German ambulatory networks and Japanese reimbursement frameworks prioritize cardiovascular outcome data, accelerating adoption beyond glycemic indications.
- Biguanides:Metformin-based first-line oral therapy suppressing hepatic gluconeogenesis. API production clusters in Chinese chemical manufacturing regions.
- DPP-4 Inhibitors:Oral agents prolonging incretin hormone half-life through dipeptidyl peptidase-4 inhibition. Volume leadership in India and Brazil primary care settings.
- Sulfonylureas:Pancreatic beta-cell stimulators triggering insulin release via ATP-sensitive potassium channel closure. Generic substitution dominates procurement.
- Thiazolidinediones:PPAR-gamma agonists improving peripheral insulin sensitivity. Safety surveillance requirements constrain new patient initiation.
Mature deployment sits with Biguanides. Newer deployment is concentrated in GLP-1 Receptor Agonists.
Therapy Type:
Protocol intensity reflects disease progression stage and payer willingness to fund combination regimens.
- Combination Therapy:Simultaneous administration of two or more drug classes targeting complementary metabolic pathways. United States specialty clinics and German physician associations negotiate direct purchasing agreements for fixed-dose combinations, compressing wholesaler margins. Outcome-based contracts reward HbA1c targets.
- Monotherapy:Single-agent treatment typically initiating with biguanides in newly diagnosed patients. Primary care prescribing dominates volume.
- Insulin Therapy:Exogenous insulin replacement for beta-cell failure progression. Basal-bolus protocols and analog formulations command premium tiers.
- Lifestyle Management:Dietary intervention, physical activity protocols, and weight reduction programs as adjunct or initial therapy. Digital health platforms and continuous glucose monitor integration expand addressable scope.
Volume concentration remains with Monotherapy. Margin expansion is steepest in Combination Therapy.
End User:
Site-of-care migration is redistributing procurement authority from centralized hospital networks toward distributed ambulatory settings.
- Specialty Clinics:Endocrinology-focused ambulatory centers administering advanced injectable therapies and continuous glucose monitoring. United States Medicare Advantage and German statutory health insurance reward HbA1c outcomes, accelerating adoption of GLP-1 receptor agonists and dual-hormone platforms.
- Ambulatory Care Centers:Community-based facilities delivering protocol-driven diabetes management with nurse practitioner oversight. Rural geographies previously underserved by endocrinology specialists gain access through device miniaturization.
- Hospitals:Acute care settings managing diabetic ketoacidosis, hyperosmolar crises, and perioperative glycemic control. Inpatient formularies prioritize rapid-acting insulin and intravenous protocols.
- Diagnostic Laboratories:HbA1c testing, continuous glucose monitor calibration, and biomarker surveillance supporting treatment adjustment. Integrated with pharmacy benefit management in United States commercial plans.
Procurement authority is fragmenting fastest toward Specialty Clinics. Hospital networks retain emergency and surgical volume.
Distribution Channel:
Channel selection determines cold chain integrity, patient adherence support, and rebate capture mechanics.
- Hospital Pharmacies:Captive dispensing integrated with inpatient and outpatient clinic workflows. 340B pricing programs in United States safety-net hospitals create arbitrage opportunities for specialty biologics.
- Online Retailers:Direct-to-patient platforms for chronic oral medications and glucose monitoring supplies. China's e-commerce infrastructure and United States mail-order pharmacy benefit managers expand refill adherence.
- Pharmacies:Community-based dispensing for oral antidiabetic agents and over-the-counter glucose testing. Generic substitution laws and preferred network tiers shape formulary compliance.
- Wholesale Distributors:Three-step distribution for temperature-controlled biologics and inventory financing. Margin compression accelerates as specialty clinics and employer programs negotiate direct manufacturer agreements.
Traditional wholesale concentration is eroding. Direct channel expansion is gaining share fastest in specialty biologics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production for biguanides concentrates in Chinese chemical manufacturing clusters, while GLP-1 receptor agonist demand anchors in United States specialty clinic networks. Germany and Japan maintain distinct reimbursement frameworks that accelerate adoption of cardiovascular-validated therapies.
United States
Medicare Advantage plans reward HbA1c reduction through outcome-based rebates, pulling procurement toward specialty clinics. The FDA's Breakthrough Therapy designation compresses review timelines for novel incretin mechanisms. Boston and San Francisco biotech corridors host dual-hormone agonist development programs.
Germany
Regional physician associations consolidate purchasing volume to extract rebates from incretin suppliers. The EMA's PRIME designation accelerates access for SGLT2 inhibitor combinations with cardiovascular endpoints. Baden-Württemberg's pharmaceutical manufacturing base supplies active ingredients for European formulation networks.
China
Domestic diabetes prevalence drives NMPA priority review pathways, compressing timelines from 200 to 130 days for qualifying submissions. The national pharmaceutical regulator mandates local trial data for market authorization. Yangtze River Delta biostatistical infrastructure pulls multinational clinical investment toward Shanghai and Suzhou recruitment centers.
Japan
PMDA's Sakigake pathway offers expedited entry for regenerative medicines and innovative delivery devices. Statutory health insurance prioritizes continuous glucose monitor integration with automated insulin delivery. Osaka-Kobe pharmaceutical corridor specializes in peptide formulation and aseptic fill-finish capacity.
India
Tier-two urban centers with rising diabetes prevalence present localized insulin analog production opportunities. The national pharmaceutical regulator streamlines biosimilar approvals through abbreviated pathways. Maharashtra and Gujarat chemical manufacturing clusters supply biguanide APIs to domestic formulation facilities.
Global Type 2 Diabetes Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue dual-hormone agonist platforms and oral peptide stability solutions. The vendor base stratifies across three tiers: biologics specialists with captive supply chains, small-molecule oral specialists with API backward integration, and device-drug combination manufacturers. Competitive positioning depends on manufacturing scale, regulatory velocity, and cold chain infrastructure. Incumbents defend position through capacity expansion and strategic partnerships with specialty clinic networks.
Among Danish and European pharmaceutical groups, Novo Nordisk AS and Sanofi SA exemplify biologics specialists with manufacturing scale advantages. Eli Lilly and Co. occupies a position within the next-generation incretin development tier. These three entities anchor competitive dynamics across North American and European channels, with each representing distinct strategic archetypes: peptide manufacturing dominance, API supply integration, and R&D intensity in novel mechanisms.
| Leading Market Players |
|---|
| Novo Nordisk AS |
| Sanofi SA |
| Eli Lilly and Co. |
| AstraZeneca PLC |
| Merck & Co. Inc |
| Boehringer Ingelheim International GmbH |
| Takeda Pharmaceutical Co. Ltd |
| Novartis AG |
| Daiichi Sankyo Co. Ltd |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty clinic networks in the United States and Germany are consolidating procurement volume to extract outcome-based rebates from incretin therapy suppliers, compressing traditional wholesaler margins while elevating pricing discipline for biologics manufacturers with captive cold chain infrastructure.
Pricing Analysis
Volume concentrates in generic biguanides where API oversupply from Chinese chemical clusters drives commodity-like pricing, while margin pools concentrate in GLP-1 receptor agonists where cold chain requirements and biologics manufacturing expertise create supply barriers that sustain premium tiers. Price differentiation hinges on cardiovascular outcome certification and Medicare Advantage HbA1c rebate eligibility. Pricing pressure stems from biosimilar entry barriers as the FDA's evolving immunogenicity standards extend clinical trial timelines for follow-on manufacturers. Primary care physicians in India and Brazil exhibit highest price sensitivity, while United States specialty clinics prioritize glycemic outcomes over unit cost.
Supply Chain Analysis
Freight costs for temperature-controlled GLP-1 receptor agonists escalate with last-mile distribution complexity, particularly where rural ambulatory centers lack validated cold storage infrastructure. Active pharmaceutical ingredient production for biguanides centers on Chinese Yangtze River Delta chemical manufacturing clusters, while peptide formulation and aseptic fill-finish capacity concentrates in the Osaka-Kobe corridor and North American contract manufacturing organizations. Supply chain risk manifests as single-source vulnerability for biguanide APIs and temperature excursion-driven batch recalls in emerging market channels. Distribution runs through three-step wholesale networks for hospital pharmacies, with direct manufacturer agreements gaining share fastest in specialty clinic and employer-sponsored health program channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturing scale and regulatory velocity, with the FDA's accelerated approval pathways for novel incretin mechanisms forcing subscale players toward exit or acquisition.
For Market Incumbents: Deploy backward integration into active pharmaceutical ingredient supply to defend margin position against Chinese chemical cluster volatility and biosimilar price erosion. Expand aseptic fill-finish capacity in the Osaka-Kobe pharmaceutical corridor to capture Japanese PMDA Sakigake pathway opportunities for dual-hormone agonist platforms. Secure exclusive supply agreements with Medicare Advantage-aligned specialty clinic networks before regional physician associations consolidate purchasing volume further. For New Entrants and Emerging Players: Rural ambulatory care centers in tier-two Indian cities present first-mover advantage for localized insulin analog production with abbreviated biosimilar approval pathways. Target continuous glucose monitor integration partnerships with German statutory health insurance frameworks, where closed-loop automated insulin delivery commands premium reimbursement tiers. Pursue licensing agreements with established peptide formulation specialists rather than building captive biologics manufacturing expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale DPP-4 inhibitor manufacturers with established India and Brazil primary care distribution but lacking GLP-1 receptor agonist pipeline depth, particularly those facing patent cliff pressure without cardiovascular outcome data differentiation. Long-term viability in this market rests on regulatory submission velocity and cold chain infrastructure ownership rather than molecule novelty alone. Watch for FDA Breakthrough Therapy designation announcements as inflection indicators for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive aseptic fill-finish capacity in Osaka-Kobe secures Japanese PMDA priority review eligibility. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses review timelines for novel incretin mechanisms against entrenched GLP-1 leaders. |
| Backward Integration | In-house API production for biguanides insulates margin from Chinese chemical cluster single-source vulnerability. |
| Hospital System Partnership | Direct purchasing agreements with Medicare Advantage specialty clinics capture outcome-based rebate pools. |
| Pipeline Diversification | Dual-hormone agonist platforms combining GLP-1 and GIP receptor activation expand beyond conventional glycemic thresholds. |
Research Methodology
Document review covered FDA Breakthrough Therapy designation filings, EMA PRIME scheme submissions, and NMPA priority review pathway records, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors at United States Medicare Advantage plans, and hospital procurement managers in German regional physician associations. Secondary validation drew from ClinicalTrials.gov recruitment data, CMS Medicare Part D formulary databases, and SEC 10-K manufacturing capacity disclosures. Bottom-up patient population modeling and top-down pharmaceutical spending analysis were triangulated against manufacturer-reported volume data.
Market size outputs across the projection horizon reflect segmented modeling by drug class mechanism, therapy protocol intensity, and care delivery setting, with regional regulatory clusters treated as distinct adoption curves. CAGRs were derived from longitudinal formulary placement data and payer contract value analysis. Forecast inputs incorporated NMPA review timeline compression effects, EMA cardiovascular outcome data requirements, and specialty clinic procurement network consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA immunogenicity standard evolution for biosimilars, Chinese API supply disruption scenarios, and Medicare Advantage outcome-based contract penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Europe Insulin Infusion Pumps Market