
 Diabetes Care Devices Market | 2026-2036
Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Care Devices Market Analysis
Endocrinology nurse practitioner shortages across major health systems is reorganizing how diabetes care gets delivered, pushing hospitals toward remote monitoring platforms that reduce in-person visit dependency. Abbott Laboratories leverages its vertically integrated sensor manufacturing to maintain cost discipline in continuous glucose monitor production. Medtronic anchors the insulin pump segment through decades of algorithm refinement and direct-to-patient training infrastructure. Dexcom competes aggressively on real-time data interoperability with consumer electronics ecosystems.
Diabetes care devices encompass instruments for glucose measurement, insulin delivery, and metabolic monitoring, typically incorporating electrochemical sensors, microfluidic cartridges, or subcutaneous cannulas operating within 40-400 mg/dL detection ranges, designed to reduce hyperglycemic episodes and delay microvascular complications. Blood glucose monitors retain the largest installed base among product types, though margin compression from private-label strip competition has shifted R&D budgets toward continuous glucose monitors and insulin pumps. Wearable technology and artificial intelligence within the technology segment are attracting disproportionate capital allocation as algorithm-driven predictive hypoglycemia alerts demonstrate measurable HbA1c reduction in randomized trials.
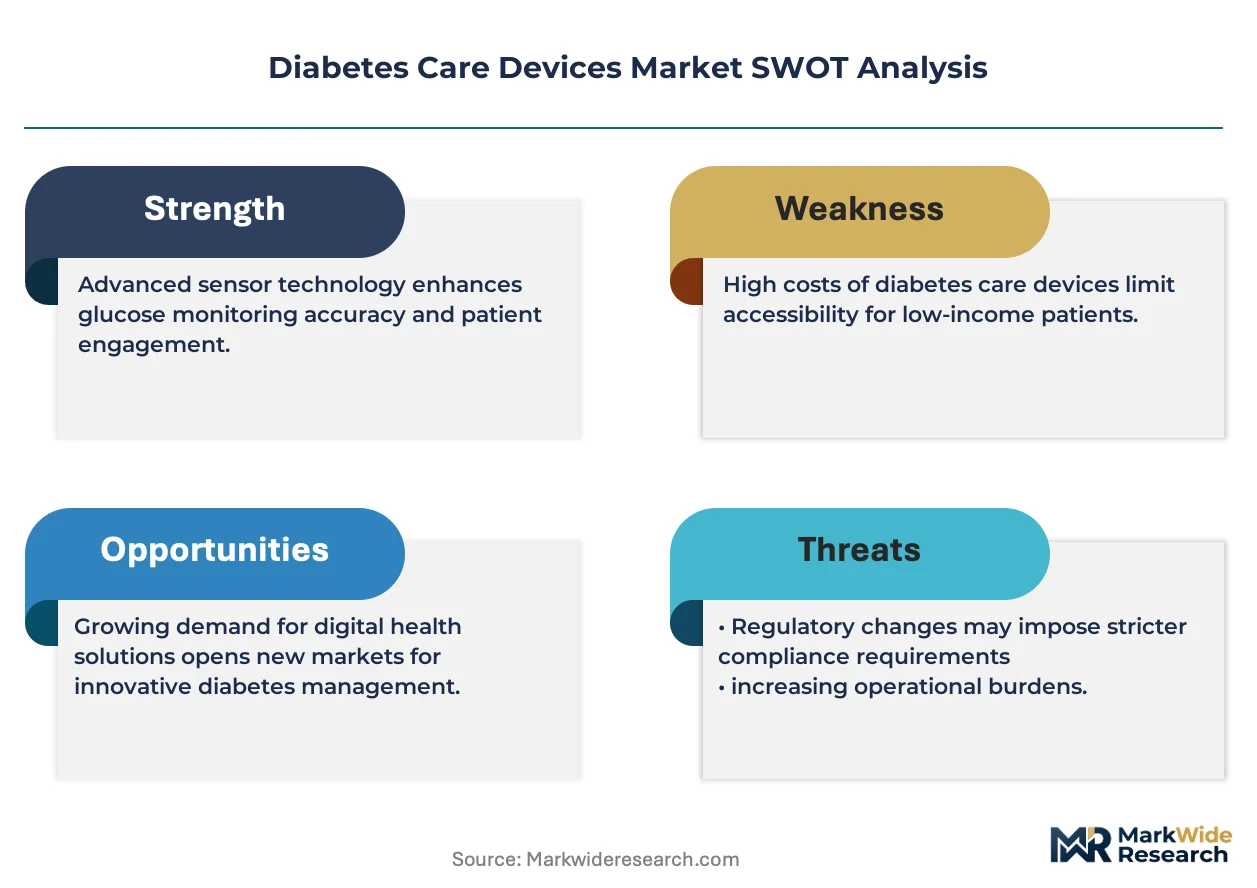
FDA premarket notification requirements and ISO 15197 accuracy standards govern glucose meter precision thresholds, while the EU MDR recertification timeline is forcing smaller manufacturers to consolidate or exit the European market entirely. CMS national coverage determinations and state-level Medicaid expansion decisions shape addressable patient populations in the United States. Stakeholders must monitor evolving interoperability mandates from the Office of the National Coordinator for Health IT, as data portability requirements threaten proprietary ecosystem lock-in strategies.
Market Dynamics
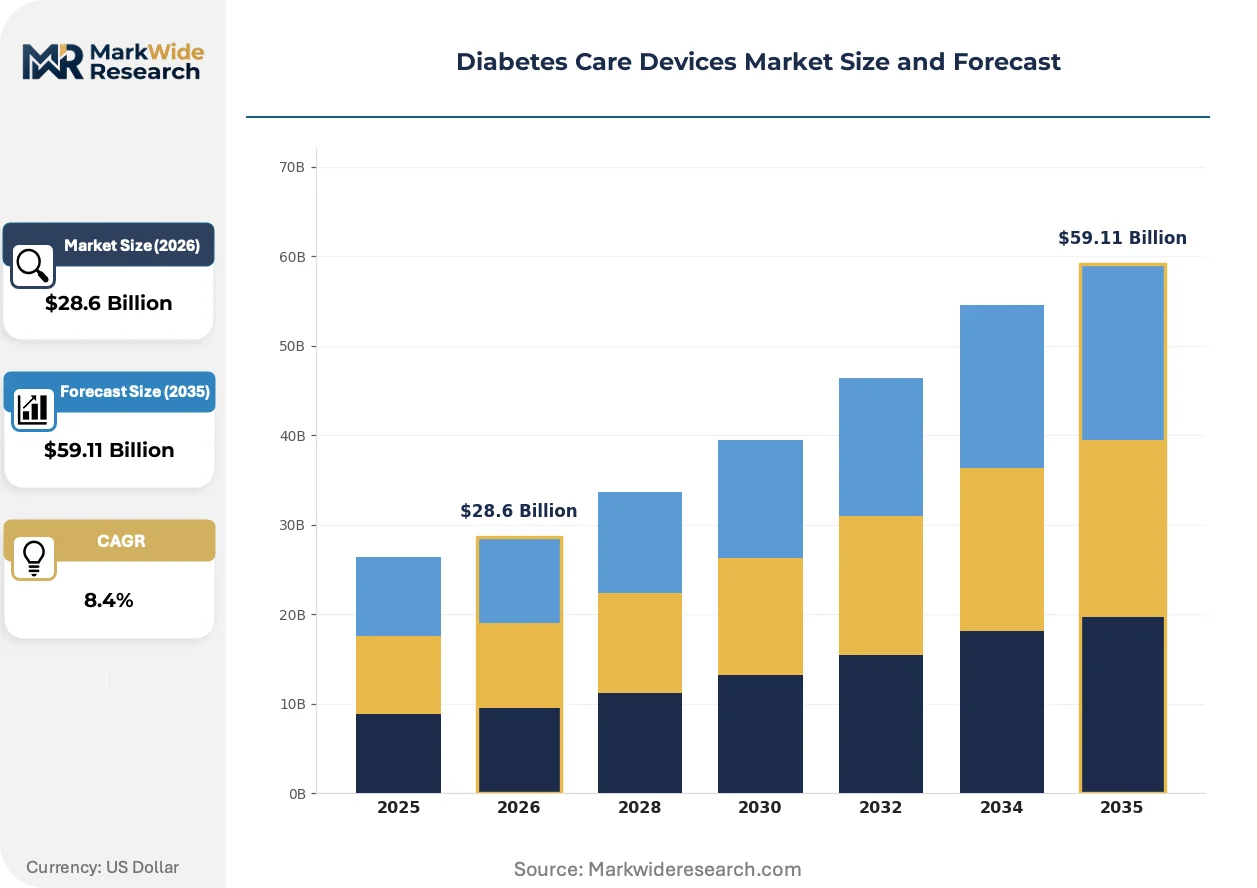
Hospital procurement of continuous glucose monitoring systems is accelerating as CMS reimbursement pathways broaden for outpatient diabetes management, compressing traditional blood glucose meter volumes while expanding real-time metabolic data capture across health systems.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement expansion for therapeutic continuous glucose monitors in type 2 diabetes management extends device access to previously excluded patient populations in the United States.
- Algorithm-driven predictive alerts:Machine learning models detecting hypoglycemic events 20-30 minutes before onset demonstrate measurable HbA1c reduction in randomized controlled trials, driving physician prescribing preference.
- Insulin pump integration:Closed-loop artificial pancreas systems combining sensor-augmented pumps with automated insulin delivery are capturing high-acuity patient segments previously managed through multiple daily injections.
Market Restraints
- Sensor manufacturing concentration:Electrochemical glucose oxidase electrode production concentrates among three specialized component suppliers, creating input bottleneck risk for downstream device assemblers.
- EU MDR recertification timeline:The European Union's Medical Device Regulation transition period expires with limited notified body capacity, forcing smaller glucose meter manufacturers to consolidate or exit the European market entirely.
- Private-label strip competition:Unbranded blood glucose test strips sold through pharmacy chains and online direct-to-consumer channels compress margins on traditional meter-strip business models.
Strategic Opportunities
- Underpenetrated type 2 non-intensive insulin users:Continuous glucose monitor adoption among basal insulin users without pump therapy remains below 15% in the United States, representing expansion white space for intermittent scanning devices.
- Interoperability mandates:The Office of the National Coordinator for Health IT's data portability requirements threaten proprietary ecosystem lock-in, creating opening for open-platform glucose data aggregators.
- Employer-sponsored chronic disease management:Self-insured corporations in the United States are expanding device subsidies as diabetes-related medical costs drive health benefit expenditure concentration.
Industry Challenges
- Endocrinology nurse practitioner shortages:Major health systems report 18-month hiring timelines for specialized diabetes educators, forcing reliance on remote monitoring platforms that reduce in-person visit dependency.
- FDA breakthrough device pathway execution:Compressed premarket review timelines for artificial pancreas systems strain regulatory affairs capacity at emerging manufacturers unfamiliar with quality system documentation requirements.
- Legacy electronic health record integration:Proprietary data formats from established continuous glucose monitor vendors create interoperability friction with Epic and Cerner deployments, delaying clinical workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Care Devices Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Insulin Pumps, Continuous Glucose Monitors, Lancet Devices Technology: Wearable Technology, Mobile Apps, Artificial Intelligence, Remote Monitoring End User: Hospitals, Clinics, Home Care Settings, Diabetes Management Centers Delivery Mode: Invasive, Non-Invasive, Continuous, Discrete |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Medtronic, Dexcom, Insulet Corporation, Novo Nordisk, Tandem Diabetes Care, Ascensia Diabetes Care, Lifescan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Care Devices Market Emerging Trajectories
Artificial intelligence and wearable form-factor miniaturization are converging to transform diabetes management from episodic glucose testing into continuous metabolic surveillance, with algorithmic prediction displacing reactive treatment protocols.
Factory-calibrated continuous glucose monitors eliminating fingerstick calibration requirements are supplanting traditional self-monitoring blood glucose systems in intensive insulin user populations. Endocrinology practices in the United States are adopting these devices at replacement rates exceeding 40% annually for new patient initiations. This technology compression is enabling remote patient monitoring reimbursement codes while reducing clinic visit frequency for stable patients.
The FDA's breakthrough device designation pathway is compressing time-to-market for closed-loop artificial pancreas systems by prioritizing review resources and enabling earlier manufacturer-investor engagement. This regulatory acceleration reduces capital requirements for premarket clinical trials through streamlined study designs. Insulin pump manufacturers with existing 510(k) clearances are most aggressively pursuing this designation for hybrid closed-loop algorithm submissions.
Self-insured employers are unbundling diabetes device procurement from traditional pharmacy benefit manager contracts, establishing direct relationships with continuous glucose monitor manufacturers for employee chronic disease management programs. This channel disintermediation bypasses formulary exclusion restrictions that previously limited device access. Large manufacturing and technology employers in the Midwestern and Southern United States are most visible in this procurement model evolution, driven by measurable reductions in emergency department utilization among enrolled employees.
Diabetes Care Devices Market Segmentation
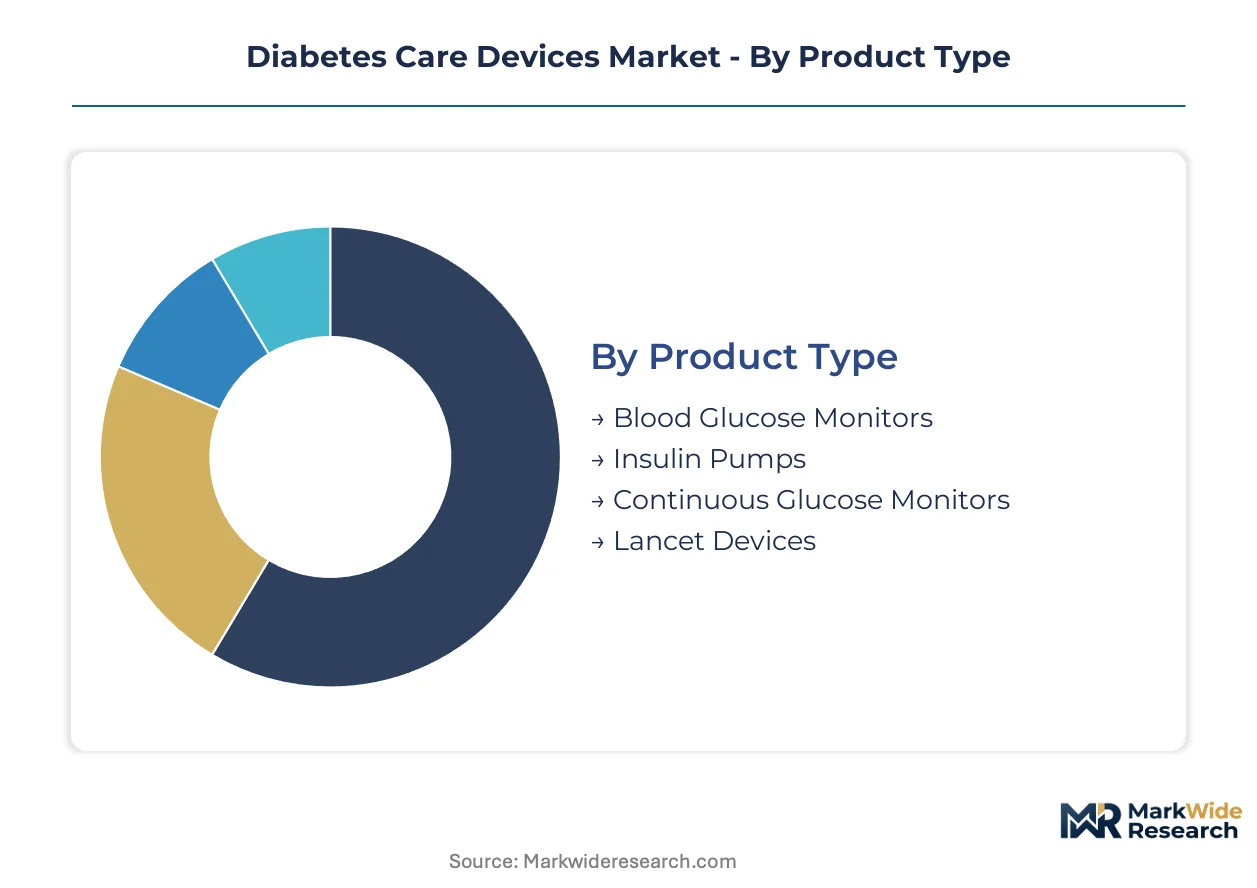
Device substitution dynamics reshape competitive boundaries across diabetes care, as continuous monitoring technologies displace episodic testing modalities and algorithm-driven systems reconfigure patient workflow economics.
Product Type:
Continuous glucose monitors exert the strongest substitution pressure on legacy blood glucose meters, compressing strip-based revenue pools while expanding sensor-augmented therapy penetration.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors operating in 40-400 mg/dL ranges eliminate fingerstick calibration requirements. Hospital procurement in the United States accelerates as CMS reimbursement pathways broaden for outpatient diabetes management, displacing traditional meter volumes in intensive insulin user populations.
- Blood Glucose Monitors:Electrochemical test strip systems with ISO 15197 accuracy compliance retain installed base dominance among non-intensive type 2 patients. Private-label strip competition through pharmacy chains compresses margins and constrains R&D reinvestment capacity for branded manufacturers.
- Insulin Pumps:Subcutaneous infusion devices with programmable basal-bolus delivery anchor algorithm-driven artificial pancreas development.
- Lancet Devices:Spring-loaded penetration instruments for capillary blood sampling face demand erosion as calibration-free sensors reduce fingerstick frequency.
Blood glucose monitors anchor the volume base while continuous glucose monitors gain share at the steepest rate.
Technology:
Capital allocation intensity concentrates in algorithmic prediction layers, where machine learning differentiation determines physician prescribing preference and reimbursement coding eligibility.
- Artificial Intelligence:Machine learning models detecting hypoglycemic events 20-30 minutes before onset demonstrate measurable HbA1c reduction in randomized controlled trials. FDA breakthrough device designation pathway prioritizes review resources for closed-loop algorithm submissions, compressing time-to-market for predictive alert systems.
- Wearable Technology:Miniaturized form-factor sensors with subcutaneous cannula deployment enable continuous metabolic surveillance without patient intervention. Real-time data interoperability with consumer electronics ecosystems drives competitive positioning among established manufacturers.
- Remote Monitoring:Cloud-connected glucose data transmission supports reimbursement-eligible virtual care delivery models.
- Mobile Apps:Smartphone-based glucose logging and insulin dose calculation face platform commoditization from operating system native health applications.
Artificial Intelligence commands premium pricing while wearable technology expands most quickly across patient demographics.
End User:
Site-of-care migration from institutional settings to distributed home environments reconfigures device procurement channels and training infrastructure requirements.
- Home Care Settings:Patient-directed glucose management with remote clinician oversight reduces in-person visit dependency amid endocrinology nurse practitioner shortages. Self-insured employers in the United States establish direct manufacturer relationships for employee chronic disease management programs, bypassing pharmacy benefit manager formulary restrictions.
- Hospitals:Inpatient glycemic control systems with electronic health record integration face interoperability friction with Epic and Cerner deployments. CMS national coverage determinations shape addressable patient populations for therapeutic continuous glucose monitor adoption.
- Clinics:Outpatient endocrinology practices drive replacement rates exceeding 40% annually for new continuous glucose monitor initiations.
- Diabetes Management Centers:Specialized educator-staffed facilities concentrate high-acuity patient onboarding for closed-loop system training.
Home care settings anchor the volume base while hospitals gain share at the steepest rate through acute-to-outpatient care pathway expansion.
Delivery Mode:
Patient preference and reimbursement coding alignment favor continuous over discrete measurement modalities, reshaping regulatory submission strategies for premarket notification pathways.
- Continuous:Uninterrupted glucose data streams with predictive algorithm overlays enable automated insulin delivery in hybrid closed-loop configurations. FDA quality system documentation requirements strain regulatory affairs capacity at emerging manufacturers pursuing 510(k) clearances for sensor-augmented pump integration.
- Non-Invasive:Optical or transdermal glucose sensing technologies seek to eliminate subcutaneous sensor insertion, though accuracy validation against ISO standards remains incomplete for commercial deployment.
- Invasive:Subcutaneous cannula or lancet-based penetration maintains clinical gold standard status for accuracy-critical dosing decisions.
- Discrete:Episodic point-in-time measurements face utilization compression as reimbursement shifts toward continuous monitoring codes.
Invasive methods anchor the volume base while continuous delivery gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States prioritizing algorithm-driven closed-loop systems while European markets emphasize MDR-compliant interoperability standards and Asian markets concentrate on cost-optimized sensor manufacturing scale.
United States
Medicare reimbursement expansion for therapeutic continuous glucose monitors and employer-sponsored chronic disease management programs drive device procurement. FDA breakthrough device designation compresses premarket review timelines for artificial pancreas systems. The Minneapolis medical device corridor anchors insulin pump algorithm development and direct-to-patient training infrastructure deployment.
Germany
Statutory health insurance coverage for continuous glucose monitoring in type 1 diabetes and rising type 2 intensive insulin user adoption expand addressable populations. EU MDR recertification requirements under notified body capacity constraints filter manufacturer market access. The Baden-Württemberg precision engineering cluster concentrates electrochemical sensor component fabrication for downstream device assemblers.
Japan
Aging demographic diabetes prevalence and reimbursement inclusion of factory-calibrated sensors accelerate continuous monitor penetration beyond traditional self-monitoring blood glucose. PMDA streamlined review pathways for wearable medical devices reduce regulatory lag for sensor-augmented pump submissions. The Kanto region around Tokyo hosts concentrated endocrinology specialist networks driving closed-loop system clinical adoption.
China
Domestic production scale-up of electrochemical glucose oxidase electrodes and NMPA accelerated review channels for innovative medical devices expand local manufacturing capacity. National essential medicines list negotiations pressure pricing for imported insulin delivery systems. The Yangtze River Delta medical device manufacturing belt concentrates sensor component supply for regional device integrators.
United Kingdom
NHS England technology appraisal decisions mandating continuous glucose monitor access for eligible type 1 patients establish procurement volume commitments. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for certain device categories. The Cambridge-Oxford-London life sciences triangle anchors algorithm development for predictive hypoglycemia alert systems.
Diabetes Care Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding algorithm-driven premium positioning and the specialist tier competing on sensor manufacturing cost discipline and regional regulatory agility. The market structure reflects decades of accumulated intellectual property in insulin delivery automation and electrochemical sensing architectures. Three strategic archetypes dominate: vertically integrated sensor-pump combinations, standalone continuous glucose monitor specialists, and diversified diagnostics conglomerates with diabetes care divisions. Competitive moves concentrate on regulatory pathway acceleration through FDA breakthrough designation pursuit and direct employer contracting bypassing traditional pharmacy benefit manager channels.
Among diversified health technology conglomerates, Abbott Laboratories and Medtronic occupy positions spanning sensor manufacturing through insulin delivery integration, while Dexcom exemplifies the standalone continuous glucose monitor specialist archetype focused on real-time data interoperability. These three entities anchor distinct competitive vectors within the market structure, with Abbott representing backward-integrated sensor cost discipline, Medtronic embodying algorithm refinement accumulated across pump generations, and Dexcom situating within consumer electronics ecosystem integration strategies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Medtronic |
| Dexcom |
| Insulet Corporation |
| Novo Nordisk |
| Tandem Diabetes Care |
| Ascensia Diabetes Care |
| Lifescan |
| Others |
Supply Flow & Price Mechanics
FDA premarket notification requirements and ISO 15197 accuracy standards gate both supply qualification and price differentiation simultaneously, creating tiered access where certification tier determines reimbursement eligibility and manufacturing scale determines unit economics across sensor and pump categories.
Pricing Analysis
Long-term offtake contracts with self-insured employers and health systems anchor pricing for continuous glucose monitors, while spot procurement through pharmacy chains compresses blood glucose meter margins. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop artificial pancreas systems from factory-calibrated sensors and private-label strip alternatives. Cost compression in the traditional meter-strip segment is intensifying because of unbranded competition through direct-to-consumer channels. Employer-sponsored chronic disease management programs exhibit lowest price sensitivity, while Medicaid expansion populations and cash-pay pharmacy customers drive hardest bargain.
Supply Chain Analysis
Inventory lead times for electrochemical glucose oxidase electrodes extend 12-18 weeks due to specialized fermentation and coating processes, constraining downstream device assembly flexibility. Component fabrication concentrates in Germany, the United States, and China, with the Baden-Württemberg precision engineering cluster and Yangtze River Delta manufacturing belt anchoring electrode supply. Raw material dependencies rest on platinum-group catalysts, medical-grade polymers, and sterile packaging films. Single-source vulnerability in enzyme supplier relationships poses structural risk. Distribution runs through group purchasing organizations for hospital systems and direct-to-patient subscription models for home care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm development talent and regulatory affairs capacity for FDA breakthrough device pathways represent scarce capabilities that constrain competitive entry and determine which manufacturers capture closed-loop system premiums.
For Market Incumbents: Compound algorithm refinement advantages through continued investment in predictive hypoglycemia alert accuracy, while securing captive supply of electrochemical sensor components to defend against input bottleneck risk from concentrated enzyme suppliers. Backward integration into glucose oxidase electrode production insulates margin structure from component cost volatility. For New Entrants and Emerging Players: Lead with interoperability-first platform architectures that aggregate glucose data across device brands, exploiting ONC data portability mandates that threaten proprietary ecosystem lock-in at established manufacturers. The underpenetrated type 2 basal insulin user segment offers most accessible entry point, with remote patient monitoring reimbursement codes enabling direct employer contracting bypassing pharmacy benefit manager formulary exclusion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed diabetes device specialists that have accumulated FDA 510(k) clearances but lack capital for artificial pancreas clinical trial execution. Long-term viability hinges on algorithm-driven differentiation rather than sensor hardware commoditization. Watch FDA breakthrough device designation grants as inflection indicator for which emerging manufacturers can compress time-to-market sufficiently to challenge integrated leaders.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compressed premarket review timelines accelerate artificial pancreas commercialization for algorithm-ready manufacturers. |
| Direct Employer Contracting | Bypassing pharmacy benefit manager channels expands continuous glucose monitor access through self-insured corporate programs. |
| Sensor Component Backward Integration | In-house electrochemical electrode production reduces dependency on three specialized external suppliers. |
| Interoperability Platform Development | ONC data portability mandates create opening for open-architecture glucose data aggregators. |
| Reimbursement Strategy Investment | CMS national coverage determination alignment determines addressable patient population scale for therapeutic device categories. |
Methodological Framework
Desk research of FDA 510(k) premarket notifications, CMS national coverage determinations, and hospital procurement databases preceded structured interviews with endocrinology nurse practitioners, biomedical engineers at integrated delivery networks, GPO contracts managers, and regulatory affairs leads at device manufacturers. Primary fieldwork with hospital purchasing committees and self-insured employer benefits directors combined with secondary validation against ISO 15197 accuracy standard documentation and EU MDR recertification filings. Bottom-up patient population sizing and top-down manufacturer revenue triangulation anchored market estimates.
Variance decomposition across product type, technology layer, end user setting, and delivery mode segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled adoption curves for continuous glucose monitors displacing traditional blood glucose meters, with insulin pump integration rates and algorithm-driven predictive alert penetration as diabetes-specific forecast inputs.
Underlying assumptions cover CMS reimbursement pathway stability and EU MDR notified body capacity recovery, with deviation risk concentrated in FDA breakthrough device pathway execution timelines and endocrinology workforce shortage persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market