
 Global Continuous Subcutaneous Insulin Infusion Market | 2026-2036
Global Continuous Subcutaneous Insulin Infusion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Subcutaneous Insulin Infusion Market Foresight
Silicone is consolidating its position as the preferred elastomer for insulin pump tubing and reservoir diaphragms, displacing older PVC formulations that raised leachability concerns. Medtronic leverages vertical integration across pump manufacturing and sensor development to sustain cost advantages in integrated closed-loop systems. Insulet Corporation anchors its competitive profile through proprietary patch-pump architecture that eliminates traditional tubing entirely. Tandem Diabetes Care differentiates via touchscreen interfaces and smartphone interoperability that appeals to digitally native patient cohorts.
Continuous subcutaneous insulin infusion denotes a method of delivering insulin through a small catheter placed under the skin, typically involving programmable basal rates and bolus dosing with precision measured in 0.025-unit increments. The apparatus serves primarily to mimic physiological pancreatic secretion patterns in insulin-dependent patients, reducing glycemic variability compared with multiple daily injection regimens. Pumps capture the dominant share of product type value owing to recurring revenue from disposable reservoirs and infusion sets, while smartphone-integrated delivery modes represent the fastest-expanding channel as FDA and EMA clearances for mobile controller applications accumulate. Type 1 diabetes retains the largest therapy area footprint, though Type 2 diabetes adoption accelerates among patients with advanced beta-cell exhaustion requiring intensive insulin regimens.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and commercial launch sequencing across manufacturers. ISO 13485 quality management standards and IEC 62304 software lifecycle requirements impose substantial compliance burdens that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EU MDR as connected pump architectures proliferate and data integrity risks intensify.
Market Dynamics
Smartphone-integrated insulin delivery architectures are compressing development cycles and forcing legacy pump manufacturers to restructure software competencies around mobile-first control interfaces.
Growth Catalysts
- Closed-loop algorithm maturation:Dual-hormone systems combining insulin and glucagon delivery are advancing through FDA breakthrough device designation pathways, expanding addressable patient populations beyond conventional pump candidates.
- Germany's DiGA fast-track:The Federal Institute for Drugs and Medical Devices accelerates reimbursement for digital diabetes applications, reducing commercialization lag for app-integrated delivery systems.
- Silicone elastomer transition:Material substitution away from plasticized PVC eliminates leachability concerns and extends reservoir shelf stability, improving supply chain reliability for disposable components.
Market Restraints
- Supply concentration in sensor substrates:Enzymatic glucose oxidase membrane production clusters among three specialized chemical suppliers, creating single-source vulnerability for integrated closed-loop systems.
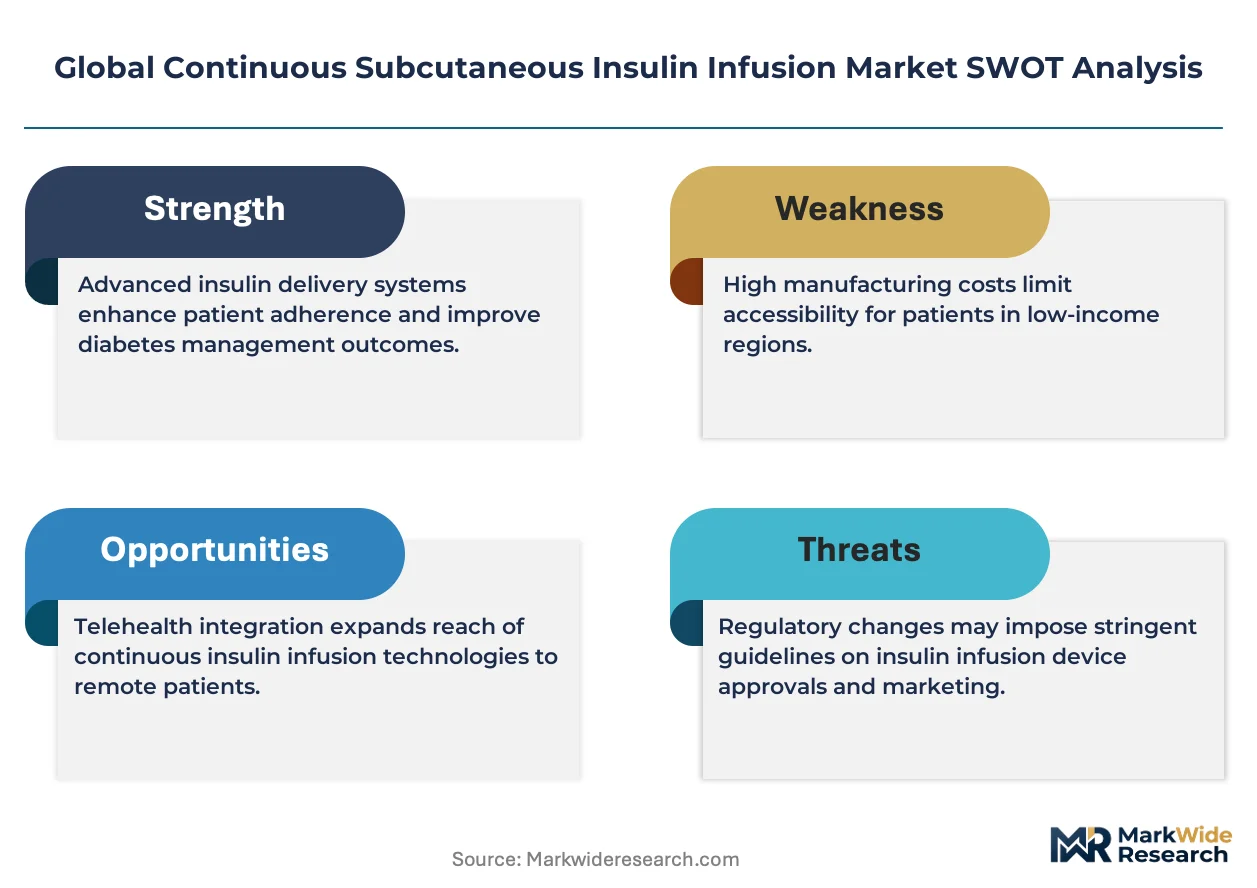
- EU MDR transition friction:Extended conformity assessment timelines for Class IIb active implantable devices delay product refresh cycles and compress revenue recognition windows.
- Multiple daily injection persistence:Pen-based basal insulin analogs with weekly dosing profiles threaten pump conversion economics in Type 2 diabetes populations with residual beta-cell function.
Strategic Opportunities
- Japan's aging diabetes burden:METI reimbursement expansion for insulin pump therapy in Type 2 patients over 65 opens a demographic segment with limited historical penetration.
- AI-enabled predictive dosing:Machine learning integration with continuous glucose monitor data streams enables proactive hypoglycemia prevention, differentiating next-generation platforms.
- Direct-to-patient subscription channels:Bypassing traditional durable medical equipment distributors captures margin and accelerates onboarding for tech-savvy patient cohorts.
Industry Challenges
- Cybersecurity engineering scarcity:FDA's 2023 guidance on premarket submission expectations for connected devices demands specialized firmware security expertise that outstrips available talent pools.
- Legacy health record interoperability:Proprietary data formats from established electronic medical record vendors obstruct seamless pump data integration into clinical workflow systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Subcutaneous Insulin Infusion Market |
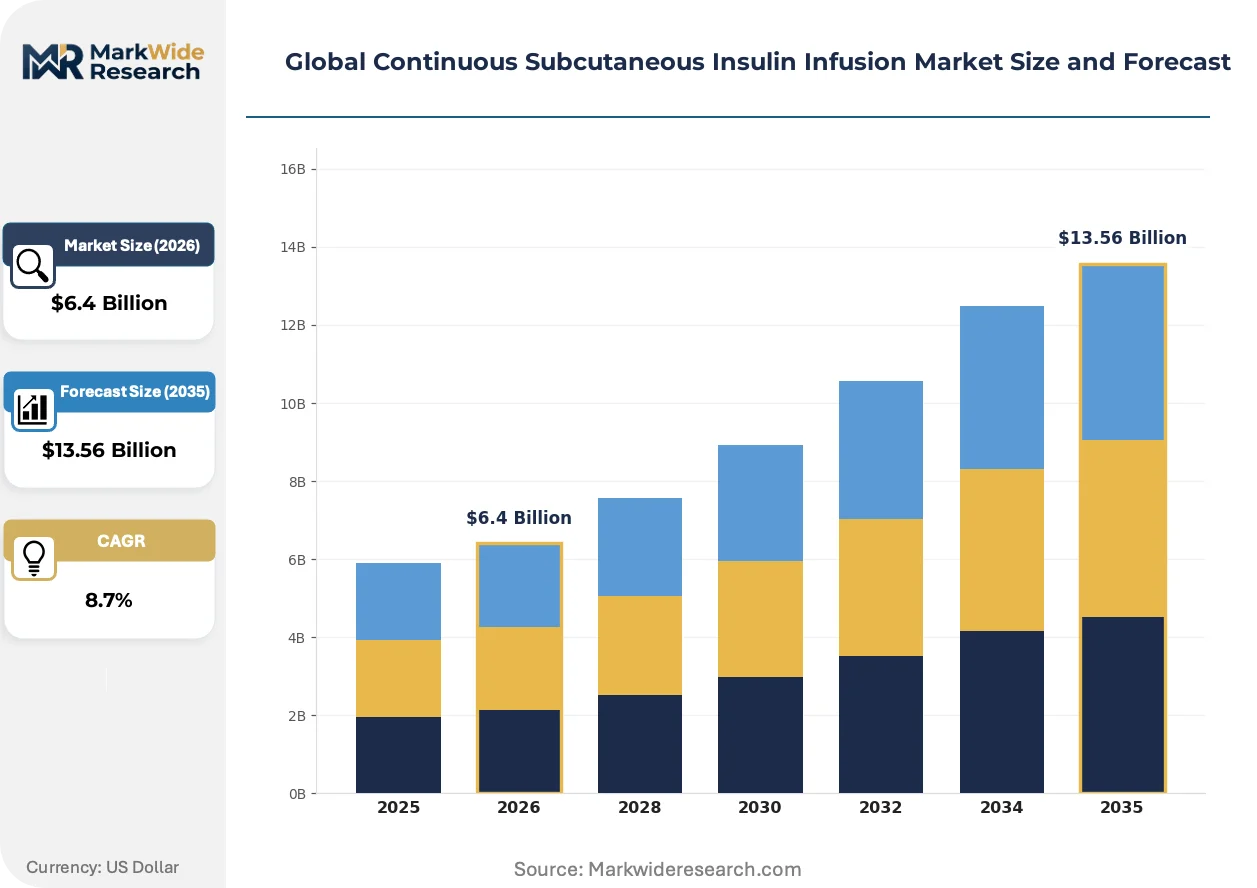
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Reservoirs, Cannulas, Infusion Sets, Controllers Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Insulin-Dependent Diabetes, Prediabetes End User: Diabetes Clinics, Endocrinology Centers, Ambulatory Care, Home Care, Specialty Pharmacies Delivery Mode: Wireless, Bluetooth Enabled, USB Connected, Smartphone Integrated, Manual |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, Hoffmann-La Roche, Ypsomed, Braun, BD (Becton, Dickinson and Company), CeQur, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Subcutaneous Insulin Infusion Market Shifts & Advancements
Convergence of continuous glucose monitoring with automated insulin delivery is eliminating manual intervention points and redefining competitive advantage around algorithm sophistication rather than hardware miniaturization alone.
Patch-pump form factors is overtaking traditional tethered pump designs in new patient acquisition. Adolescents and young adults with Type 1 diabetes in the United States and Germany are selecting tubeless systems at rates that now exceed conventional pump starts. This shift is compressing market position for manufacturers without proprietary wearable architectures.
EMA's expanded guidance on software as a medical device under EU MDR is forcing recertification of mobile controller applications previously cleared as accessory devices. Manufacturers must now submit standalone technical documentation for smartphone apps that adjust insulin delivery parameters. This regulatory elevation most affects mid-tier competitors lacking dedicated regulatory affairs infrastructure in Brussels.
Patient data ownership preferences are disrupting traditional device-centric business models. Individuals with diabetes in Japan and Germany increasingly demand portable health records that migrate across pump brands and enable third-party algorithm development. This behavioral shift pressures proprietary data silos and creates opening for open-architecture platforms that prioritize interoperability over ecosystem lock-in.
Global Continuous Subcutaneous Insulin Infusion Market Segmentation
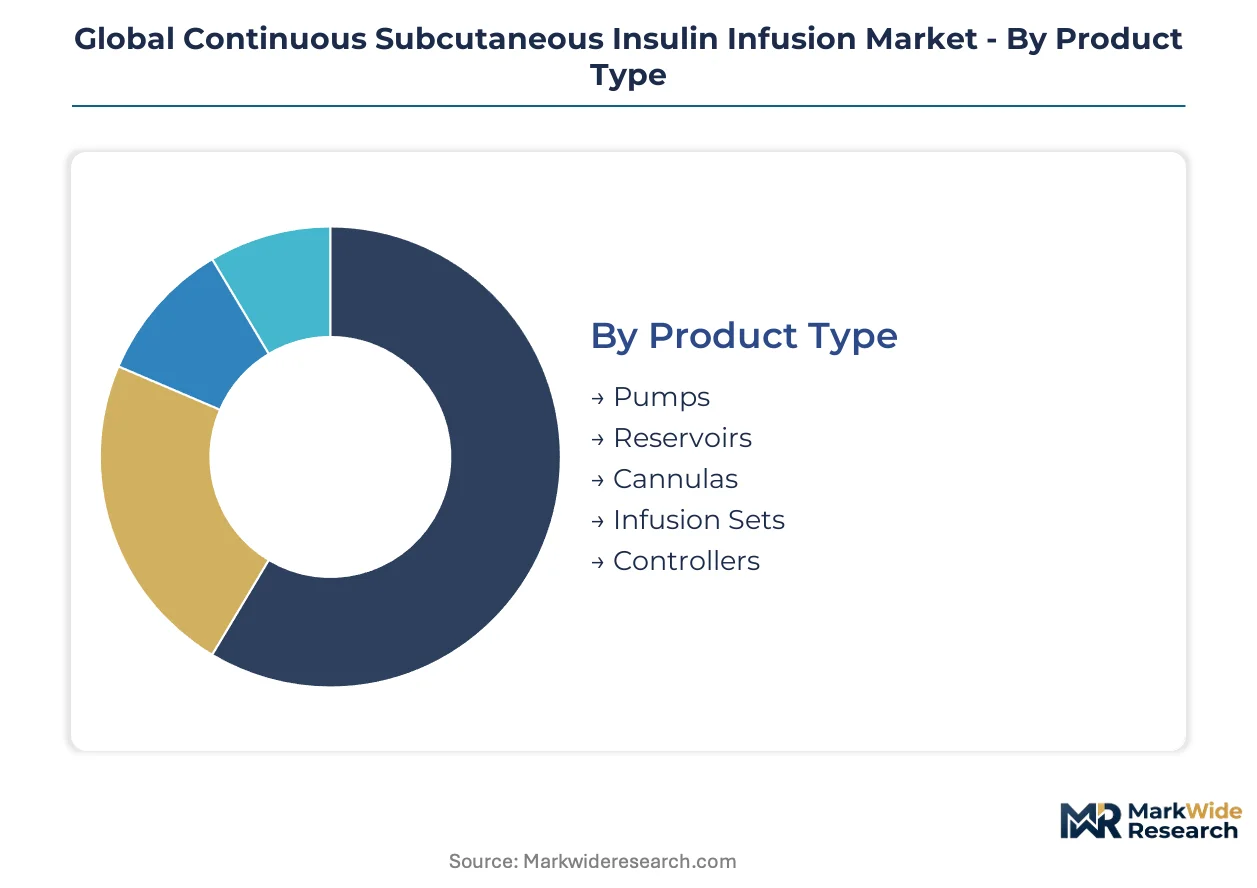
Segmentation in insulin infusion markets reveals where technology investments concentrate and which patient workflows drive procurement decisions. Manufacturers calibrate R&D spending across hardware, connectivity, and disposable components based on distinct margin profiles and replacement cycle dynamics.
Product Type:
Customization intensity varies sharply across this category, from patient-programmable devices to standardized single-use consumables.
- Pumps:Programmable basal-bolus delivery systems with precision increments of 0.025 units. Demand clusters in Germany and the United States where reimbursement frameworks cover advanced closed-loop configurations. Hardware refresh cycles extend 4-7 years, creating recurring revenue pressure.
- Reservoirs:Disposable insulin storage chambers, typically 1.8-3.0 mL capacity, constructed from silicone elastomer or specialized polymer formulations. Japan's METI reimbursement expansion accelerates volume consumption as pump adoption broadens beyond Type 1 populations.
- Cannulas:Subcutaneous insertion devices in steel or Teflon variants, with 90-degree and angled configurations for varying tissue depth.
- Infusion Sets:Complete tubing assemblies connecting reservoir to cannula, replaced every 2-3 days under clinical protocols.
- Controllers:Dedicated handheld or smartphone-linked devices adjusting delivery parameters, subject to IEC 62304 software lifecycle compliance.
Most installed capacity flows through Pumps. Expansion is steepest in Smartphone Integrated controllers.
Therapy Area:
Volume concentration versus margin opportunity splits this category between established insulin-dependent populations and emerging indications.
- Type 1 Diabetes:Absolute insulin deficiency requiring exogenous replacement through physiological secretion mimicking. Germany, the United States, and Japan dominate addressable volume, with pediatric and adolescent populations driving early pump adoption.
- Type 2 Diabetes:Progressive beta-cell exhaustion in advanced disease stages creating intensive insulin requirements. METI reimbursement expansion for patients over 65 unlocks Japan's historically underpenetrated demographic segment.
- Gestational Diabetes:Temporary insulin requirements during pregnancy with strict glycemic targets.
- Insulin-Dependent Diabetes:Broad classification encompassing all etiologies requiring exogenous insulin.
- Prediabetes:Preliminary glucose dysregulation, rarely indicating pump therapy under current protocols.
Type 1 Diabetes retains the dominant revenue share. Type 2 Diabetes is climbing the fastest as beta-cell failure timelines compress.
End User:
Channel economics diverge between reimbursed clinical settings and direct-to-patient subscription models.
- Diabetes Clinics:Specialized outpatient facilities managing complex insulin regimens and pump initiation protocols. Germany's DiGA fast-track accelerates digital application integration within these settings.
- Endocrinology Centers:Academic and tertiary referral hubs handling closed-loop algorithm optimization and dual-hormone system trials.
- Ambulatory Care:General medical settings with limited pump management expertise.
- Home Care:Patient-directed self-management environments where smartphone-integrated delivery modes reshape adherence patterns. Direct-to-patient subscription channels bypass traditional durable medical equipment distributors in the United States.
- Specialty Pharmacies:Insulin and supply fulfillment with adherence monitoring services.
Home Care channels capture margin expansion. Diabetes Clinics maintain the steepest patient onboarding velocity.
Delivery Mode:
Connectivity sophistication determines regulatory pathway complexity and cybersecurity engineering requirements.
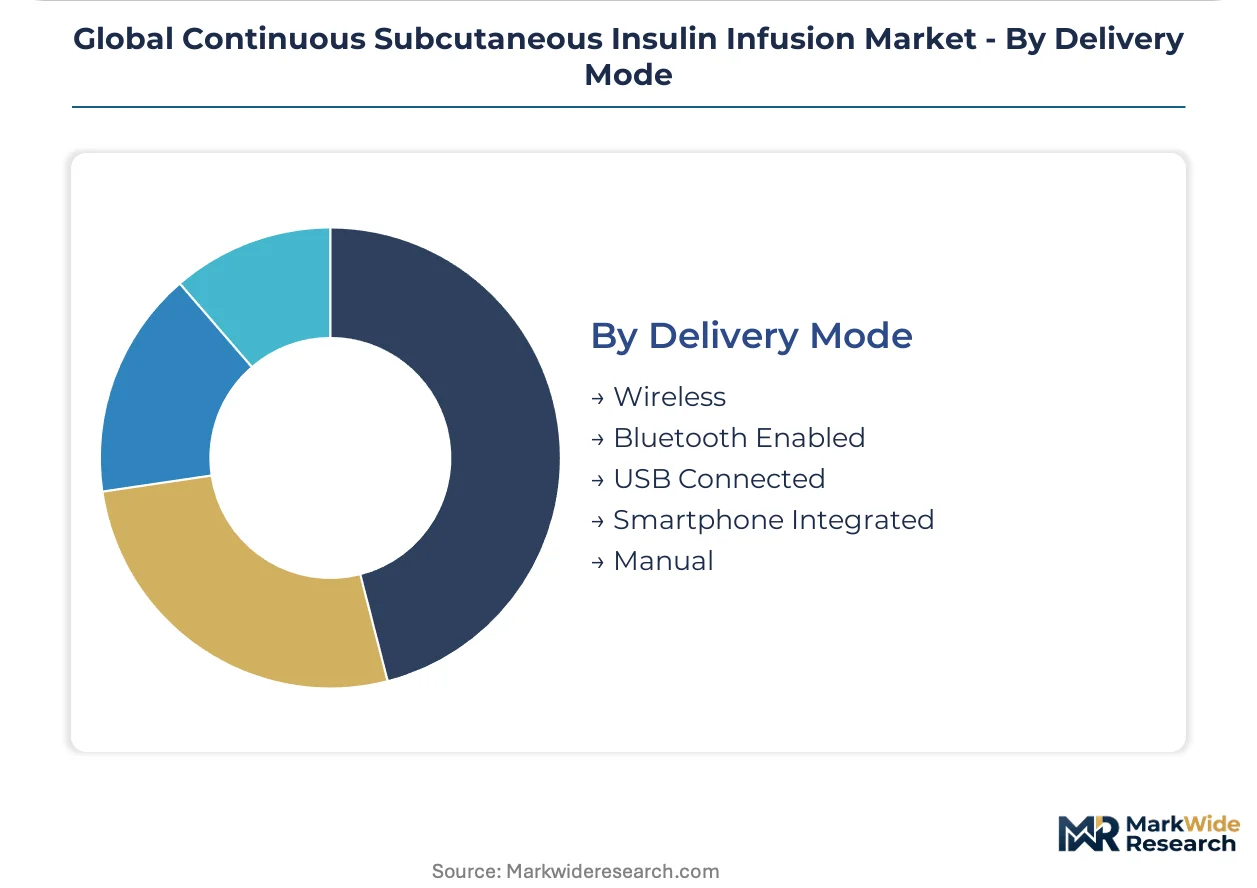
- Smartphone Integrated:Mobile controller applications enabling remote dose adjustment and data visualization. FDA and EMA clearances accumulate as software as medical device frameworks mature, though EMA's expanded EU MDR guidance forces recertification of previously accessory-classified apps.
- Bluetooth Enabled:Short-range wireless pairing with continuous glucose monitors and dedicated controllers.
- Wireless:Broad radio-frequency communication protocols for pump-to-sensor integration.
- USB Connected:Physical data transfer and charging interfaces, declining in new product architectures.
- Manual:On-device button interfaces without external connectivity, retaining relevance in cybersecurity-sensitive environments.
Smartphone Integrated systems command R&D prioritization. Bluetooth Enabled platforms sustain the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors insulin pump manufacturing through Medtronic's operational base, while regulatory clearances from FDA and EMA concentrate commercial launch sequencing in the United States and Germany. Reimbursement frameworks in these markets determine adoption velocity for closed-loop configurations.
United States
Endocrinology centers in Boston and San Francisco drive algorithm development for dual-hormone systems. FDA breakthrough device designations accelerate commercialization timelines for integrated closed-loop platforms. The direct-to-patient subscription channel captures margin expansion as durable medical equipment distributors face displacement.
Germany
Diabetes clinics in Munich and Heidelberg optimize digital application integration under BfArM's DiGA fast-track pathway. The Federal Institute for Drugs and Medical Devices compresses reimbursement lag for smartphone-integrated delivery modes. Bavaria's medical technology cluster sustains manufacturing scale for precision pump components.
Japan
METI reimbursement expansion targets patients over 65 with Type 2 diabetes in Tokyo and Osaka metropolitan areas. PMDA regulatory frameworks align with international standards for software as medical device classifications. The Kansai region concentrates sensor substrate supply relationships for integrated systems.
Switzerland
Ypsomed's operational presence in Burgdorf anchors European reservoir and infusion set manufacturing. Swissmedic conformity assessments run parallel to EU MDR timelines for Class IIb active devices. The Basel-Zurich corridor sustains specialized chemical supply for enzymatic glucose oxidase membranes.
Global Continuous Subcutaneous Insulin Infusion Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance infrastructure and closed-loop algorithm sophistication. The vendor base clusters around three strategic tiers: vertically integrated systems specialists, patch-pump architecture innovators, and disposable component manufacturers. Consolidation pressures intensify as smartphone interoperability becomes table stakes. Dominant competitive moves include backward integration into sensor substrates and geographic expansion through reimbursement pathway optimization.
Within the integrated systems tier, Medtronic exemplifies vertical control across pump manufacturing and continuous glucose monitoring development. Insulet Corporation occupies a distinctive position through tubeless patch-pump architectures that eliminate traditional infusion sets entirely. Tandem Diabetes Care represents the smartphone-native cohort, anchoring competitive differentiation around touchscreen interfaces and mobile controller applications.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| Hoffmann-La Roche |
| Ypsomed |
| Braun |
| BD (Becton, Dickinson and Company) |
| CeQur |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
EU MDR conformity assessment timelines and FDA cybersecurity guidance gates qualified supply access and premium-tier pricing power for closed-loop insulin pump systems. Manufacturers bearing these compliance burdens capture pricing premiums while mid-tier competitors face margin compression from extended certification cycles.
Pricing Analysis
Input-cost pass-through from enzymatic glucose oxidase membranes and silicone elastomer formulations sustains premium pricing for integrated closed-loop configurations. Three-tier pricing structure across premium, standard, and economy levels separates algorithm-enabled systems from basic programmable pumps and entry-level patch devices. Cost compression in standard-tier hardware intensifies as pen-based basal analogs with weekly dosing profiles threaten pump conversion economics. Hospital purchasing committees demonstrate highest price sensitivity, while direct-to-patient subscription channels in the United States exhibit lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Freight cost volatility from Swiss reservoir manufacturing to German diabetes clinics and Japanese metropolitan distribution centers elevates landed costs for disposable components. Supply concentrates in Switzerland for precision pump components, the United States for sensor substrate development, and Japan for enzymatic membrane chemistry. Raw material dependencies center on silicone elastomers, glucose oxidase biocatalysts, and specialized polymer tubing. Single-source vulnerability in enzymatic membrane production creates supply chain risk. Distribution runs through durable medical equipment channels in the United States and direct-to-patient subscriptions in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Continuous Subcutaneous Insulin Infusion Market functions as a geographic-arbitrage play where METI reimbursement expansion in Japan offers faster commercialization timelines than EU MDR transition friction in Europe.
For Market Incumbents: Hedge algorithm differentiation against patch-pump architecture displacement by acquiring proprietary wearable form factors or licensing tubeless technology. Backward integration into sensor substrates reduces single-source vulnerability from concentrated enzymatic membrane suppliers. Prioritize FDA breakthrough device designation pathways for dual-hormone systems before EU MDR recertification burdens escalate.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in smartphone-integrated controllers creates white-space opportunity for mid-tier competitors lacking dedicated Brussels regulatory infrastructure. Target Type 2 diabetes patients over 65 in Japan where METI reimbursement expansion unlocks historically underpenetrated volume. Pursue DiGA fast-track alignment in Germany for digital application integration that accelerates reimbursement lag compression.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier pump manufacturers with proprietary patch-pump architectures because smartphone interoperability requirements are compressing standalone hardware valuations. Long-term viability hinges on algorithm sophistication rather than device miniaturization alone. Watch FDA cybersecurity guidance enforcement intensity as inflection indicator for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for dual-hormone closed-loop systems in Boston and San Francisco endocrinology centers. |
| EU MDR Recertification Investment | Preserves market access for smartphone controller applications elevated to standalone medical device classification under EMA guidance. |
| Sensor Substrate Backward Integration | Captures margin from enzymatic glucose oxidase membrane production concentrated among three specialized chemical suppliers. |
| DiGA Fast-Track Alignment | Compresses reimbursement lag for app-integrated delivery systems in Munich and Heidelberg diabetes clinics. |
| Direct-to-Patient Subscription Launch | Bypasses durable medical equipment distributor margin capture in United States home care channels. |
Research Methodology
Coverage spans the United States, Germany, Japan, and Switzerland, with primary inputs from each region combining structured interviews with regulatory affairs leads, biomedical engineers, hospital purchasing committees, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, EMA submission databases, METI reimbursement bulletins, and hospital procurement records. Bottom-up patient population modeling and top-down manufacturer revenue triangulation cross-check volume and value estimates.
Rate-of-change decomposition separates basal-bolus therapy penetration from closed-loop algorithm adoption across the analysis window. Segmentation dimensions include product type hardware hierarchy, therapy area beta-cell exhaustion stages, end-user channel economics, and delivery mode connectivity sophistication. CAGRs derive from installed base replacement cycles, reimbursement pathway velocity differentials, and patient demographic shift projections. Industry-specific inputs incorporate insulin pump prescription data from CMS Medicare and Japan's National Health Insurance claims.
Caveats apply where EU MDR transition delays, FDA cybersecurity enforcement intensity, or glucagon formulation supply disruptions could materially shift the outlook. Forecasts reflect assumptions about reimbursement expansion continuity and algorithm regulatory clearance trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Malaysia Diabetes Care Devices Market