
 Philippines Oral Anti-Diabetic Drug Market | 2026-2036
Philippines Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Oral Anti-Diabetic Drug Market Insights
Aftermarket patient support programs is rewriting how pharmaceutical margins accumulate beyond the initial prescription. Sanofi leverages its chronic disease management infrastructure to sustain loyalty among endocrinology clinics. Novo Nordisk anchors its position through specialized diabetes educator networks that extend reach into provincial health facilities.
Oral anti-diabetic drugs comprise synthetic or semi-synthetic pharmaceutical agents administered perorally to lower blood glucose through mechanisms including hepatic glucose suppression, insulin secretion enhancement, or renal glucose excretion inhibition, formulated as immediate-release tablets, film-coated capsules, or osmotic pump-based extended-release matrices designed for chronic daily administration. The Philippines Oral Anti-Diabetic Drug Market segments across product types where SGLT2 inhibitors command premium positioning due to cardiovascular outcome benefits, while metformin occupies the volume base as the first-line generic standard. Delivery mode differentiation concentrates in extended-release formulations that reduce pill burden and improve adherence metrics in multi-morbid patient populations.
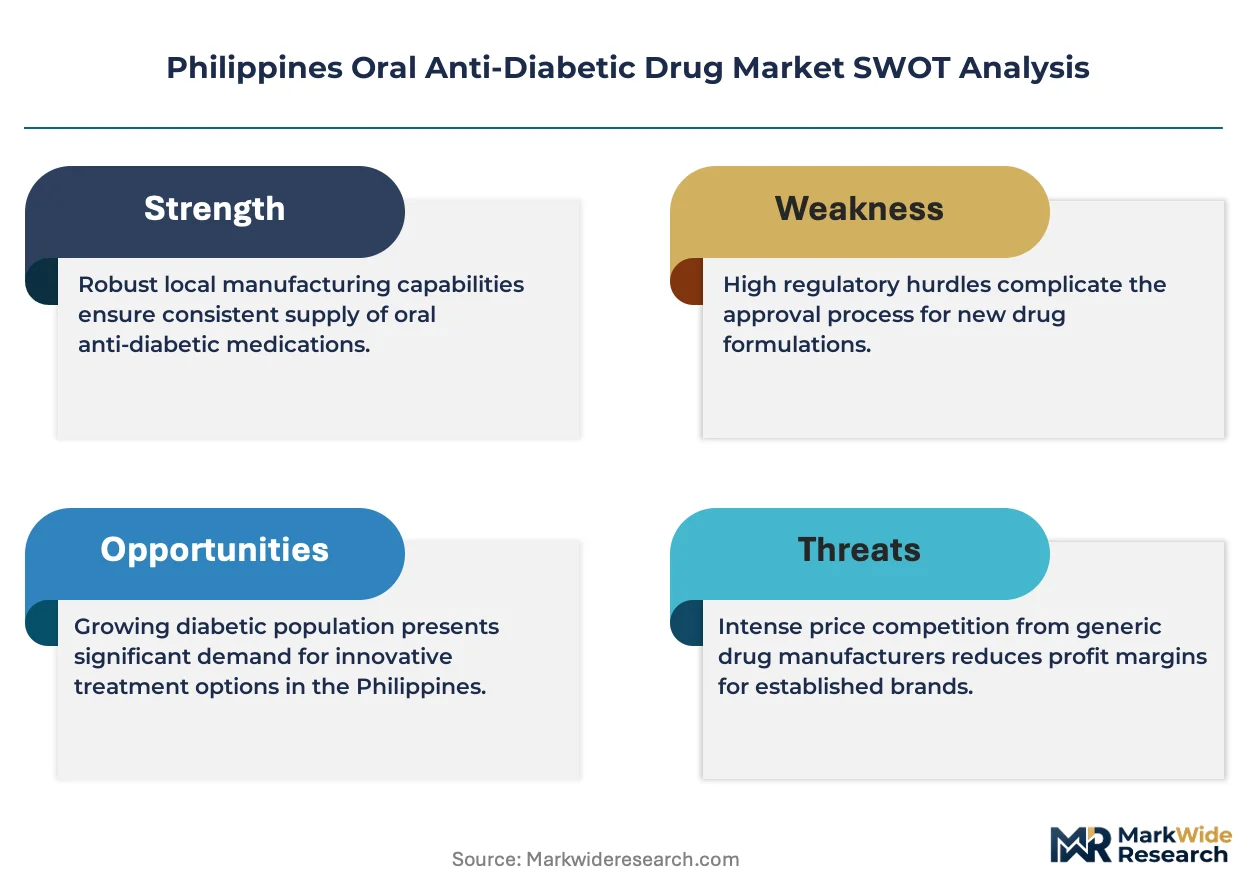
The FDA Philippines regulates product registration and post-market surveillance for all oral hypoglycemic agents, while the Department of Health's Philippine National Formulary determines which molecules receive public sector procurement priority. PhilHealth's outpatient benefit packages for chronic conditions shape demand concentration toward formulary-listed molecules with established reimbursement codes. Stakeholders must monitor how the FDA's biosimilar and generic interchangeability guidelines will reshape competitive dynamics between originator brands and local manufacturers.
Market Dynamics
PhilHealth's outpatient benefit packages are concentrating demand toward formulary-listed molecules with established reimbursement codes, compressing physician prescribing autonomy and reshaping procurement patterns across Metro Manila's tertiary hospital networks.
Growth Catalysts
- PhilHealth Outpatient Benefit Expansion:The national health insurer's chronic disease packages broaden patient access to maintenance medications, pulling volume into public sector channels.
- SGLT2 Cardiovascular Outcome Data:Cardiologists in Philippine Heart Center networks increasingly co-prescribe these agents alongside standard glucose-lowering therapy.
- Provincial Health Facility Upgrades:Central Visayas regional health system investments extend specialist endocrinology reach beyond Metro Manila's concentration.
Market Restraints
- Import-Dependent API Supply:Active pharmaceutical ingredient sourcing concentrates through Indian and Chinese bulk manufacturers, exposing formulators to currency fluctuation and shipping disruption.
- FDA Philippines Registration Timelines:Post-market surveillance requirements and bioequivalence study mandates extend product launch windows for generic entrants.
- Metformin Generic Saturation:First-line therapy commoditization erodes originator brand pricing power in the volume base segment.
Strategic Opportunities
- Davao Region Penetration:Mindanao's underserved diabetes population presents white space for diabetes educator network extension beyond established Luzon and Visayas corridors.
- Fixed-Dose Combination Formulations:Dual- and triple-agent tablets reduce pill burden in multi-morbid patient populations, commanding premium positioning over single-agent generics.
- Telemedicine Integration:Remote consultation platforms enable provincial patient monitoring without physical clinic visits, opening channel innovation for medication adherence programs.
Industry Challenges
- Specialized Diabetes Educator Shortage:Endocrinology nursing expertise concentrates in tertiary Metro Manila hospitals, constraining provincial patient education scale.
- Cold Chain Integrity for Biosimilar Storage:Temperature-controlled logistics requirements for emerging insulin analog alternatives demand capital investment beyond oral solid dose capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Oral Anti-Diabetic Drug Market |
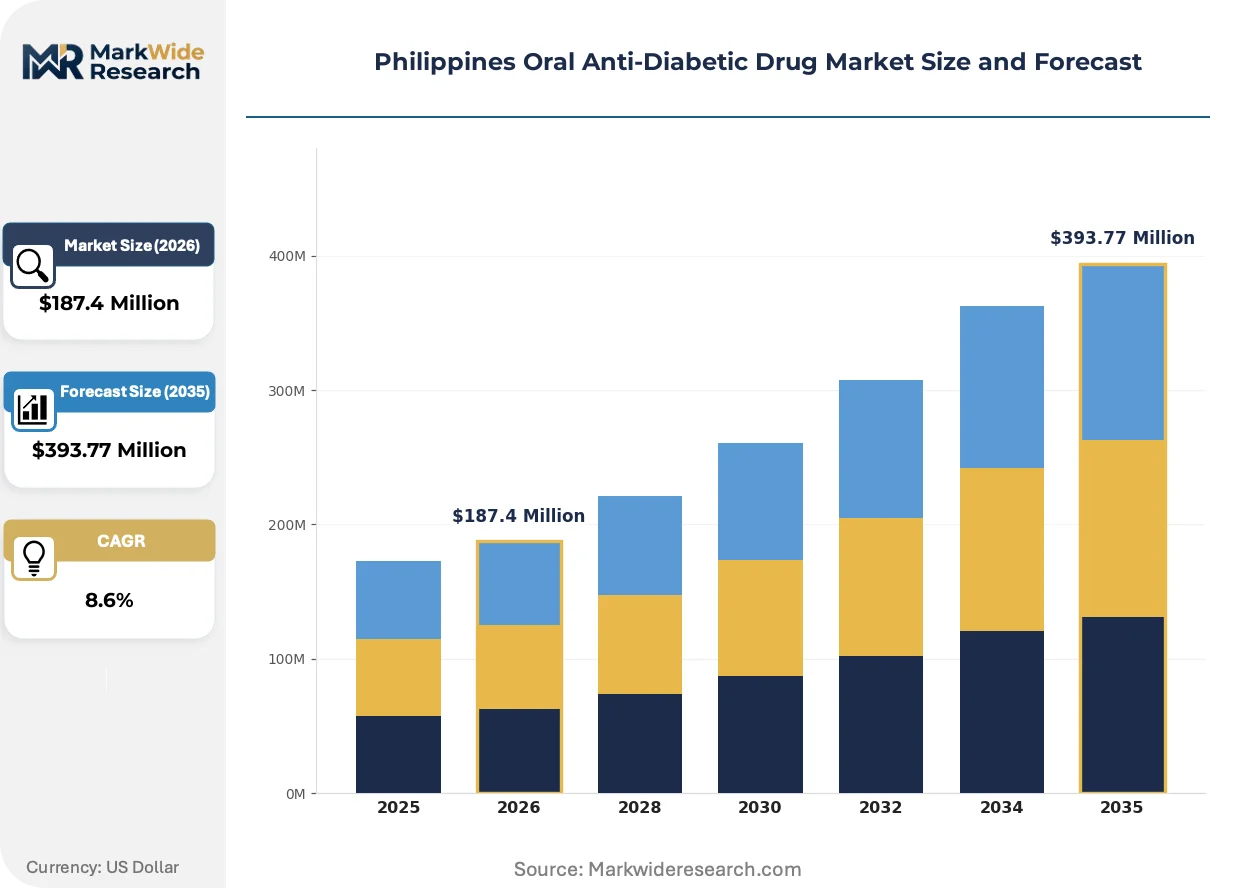
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Mode: Tablet, Capsule, Liquid Formulation, Extended Release End User: Clinics, Hospitals, Pharmacies, Homecare Therapy Area: Type 2 Diabetes, Prediabetes, Insulin Resistance, Obesity Management |
| Companies Covered | Sanofi, AstraZeneca, Eli Lilly and Company, Janssen, Astellas Pharma, Merck & Co., Novo Nordisk, Takeda Pharmaceutical Company, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Oral Anti-Diabetic Drug Market Trends and Innovations
Digital health infrastructure is compressing traditional clinic-based care models while regulatory pressure accelerates formulary alignment and patient support programs extend pharmaceutical value capture beyond the prescription transaction.
Continuous glucose monitoring integration with smartphone applications is virtualizing traditional endocrinology consultations. Philippine Diabetes Association member clinics in Metro Manila deploy remote glucose data review to reduce in-person visit frequency. This virtualization compresses geographic barriers between specialist physicians and provincial patients.
FDA Philippines biosimilar interchangeability guidelines are reshaping competitive dynamics between originator brands and local manufacturers. The regulator's bioequivalence study requirements create tiered approval pathways that favor established domestic formulators with in-house analytical capabilities. Generic sponsors with pre-existing FDA Philippines relationships navigate registration timelines more efficiently than new market entrants.
Hospital pharmacy consolidation is compressing traditional multi-brand stocking patterns. Large tertiary networks in Quezon City and Cebu City centralize procurement through committee-based formulary decisions, displacing individual physician brand preference. This concentration is most visible in PhilHealth-accredited institutions where reimbursement alignment drives therapeutic class standardization.
Philippines Oral Anti-Diabetic Drug Market Segmentation
Segmentation in the Philippines oral anti-diabetic drug market reveals how therapeutic positioning, formulation technology, and care setting economics interact to determine commercial outcomes. Each dimension carries distinct regulatory, reimbursement, and competitive implications that shape stakeholder strategy.
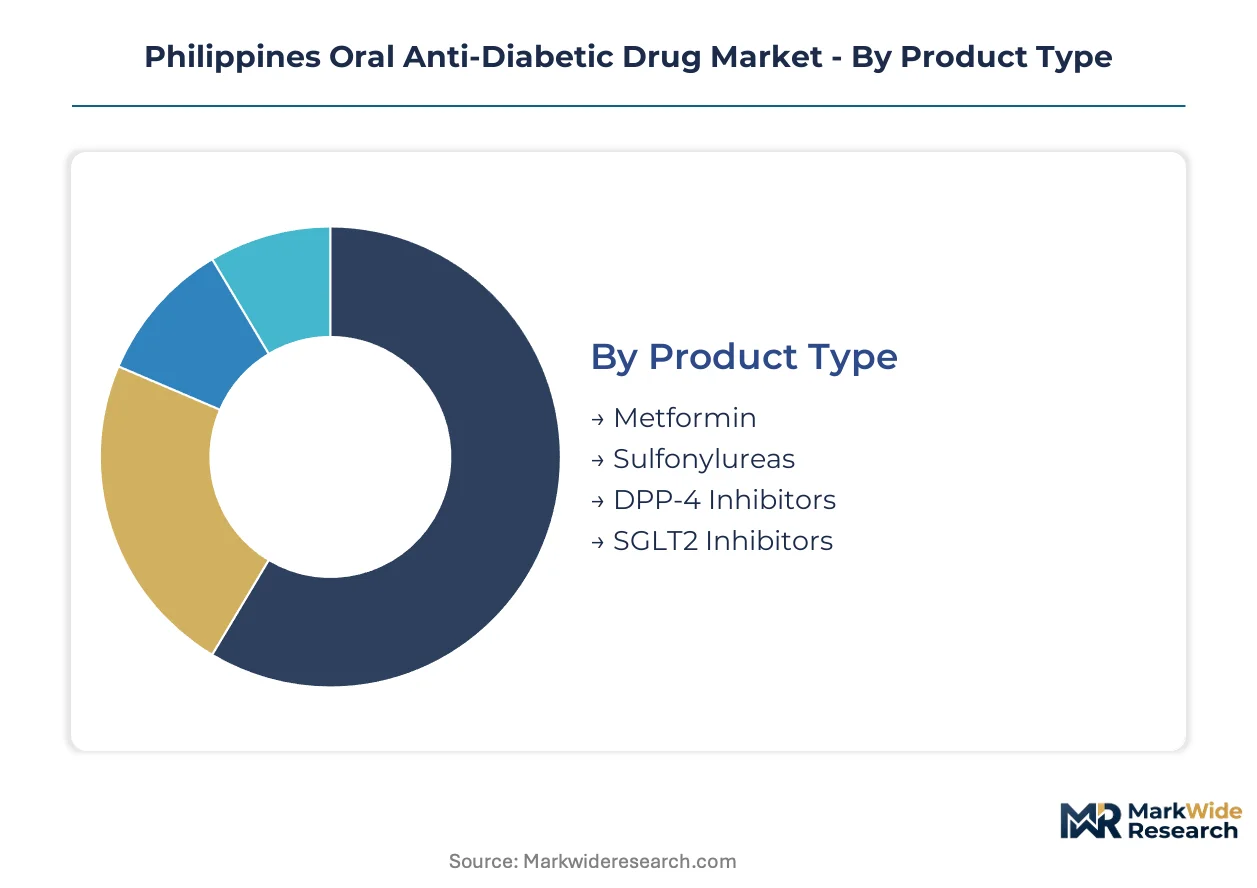
Product Type:
Mature molecules anchor volume while cardiovascular outcome data drives premium positioning for newer therapeutic classes.
- Metformin:Biguanide compound suppressing hepatic gluconeogenesis serves as the first-line standard across PhilHealth outpatient packages. Demand concentrates in public hospital pharmacies throughout Metro Manila's tertiary networks where generic substitution protocols maximize formulary compliance.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers reducing renal glucose reabsorption command specialist prescribing in Philippine Heart Center cardiology units. Central Visayas regional hospitals increasingly adopt these agents for dual cardiovascular-renal benefit in multi-morbid populations.
- Sulfonylureas:Pancreatic beta-cell stimulators including glimepiride and gliclazide persist in provincial health facilities with limited endocrinology specialist access.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors offering weight-neutral glucose reduction occupy the middle tier of private hospital formularies.
Metformin handles the majority of throughput; SGLT2 inhibitors are gaining share fastest on cardiovascular outcome differentiation.
Delivery Mode:
Formulation sophistication determines adherence economics and manufacturing complexity tiers across domestic production and import channels.
- Extended Release:Osmotic pump and matrix-based formulations reduce dosing frequency to once-daily regimens. Adoption concentrates among multi-morbid patients in Quezon City and Cebu City tertiary networks where pill burden reduction improves HbA1c persistence metrics.
- Tablet:Immediate-release compressed solids dominate PhilHealth procurement tenders through cost-minimization protocols. Volume concentrates in Department of Health regional warehouses supplying barangay health stations nationwide.
- Capsule:Gelatin and HPMC shell formulations serve patients with tablet swallowing difficulties in geriatric homecare settings.
- Liquid Formulation:Oral solutions and suspensions address pediatric and dysphagic patient populations in specialized endocrinology clinics.
Tablet formulations handle the majority of throughput; extended release is climbing the fastest on adherence program integration.
End User:
Care setting concentration shapes distribution infrastructure requirements and patient education investment levels.
- Hospitals:Tertiary and secondary institutions with PhilHealth accreditation drive formulary-standardized procurement through pharmacy and therapeutics committees. Demand concentrates in Metro Manila's university hospital networks and Central Visayas medical centers with dedicated endocrinology departments.
- Pharmacies:Community retail channels including Mercury Drug and Watsons networks handle maintenance prescription refills for stabilized patients. Out-of-pocket spending concentrates in urban centers with higher disposable income profiles.
- Clinics:Private endocrinology and internal medicine practices in Makati and Ortigas business districts serve insured professional populations.
- Homecare:Nurse-administered medication management supports elderly and mobility-limited patients in Davao Region and other Mindanao corridors.
Hospital channels handle the majority of throughput; homecare is expanding most quickly on telemedicine platform integration.
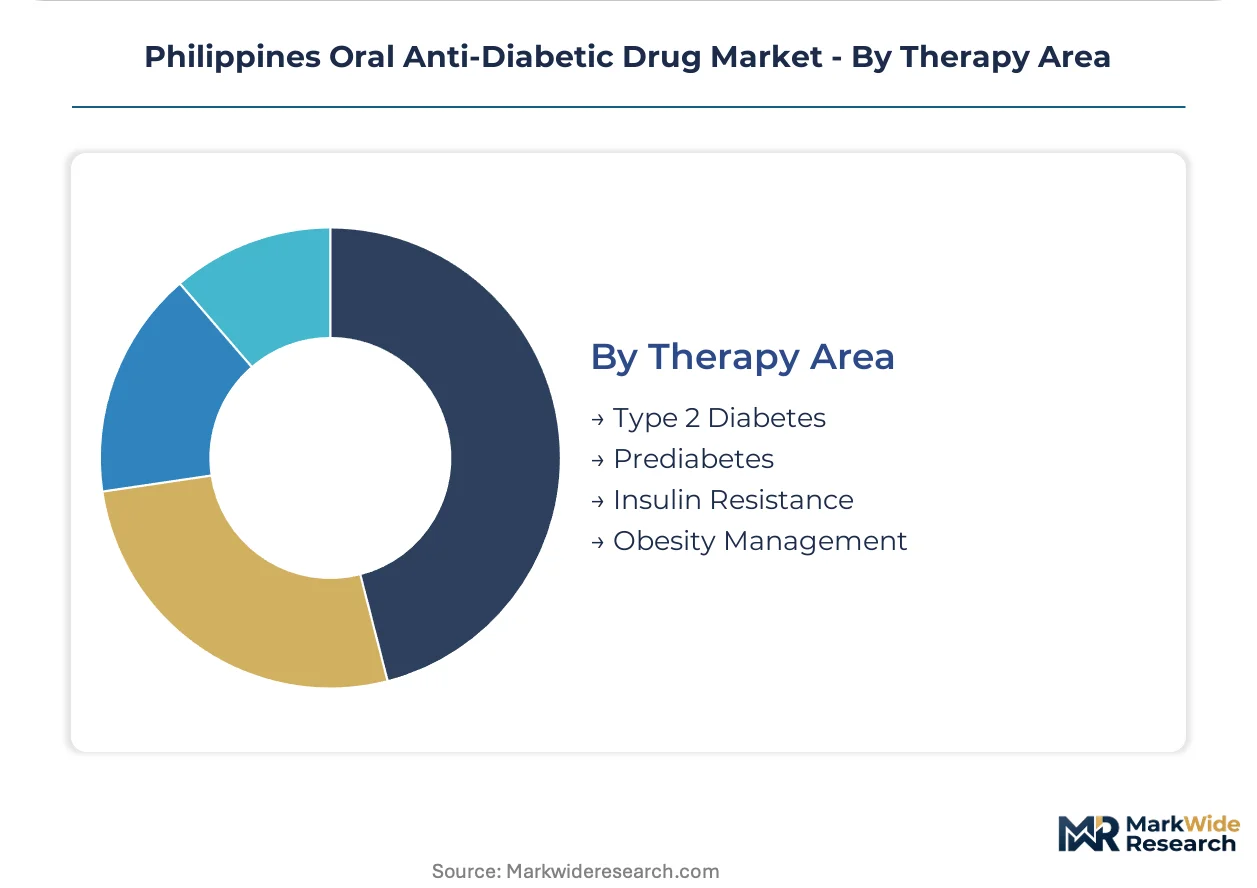
Therapy Area:
Disease stage and comorbidity profile determine reimbursement eligibility and therapeutic intensity requirements.
- Type 2 Diabetes:Established hyperglycemia with insulin resistance or relative deficiency constitutes the core addressable population. PhilHealth chronic disease packages cover maintenance medications for diagnosed patients across all regional health systems.
- Obesity Management:Metabolic syndrome and weight-centric prescribing drives SGLT2 inhibitor and metformin off-label utilization in bariatric surgery referral networks.
- Prediabetes:Impaired glucose tolerance and fasting glucose elevation represents an emerging prevention-focused segment in corporate wellness programs.
- Insulin Resistance:Polycystic ovary syndrome and metabolic syndrome applications extend prescribing beyond classical diabetes diagnosis in reproductive endocrinology practices.
Type 2 diabetes handles the majority of throughput; obesity management is advancing fastest on cardiometabolic risk repositioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila's tertiary hospital networks consume oral anti-diabetic drugs through PhilHealth-accredited procurement channels, while Central Visayas and Davao Region present divergent access patterns shaped by specialist availability and provincial health system maturity.
Metro Manila
PhilHealth outpatient benefit packages concentrate demand in Quezon City and Makati tertiary networks where endocrinology specialists drive SGLT2 inhibitor adoption. The Department of Health's Philippine National Formulary determines public hospital procurement priorities. Philippine General Hospital and St. Luke's Medical Center anchor specialist prescribing patterns that diffuse to regional hubs.
Central Visayas
Cebu City medical centers extend endocrinology reach into provincial municipalities through regional health system investments. FDA Philippines registration timelines affect generic entry speed into Visayas distribution channels. Vicente Sotto Memorial Medical Center and Cebu Doctors' University Hospital serve as referral anchors for diabetes educator network extension.
Davao Region
Mindanao's underserved diabetes population presents white space for patient support program deployment beyond established Luzon corridors. PhilHealth reimbursement codes for chronic disease packages lag in penetration compared to Metro Manila. Southern Philippines Medical Center in Davao City concentrates specialist capacity that surrounding provinces depend upon for complex case management.
Calabarzon
Laguna and Cavite industrial zones generate employed populations with private insurance coverage for premium oral anti-diabetic segments. Out-of-pocket spending concentrates in Sta. Rosa and Biñan pharmacy retail networks. The region's manufacturing base supports corporate wellness programs that drive prediabetes screening and early pharmacological intervention.
Philippines Oral Anti-Diabetic Drug Market Competitive Landscape
Capability concentration sits with multinational originators holding cardiovascular outcome data and diabetes educator infrastructure; scale advantage sits with domestic formulators navigating FDA Philippines generic pathways. The market structures around three tiers: originator brands commanding specialist channels, licensed local manufacturers supplying PhilHealth tenders, and pure generics competing on price in retail pharmacy. Consolidation pressures intensify through hospital pharmacy committee centralization and formulary standardization across tertiary networks.
Within the originator tier, Sanofi and Novo Nordisk anchor chronic disease management ecosystems extending beyond prescription transactions. AstraZeneca occupies a position tied to SGLT2 cardiovascular outcome differentiation. Among these, Sanofi exemplifies the patient support program archetype, Novo Nordisk represents specialized educator network investment, and AstraZeneca illustrates cardiometabolic repositioning strategy. Domestic formulators compete through bioequivalence study completion speed and pre-existing FDA Philippines regulatory relationships.
| Leading Market Players |
|---|
| Sanofi |
| AstraZeneca |
| Eli Lilly and Company |
| Janssen |
| Astellas Pharma |
| Merck & Co. |
| Novo Nordisk |
| Takeda Pharmaceutical Company |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
Import-dependent API sourcing from Indian and Chinese bulk manufacturers exposes Philippine formulators to currency fluctuation and shipping disruption, compressing margin spreads across originator brands while forcing domestic manufacturers toward extended-release formulation premiums and fixed-dose combination strategies to escape commodity metformin pricing.
Pricing Analysis
Long-term offtake contracts anchor PhilHealth procurement tenders for metformin and sulfonylureas, while spot-market dynamics govern SGLT2 inhibitor and DPP-4 inhibitor volumes in private hospital channels. Three-tier pricing structure across premium, standard, and economy levels separates cardiovascular-outcome-differentiated originators from bioequivalence-certified domestic formulators and unbranded generics. Pricing pressure stems from metformin generic saturation eroding first-line therapy margins. Public hospital procurement committees exhibit highest price sensitivity; Philippine Heart Center cardiology units show lowest sensitivity due to outcome-based prescribing protocols.
Supply Chain Analysis
Contract manufacturing concentration for oral solid dose production sits with Indian API suppliers and Chinese intermediate processors, with Philippine domestic formulators handling final tableting and packaging operations. Active pharmaceutical ingredient supply draws from Gujarat and Hyderabad manufacturing clusters in India, plus Zhejiang and Jiangsu provinces in China. Raw material dependencies include metformin hydrochloride bulk, glimepiride intermediates, and SGLT2 inhibitor active moieties. Single-source vulnerability concentrates in dapagliflozin and empagliflozin API channels. Distribution runs through Department of Health regional warehouses to barangay health stations, with cold chain logistics for temperature-sensitive formulations managed through tertiary hospital pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines oral anti-diabetic drug market functions as a defensive-moat arena where FDA Philippines regulatory entrenchment and PhilHealth formulary alignment create switching costs that protect incumbent positions against generic challengers lacking established bioequivalence study infrastructure.
For Market Incumbents: Entrench position through vertical integration into diabetes educator network deployment across Central Visayas and Davao Region corridors, while securing fixed-dose combination formulation patents ahead of FDA Philippines biosimilar interchangeability guideline implementation. Threat from domestic formulators with pre-existing regulatory relationships demands preemptive channel control in hospital pharmacy and therapeutics committees. For New Entrants and Emerging Players: Build out telemedicine-integrated patient support programs targeting Davao Region and Mindanao white space where specialist endocrinology access remains constrained. Most penetrable segment lies in extended-release metformin formulations for multi-morbid geriatric populations in provincial health facilities. Go-to-market angle centers on nurse-administered homecare partnerships reducing pill burden adherence gaps. For Investors and Strategic Acquirers: FDA Philippines biosimilar interchangeability guideline finalization reshapes the acquisition landscape toward domestic formulators with in-house analytical capabilities and completed bioequivalence portfolios. Long-term viability favors targets with established PhilHealth reimbursement code access and regional distribution infrastructure. Signal to watch is PhilHealth outpatient benefit package expansion into prediabetes pharmacological intervention categories.| Strategic Initiative | Industry Significance |
|---|---|
| Diabetes Educator Network Extension | Specialist nursing deployment into provincial facilities reduces patient education bottlenecks constraining volume growth. |
| Fixed-Dose Combination Development | Dual-agent tablets command premium positioning over single-agent generics in multi-morbid populations. |
| Telemedicine Platform Integration | Remote glucose monitoring virtualizes endocrinology consultations beyond Metro Manila concentration. |
| PhilHealth Reimbursement Strategy | Formulary alignment with outpatient chronic disease packages determines public sector procurement access. |
| Extended-Release Formulation Investment | Osmotic pump technology reduces dosing frequency and improves HbA1c persistence metrics in geriatric segments. |
Research Methodology
A spread of perspectives from endocrinology specialists, hospital pharmacy directors, FDA Philippines regulatory affairs officers, and PhilHealth formulary managers converged on the working assumptions driving this analysis. Primary interviews with diabetes educator network coordinators and provincial health facility administrators were cross-validated against FDA Philippines registration databases, Department of Health essential medicines list revisions, and PhilHealth benefit package documentation. Secondary sources included Philippine National Formulary updates, clinical practice guidelines from the Philippine Diabetes Association, and customs import records for active pharmaceutical ingredients. Bottom-up patient population estimates and top-down pharmaceutical spending flows were triangulated to establish market sizing boundaries.
Demand-supply balance framing anchored the forecast framework across the analysis window, with patient volume projections calibrated against endocrinology specialist capacity expansion and provincial health facility upgrade timelines. Segmentation dimensions modeled included therapeutic class, dosage form sophistication, care setting economics, and regional reimbursement penetration. CAGRs were derived from elasticity-adjusted volume forecasts and pricing trajectory assumptions. Industry-specific inputs incorporated PhilHealth outpatient benefit package expansion scenarios and FDA Philippines generic approval velocity metrics.
Stress conditions across peso-dollar exchange rate volatility, Indian and Chinese API supply disruption, and PhilHealth formulary revision timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding specialist workforce expansion and telemedicine infrastructure deployment. Regulatory guideline publication delays or biosimilar interchangeability standard changes could materially revise projections. Quarterly review of FDA Philippines registration queue lengths and PhilHealth reimbursement code updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
North America Insulin Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Digital Diabetes Market