
 Global Non Clinical Information System Market | 2026-2036
Global Non Clinical Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Clinical Information System Market Foresight
Subscription-based software-defined feature layers is pivoting vendor economics away from perpetual licenses toward recurring revenue streams. Epic Systems Corporation leverages deep integration with academic medical centers to anchor its research informatics footprint. Oracle Cerner sustains competitive positioning through backward integration into data infrastructure. McKesson Corporation dominates pharmaceutical supply chain adjacencies that extend into non-clinical workflow orchestration.
A non-clinical information system constitutes an integrated software environment that manages laboratory data, study protocols, and regulatory documentation across preclinical and translational research phases, typically incorporating audit trails, electronic signatures, and GLP-compliant data hierarchies to ensure reproducibility and regulatory defensibility. Software Platforms capture the dominant margin pool given their role as the orchestration layer for downstream analytics and reporting modules. Cloud-Based deployment is expanding fastest among contract research organizations seeking elastic compute for toxicology studies, while On-Premises systems retain entrenched positions at regulatory bodies with stringent data sovereignty mandates.
FDA 21 CFR Part 11 shapes product standards by mandating electronic records and signature validation, while EMA's GLP monitoring framework governs study data integrity for European submissions. ISO 14155 and OECD principles on good laboratory practice create baseline compliance thresholds that determine market access across jurisdictions. Stakeholders must monitor evolving AI validation requirements from regulators as machine learning modules penetrate pharmacovigilance and predictive toxicology workflows.
Market Dynamics
Cloud deployment architectures are compressing implementation timelines for contract research organizations while simultaneously triggering compliance recertification cycles across legacy on-premise installations at regulatory bodies.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature mandates compel pharmaceutical sponsors to replace paper-based study documentation with validated software platforms.
- Toxicology study complexity:Rising molecular diversity in biologics pipelines generates exponential data volumes that manual workflows cannot process.
- China biotechnology funding:Domestic venture capital concentration in Shanghai and Suzhou clusters accelerates demand for GLP-compliant data management infrastructure.
Market Restraints
- Validation cost structure:FDA 21 CFR Part 11 compliance documentation and audit trail implementation add substantial fixed costs to platform deployment.
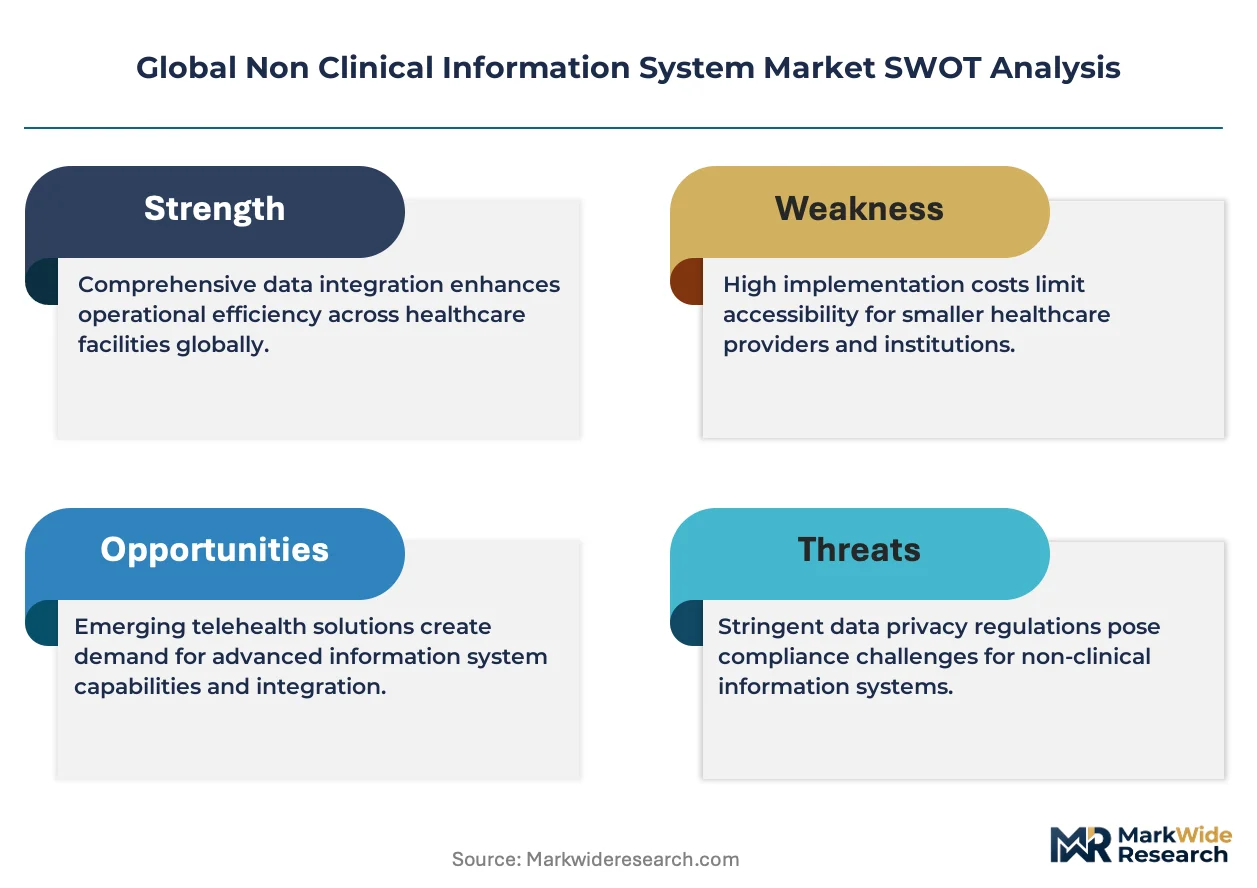
- Data sovereignty requirements:German and French regulatory bodies mandate on-premise hosting, fragmenting vendor cloud scale economies.
- Legacy system entrenchment:Decades of proprietary data formats in established pharmaceutical R&D sites create technical debt that slows migration timelines.
Strategic Opportunities
- AI validation frameworks:Emerging EMA and FDA guidance on machine learning in pharmacovigilance creates first-mover advantage for predictive toxicology modules.
- India contract research expansion:Hyderabad and Bangalore CRO clusters remain underpenetrated by integrated platform vendors relative to study volume growth.
- API-first architectures:Open integration standards enable modular substitution of analytics layers without full platform replacement.
Industry Challenges
- GLP auditor scarcity:Qualified study directors capable of certifying computer system validation under OECD principles command premium compensation that strains mid-tier CRO budgets.
- Multi-jurisdiction synchronization:Divergent FDA, EMA, and NMPA submission timelines force parallel documentation tracks that duplicate workflow overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Clinical Information System Market |
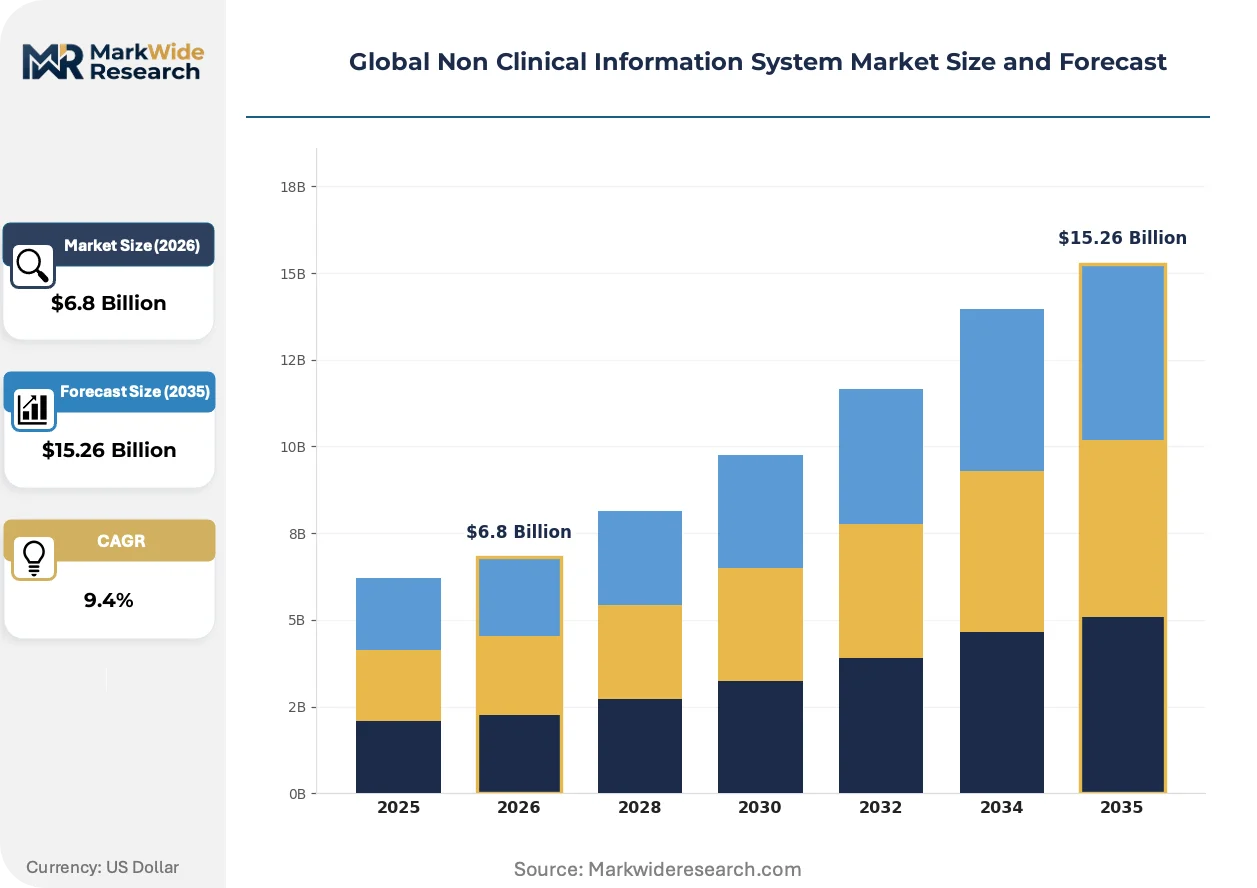
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Platforms, Data Management Tools, Reporting Solutions, Integration Modules, Analytics Tools Application: Preclinical Research, Clinical Data Management, Pharmacovigilance, Regulatory Compliance, Toxicology Studies End User: Pharmaceutical Companies, Contract Research Organizations, Biotechnology Firms, Academic Institutions, Regulatory Bodies Deployment: On-Premises, Cloud-Based, Hybrid Systems, SaaS Models, Dedicated Hosting |
| Companies Covered | Epic Systems Corporation, Oracle Cerner, Allscripts Healthcare Solutions, McKesson Corporation, Athenahealth, NextGen Healthcare, eClinicalWorks, GE Healthcare, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Clinical Information System Market Shifts & Advancements
Artificial intelligence modules are penetrating core workflow layers that were previously resistant to automation, while regulatory bodies simultaneously draft validation standards that lag implementation by multiple release cycles.
Natural language processing is consolidating protocol authoring and adverse event narrative generation into unified interfaces. Mid-size biotechnology sponsors in Boston and San Francisco clusters are adopting these tools within twelve-month procurement windows. The technology is consolidating previously separate medical writing and data management functions into single-platform subscriptions.
EMA's GLP monitoring framework revisions are tightening raw data integrity requirements for European submissions. Sponsors must now implement real-time audit trail verification that extends to third-party CRO partners. German pharmaceutical manufacturers are responding by mandating on-premise data lakes with blockchain-anchored timestamps.
Subscription unbundling is fragmenting traditional platform contracts into component modules. Toxicology CROs now procure electronic lab notebook, study management, and regulatory submission tools from separate vendors. This pattern is most visible in United States East Coast clusters where venture-backed sponsors prioritize capital efficiency over integrated suites.
Global Non Clinical Information System Market Segmentation
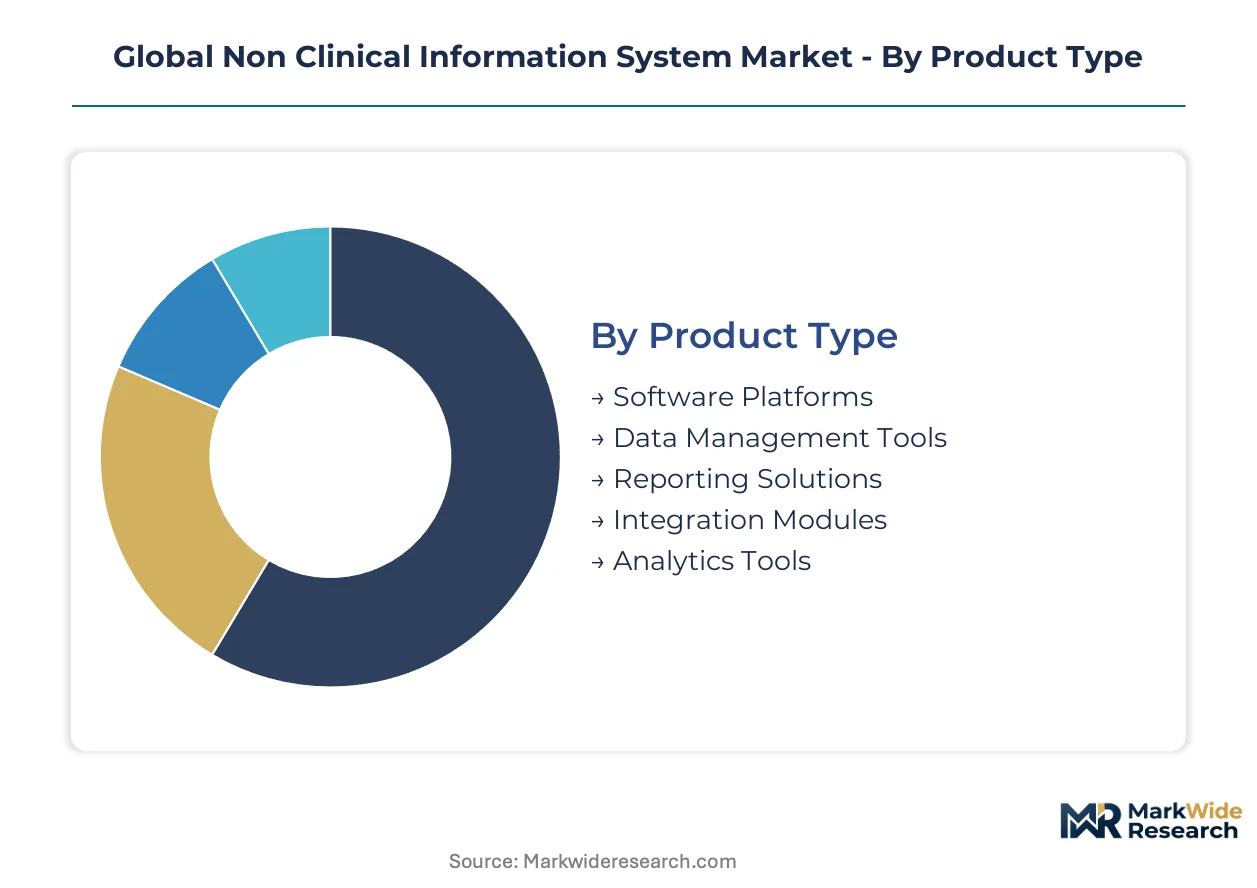
Segmentation in the non-clinical information system market determines procurement priorities and compliance pathways. Pharmaceutical sponsors select configurations based on study complexity, regulatory jurisdiction, and integration requirements with legacy infrastructure.
Product Type:
Capital intensity varies sharply across product categories, with orchestration layers demanding substantially higher upfront investment than point solutions.
- Software Platforms:Comprehensive environments integrating protocol management, audit trails, and electronic signatures under unified architectures. Pharmaceutical companies in the United States and Germany deploy these as core infrastructure for multi-site toxicology programs, driven by FDA 21 CFR Part 11 and EMA GLP mandates that prohibit fragmented toolchains.
- Data Management Tools:Specialized modules handling raw data capture, transformation, and lineage tracking across laboratory instruments. Contract research organizations in China prioritize these investments to manage exponential data volumes from biologics pipelines, though validation documentation adds substantial fixed costs to deployment.
- Reporting Solutions:Regulatory submission generators formatting study outputs for agency-specific templates.
- Integration Modules:Middleware connecting disparate laboratory instruments and legacy databases.
- Analytics Tools:Statistical and visualization engines for pharmacokinetic modeling and dose-response analysis.
Most installed capacity flows through Software Platforms. Expansion is steepest in Data Management Tools.
Application:
Application segmentation maps directly to study-phase economics, with late-stage validation work commanding premium pricing over exploratory research.
- Preclinical Research:In vivo and in vitro study execution spanning pharmacology, safety pharmacology, and ADME profiling. Biotechnology firms in Boston and San Francisco clusters drive demand here, requiring GLP-compliant data hierarchies from discovery through IND-enabling studies.
- Toxicology Studies:Repeat-dose, carcinogenicity, and reproductive toxicology programs generating the largest raw data volumes per protocol. Contract research organizations in the United States and China expand capacity fastest in this segment, pressured by molecular diversity in antibody-drug conjugate and cell therapy pipelines.
- Clinical Data Management:Translational bridge studies connecting non-clinical findings to first-in-human protocols.
- Pharmacovigilance:Post-marketing safety surveillance leveraging non-clinical reference data.
- Regulatory Compliance:Submission assembly and agency correspondence management.
Preclinical Research captures the largest share of existing deployments. Toxicology Studies are gaining share fastest as biologics pipelines mature.
End User:
End user segmentation reflects divergent procurement authority, with sponsor organizations controlling platform selection while service providers adapt to client-mandated configurations.
- Pharmaceutical Companies:Integrated sponsors operating captive R&D facilities and managing outsourced study portfolios. German and Japanese manufacturers lead investment in on-premise validated systems, responding to national data sovereignty requirements that restrict cloud migration.
- Contract Research Organizations:Multi-client service providers requiring elastic infrastructure and rapid study onboarding. United States East Coast and Chinese CRO clusters expand cloud-based deployments fastest, prioritizing capital efficiency over integrated suite ownership.
- Biotechnology Firms:Venture-backed developers with concentrated pipeline risk and limited validation expertise.
- Academic Institutions:Non-commercial research sites with fragmented funding and inconsistent compliance maturity.
- Regulatory Bodies:Government agencies conducting reference studies and setting inspection precedents.
Pharmaceutical Companies maintain the deepest installed base. Contract Research Organizations are expanding procurement most aggressively.
Deployment:
Deployment architecture determines compliance recertification cycles and total cost of ownership across multi-year study portfolios.
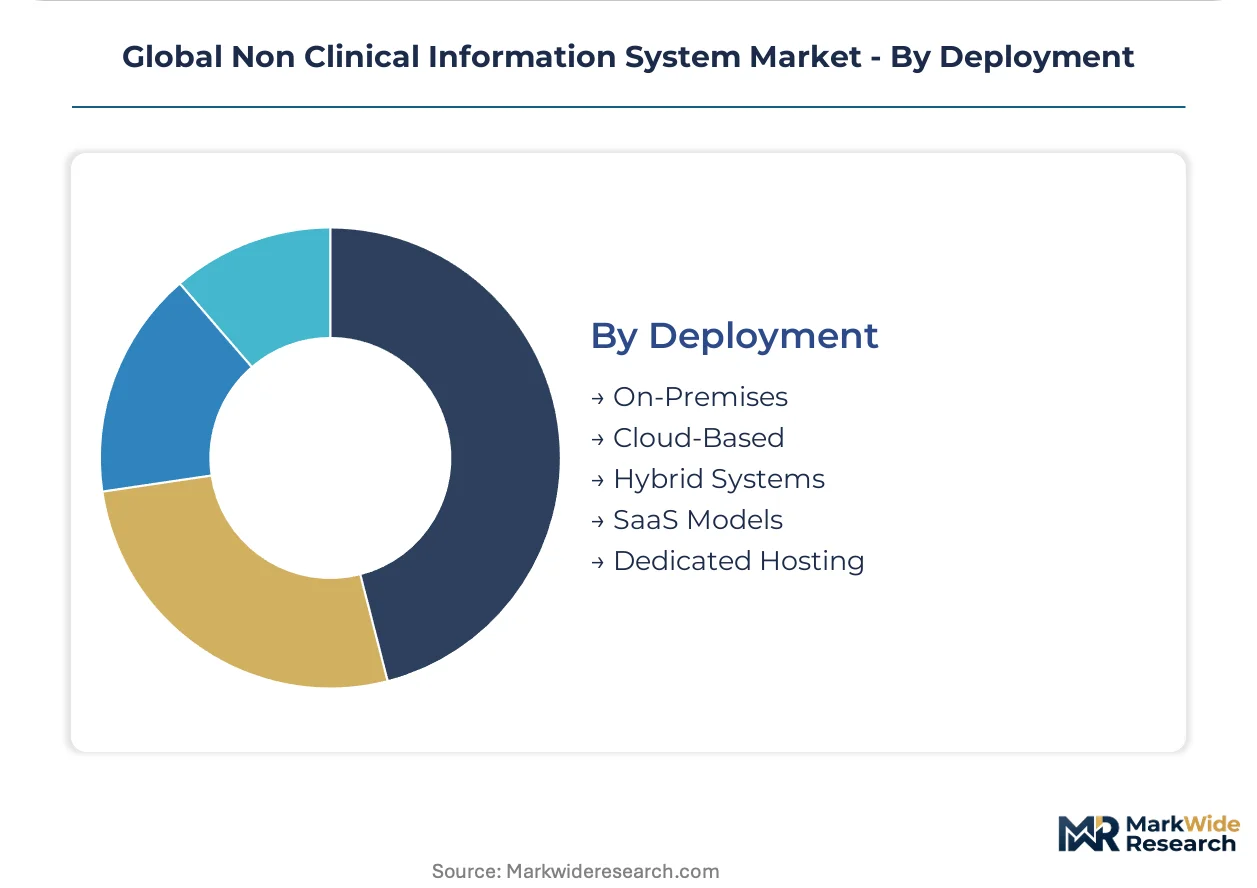
- Cloud-Based:Elastic compute environments with vendor-managed infrastructure and subscription pricing. Contract research organizations in India and the United States adopt these fastest for toxicology studies requiring burst capacity, though German and French regulatory constraints limit addressable market.
- On-Premises:Captive hardware installations with direct control over physical security and data residency. Regulatory bodies in Germany and Japan mandate these configurations, preserving entrenched positions despite higher maintenance overhead.
- Hybrid Systems:Partitioned architectures separating sensitive raw data on-premise from analytics workloads in cloud environments.
- SaaS Models:Fully managed software layers with minimal client infrastructure responsibility.
- Dedicated Hosting:Single-tenant cloud instances addressing data sovereignty without full on-premise burden.
On-Premises retains the largest installed footprint. Cloud-Based deployment is climbing the fastest as vendor validation documentation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States deployment velocity outpaces German adoption curves, while Chinese biotechnology clusters compress implementation timelines through aggressive cloud migration strategies.
United States
FDA 21 CFR Part 11 mandates compel pharmaceutical sponsors to replace paper-based documentation with validated electronic systems. The regulation's electronic signature requirements reshape procurement priorities across Boston and San Francisco biotechnology corridors. Contract research organizations in these clusters prioritize cloud-based platforms that accelerate toxicology study onboarding.
Germany
EMA's GLP monitoring framework and national data sovereignty requirements preserve entrenched on-premise installations at regulatory bodies. German pharmaceutical manufacturers mandate captive data lakes with blockchain-anchored timestamps to satisfy raw data integrity standards. The Baden-Württemberg and Bavaria chemical-pharma belts host the densest concentration of validated system deployments.
China
NMPA regulatory convergence with OECD principles accelerates GLP-compliant infrastructure investment across domestic biotechnology pipelines. Shanghai and Suzhou venture capital clusters fund rapid platform adoption for antibody-drug conjugate development programs. Contract research organizations in these cities expand elastic compute capacity for biologics toxicology studies.
India
Hyderabad and Bangalore contract research clusters remain underpenetrated by integrated platform vendors relative to study volume expansion. CDSCO's evolving data integrity guidelines create compliance preparation windows for domestic service providers. These southern cities attract multinational pharmaceutical sponsors seeking cost-optimized preclinical execution.
Japan
PMDA inspection precedents and METI industrial policy reinforce stringent validation documentation requirements at established manufacturers. Japanese pharmaceutical sponsors maintain captive on-premise systems with multi-decade depreciation cycles. The Kanto and Kansai metropolitan areas concentrate domestic R&D facility investment.
Global Non Clinical Information System Market Competitive Landscape
Top-tier vendors anchor enterprise platform consolidation, while mid-tier specialists occupy modular niches and regional service providers compete on implementation velocity. The vendor base stratifies across three functional archetypes: integrated healthcare IT conglomerates, research informatics pure-plays, and instrumentation manufacturers extending into software layers. Dominant competitive moves include backward integration into data infrastructure and geographic expansion through academic medical center partnerships.
Within the integrated healthcare IT tier, Epic Systems Corporation and Oracle Cerner exemplify divergent anchoring strategies. Epic leverages deep academic medical center relationships to secure research informatics footprint, while Oracle Cerner sustains positioning through upstream control over database infrastructure. McKesson Corporation occupies a distinct position at the pharmaceutical supply chain intersection, extending workflow orchestration capabilities into non-clinical domains.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Cerner |
| Allscripts Healthcare Solutions |
| McKesson Corporation |
| Athenahealth |
| NextGen Healthcare |
| eClinicalWorks |
| GE Healthcare |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
OECD principles on good laboratory practice and FDA 21 CFR Part 11 compliance documentation gate qualified supply access and premium-tier pricing for validated software platforms, forcing pharmaceutical sponsors to absorb substantial fixed validation costs or retreat to lower-tier modular alternatives with reduced audit trail capabilities.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for data management tools as contract research organizations in Hyderabad and Bangalore expand elastic compute offerings. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated platforms with full electronic signature support from stripped-down SaaS modules and open-source alternatives. Price differentiation hinges on certification grade and after-sales validation support. Cost compression in the standard tier is intensifying because Indian CROs bundle implementation services at marginal cost. Biotechnology firms in Boston and San Francisco clusters show least price sensitivity due to venture-funded procurement timelines.
Supply Chain Analysis
GLP auditor scarcity in Germany, the United States, and Japan constrains platform vendor expansion velocity as qualified study directors command premium compensation. Software development draws from cloud infrastructure providers, specialized compliance documentation firms, and academic medical center research informatics units. Single-source vulnerability concentrates in FDA audit trail validation expertise held by a limited consultant pool. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partners for mid-tier CRO access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where cloud deployment in India and China delivers equivalent GLP compliance at substantially lower validation labor costs than German or Japanese on-premise mandates.
For Market Incumbents: Lock in multi-year subscription contracts with United States East Coast biotechnology clusters before FDA AI validation guidance crystallizes and triggers platform replacement cycles. Deepen backward integration into compliance documentation services to capture GLP auditor scarcity premiums. Anchor positioning through captive data lake architectures at German pharmaceutical manufacturers responding to EMA raw data integrity tightening.
For New Entrants and Emerging Players: Launch via API-first modular pricing that unbundles electronic lab notebook, study management, and regulatory submission functions for toxicology CROs seeking capital efficiency. Target India contract research expansion in Hyderabad and Bangalore where integrated platform penetration lags study volume growth. Penetrate through open integration standards that enable modular substitution without full platform displacement.
For Investors and Strategic Acquirers: Roll-up economics work for regional compliance documentation specialists because GLP auditor scarcity and multi-jurisdiction synchronization complexity prevent organic vendor expansion. Five-to-ten year viability rests on AI validation framework first-mover positioning as EMA and FDA guidance matures. Watch for predictive toxicology module adoption inflection among antibody-drug conjugate developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Validation Documentation Investment | FDA 21 CFR Part 11 audit trail requirements compel pharmaceutical sponsors toward vendor-managed compliance layers. |
| API-First Architecture Development | Open integration standards enable modular substitution that fragments traditional platform subscription contracts. |
| Academic Medical Center Partnership | Epic Systems leverages deep institutional relationships to anchor research informatics footprint against database competitors. |
| India CRO Geographic Expansion | Hyderabad and Bangalore clusters remain underpenetrated relative to toxicology study volume growth. |
| AI Validation Framework Pre-Positioning | EMA and FDA machine learning guidance creates first-mover advantage for predictive toxicology modules. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged regulatory affairs leads at pharmaceutical sponsors, study directors at contract research organizations, platform engineers at software vendors, and compliance documentation specialists. Secondary sources included FDA 21 CFR Part 11 guidance documents, EMA GLP monitoring framework revisions, NMPA regulatory convergence notices, OECD principles on good laboratory practice, and SEC filings from publicly traded healthcare IT conglomerates. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Rate-of-change decomposition isolated volume and value drivers across the projection horizon. Segmentation dimensions modeled include product type, application, end user, deployment architecture, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Industry-specific inputs incorporated toxicology study complexity indices from biologics pipeline data and cloud infrastructure capex disclosures from hyperscaler partners.
Several conditions sit outside the modeled scope, including specific AI validation guidance release timing from FDA and EMA, unforeseen data sovereignty mandate expansions, and abrupt shifts in China biotechnology venture capital availability. Forecasts reflect assumptions about regulatory convergence trajectory and CRO outsourcing elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Allergy Care Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Global Health IT Security Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
AI in Epidemiology Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
IHE XDS.B Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Global Healthcare EDI Market