
 Australia Skin Laser Market | 2026-2036
Australia Skin Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Skin Laser Market Intelligence
Diode laser technology is shifting toward longer wavelengths to improve efficacy across darker skin phototypes, reducing adverse event rates and expanding addressable patient populations. Alma Lasers leverages its multi-platform portfolio to dominate the dermatology center channel across New South Wales and Victoria. Cynosure competes through specialized picosecond platforms targeting tattoo removal and pigmentation correction. Lutronic Corporation anchors its position with fractional CO2 systems that integrate real-time temperature monitoring for enhanced safety profiles.
Australia skin laser systems employ coherent light emission at specific wavelengths between 532 nm and 10,600 nm to selectively target chromophores including melanin, hemoglobin, and water within dermal and epidermal tissues. The primary commercial purpose centers on controlled photothermal or photomechanical destruction of target structures while preserving surrounding tissue integrity. Fractional laser platforms command premium positioning due to shorter downtime profiles and expanded treatment protocols for skin rejuvenation. Diode laser systems lead hair removal volumes through speed advantages and reduced per-session costs. Non-ablative technology captures growing share among first-time patients prioritizing minimal recovery intervals over single-treatment efficacy.
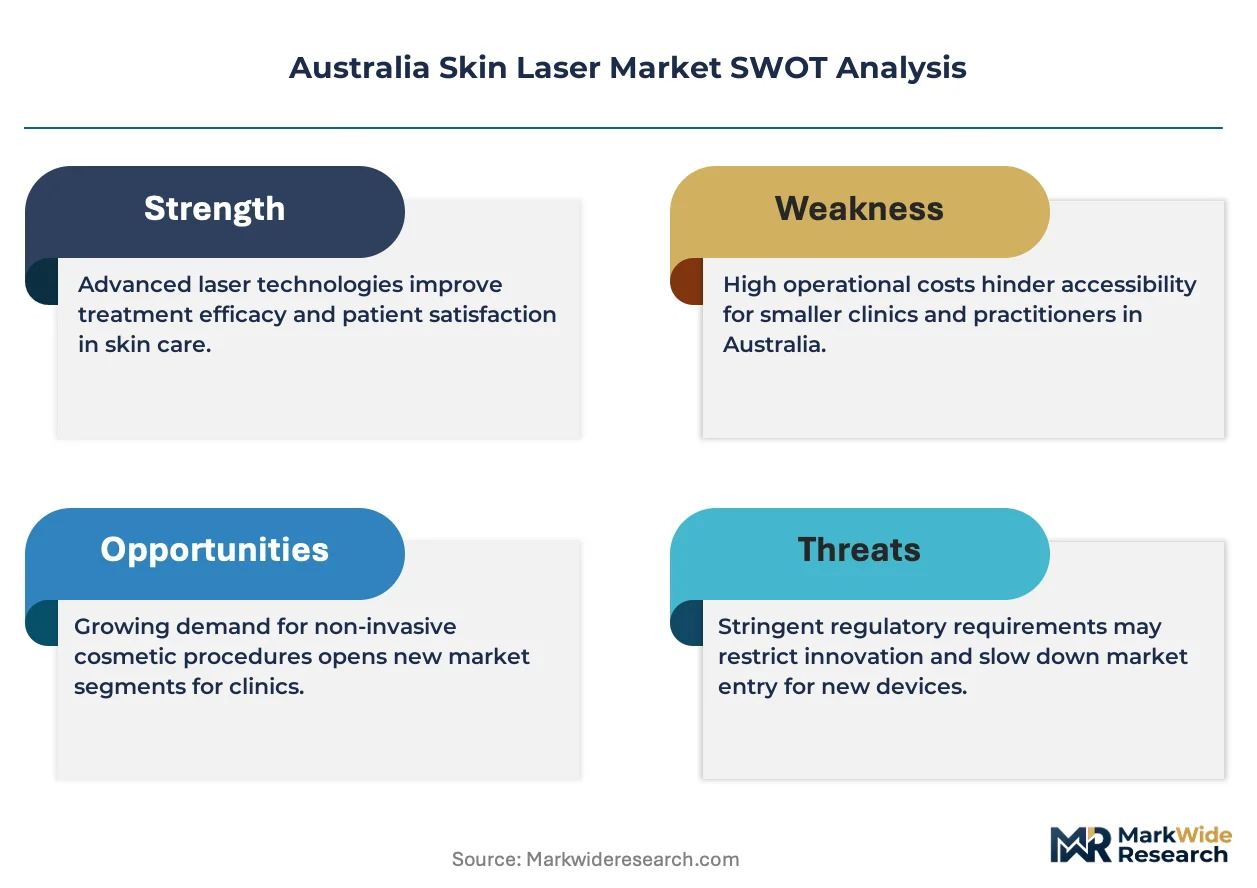
TGA medical device regulations govern pre-market assessment and post-market surveillance, directly influencing product registration timelines and clinical evidence requirements for new laser platforms. Australian Radiation Protection and Nuclear Safety Agency standards mandate operator certification and facility licensing, creating compliance barriers that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving state-based laser safety legislation and reimbursement positioning for medically indicated procedures versus cosmetic applications.
Market Dynamics
TGA medical device regulations are compressing product registration timelines while simultaneously elevating clinical evidence requirements, creating a bifurcated competitive landscape where established suppliers with dedicated regulatory affairs capabilities capture disproportionate share in New South Wales and Victoria dermatology centers.
Growth Catalysts
- Fractional laser protocols:Expanded treatment menus for acne scarring and skin rejuvenation are pulling younger demographics toward non-surgical alternatives across Sydney and Melbourne medical spas.
- ARPANSA certification mandates:Operator licensing requirements are professionalizing the channel, filtering out undercapitalized competitors and concentrating volume among credentialed facility networks.
- Diode wavelength extension:Longer-wavelength systems targeting darker skin phototypes are reducing adverse event rates and unlocking previously excluded patient populations in multicultural urban corridors.
Market Restraints
- Capital intensity of CO2 platforms:Fractional ablative systems require substantial upfront investment and dedicated maintenance contracts, limiting penetration outside major metropolitan dermatology chains.
- Import dependency for consumables:Handpiece tips, cooling gels, and calibration components concentrate supply through limited distribution channels, exposing operators to currency fluctuation risk.
- Substitution by energy-based alternatives:Radiofrequency microneedling and intense pulsed light platforms compete for overlapping indications at lower per-treatment price points in budget-conscious segments.
Strategic Opportunities
- Western Australia expansion:Perth and regional centers exhibit underpenetrated dermatology infrastructure relative to eastern seaboard density, presenting first-mover positioning for platform suppliers.
- Picosecond tattoo removal:Rising body-art prevalence among millennials creates dedicated service-line potential distinct from general rejuvenation offerings.
- Telemedicine pre-consultation:Remote skin assessment protocols are streamlining patient qualification, reducing no-show rates, and optimizing device utilization in high-rent clinic locations.
Industry Challenges
- Laser safety officer scarcity:ARPANSA-mandated facility certification requires dedicated personnel that smaller operators struggle to recruit and retain in tight labor markets.
- Device integration complexity:New platforms must interface with existing practice management software and electronic health records, extending deployment timelines and training burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Skin Laser Market |
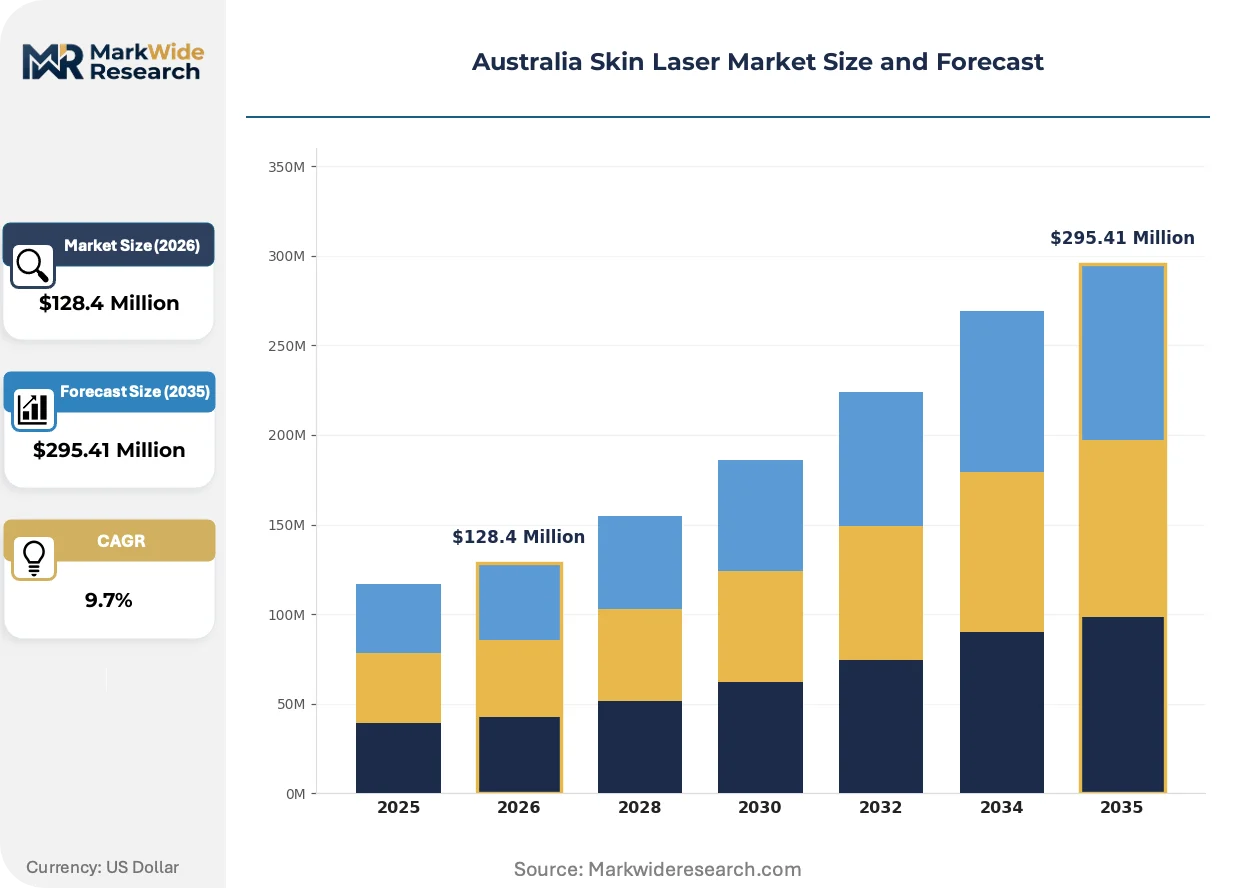
| Market Size in 2026 | $128.4 Million |
| Market Size in 2035 | $295.41 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fractional Laser, Intense Pulsed Light, Q-Switched Laser, Diode Laser Application: Hair Removal, Acne Scarring, Skin Rejuvenation, Pigmentation End User: Clinics, Hospitals, Medical Spas, Dermatology Centers Technology: Non-Ablative, Ablative, Pico Laser, RF Technology |
| Companies Covered | Alma Lasers, Cynosure, Cutera, Lumenis, Sciton, Lutronic Corporation, Fotona, Candela Medical, Aerolase, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Skin Laser Market Strategic Shifts & Innovations
Non-ablative technology platforms are reshaping patient acquisition economics by compressing recovery intervals and enabling same-day social reintegration, fundamentally altering how clinics structure treatment packages and price per-session value.
Picosecond pulse-duration technology is expanding into tattoo removal and refractory pigmentation indications previously resistant to nanosecond platforms. High-volume chains in Brisbane and Adelaide are deploying these systems as anchor service differentiators. The technology is expanding into premium positioning that commands elevated per-treatment pricing while reducing required session counts.
TGA's streamlined medical device clearance pathways are accelerating market entry for novel laser platforms while maintaining post-market surveillance obligations. Manufacturers must now submit real-world safety data within defined intervals. Dermatology centers in Victoria are responding by prioritizing suppliers with established Australian regulatory track records over newer entrants.
Patient qualification workflows are migrating toward digital pre-screening tools that reduce in-clinic consultation time and improve conversion rates. Medical spas are displacing traditional referral-dependent acquisition with direct-to-consumer channels. This shift concentrates in Sydney's competitive cosmetic corridor where rent pressures demand higher patient throughput per square meter.
Australia Skin Laser Market Segmentation
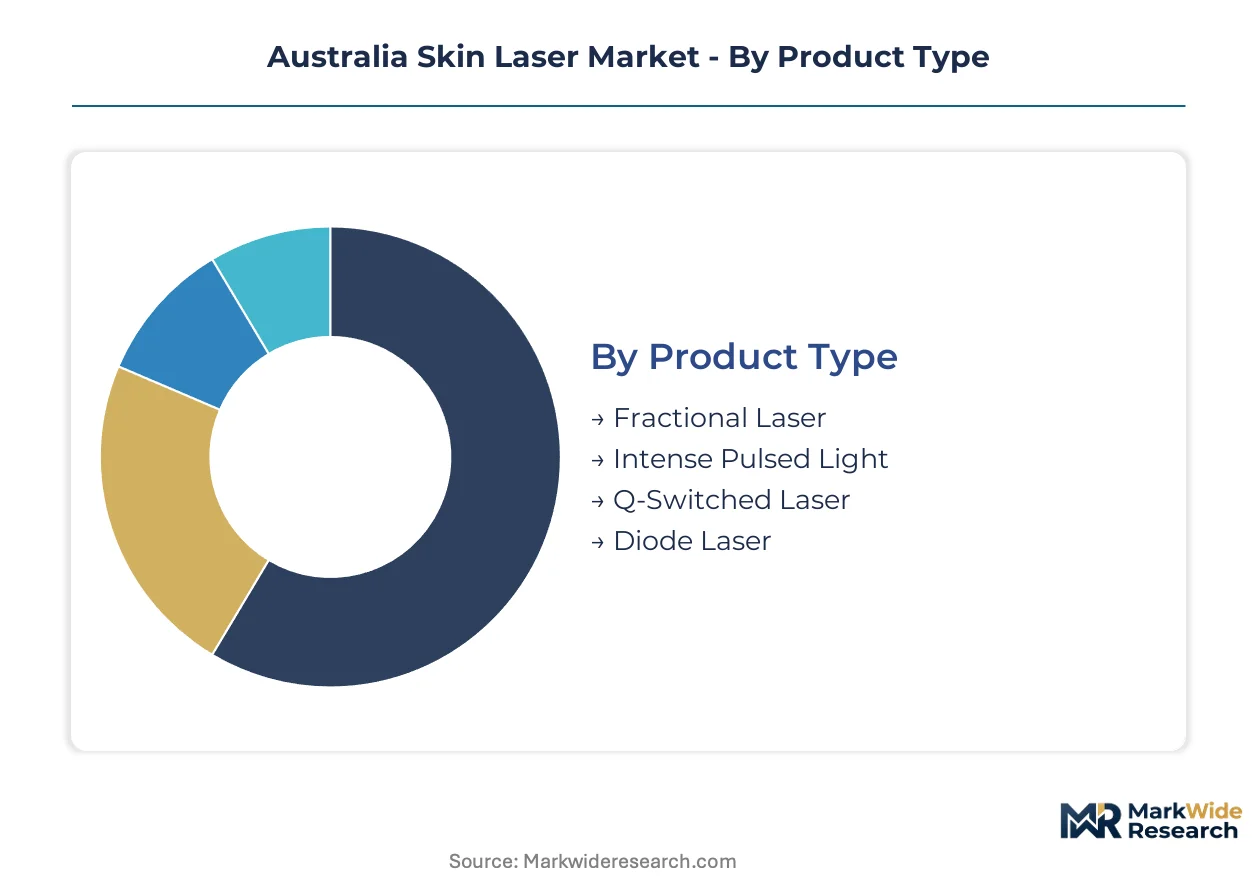
Device selection in the Australia skin laser market hinges on treatment specificity, downtime tolerance, and patient skin phototype compatibility. Segmentation reveals how technology platforms align with distinct clinical workflows and revenue models across metropolitan medical spas and hospital dermatology departments.
Product Type:
Purchase decisions prioritize treatment versatility against per-session throughput economics, with platform selection directly determining service menu breadth and patient retention potential.
- Fractional Laser:Delivers micro-beam arrays that create controlled thermal zones while preserving intervening tissue for accelerated healing. Demand concentrates in Sydney and Melbourne dermatology centers where acne scarring protocols attract younger demographics seeking surgical alternatives. TGA clearance pathways for newer fractional platforms are compressing upgrade cycles among established chains.
- Diode Laser:Employs semiconductor-generated coherent light at 800-1060 nm wavelengths optimized for melanin absorption in hair follicles. Western Australia medical spas are expanding diode capacity as longer-wavelength variants reduce adverse events across darker skin phototypes in multicultural urban corridors. Speed advantages and reduced per-session costs sustain volume leadership in hair removal.
- Intense Pulsed Light:Broadband non-coherent emission targets multiple chromophores simultaneously for generalized photorejuvenation. Queensland clinics favor IPL for budget-conscious patient segments.
- Q-Switched Laser:Nanosecond pulse duration delivers photomechanical disruption of tattoo pigment and refractory melanin lesions. Perth operators are adding Q-switched capacity as body-art prevalence rises among millennials.
Diode laser leads on scale; fractional laser leads on momentum.
Application:
Indication-specific demand patterns reflect demographic aging trajectories and cultural preferences for non-surgical aesthetic intervention across Australian metropolitan markets.
- Hair Removal:Diode and IPL platforms dominate this high-frequency, repeat-visit category that anchors patient acquisition economics. Brisbane medical spas structure membership models around laser hair removal to secure recurring revenue streams.
- Skin Rejuvenation:Fractional and non-ablative modalities address photoaging and textural irregularities with variable downtime profiles. Sydney's competitive cosmetic corridor drives premium positioning for minimal-recovery protocols.
- Acne Scarring:Ablative fractional systems command elevated per-treatment pricing for atrophic and hypertrophic scar revision. Melbourne dermatology centers report strongest growth in this indication among patients aged 25-40.
- Pigmentation:Q-switched and picosecond technologies target solar lentigines, melasma, and tattoo removal. Adelaide clinics are expanding dedicated pigmentation service lines as patient awareness of specialized protocols rises.
Hair removal leads on scale; acne scarring leads on momentum.
End User:
Facility type determines capital deployment intensity, regulatory compliance burden, and reimbursement positioning for medically indicated versus cosmetic procedures.
- Medical Spas:Hybrid retail-clinical environments emphasizing high-throughput, minimally invasive aesthetic services. Victoria and New South Wales medical spas are capturing share from traditional dermatology referrals through direct-to-consumer marketing.
- Dermatology Centers:Physician-supervised facilities integrating laser platforms with comprehensive medical and cosmetic dermatology. These centers command premium pricing for complex indications requiring diagnostic expertise.
- Clinics:Independent or small-group practices with focused service menus and lower overhead structures. Regional Queensland clinics are consolidating through franchise networks to achieve procurement scale.
- Hospitals:Tertiary care settings deploying laser systems for medically necessary procedures including scar revision and vascular lesion treatment. Public hospital procurement cycles extend 18-24 months but secure multi-unit commitments.
Medical spas lead on scale; dermatology centers lead on momentum.
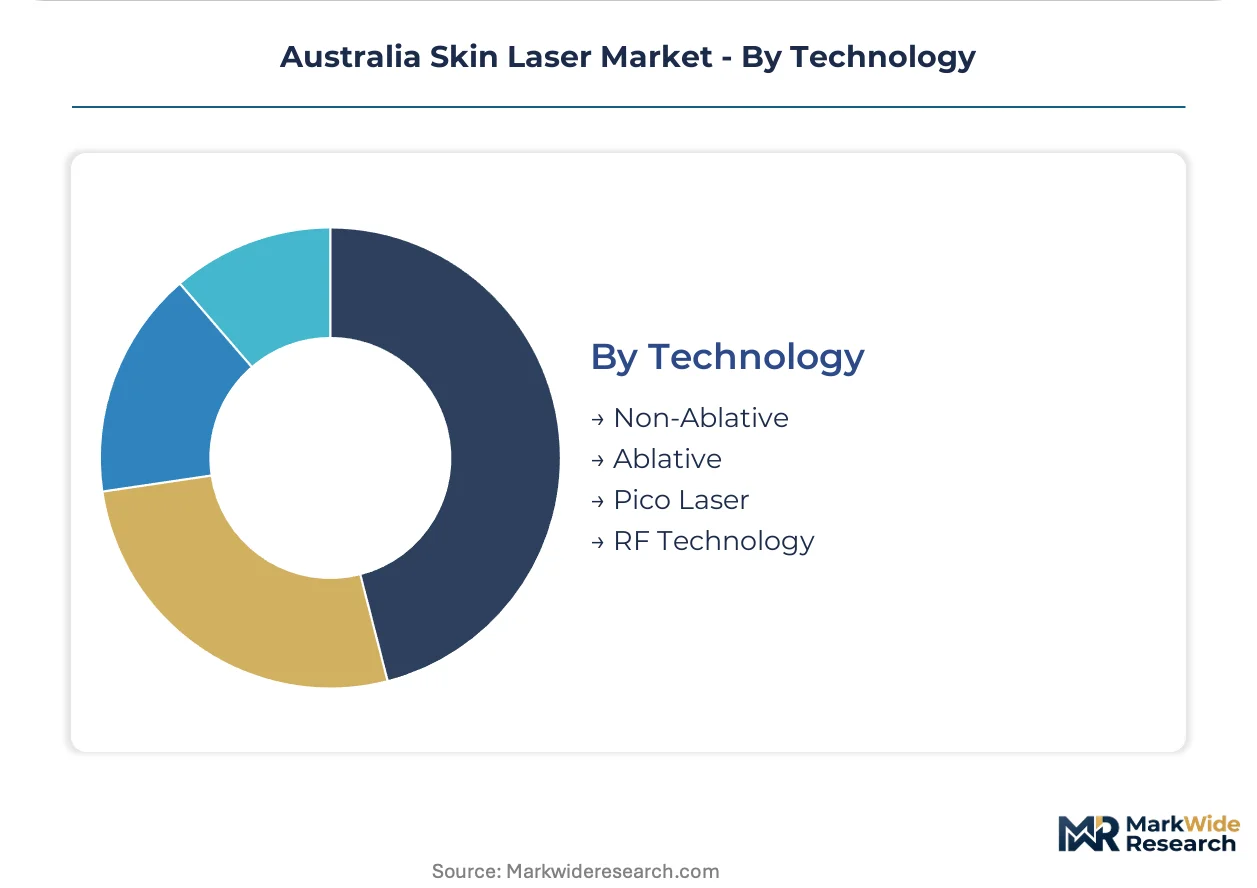
Technology:
Thermal mechanism and tissue interaction profile define safety margins, recovery intervals, and treatable patient populations across skin phototypes.
- Non-Ablative:Subsurface heating without epidermal disruption enables same-day social reintegration. First-time patients in Sydney's high-rent districts prioritize these protocols despite requiring multiple sessions.
- Ablative:Controlled vaporization of epidermal and superficial dermal layers delivers single-treatment efficacy for severe photoaging and scarring. Capital intensity and downtime limit deployment to major metropolitan chains.
- Pico Laser:Picosecond pulse duration creates photomechanical rather than photothermal effects for refractory pigmentation. Brisbane high-volume chains are deploying these systems as anchor differentiators.
- RF Technology:Radiofrequency energy complements optical modalities for skin tightening and collagen remodeling. Hybrid RF-laser platforms are gaining share in medical spa menus seeking protocol diversification.
Non-ablative leads on scale; pico laser leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne medical spa clusters anchor demand concentration for fractional and diode laser platforms, with regulatory compliance requirements filtering operator entry across state-level jurisdictions.
New South Wales
Sydney's cosmetic corridor drives premium positioning for non-ablative rejuvenation protocols among high-rent district clinics. ARPANSA facility licensing mandates professionalize channel entry, concentrating volume among credentialed networks. Eastern suburbs medical spas are expanding picosecond capacity for tattoo removal as millennial demand rises.
Victoria
Melbourne dermatology centers report strongest fractional laser adoption for acne scarring among patients aged 25-40. TGA medical device regulations compress registration timelines while elevating clinical evidence requirements, favoring established suppliers. Inner-city clinics are deploying telemedicine pre-consultation workflows to optimize device utilization.
Queensland
Brisbane high-volume chains favor IPL platforms for budget-conscious patient segments alongside membership-model hair removal services. State-based laser safety legislation requires operator certification that smaller regional operators struggle to meet. Gold Coast medical spas are consolidating through franchise networks to achieve procurement scale.
Western Australia
Perth exhibits underpenetrated dermatology infrastructure relative to eastern seaboard density, presenting first-mover positioning for platform suppliers. Longer-wavelength diode variants reduce adverse events across darker skin phototypes in multicultural urban corridors. Regional centers are adding Q-switched capacity as body-art prevalence drives dedicated service lines.
South Australia
Adelaide clinics are expanding dedicated pigmentation service lines as patient awareness of specialized protocols rises. Import dependency for consumables concentrates supply through limited distribution channels, exposing operators to currency fluctuation risk. Metropolitan dermatology centers prioritize suppliers with established Australian regulatory track records.
Australia Skin Laser Market Key Industry Players
Global majors compete with regional champions across regulatory affairs capabilities and clinical evidence portfolios, creating a tiered structure where established suppliers capture disproportionate share in New South Wales and Victoria dermatology centers. The vendor base separates into three strategic archetypes: multi-platform portfolio holders, specialized indication-focused suppliers, and emerging wavelength-technology developers. Dominant competitive moves include portfolio diversification into adjacent energy-based modalities and geographic expansion into underpenetrated western states.
Within the multi-platform tier, Alma Lasers and Cynosure occupy positions as anchor suppliers to metropolitan medical spa chains. Lutronic Corporation exemplifies the specialized-system archetype through its fractional CO2 positioning. These three entities represent the competitive core against which newer entrants must demonstrate TGA clearance efficiency and post-market surveillance capabilities.
| Leading Market Players |
|---|
| Alma Lasers |
| Cynosure |
| Cutera |
| Lumenis |
| Sciton |
| Lutronic Corporation |
| Fotona |
| Candela Medical |
| Aerolase |
| Others |
Cost & Logistics Intelligence
Platform certification tiers between TGA-cleared premium systems and uncertified economy alternatives create a bifurcated procurement landscape where supply chain reliability and pricing power diverge sharply across Sydney and Melbourne medical spa networks. Higher-tier devices command elevated upfront investment but secure preferential consumables allocation and service response times, while budget operators absorb currency fluctuation risk through concentrated import channels.
Pricing Analysis
Input-cost pass-through from laser source components and precision optics is intensifying margin pressure on fractional CO2 platforms, compressing distributor markups on high-capital systems. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ARPANSA certification status and after-sales bundling intensity. Cost compression in the economy tier is intensifying because smaller regional operators lack volume leverage against import-dependent consumables suppliers. Medical spa chains with multi-unit procurement scale exhibit lowest price sensitivity, while independent Perth clinics face acute budget constraints.
Supply Chain Analysis
Local-content-rule gaps in Australian medical device procurement expose operators to concentrated sourcing from Israel, the United States, and South Korea for solid-state laser sources and precision handpiece assemblies. Device manufacturing draws from specialized semiconductor foundries, rare-earth-doped fiber suppliers, and medical-grade cooling system fabricators. Single-source vulnerability concentrates in picosecond laser crystal supply, where limited qualified vendors create procurement bottlenecks. Distribution runs through authorized distributor networks with TGA-registered import licenses, concentrating channel control among established medical device specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA's streamlined clearance pathways function as a regulatory compounder, accelerating platform turnover cycles as ARPANSA facility mandates simultaneously elevate compliance barriers that filter undercapitalized competitors.
For Market Incumbents: To counter substitution by radiofrequency microneedling and intense pulsed light platforms, Alma Lasers and Cynosure must deepen backward integration into consumables production and secure exclusive service contracts with Victoria dermatology center chains. Channel control through dedicated regulatory affairs capabilities captures disproportionate share in credential-dependent markets. For New Entrants and Emerging Players: Begin with Western Australia's underpenetrated Perth corridor, where dermatology infrastructure density lags eastern seaboard benchmarks and longer-wavelength diode demand among multicultural patient populations creates first-mover positioning. Target picosecond tattoo removal service lines as a distinct revenue anchor, leveraging direct-to-consumer digital pre-consultation workflows to bypass established referral networks. For Investors and Strategic Acquirers: Consolidation pressure builds where ARPANSA-mandated laser safety officer scarcity strains smaller operator economics, creating distressed acquisition opportunities among regional Queensland and South Australia clinic networks. Mid-scale dermatology centers with established TGA clearance track records and integrated telemedicine infrastructure represent the optimal acquisition archetype. Watch picosecond platform adoption rates in Brisbane high-volume chains as the signal indicating technology transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Clearance Pathway Optimization | Compressed registration timelines accelerate platform upgrade cycles among established chains. |
| ARPANSA Certification Investment | Facility licensing mandates professionalize channel entry and filter undercapitalized competitors. |
| Consumables Backward Integration | In-house production of handpiece tips reduces currency exposure and secures margin control. |
| Telemedicine Pre-Consultation Deployment | Remote skin assessment workflows optimize device utilization in high-rent Sydney clinic locations. |
| Western Australia Geographic Expansion | Perth's underpenetrated infrastructure presents first-mover positioning for platform suppliers. |
Research Approach
Bottom-up medical spa and dermatology center modeling reconciled against top-down laser platform shipment tracking forms the analytical core of this study. Primary interviews with clinic operators, biomedical engineers, ARPANSA compliance officers, and medical device procurement managers combined with secondary validation from TGA device registration databases, ARPANSA facility licensing records, and Australian Bureau of Statistics healthcare expenditure data. Triangulation between installation base estimates and consumables import volumes anchors volume projections.
Historical trendline analysis across platform technology generations informed CAGR derivation through the projection horizon, with segmentation modeling across product type, application, end user, and technology dimensions. Treatment protocol evolution, skin phototype demographic shifts, and regulatory clearance velocity served as industry-specific forecast inputs. Price-point trajectories by certification tier and regional rent-cost differentials informed value projections.
Several conditions sit outside the modeled scope, including potential ARPANSA regulatory amendments, TGA reclassification of cosmetic versus medical indications, and macroeconomic currency fluctuations affecting import-dependent supply chains. Forecasts reflect documented assumptions regarding technology adoption curves and competitive response timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Common Warts Market
Dermatology
Dermatology Drugs Market
Dermatology
Microneedling Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Dermabrasion Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Global Onychomycosis Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Derma Rollers Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Global Hirsutism Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Acne Vulgaris Market
Dermatology
Skin Cancer Market