
 Acne Vulgaris Treatment Market | 2026-2036
Acne Vulgaris Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Vulgaris Treatment Market Analysis
The acne vulgaris treatment market is consolidating around a sharp split between premium biologic and prescription retinoid tiers and commodity benzoyl peroxide and salicylic acid offerings. Galderma leverages its vertical integration in topical dermatology to sustain pricing power across prescription and over-the-counter channels. Johnson & Johnson anchors the mass-market segment through broad retail distribution and consumer brand recognition.
Acne vulgaris treatment encompasses pharmacological and device-based interventions targeting pilosebaceous unit inflammation, with topical formulations typically containing retinoids, antimicrobials, or keratolytic agents in concentrations ranging from 0.025% to 10% depending on severity and tolerance. The primary purpose is reduction of lesion count, prevention of scarring, and improvement of psychosocial outcomes across adolescent and adult populations. Topical therapies occupy the largest volume share due to first-line prescribing patterns, while combination therapy captures expanding margin pools as clinicians seek to address antibiotic resistance and improve adherence. Light therapy segments are gaining traction fastest in dermatology clinics where capital equipment supports premium service bundling.
FDA oversees prescription acne drug approvals and labeling standards, while EMA's centralized procedure governs market access across European Union member states; both agencies have tightened requirements for long-term safety data on hormonal and isotretinoid therapies. The EU Green Deal and REACH frameworks additionally constrain excipient sourcing and packaging sustainability claims, forcing reformulation investments. Stakeholders must monitor evolving antibiotic stewardship guidelines from WHO and national regulators that threaten legacy oral tetracycline prescribing volumes while creating entry windows for non-antibiotic modalities.
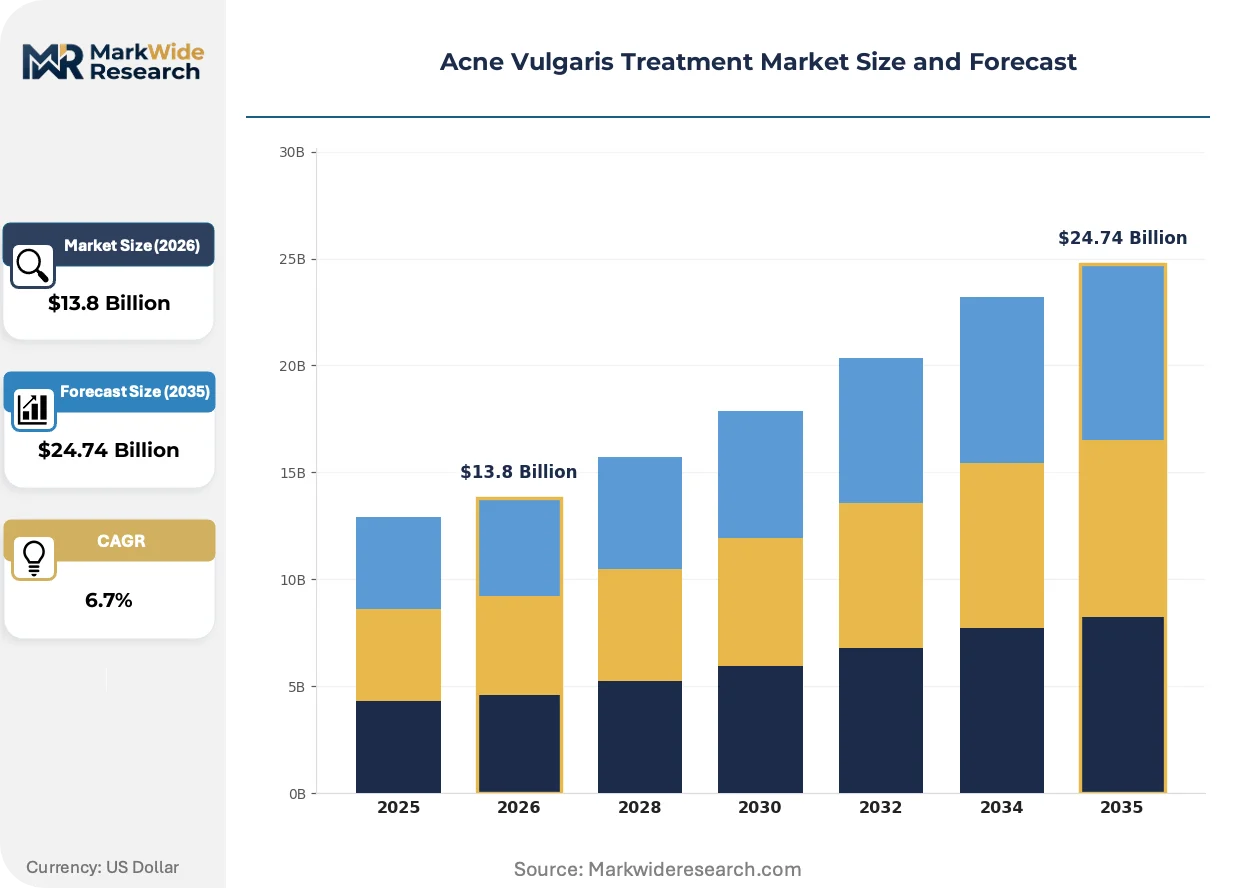
Market Dynamics
The acne vulgaris treatment market is restructuring around antibiotic stewardship mandates that systematically displace oral tetracycline prescriptions while elevating non-antibiotic topical and device-based alternatives into first-line protocols.
Growth Catalysts
- FDA's iPLEDGE REMS modernization:Streamlined isotretinoin risk management protocols reduce prescriber administrative burden and expand qualified provider pools for severe acne management.
- Dermatology clinic consolidation:Multi-site specialty groups in the United States deploy capital equipment for photodynamic and laser therapies, bundling procedural revenue with pharmaceutical dispensing.
- Adult acne recognition:Shifting diagnostic frameworks now capture persistent and late-onset presentations in patients aged 25-40, extending addressable patient lifecycles beyond adolescence.
Market Restraints
- Isotretinoin teratogenicity monitoring:Mandatory pregnancy prevention programs impose fixed compliance costs that constrain prescribing in female patients of reproductive potential.
- Retinoid API concentration:Three contract manufacturers in India and China supply the majority of topical and oral retinoid active pharmaceutical ingredients, creating single-source vulnerability.
- Fixed-dose combination stagnation:Patent cliffs on legacy adapalene-benzoyl peroxide formulations expose originators to immediate generic substitution without formulation differentiation.
Strategic Opportunities
- Telehealth prescribing expansion:Asynchronous dermatology platforms in the United States now qualify for reimbursement under select Medicaid plans, opening rural and underserved urban corridors.
- Microbiome-targeted therapeutics:Emerging C. acnes phage therapies and sebum-modulating biologics address antibiotic resistance without disrupting skin commensal populations.
- EU Green Deal packaging mandates:REACH-compliant recyclable tube and pump formats create first-mover positioning for sustainability-certified OTC and prescription brands.
Industry Challenges
- Formulation stability expertise:Retinoid oxidation and photodegradation chemistry requires specialized analytical capabilities scarce among mid-scale topical CDMOs.
- Combination therapy IP navigation:Freedom-to-operate analyses for novel fixed-dose pairings must thread densely overlapping method-of-treatment and formulation patents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Vulgaris Treatment Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.74 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical, Oral, Light Therapy, Combination Therapy End User: Dermatology Clinics, Hospitals, Homecare, Online Pharmacy Application: Men, Women, Adolescents, Adults Delivery Mode: Prescription, Over-the-Counter, Herbal, Injectable |
| Companies Covered | Galderma, Johnson & Johnson, Bausch Health Companies Inc., Bayer AG, Pfizer Inc., AbbVie Inc., Allergan, Sun Pharmaceutical Industries Ltd., GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Vulgaris Treatment Market Emerging Trajectories
Product architecture is fragmenting from monolithic blockbuster formulations toward configurable therapy stacks that clinicians assemble from component actives and delivery vehicles.
Personalized topical compounding technology is modularizing. Digital teledermatology platforms transmit lesion photography and sebum analysis to central pharmacies that produce patient-specific retinoid-antimicrobial-hydrator combinations within 48 hours. Dermatology groups in California and Texas pilot these workflows for moderate cases failing standard-of-care. The technology is modularizing prescriber-pharmacist relationships and compressing brand loyalty into ingredient-level preference.
EMA's tightened excipient safety guidelines under the Medical Device Regulation framework now classify certain topical vehicle components as co-active substances requiring separate toxicological dossiers. European manufacturers reformulate emulsion bases to exclude flagged penetration enhancers. The policy most affects legacy benzoyl peroxide gels with propylene glycol concentrations above threshold limits, forcing portfolio rationalization ahead of 2026 compliance deadlines.
Direct-to-consumer subscription models displace pharmacy fulfillment for maintenance-phase therapies. Patients receiving initial prescriptions through traditional channels convert to automated delivery for refill retinoids and gentle cleansers, bypassing retail markup. This pattern concentrates in United States metropolitan markets with established telehealth infrastructure and weak pharmacy benefit management controls on topical exclusions.
Acne Vulgaris Treatment Market Segmentation
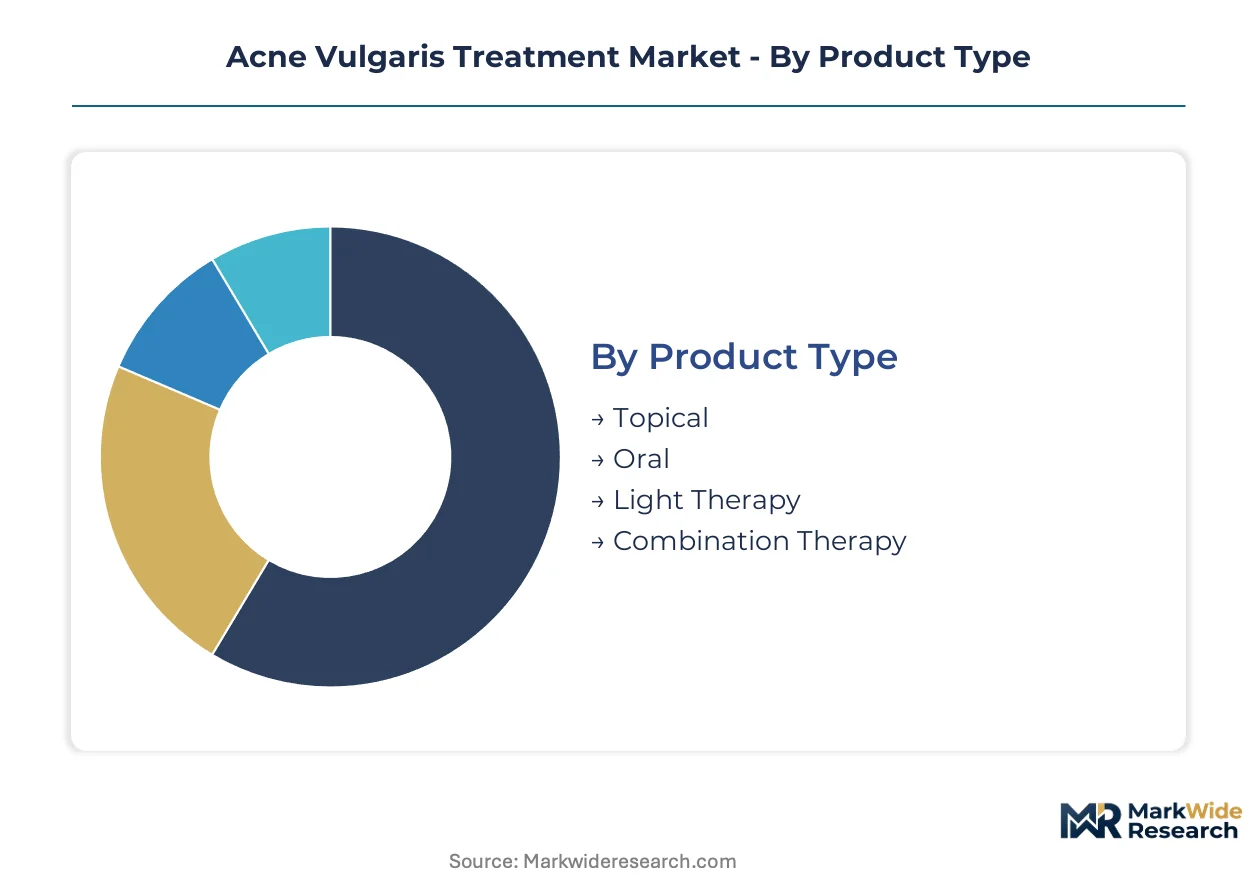
Acne vulgaris treatment segmentation reveals how supply chain configuration shapes competitive positioning across formulation types and access channels. Manufacturers align production assets with distinct regulatory pathways, reimbursement profiles, and patient adherence requirements.
Product Type:
Supply concentration in retinoid active pharmaceutical ingredients from Indian and Chinese contract manufacturers directly shapes competitive dynamics across formulation categories.
- Topical:Creams, gels, and lotions containing retinoids, benzoyl peroxide, or salicylic acid in concentrations from 0.025% to 10%. Demand concentrates in United States dermatology practices where first-line prescribing patterns favor localized delivery with minimized systemic exposure. Formulation stability expertise remains scarce among mid-scale CDMOs, constraining new entrant capacity.
- Oral:Systemic therapies including isotretinoin, tetracyclines, and hormonal agents targeting severe or refractory cases. Demand concentrates among female patients aged 25-40 with persistent adult acne, though isotretinoin teratogenicity monitoring limits prescribing in reproductive populations. FDA's iPLEDGE REMS modernization reduces administrative burden and expands qualified provider pools.
- Light Therapy:Photodynamic and laser-based interventions delivered through capital equipment in clinical settings. Dermatology clinic consolidation in California and Texas drives adoption through bundled procedural revenue models.
- Combination Therapy:Fixed-dose pairings of retinoids with antimicrobials or benzoyl peroxide. Patent cliffs on legacy adapalene-benzoyl peroxide formulations expose originators to immediate generic substitution without formulation differentiation.
Today's leader: Topical. Tomorrow's challenger: Combination Therapy.
End User:
Cost tier stratification separates premium clinical service delivery from commodity retail and direct-to-consumer channels.
- Dermatology Clinics:Multi-site specialty groups deploy capital equipment for photodynamic and laser therapies, bundling procedural revenue with pharmaceutical dispensing. United States metropolitan markets with established telehealth infrastructure support premium service line expansion for moderate-to-severe cases.
- Hospitals:Acute and referral centers manage severe nodulocystic presentations requiring isotretinoin initiation or antibiotic stewardship oversight. Volume concentrates in academic medical centers with specialized dermatology residency programs.
- Homecare:Self-administered maintenance regimens using OTC retinoids and gentle cleansers. Direct-to-consumer subscription models displace pharmacy fulfillment in United States markets with weak pharmacy benefit management controls on topical exclusions.
- Online Pharmacy:Asynchronous dermatology platforms now qualify for reimbursement under select United States Medicaid plans, opening rural and underserved urban corridors through automated delivery systems.
Volume concentrates in Dermatology Clinics. Margin expansion concentrates in Online Pharmacy.
Application:
Demographic recognition patterns are restructuring addressable patient lifecycles beyond traditional adolescent frameworks.
- Men:Late-onset and truncal presentations often underdiagnosed due to lower healthcare-seeking rates. Telehealth platforms reduce stigma barriers and expand screening capture.
- Women:Hormonal acne driven by androgen sensitivity and polycystic ovary syndrome associations. EMA's tightened excipient safety guidelines under Medical Device Regulation framework force reformulation of legacy hormonal delivery systems.
- Adolescents:Traditional peak incidence population with high lesion counts and psychosocial burden. School-based screening programs and pediatric dermatology referral networks concentrate volume in United States urban corridors.
- Adults:Persistent and late-onset presentations in patients aged 25-40 now explicitly captured in diagnostic frameworks. This segment gains share fastest as clinicians extend maintenance therapy durations and address antibiotic resistance through non-antibiotic modalities.
Adolescents anchor current volume. Adults drive the steepest expansion trajectory.
Delivery Mode:
Regulatory pathway complexity creates tiered market access with distinct compliance architectures and competitive moats.
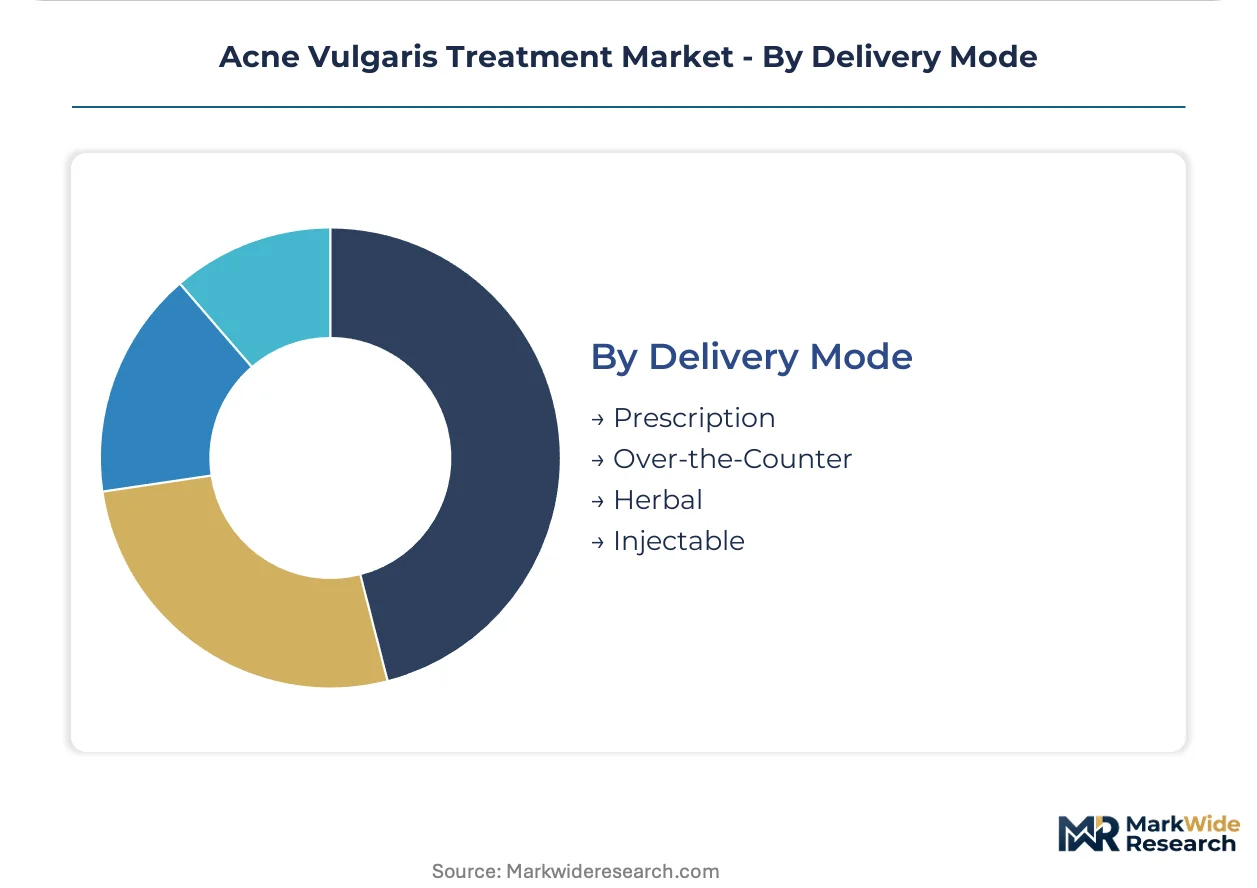
- Prescription:FDA and EMA pathways for novel retinoid and biologic formulations reshape product approval timelines. Mandatory pregnancy prevention programs for isotretinoin impose fixed compliance costs that constrain prescribing in female patients of reproductive potential.
- Over-the-Counter:Benzoyl peroxide and salicylic acid formulations distributed through mass retail. Johnson & Johnson anchors this segment through broad distribution and consumer brand recognition.
- Herbal:Botanical extracts and traditional medicine approaches with variable regulatory status across jurisdictions. REACH-compliant sourcing requirements under EU Green Deal constrain excipient availability and packaging sustainability claims.
- Injectable:Emerging biologic and microbiome-targeted modalities including C. acnes phage therapies. Sebum-modulating biologics address antibiotic resistance without disrupting skin commensal populations.
Prescription commands pricing power. Injectable represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dermatology talent clusters in the United States and Western Europe anchor premium acne therapy development, while Asian manufacturing hubs supply retinoid active pharmaceutical ingredients at scale.
United States
Dermatology residency programs at academic medical centers in Boston and New York Metro generate specialized prescribers for isotretinoin and biologic therapies. FDA's iPLEDGE REMS modernization streamlines risk management protocols for female patients of reproductive potential. Multi-site specialty groups in California and Texas deploy capital equipment for photodynamic therapy, bundling procedural revenue with pharmaceutical dispensing.
Germany
Pharmaceutical formulation expertise concentrated in Baden-Württemberg and North Rhine-Westphalia supports complex topical delivery system development. EMA's centralized procedure under REACH frameworks governs excipient safety dossiers for benzoyl peroxide gels. Industrial clusters around Frankfurt and Munich host CDMOs specializing in retinoid stability chemistry for European market access.
India
Contract manufacturing organizations in Gujarat and Maharashtra produce the majority of global topical and oral retinoid active pharmaceutical ingredients. CDSCO oversight of generic isotretinoin exports shapes quality certification requirements for destination markets. Hyderabad and Ahmedabad manufacturing corridors face single-source vulnerability concentration that threatens supply continuity.
China
NMPA regulatory pathways for novel retinoid formulations extend approval timelines compared to Western benchmarks. Yangtze River Delta chemical manufacturing bases supply benzoyl peroxide and salicylic acid precursors at commodity scale. Shanghai and Suzhou industrial parks host joint ventures between domestic API producers and multinational dermatology companies seeking backward integration.
United Kingdom
Adult acne recognition in NHS diagnostic frameworks extends addressable patient lifecycles beyond traditional adolescent cohorts. MHRA post-Brexit regulatory autonomy creates divergence from EMA centralized procedures for topical combination therapies. London and Southeast England dermatology clinics pilot teledermatology platforms qualifying for asynchronous reimbursement under evolving primary care contracts.
Acne Vulgaris Treatment Market Vendor Landscape
Top-tier vendors anchor prescription retinoid and biologic tiers, while commodity benzoyl peroxide and salicylic acid producers compete on manufacturing scale and retail distribution reach. The vendor base stratifies across three archetypes: vertically integrated dermatology specialists with captive R&D pipelines, mass-market consumer health conglomerates with pharmacy channel dominance, and generic API-to-formulation manufacturers competing on cost. Consolidation pressure concentrates in the mid-tier, where patent cliffs on legacy fixed-dose combinations expose originators to immediate substitution. Dominant competitive moves include dermatology clinic acquisition for vertical dispensing integration and microbiome therapeutic platform licensing.
Within the prescription dermatology archetype, Galderma exemplifies vertical integration across topical development, manufacturing, and clinical channel deployment. Johnson & Johnson occupies a position representing mass-market consumer health scale with pharmacy and retail distribution infrastructure. Sun Pharmaceutical Industries Ltd. anchors the generic API-to-formulation tier with manufacturing concentration in Indian chemical corridors serving export markets.
| Leading Market Players |
|---|
| Galderma |
| Johnson & Johnson |
| Bausch Health Companies Inc. |
| Bayer AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Allergan |
| Sun Pharmaceutical Industries Ltd. |
| GlaxoSmithKline |
| Others |
Supply Flow & Price Mechanics
Captive API sourcing from Indian and Chinese contract manufacturers anchors pricing power for vertically integrated dermatology specialists while exposing mid-tier formulators to margin compression when retinoid concentrate costs fluctuate. This upstream control dynamic separates premium prescription tiers from commodity OTC offerings.
Pricing Analysis
Bundled procedural-plus-pharmaceutical service models in dermatology clinics command premium capture against unbundled pharmacy fulfillment for maintenance therapies. Three-tier pricing structure across premium biologic, standard prescription retinoid, and economy benzoyl peroxide tiers reflects formulation complexity and channel control. Cost compression in the OTC tier intensifies as direct-to-consumer subscriptions bypass retail markup. Price sensitivity concentrates among adolescent patients and cash-pay segments, while insured adults aged 25-40 show tolerance for premium positioning.
Supply Chain Analysis
Retinoid active pharmaceutical ingredient supply rests on contract manufacturing corridors in Gujarat and Maharashtra, India, plus Yangtze River Delta chemical bases in China. Benzoyl peroxide and salicylic acid precursors feed from these same manufacturing clusters. Single-source vulnerability threatens continuity when geopolitical friction disrupts cross-border certification flows. Distribution runs through dermatology clinic dispensing, mass retail pharmacy, and automated direct-to-consumer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acne vulgaris treatment functions as a regulatory compounder where FDA's iPLEDGE REMS modernization expanded qualified prescriber pools and reshaped competitive access for severe acne management.
For Market Incumbents: Extend formulation stability capabilities through captive CDMO relationships or acquisition of specialized retinoid chemistry expertise in Baden-Württemberg and North Rhine-Westphalia clusters. Patent cliffs on legacy adapalene-benzoyl peroxide combinations expose originators to immediate generic substitution; defend through microbiome therapeutic platform licensing and dermatology clinic vertical dispensing integration. For New Entrants and Emerging Players: The price-point gap between premium biologic injections and economy OTC topicals creates entry space for mid-tier prescription retinoids with differentiated delivery vehicles. Target adult acne recognition in NHS and select Medicaid frameworks where reimbursement access is expanding. Enter through asynchronous telehealth platforms qualifying for automated delivery reimbursement. For Investors and Strategic Acquirers: Roll-up economics work for microbiome-targeted therapeutic platforms because antibiotic stewardship mandates are systematically displacing oral tetracycline volumes and creating replacement demand for non-antibiotic modalities. Long-term viability hinges on pipeline depth against resistance mechanisms. Watch EMA excipient safety guideline enforcement as inflection indicator for European portfolio rationalization requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Platform Licensing | C. acnes phage therapies address antibiotic resistance without disrupting skin commensal populations. |
| Dermatology Clinic Acquisition | Vertical dispensing integration captures procedural revenue bundling with pharmaceutical fulfillment. |
| Telehealth Platform Expansion | Asynchronous reimbursement under select Medicaid plans opens rural and underserved urban corridors. |
| Green Packaging Transition | REACH-compliant recyclable formats create first-mover positioning for sustainability-certified brands. |
| Retinoid Stability CDMO Investment | Specialized analytical capabilities remain scarce among mid-scale topical contract manufacturers. |
Methodological Framework
Multiple input streams — primary interviews with dermatology practice administrators, formulary directors at managed care organizations, and regulatory affairs leads at topical formulation developers — were reconciled against secondary validation from FDA filings, EMA centralized procedure submissions, ClinicalTrials.gov entries, and dermatology clinic equipment procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored the analytical framework.
Data-stream reconciliation across product type, end user channel, patient demographic application, and delivery mode segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from patient population expansion rates, therapy penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporated iPLEDGE REMS prescriber pool expansion metrics and antibiotic stewardship guideline adoption curves.
Caveats apply where EMA excipient safety enforcement, retinoid API supply disruptions, or telehealth reimbursement policy reversals could materially shift the outlook. Forecasts reflect documented assumptions about regulatory pathway timelines and patient adherence patterns. A small set of named triggers — CDSCO export certification changes, REACH packaging compliance deadlines, and Medicaid asynchronous platform reimbursement decisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Hirsutism Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Scleroderma Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Derma Rollers Market
Dermatology
Australia Skin Laser Market
Dermatology
Immunodermatology Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Dermatological Products Market
Dermatology
Keloid Treatment Market