
 Seborrheic Keratosis Market | 2026-2036
Seborrheic Keratosis Market Size, Share, and Industry Trends Forecast 2026-2036
Seborrheic Keratosis Market Outlook
CE marking under the EU Medical Device Regulation is unwinding competitive access for non-European laser and energy-based device manufacturers seeking European distribution. Aclaris Therapeutics leverages its topical drug development platform to compete in prescription treatment segments. Lumenis anchors its position through installed-base dominance in dermatology laser systems across North American clinics. Alma Lasers extends its reach via cost-optimized platforms targeting ambulatory surgical centers in price-sensitive markets.
Seborrheic keratosis comprises benign epidermal proliferations characterized by acanthotic keratinocyte clusters with horn cyst formation, typically presenting as waxy, stuck-on plaques ranging from millimeters to several centimeters in diameter. These lesions drive clinical intervention for diagnostic confirmation, symptomatic relief from pruritus or bleeding, and cosmesis, with histopathological verification remaining standard when atypical features appear. Laser therapy segments command premium positioning due to precision ablation and reduced scarring profiles, while cryotherapy sustains volume leadership through low per-procedure cost and minimal infrastructure requirements. Topical treatments represent the fastest-expanding category as patients seek non-invasive alternatives, though margin pools remain concentrated in device-mediated procedures performed in clinical settings.
FDA 510(k) pathways govern device commercialization, while EPA oversight applies to cryogen formulations used in dermatologic freezing procedures, creating layered compliance burdens for multi-modality suppliers. The EU MDR and FDA quality system regulations are forcing consolidation in device manufacturing as smaller entrants lack resources for dual-territory certification. Stakeholders must monitor reimbursement coding shifts for lesion destruction procedures, as payer classification between cosmetic and medically necessary indications directly determines addressable market expansion.
Market Dynamics
The dermatology device sector faces intensifying regulatory compression as FDA 510(k) pathways tighten evidentiary standards for ablative technologies while EU MDR transition costs filter smaller manufacturers from European distribution networks.
Growth Catalysts
- Cosmetic Reimbursement Arbitrage:United States payers increasingly classify symptomatic lesion removal as medically necessary, expanding procedural volumes beyond pure out-of-pocket cosmetic demand.
- Topical Formulation Advances:Hydrogen peroxide-based prescription therapies receive priority review designations from FDA, creating non-invasive alternatives that expand addressable patient populations.
- Ambulatory Site Migration:Office-based surgical centers in Germany and France deploy compact laser platforms, capturing cases from hospital outpatient departments through lower facility fees.
Market Restraints
- Dual-Territory Certification Costs:EU MDR technical documentation requirements and FDA quality system regulations impose parallel compliance burdens exceeding €2 million for novel device entrants.
- Substitute Modality Competition:Cryotherapy sustains volume leadership through minimal capital requirements, pressuring laser manufacturers to justify premium pricing through outcome differentiation.
- Input Supply Concentration:Solid-state laser crystal production concentrates among Japanese and German optical component suppliers, creating vulnerability for device assemblers without captive supply arrangements.
Strategic Opportunities
- Underpenetrated Primary Care Integration:United Kingdom general practitioners seek lesion destruction capabilities through compact cryogenic devices, bypassing specialist referral bottlenecks.
- Technology Convergence:Artificial intelligence-powered dermoscopy integration with ablative platforms enables real-time margin assessment, reducing histopathological verification requirements.
- Direct-to-Patient Channel Development:Telehealth platforms in Australia facilitate remote lesion triage, channeling appropriate cases toward procedural intervention while filtering benign mimickers.
Industry Challenges
- Specialized Technician Scarcity:Laser safety certification programs fail to match deployment rates of new ablative devices, constraining utilization at expanded clinic sites.
- Legacy EMR Integration Friction:Procedural documentation requirements for lesion destruction coding clash with existing dermatology practice management systems, delaying reimbursement capture.
- IP Licensing Complexity:Patent thickets around fractional laser delivery mechanisms force device manufacturers into costly cross-licensing arrangements or design-around engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seborrheic Keratosis Market |
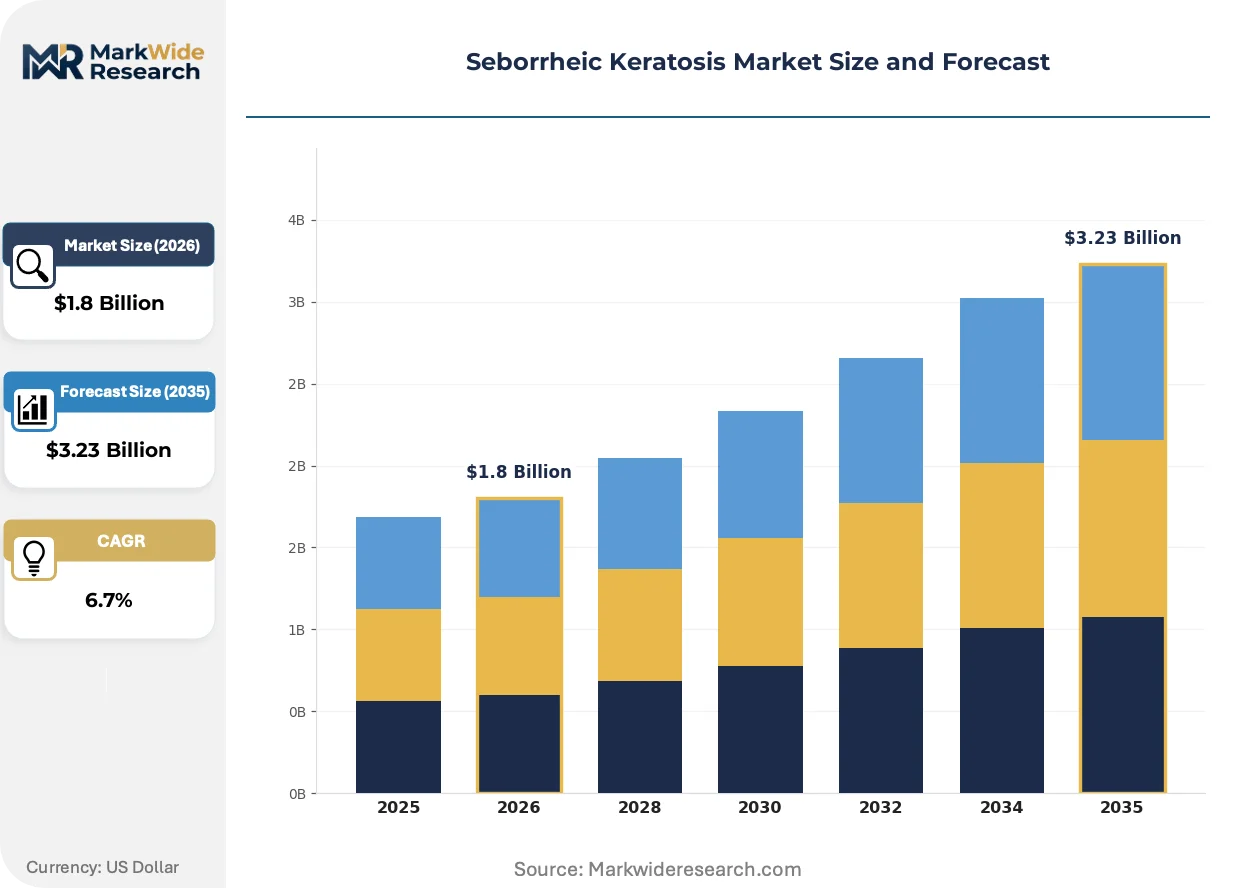
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryotherapy, Curettage, Laser Therapy, Topical Treatments End User: Dermatology Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Technology: Radiofrequency, Photodynamic Therapy, Electrosurgery, Chemical Peels Formulation: Creams, Gels, Solutions, Ointments |
| Companies Covered | Aclaris Therapeutics, Lumenis, Bausch Health Companies, AbbVie, Cutera, Alma Lasers, Becton Dickinson, Quanta Systems, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seborrheic Keratosis Market Strategic Shifts
Device-mediated lesion management confronts a technology transition where precision ablation tools compete against pharmaceutical alternatives, while regulatory frameworks on both sides of the Atlantic reshape competitive access conditions.
Picosecond laser systems is displacing nanosecond platforms in premium dermatology clinics across the United States. These ultrafast pulse durations minimize thermal diffusion to surrounding tissue, enabling treatment of darker skin phototypes without post-inflammatory hyperpigmentation risk. Academic medical centers in Boston and San Francisco report adoption curves compressing from five-year to eighteen-month cycles as patient demand for reduced downtime intensifies.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all Class IIa and above dermatology devices, including retrospective data on legacy laser platforms. Manufacturers with products already CE-marked under the Medical Device Directive face substantial conformity assessment costs to maintain European market access. German notified bodies report application backlogs exceeding fourteen months, forcing strategic prioritization of high-revenue device lines over accessory portfolios.
Patient-initiated lesion assessment through smartphone dermoscopy attachments is redirecting diagnostic workflows in Australian and Canadian markets. Primary care networks now receive pre-triaged cases with structured image documentation, compressing specialist consultation requirements for obvious benign presentations. This behavioral shift concentrates procedural demand at high-throughput ambulatory sites capable of same-day diagnosis and treatment, marginalizing traditional referral-based practice models.
Seborrheic Keratosis Market Segmentation
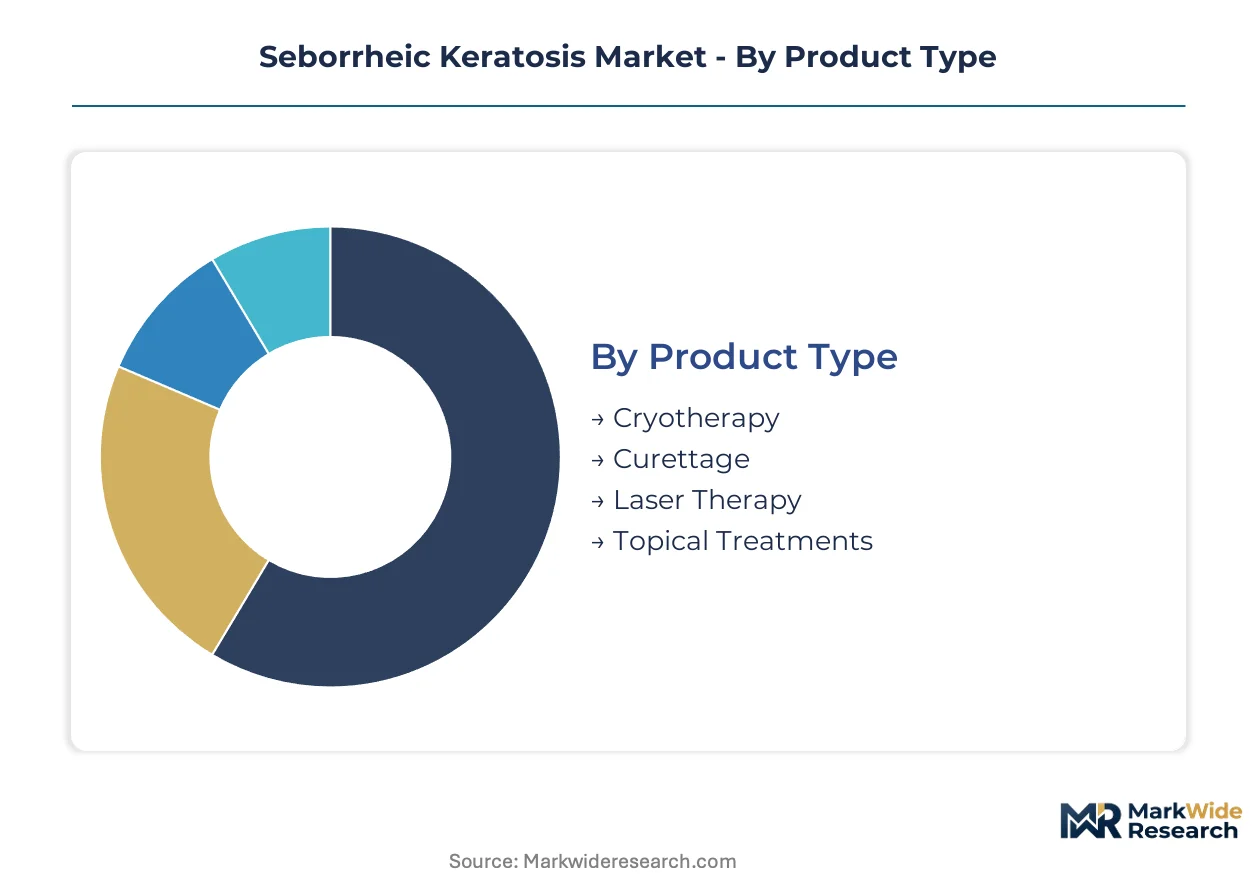
Segmentation in the seborrheic keratosis market reveals distinct procurement patterns across clinical and consumer channels. Treatment modality selection depends heavily on reimbursement classification, capital availability, and patient preference for invasive versus non-invasive intervention.
Product Type:
Cryotherapy and laser platforms dominate United States clinic procurement, while topical formulations concentrate in European pharmacy dispensing and direct-to-patient channels.
- Cryotherapy:Liquid nitrogen or cryogen spray devices deliver rapid lesion destruction through controlled tissue freezing. Demand concentrates in United States dermatology clinics where Medicare reimbursement codes support symptomatic lesion removal. The modality sustains volume leadership through minimal capital requirements and same-day procedure completion.
- Laser Therapy:Ablative and fractional laser systems enable precision keratinocyte ablation with tunable depth control. Adoption clusters in affluent United States metropolitan markets where patients prioritize cosmetic outcomes and reduced scarring profiles over cost minimization.
- Curettage:Mechanical scraping with electrosurgical control remains a staple in hospital outpatient departments requiring histopathological specimen retrieval.
- Topical Treatments:Hydrogen peroxide-based prescription formulations expand through Australian and Canadian telehealth channels serving patients seeking non-invasive alternatives.
Cryotherapy commands the established base. The steepest expansion runs through topical treatments.
End User:
Site-of-care migration is redistributing procedural volume from hospital systems toward lower-acuity settings with compressed facility fees.
- Dermatology Clinics:Specialized practices in Germany and France deploy multi-modality platforms offering same-day diagnosis and treatment. These sites capture premium pricing through outcome guarantees and reduced recurrence rates.
- Ambulatory Surgical Centers:Office-based surgical facilities in Texas and Florida leverage streamlined credentialing to perform high-volume lesion destruction. Lower overhead structures enable competitive pricing against hospital outpatient departments.
- Hospitals:Academic medical centers retain complex cases requiring histopathological verification or concurrent dermatologic surgery.
- Home Care:Over-the-counter cryogenic devices and cosmetic skin tag removers penetrate United States retail pharmacy chains, though regulatory boundaries limit claims for seborrheic keratosis specifically.
Dermatology clinics anchor revenue concentration. Ambulatory surgical centers are gaining share fastest through site-of-care arbitrage.
Technology:
Energy-based modalities stratify by tissue interaction mechanism, with thermal versus photochemical approaches serving distinct lesion characteristics and patient tolerances.
- Radiofrequency:High-frequency alternating current generates localized thermal necrosis with minimal collateral damage. United States device manufacturers emphasize precision tip designs for facial lesion applications where scarring risk carries highest patient concern.
- Photodynamic Therapy:Photosensitizer activation with specific wavelength light enables selective keratinocyte destruction. German dermatology research centers investigate combination protocols for extensive or recalcitrant lesions.
- Electrosurgery:Blend and cutting modes persist in cost-sensitive clinic environments with legacy equipment depreciation.
- Chemical Peels:Trichloroacetic acid formulations serve superficial seborrheic keratosis in cosmetic dermatology practices seeking procedure bundling opportunities.
Radiofrequency holds the installed base advantage. Photodynamic therapy is climbing the fastest through academic center protocol development.
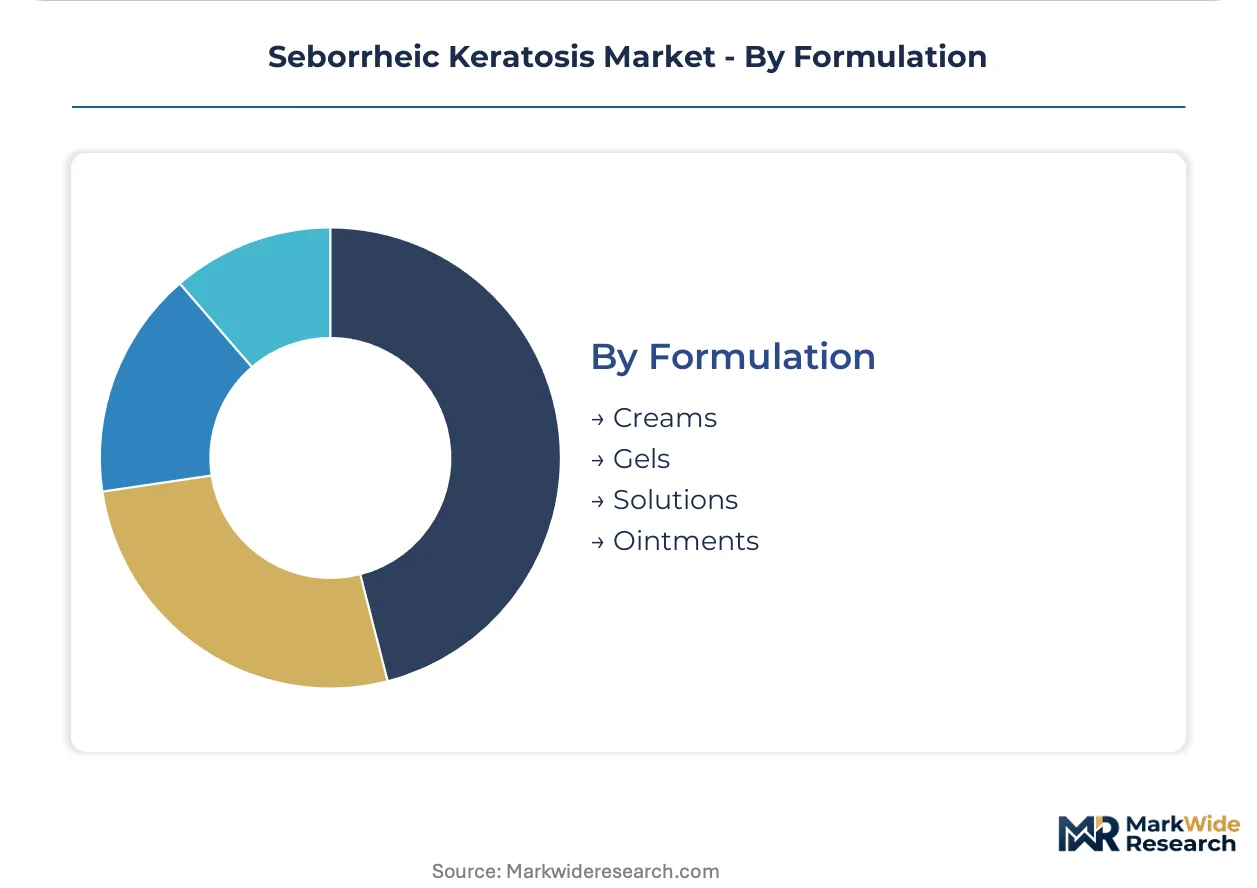
Formulation:
Topical drug delivery formats align with patient compliance patterns and lesion anatomical distribution across body sites.
- Solutions:Alcohol-based liquid formulations enable precise application to discrete facial lesions. United States prescription launches emphasize pen-applicator designs for controlled dosing.
- Creams:Emulsion-based vehicles suit trunk and extremity applications where larger surface areas require spreadable coverage. European pharmacy networks stock compounded alternatives where regulatory pathways delay commercial product availability.
- Gels:Hydrogel matrices provide non-greasy cosmetic elegance for visible body sites.
- Ointments:Occlusive petrolatum-based preparations serve hyperkeratotic lesions requiring enhanced penetration.
Solutions lead prescription volume through precision application. Creams are expanding most quickly through pharmacy channel breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European distribution of cryogenic dermatology supplies, while direct air freight corridors from Cincinnati/Northern Kentucky International Airport sustain rapid device deployment across North American clinic networks.
United States
Medicare reimbursement expansion for symptomatic lesion removal drives procedural volumes in dermatology clinics. FDA 510(k) pathway modifications compress clearance timelines for novel ablative devices. Boston and San Francisco academic medical centers anchor adoption curves for picosecond laser platforms.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia capture cases from hospital outpatient departments through lower facility fees. EU MDR notified body backlogs exceeding fourteen months force manufacturers to prioritize high-revenue device lines. Frankfurt dermatology research clusters advance photodynamic therapy protocol development.
France
ANSM oversight of medical device vigilance reporting shapes post-market surveillance requirements for laser manufacturers. Paris and Lyon metropolitan practices deploy multi-modality platforms offering same-day diagnosis and treatment. Primary care networks seek compact cryogenic devices to bypass specialist referral bottlenecks.
Australia
TGA regulatory frameworks govern prescription topical formulations entering pharmacy channels. Sydney and Melbourne telehealth platforms facilitate remote lesion triage, channeling appropriate cases toward procedural intervention. Smartphone dermoscopy attachments redirect diagnostic workflows toward high-throughput ambulatory sites.
Canada
Health Canada/PMRA joint oversight applies to cryogen formulations and energy-based devices. Ontario and British Columbia primary care networks receive pre-triaged cases with structured image documentation. Same-day diagnosis and treatment capabilities concentrate procedural demand at specialized ambulatory centers.
Seborrheic Keratosis Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory sophistication dimensions. The vendor base stratifies between diversified medical device conglomerates and focused dermatology equipment fabricators. Three archetypes dominate: installed-base incumbents leveraging service revenue streams, platform specialists optimizing for ambulatory surgical center procurement, and pharmaceutical developers advancing topical alternatives. Competitive moves center on M&A for regulatory capabilities and strategic partnerships for distribution reach.
Among Israel-based laser system developers, Lumenis occupies a position exemplifying installed-base dominance in North American dermatology clinics. Alma Lasers, also Israel-based, represents the cost-optimized platform archetype targeting price-sensitive ambulatory markets. Aclaris Therapeutics, a U.S.-based pharmaceutical developer, anchors the prescription topical treatment segment competing against device-mediated procedures.
| Leading Market Players |
|---|
| Aclaris Therapeutics |
| Lumenis |
| Bausch Health Companies |
| AbbVie |
| Cutera |
| Alma Lasers |
| Becton Dickinson |
| Quanta Systems |
| AngioDynamics |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month notified body backlogs for EU MDR recertification compress inventory turnover for laser device manufacturers, concentrating pricing power with Japanese and German optical component suppliers who command premium terms from assembly firms lacking captive sourcing.
Pricing Analysis
Volume-discount tiering structures separate premium picosecond laser platforms from standard nanosecond systems and economy cryotherapy devices. Price differentiation hinges on FDA 510(k) clearance tier and bundled service contracts. Pricing pressure intensifies as topical hydrogen peroxide formulations capture pharmacy channel volume. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize outcome guarantees over cost minimization.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes solid-state laser crystal shipments from Japanese and German optical houses to Middle Eastern distribution hubs. Device assembly draws from concentrated rare-earth mineral processing in China and specialized coating services in South Korea. Single-source vulnerability persists for ytterbium-doped gain media. Distribution runs through direct air freight from Cincinnati/Northern Kentucky International Airport to North American clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face substitution defense imperatives as prescription topical therapies expand through telehealth channels, threatening procedural volume capture in cosmetic-sensitive patient segments.
For Market Incumbents: Fortify installed-base lock-in through extended service contracts and software companion development for dermoscopy integration. Laser platform specialists should secure captive supply arrangements with Japanese crystal growers to offset input concentration risk. Defensive patent licensing around fractional delivery mechanisms preserves margin pools against emerging radiofrequency competitors.
For New Entrants and Emerging Players: FDA 510(k) priority review pathways for topical formulations offer fastest regulatory traction against device-dominated incumbents. White-space concentration sits with compact cryogenic devices for United Kingdom primary care networks seeking lesion destruction capabilities. Telehealth-integrated triage platforms in Australian and Canadian markets provide channel access with reduced specialist referral friction.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because dual-territory certification costs exceeding two million euros filter subscale device manufacturers from European and North American markets. Acquisition targets should display existing FDA 510(k) portfolios or EU MDR technical documentation completion. Monitor reimbursement coding shifts for symptomatic lesion removal as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance pathways compress competitive entry timelines for ablative device innovators. |
| CE Marking Pathway | EU MDR Article 10 compliance determines sustained access to German and French clinic procurement. |
| Hospital System Partnership | GPO contracts with United States dermatology networks secure high-volume procedural placement. |
| Software Companion Development | AI-powered dermoscopy integration differentiates premium laser platforms through real-time margin assessment. |
| Reimbursement Strategy | Medicare coding advocacy for symptomatic lesion removal expands addressable patient populations beyond cosmetic payers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA device vigilance reports, and hospital procurement databases. Dermatology practice administrators, biomedical engineers, and GPO contract managers provided operational perspective. CMS Medicare claims data and EU MDR notified body disclosure records supplied volume and regulatory validation. Bottom-up procedure counts triangulate against top-down manufacturer shipment estimates.
Segmentation dimensions modeled include treatment modality, site-of-care tier, and technology platform type across the analysis window. CAGRs derive from procedure volume trajectories weighted by reimbursement classification shifts and device replacement cycles. Forecast inputs incorporate EU MDR transition cost absorption rates and topical formulation pharmacy channel penetration curves.
Decision-makers should treat outputs as directional under stable regulatory pathway assumptions; material deviation in FDA evidentiary standards or EU notified body capacity would warrant model refresh. Practitioners should keep alternative scenarios live as hydrogen peroxide therapy efficacy data and payer cosmetic-medical necessity boundary shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Scar Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Microneedling Market
Dermatology
Derma Rollers Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Dermatology Devices Market
Dermatology
China Scar Treatment Market
Dermatology
Acne Scar Treatment Market
Dermatology
Keratoacanthoma Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Microdermabrasion Market
Dermatology
Saudi Arabia Hair Transplant Market