
 Erythema Treatment Market | 2026-2036
Erythema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Erythema Treatment Market Foresight
Project finance for phototherapy equipment is tilting competitive dynamics toward asset-light clinic networks that avoid heavy capital outlays. Pfizer Inc. leverages its scale in corticosteroid manufacturing to sustain supply chain efficiencies across hospital systems. AbbVie Inc. anchors its position through R&D intensity in immunomodulator pipelines. Galderma S.A. specializes in topical agent formulations that dermatology clinics favor for rosacea protocols.
Erythema treatment encompasses pharmacological and physical interventions targeting cutaneous redness, inflammation, and vascular dilation through mechanisms such as vasoconstriction, immune suppression, or selective photothermolysis using wavelengths between 585 and 595 nanometers. These therapies serve to reduce symptomatic flushing, prevent disease progression, and restore barrier function in conditions ranging from rosacea to photodamage. Corticosteroids and immunomodulators command the largest current revenue pools due to established reimbursement pathways, while phototherapy segments exhibit the fastest structural growth as clinics invest in narrowband UVB and pulsed-dye laser platforms. Topical agents retain strong margin profiles in homecare channels where patient self-administration reduces clinical overhead.
The FDA and EMA jointly shape formulation standards through bioequivalence requirements for topical generics and safety monitoring for corticosteroid potency classifications, directly influencing which products gain market access. Health Canada and the TGA enforce parallel labeling standards that manufacturers must navigate for multi-territory launches. Stakeholders should monitor how regulators reconcile emerging real-world evidence with traditional trial endpoints for laser-based interventions.
Market Dynamics
The FDA's evolving guidance on topical immunomodulators is compressing formulation timelines while dermatology clinics accelerate phototherapy capital deployment to capture rising patient volumes. This regulatory-clinical tension is redistributing margin pools between pharmaceutical manufacturers and service-based providers.
Growth Catalysts
- Narrowband UVB phototherapy:Dermatology clinics in the United States are expanding service lines as reimbursement pathways stabilize for in-office light-based interventions.
- EMA bioequivalence requirements:Streamlined generic topical approvals are expanding patient access to corticosteroid alternatives across European markets.
- Rosacea protocol specialization:Targeted topical agent development is concentrating R&D investment in vascular-specific mechanisms.
Market Restraints
- Phototherapy equipment costs:Pulsed-dye laser platforms require substantial capital outlay, limiting deployment to well-capitalized hospital systems.
- Corticosteroid potency classifications:FDA safety monitoring creates formulation complexity that extends development cycles for new topical entrants.
- Specialized dermatology network concentration:Treatment demand clusters in urban United States markets, leaving rural access gaps.
Strategic Opportunities
- Homecare channel expansion:Patient self-administration of topical agents reduces clinical overhead and captures recurring revenue streams.
- Real-world evidence integration:Laser-based interventions are gaining regulatory acceptance through post-market surveillance data.
- Asset-light clinic networks:Equipment leasing models are enabling mid-tier dermatology practices to compete without heavy balance-sheet investment.
Industry Challenges
- Phototherapy technician certification:Operating narrowband UVB and laser platforms requires specialized training that outpaces workforce supply.
- Multi-territory labeling compliance:Manufacturers must reconcile FDA, EMA, Health Canada, and TGA standards for simultaneous market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erythema Treatment Market |
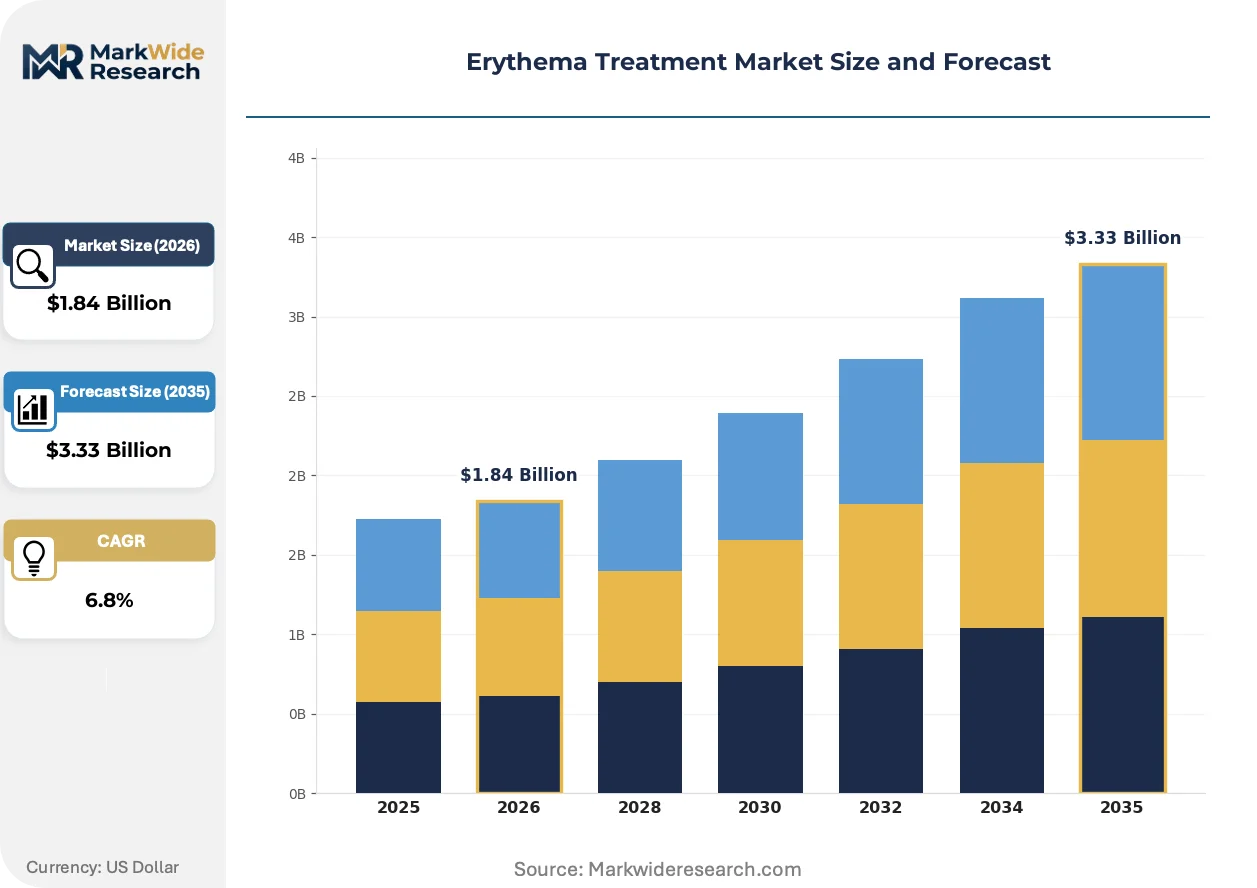
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunomodulators, Phototherapy, Topical Agents Application: Psoriasis, Rosacea, Dermatitis, Vascular Lesions Delivery Mode: Topical, Injectable, Oral, Laser End User: Hospitals, Dermatology Clinics, Homecare Settings, Research Centers |
| Companies Covered | Pfizer Inc., Novartis AG, AbbVie Inc., Galderma S.A., Bausch Health Companies Inc., Astellas Pharma Inc., LEO Pharma A/S, Sanofi S.A., Regeneron Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erythema Treatment Market Shifts & Advancements
Selective photothermolysis at 585-595 nanometer wavelengths is compressing treatment protocols while raising efficacy benchmarks. This technological pivot is forcing simultaneous adaptation across device manufacturers, clinic operators, and reimbursement frameworks.
Pulsed-dye laser systems are collapsing the traditional gap between cosmetic and medical dermatology applications. Academic medical centers in the United States are adopting these platforms at accelerated pace for rosacea and vascular lesion protocols. The technology is collapsing referral bottlenecks by enabling same-day diagnosis and treatment within specialized dermatology networks.
REACH and RoHS compliance requirements in Europe are reshaping topical formulation chemistry and device material specifications. Manufacturers are reformulating excipient bases and substituting heavy metals in laser components to maintain market access. The medical device segment faces the steepest adaptation curve as MDR technical documentation requirements extend certification timelines.
Patient self-administration preferences are fragmenting the traditional clinic-centric care model. Homecare channels for topical immunomodulators are displacing routine follow-up visits in United States metropolitan markets. This behavioral shift concentrates in commercially insured populations where cost-sharing incentives favor reduced clinical touchpoints.
Erythema Treatment Market Segmentation
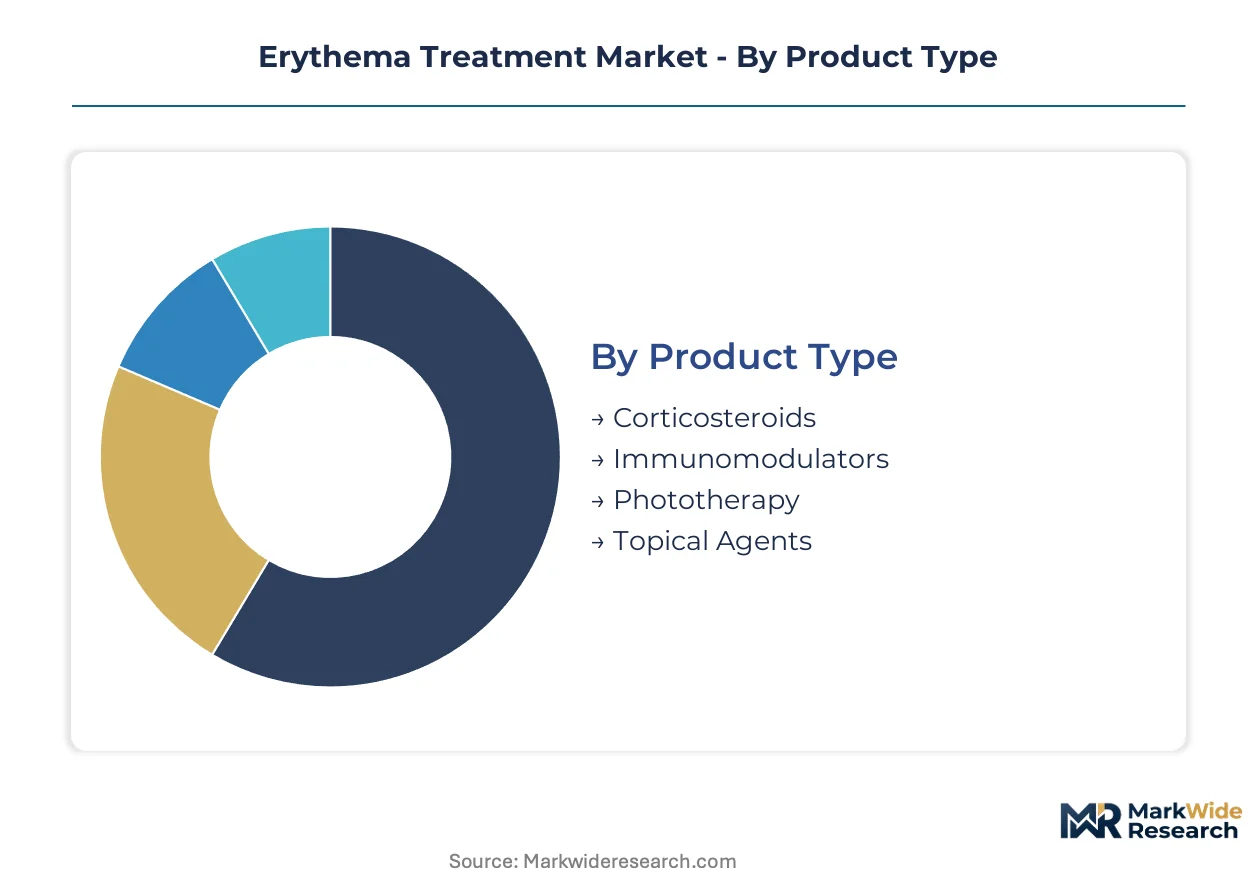
Erythema treatment modalities fragment across pharmacological, physical, and device-based interventions, each commanding distinct margin profiles and capital requirements. Understanding how patient pathways split across these dimensions clarifies where reimbursement stability meets growth volatility.
Product Type:
Cost tiers separate pharmaceutical formulations from capital-intensive device platforms, with reimbursement pathways diverging sharply across these boundaries.
- Corticosteroids:These anti-inflammatory compounds suppress local immune response through glucocorticoid receptor binding. Demand concentrates in United States hospital systems where established formularies and FDA potency classifications sustain predictable procurement volumes. Medicare Part B reimbursement creates procurement stability that pharmaceutical manufacturers prioritize.
- Phototherapy:Narrowband UVB and pulsed-dye laser platforms deliver selective photothermolysis at 585-595 nanometer wavelengths. United States dermatology clinics are expanding service lines as patient self-pay for cosmetic-adjacent applications supplements insurance reimbursement. Equipment leasing models are compressing capital barriers for mid-tier practices.
- Immunomodulators:Topical calcineurin inhibitors modulate T-cell activation without corticosteroid side-effect profiles. European markets access these through EMA bioequivalence pathways for generic alternatives.
- Topical Agents:Barrier repair formulations and vasoconstrictive compounds address rosacea-related flushing. Homecare channels in United States metropolitan markets favor patient self-administration.
Corticosteroids hold installed capacity. Phototherapy is rotating up the share rankings.
Application:
Clinical indications vary in disease chronicity, aesthetic impact, and referral complexity, shaping where providers invest specialized expertise.
- Rosacea:Chronic facial erythema and telangiectasia drive recurring consultation demand. United States specialized dermatology networks capture premium pricing for vascular-specific protocols. Pulsed-dye laser adoption is collapsing referral bottlenecks through same-day diagnosis and treatment capabilities.
- Psoriasis:Plaque formation with inflammatory erythema requires sustained immunomodulation. Hospital-based phototherapy departments in Germany and France manage high-volume narrowband UVB protocols under statutory reimbursement frameworks.
- Dermatitis:Contact and atopic variants respond to corticosteroid tapering regimens. Primary care gatekeeping in United Kingdom NHS structures filters severe cases to dermatology referrals.
- Vascular Lesions:Port-wine stains and hemangiomas demand precise laser parameters. Academic medical centers in United States urban markets concentrate pediatric and adult treatment expertise.
Rosacea commands premium pricing bandwidth. Psoriasis is expanding most quickly as biologic alternatives extend treatment persistence.
Delivery Mode:
Patient touchpoint intensity and clinical oversight requirements differentiate administration pathways, with self-care preferences reshaping traditional models.
- Topical:Cream, gel, and ointment formulations enable home administration with periodic monitoring. United States commercially insured populations favor reduced clinic visits where cost-sharing incentives align.
- Laser:Pulsed-dye and potassium titanyl phosphate systems require technician-operated platforms. Dermatology clinics in Australia face TGA device certification timelines that extend deployment schedules.
- Injectable:Intradermal and intralesional corticosteroid delivery addresses refractory plaques. Hospital outpatient departments manage these under procedural reimbursement codes.
- Oral:Systemic immunomodulators and antibiotics target refractory or widespread disease. FDA safety monitoring for isotretinoin and similar agents creates prescriber certification requirements.
Topical delivery dominates prescription volume. Laser administration is climbing the fastest as aesthetic-medical boundaries blur.
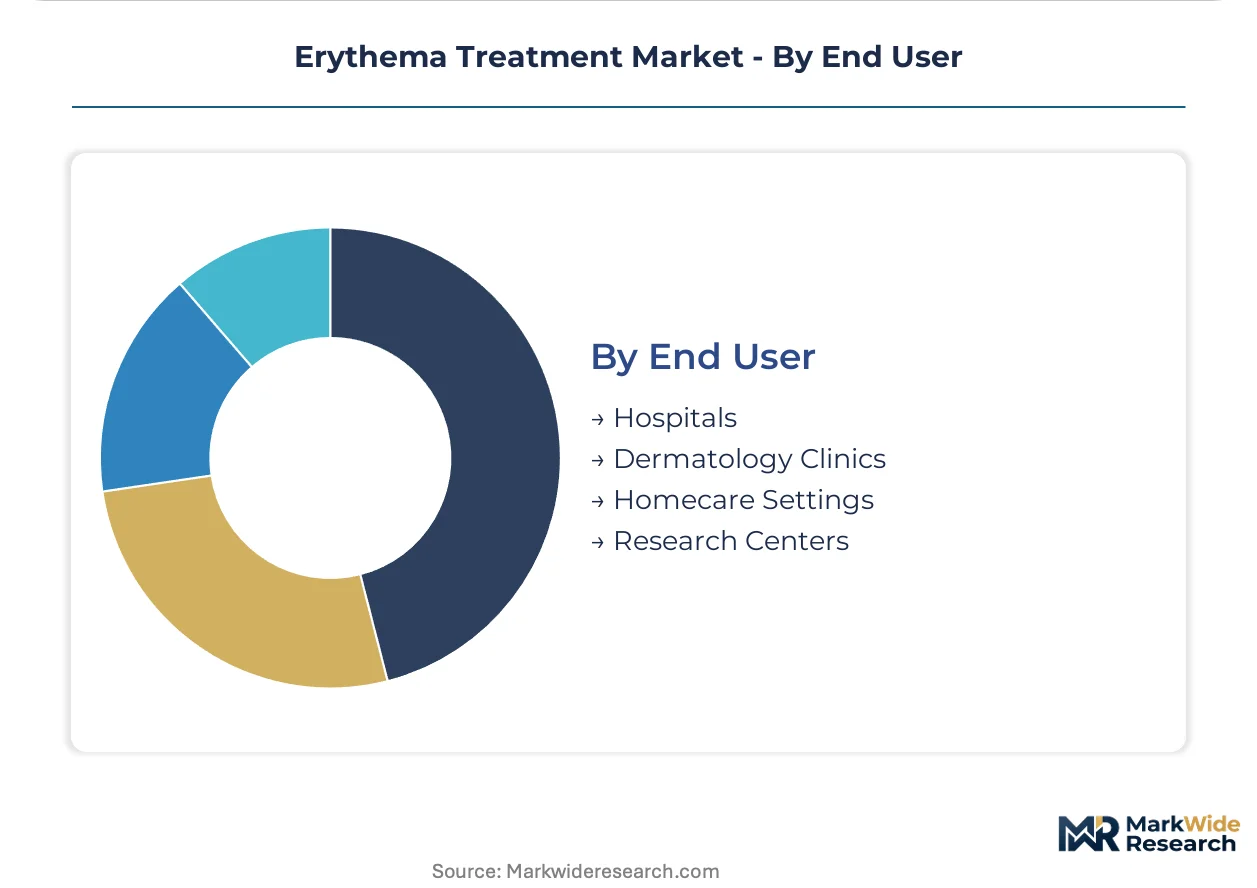
End User:
Facility type determines capital deployment capacity, patient acuity mix, and reimbursement capture mechanics across the care continuum.
- Dermatology Clinics:Specialized facilities concentrate phototherapy equipment and laser platforms. United States private practice networks and corporate-affiliated chains are expanding narrowband UVB service lines. Asset-light leasing structures enable competitive entry without balance-sheet strain.
- Hospitals:Academic medical centers and community systems manage complex, multi-morbid cases. Pulsed-dye laser capital requirements limit deployment to well-capitalized systems with procedural volume to justify fixed costs.
- Homecare Settings:Patient-administered topical regimens displace routine follow-up visits. United States metropolitan markets with high commercial insurance penetration show strongest channel shift.
- Research Centers:Academic institutions conduct laser-based intervention trials and real-world evidence collection. EMA and FDA post-market surveillance requirements create demand for longitudinal study infrastructure.
Dermatology clinics concentrate procedure revenue. Homecare settings are gaining share fastest as self-administration preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement pathway expansions for phototherapy services are accelerating clinic network investments across multiple jurisdictions. EMA bioequivalence frameworks are streamlining topical generic approvals in parallel markets. Regulatory divergence between these systems is creating distinct competitive entry points for device manufacturers versus pharmaceutical formulators.
United States
Specialized dermatology networks in metropolitan corridors drive premium treatment adoption for vascular-specific protocols. Medicare Part B reimbursement stability sustains predictable procurement volumes for corticosteroid formularies in hospital systems. Academic medical centers in Boston and New York are deploying pulsed-dye laser platforms for same-day diagnosis and treatment capabilities.
Germany
Statutory reimbursement frameworks under the GKV system support high-volume narrowband UVB protocols in hospital-based phototherapy departments. The BfArM maintains stringent safety monitoring for corticosteroid potency classifications that extend development cycles. Industrial concentration in North Rhine-Westphalia hosts device manufacturing clusters serving central European clinic networks.
France
ANSM oversight of topical immunomodulator formulations shapes multi-territory labeling strategies for manufacturers targeting EU market entry. Rosacea protocol specialization concentrates R&D investment in vascular-specific mechanisms among Paris-based dermatology research institutes. The Île-de-France region anchors clinical trial infrastructure for laser-based intervention studies.
Japan
PMDA guidance on real-world evidence integration is compressing regulatory timelines for phototherapy device approvals. Aging demographic profiles are expanding patient volumes for chronic inflammatory skin conditions in urban centers. The Kanto region surrounding Tokyo concentrates specialized dermatology networks with advanced laser platform deployment.
Australia
TGA device certification timelines for laser platforms extend deployment schedules for mid-tier dermatology practices. Homecare channel preferences for patient-administered topical agents are displacing routine clinic visits in commercially insured metropolitan markets. Sydney and Melbourne anchor specialized dermatology networks with concentrated phototherapy service line expansion.
Erythema Treatment Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers with divergent capital intensity requirements. Large-scale pharmaceutical manufacturers command established corticosteroid supply chains with hospital system integration. Device specialists concentrate phototherapy platform development with clinic-direct distribution models. Mid-tier topical formulators occupy niche positions through dermatology network relationships. Competitive moves center on strategic partnerships between pharmaceutical and device players, alongside portfolio diversification into homecare channel formulations.
Among North American and European pharmaceutical incumbents, Pfizer Inc., AbbVie Inc., and Galderma S.A. occupy positions representing distinct strategic archetypes. Pfizer exemplifies the scale-driven manufacturer with supply chain efficiencies across hospital procurement systems. AbbVie sits within the R&D-intensive tier with immunomodulator pipeline concentration. Galderma represents the dermatology-specialized formulator with topical agent expertise aligned to clinic protocol preferences. These three entities collectively illustrate how competitive positioning fragments across manufacturing scale, therapeutic focus, and channel specialization dimensions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| AbbVie Inc. |
| Galderma S.A. |
| Bausch Health Companies Inc. |
| Astellas Pharma Inc. |
| LEO Pharma A/S |
| Sanofi S.A. |
| Regeneron Pharmaceuticals Inc. |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient manufacturing for corticosteroid formulations clusters in India and China, concentrating upstream margin capture among contract manufacturers while downstream pricing power fragments across branded and generic topical formulators competing on FDA potency classification tiers.
Pricing Analysis
Certification level creates the primary spread between premium FDA-approved phototherapy platforms and economy-tier clinic equipment lacking full regulatory dossiers. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center procurements from mid-tier dermatology practices and budget-constrained hospital systems. Price differentiation hinges on after-sales service bundling and technician training packages rather than hardware specifications alone. Cost compression in the standard tier intensifies because equipment leasing models proliferate among asset-light clinic networks. Commercially insured patient populations show lowest price sensitivity for same-day laser protocols, while Medicare-dependent demographics drive corticosteroid generic substitution.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for excipient sourcing and laser component procurement. Manufacturing concentration in Germany, Switzerland, and the United States anchors high-precision phototherapy device assembly, while India and China feed corticosteroid API production. Raw material dependencies center on xenon flashlamps, optical fibers, and glucocorticoid precursor chemicals. Single-source vulnerability for 585-595 nanometer wavelength-specific optical components creates procurement bottlenecks. Distribution runs through dermatology clinic-direct sales forces for capital equipment and pharmaceutical wholesaler networks for topical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The erythema treatment market functions as a service-attach opportunity where recurring revenue from phototherapy maintenance contracts and topical immunomodulator prescription refills expands faster than one-time device sales or acute corticosteroid courses.
For Market Incumbents: Insulate formulary position by deepening backward integration into corticosteroid API production and securing exclusive narrowband UVB service line partnerships with expanding dermatology clinic networks. The threat of biosimilar topical immunomodulators entering through EMA bioequivalence pathways demands accelerated R&D investment in vascular-specific mechanisms. Certification investment for MDR technical documentation provides defensive moats against mid-tier device competitors. For New Entrants and Emerging Players: Asset-light dermatology clinic networks in Australian metropolitan markets represent the most penetrable entry point for leased phototherapy platform deployment. Homecare channel topical agent formulations for rosacea self-administration offer secondary white-space capture with lower capital barriers. Go-to-market execution should emphasize direct-to-clinic equipment leasing with bundled technician certification programs. For Investors and Strategic Acquirers: Capital is best deployed toward dermatology-specialized topical formulators with established clinic protocol relationships and homecare channel infrastructure. Long-term viability over the projection horizon favors entities with dual capability in pharmaceutical manufacturing and phototherapy device distribution. The signal to watch is FDA guidance evolution on real-world evidence acceptance for laser-based intervention reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| Phototherapy Equipment Leasing Models | Asset-light structures enable mid-tier dermatology practices to compete without heavy balance-sheet investment. |
| Homecare Channel Formulation Development | Patient self-administration preferences in United States metropolitan markets displace routine clinic visits. |
| Real-World Evidence Collection Infrastructure | Post-market surveillance data accelerates regulatory acceptance for laser-based interventions under FDA guidance. |
| Multi-Territory Labeling Harmonization | Simultaneous FDA, EMA, Health Canada, and TGA compliance streamlines global product launches for topical generics. |
| Technician Certification Program Expansion | Specialized training pipelines address workforce supply gaps for narrowband UVB and pulsed-dye laser platforms. |
Research Methodology
A standing panel of dermatology clinic operators, pharmaceutical regulatory affairs directors, hospital procurement managers, and phototherapy device service technicians provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA marketing authorization databases, ClinicalTrials.gov intervention records, and dermatology society protocol guidelines. Bottom-up prescription volume modeling and top-down equipment shipment analysis triangulated market sizing across product type, application, delivery mode, and end user segmentation dimensions.
Scenario-bracketing around reimbursement pathway stability and phototherapy capital deployment cycles anchored the analytical framework across the analysis window. Segmentation modeling incorporated treatment modality, disease indication, administration setting, and regional regulatory cluster variations. CAGRs derived from fitted growth curves applied to procedure volume projections and pharmaceutical unit demand. Forecast inputs included Medicare Part B reimbursement rate trajectories and dermatology clinic network expansion plans reported in health system capital expenditure disclosures.
Practitioners should monitor FDA phototherapy service reimbursement expansions, EMA bioequivalence framework modifications, and pulsed-dye laser platform adoption curves for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Onychomycosis Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Folliculitis Market
Dermatology
Australia Skin Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Global Radiodermatitis Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Scleroderma Treatment Market
Dermatology
Impetigo Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Acne Scar Treatment Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Dermatology Cryosurgery Units Market