
 Dermatology Devices Market | 2026-2036
Dermatology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Devices Market Analysis
Silicon-based photonic components is shifting toward gallium arsenide substrates in dermatology laser manufacturing, improving thermal efficiency and wavelength precision. Alma Lasers leverages captive semiconductor sourcing to stabilize diode laser output consistency. Cynosure anchors North American service infrastructure for physician training and device maintenance. Solta Medical specializes in fractional radiofrequency platforms that target scar reduction protocols.
Dermatology devices comprise electromechanical and optical instruments engineered to deliver controlled energy doses—typically 532 nm to 1064 nm for lasers, with fluence parameters calibrated to epidermal depth—for diagnostic imaging or therapeutic modification of skin tissue. Laser Devices command the dominant revenue share due to capital intensity and recurring consumable attach rates, while Radiofrequency Devices represent the fastest-expanding margin pool as physicians adopt non-ablative tightening protocols. Dermatoscopes occupy a mature niche with stable replacement cycles tied to digital imaging upgrades rather than procedural volume growth.
FDA 510(k) clearance requirements shape product development timelines and predicate device selection for US market entrants, while EMA MDR compliance in Europe mandates expanded clinical evidence portfolios for laser classification upgrades. India's CDSCO import licensing rules for Class C and D medical devices create registration bottlenecks that favor established multinationals with local subsidiary infrastructure. Stakeholders must monitor harmonization gaps between FDA laser product codes and EU common specifications as dual-market certification costs influence regional launch sequencing.
Market Dynamics
Diode laser thermal management requirements are forcing manufacturers to reconfigure semiconductor sourcing strategies as gallium arsenide substrates replace silicon photonics for wavelength precision above 800 nm.
Growth Catalysts
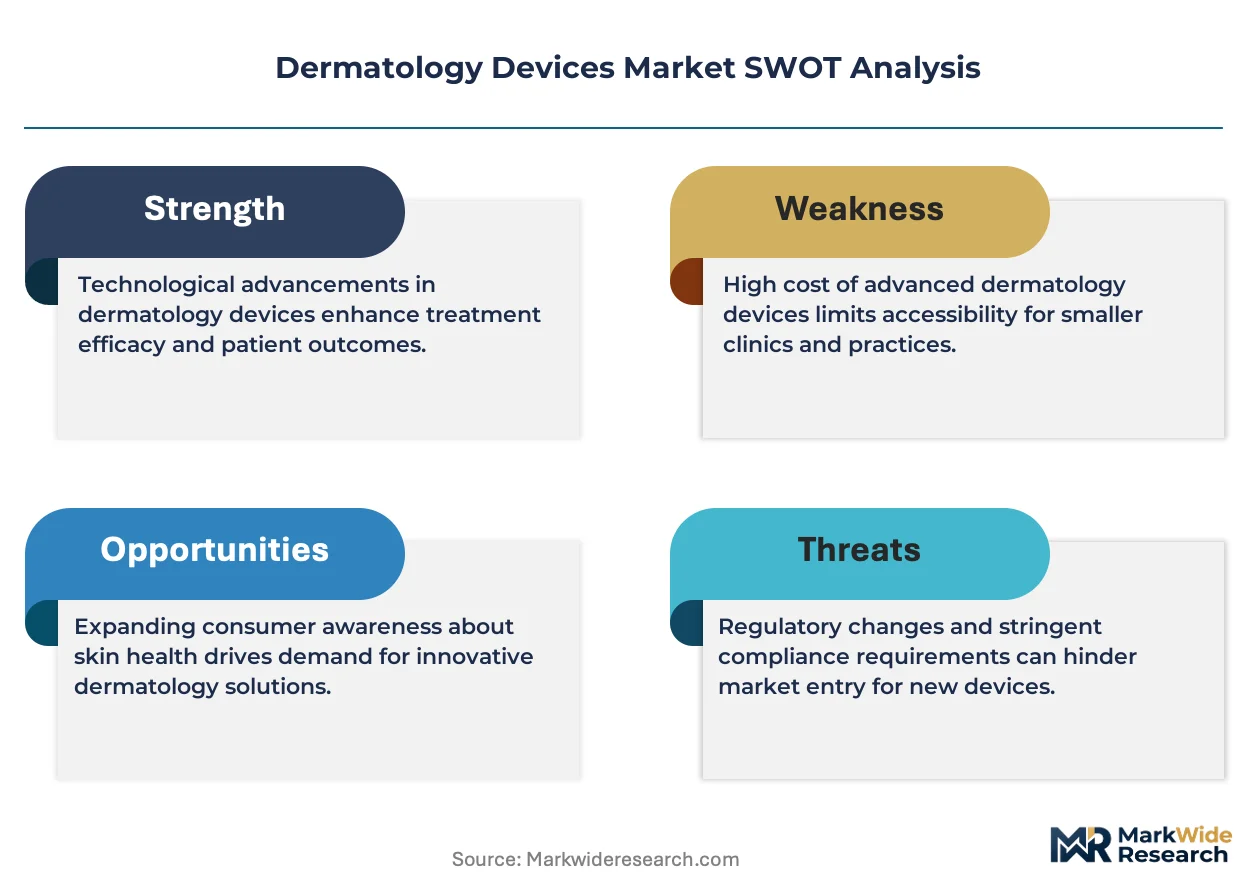
- FDA 510(k) clearance pathway:Streamlined predicate device referencing accelerates US market entry for fractional radiofrequency platforms targeting scar reduction protocols.
- India's tier-1 dermatology chains:Private clinic networks in Mumbai, Delhi, and Bangalore deploy imported light therapy devices for skin rejuvenation, creating concentrated demand pull for imported capital equipment.
- Non-ablative tightening protocols:Physician adoption of radiofrequency-based collagen remodeling is expanding addressable patient populations beyond traditional ablative laser candidates.
Market Restraints
- Gallium arsenide wafer supply:Captive semiconductor fabrication capacity concentrates among legacy telecom substrate manufacturers, creating input bottlenecks for diode laser producers.
- EMA MDR clinical evidence requirements:Expanded predicate dossiers for laser classification upgrades extend European certification timelines and inflate regulatory compliance costs.
- Intense pulsed light substitution:Lower-capital IPL systems compete for pigmentation and vascular lesion indications, compressing addressable market for single-wavelength laser platforms.
Strategic Opportunities
- India CDSCO registration infrastructure:Established multinationals with local subsidiary legal entities bypass import licensing bottlenecks for Class C and Class D medical devices.
- Telemedicine-integrated dermatoscopy:Digital imaging platforms with cloud-based diagnostic support enable remote lesion screening, opening rural and secondary city access.
- EU Green Deal medical device sustainability mandates:Energy efficiency and recyclability requirements favor manufacturers with modular, upgradeable hardware architectures.
Industry Challenges
- Laser safety officer certification:Jurisdictional variation in physician training requirements complicates service infrastructure scaling across multi-state clinic networks.
- Electromagnetic compatibility retesting:Germany's tightened radiofrequency equipment standards force hardware redesigns for existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Devices Market |
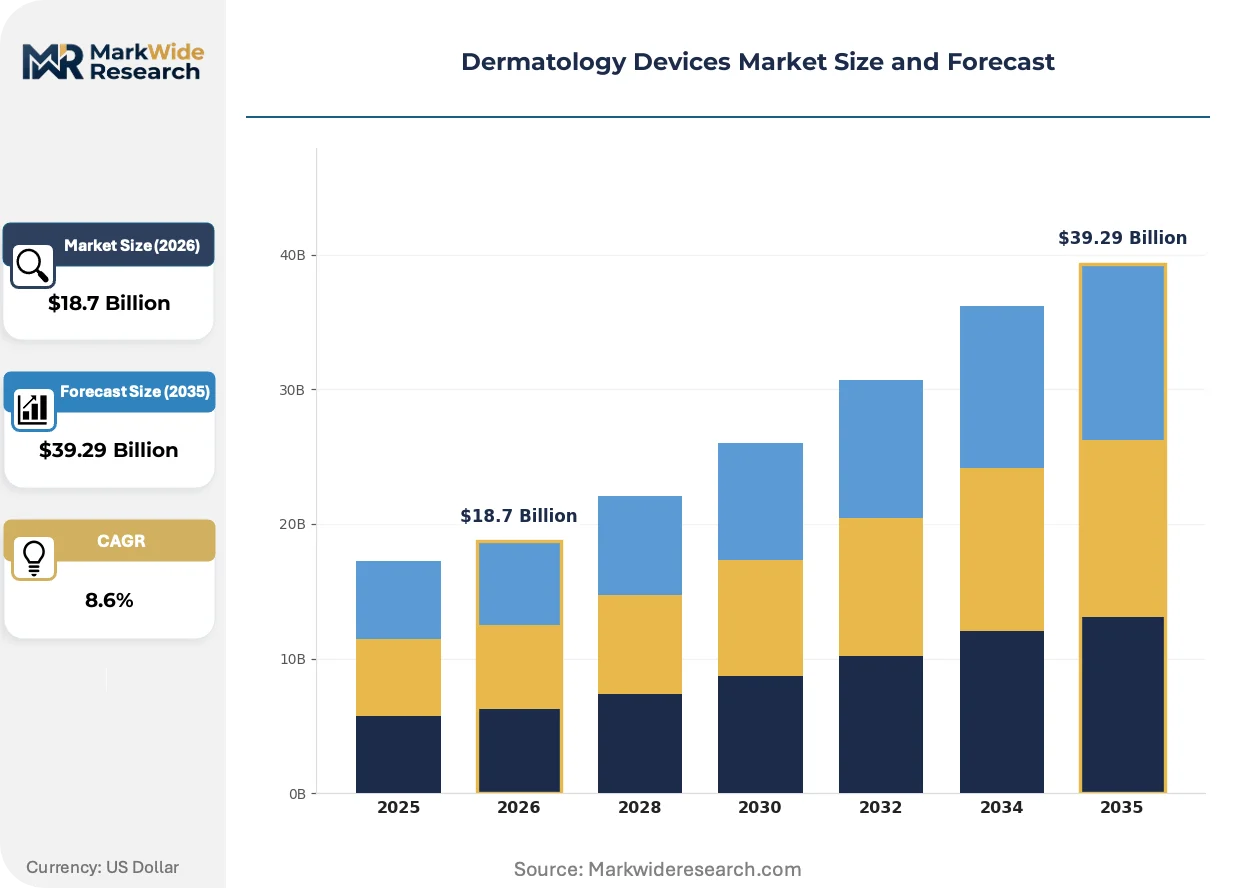
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Light Therapy Devices, Radiofrequency Devices, Dermatoscopes End User: Hospitals, Dermatology Clinics, Research Laboratories, Home Care Settings Technology: Diode Laser, Intense Pulsed Light, Microdermabrasion, Cryotherapy Application: Acne Treatment, Scar Reduction, Skin Rejuvenation, Psoriasis Management |
| Companies Covered | Cynosure, Solta Medical, Alma Lasers, Syneron Medical, Hologic, Lumenis, Candela, Canfield Scientific, Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Devices Market Emerging Trajectories
Photonic substrate materials and regulatory harmonization pressures are simultaneously reshaping hardware engineering priorities and geographic launch sequencing for device manufacturers.
Picosecond-domain pulse delivery is rewriting treatment protocols for tattoo removal and benign pigmented lesions. Dermatology clinics in South Korea and the United States are replacing nanosecond Q-switched platforms at compressed replacement cycles. The technology is compressing session counts per complete clearance, eroding recurring revenue from maintenance visits.
EMA MDR Article 10 clinical evidence requirements are extending laser device certification timelines. Manufacturers must now submit expanded post-market surveillance data for classification upgrades previously grandfathered under the MDD. Fractional ablative platforms face the steepest documentation burdens, prompting some firms to sequence EU launches behind FDA clearances.
Equipment leasing with bundled consumable supply contracts is displacing outright capital purchases among mid-size dermatology groups. Third-party financing entities now intermediate device procurement for practices with fifteen to fifty providers. This arrangement concentrates most visibly in Texas and Florida, where private equity-backed clinic rollups standardize technology platforms across acquired practices.
Dermatology Devices Market Segmentation
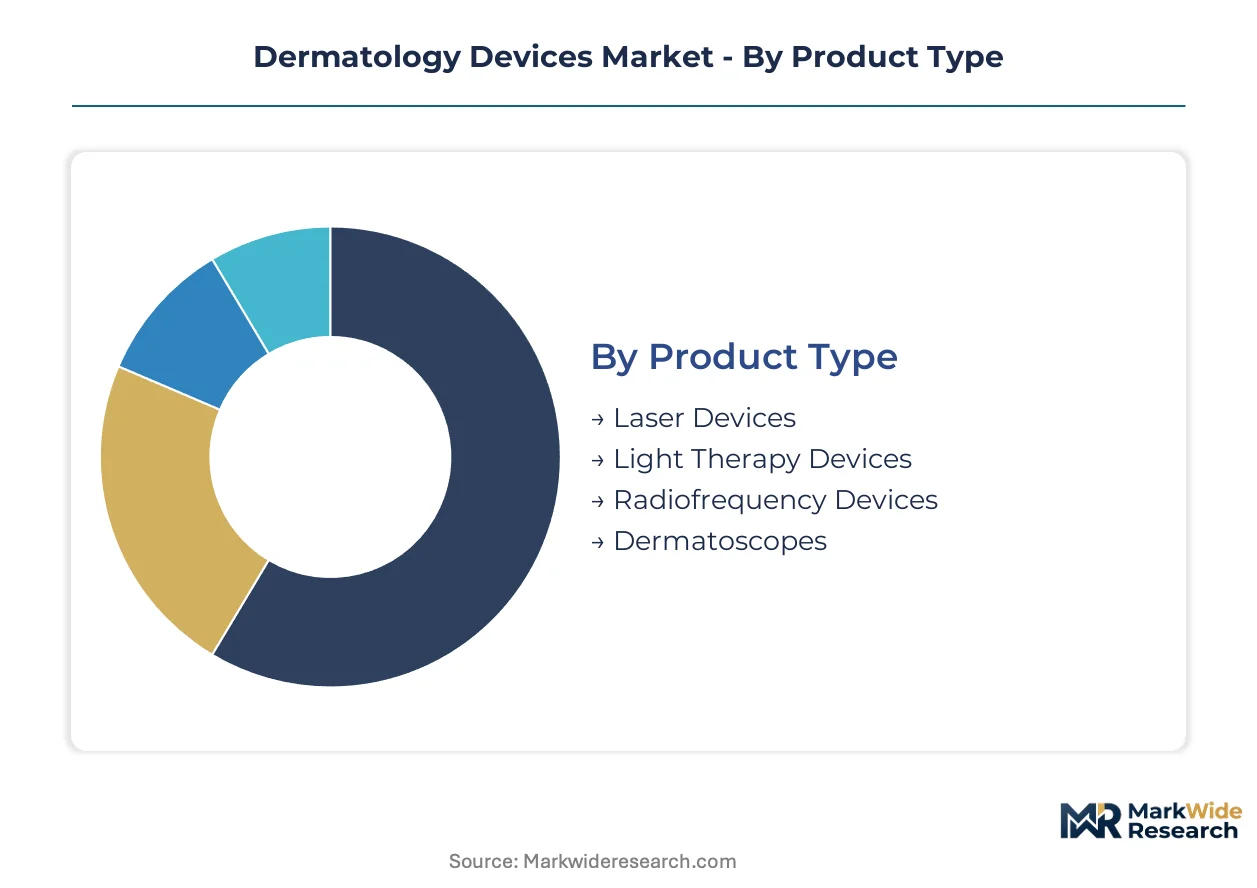
Dermatology device segmentation reveals divergent margin structures across hardware categories. Procurement patterns split between capital-intensive laser platforms with recurring consumable revenue and lower-barrier diagnostic instruments with replacement-driven sales cycles.
Product Type:
Wavelength precision and thermal management specifications differentiate hardware tiers across procedural applications.
- Laser Devices:Electromechanical systems delivering controlled energy doses across 532 nm to 1064 nm wavelengths with fluence calibrated to epidermal depth. Demand clusters in United States dermatology clinics expanding diode-based acne treatment capacity following FDA 510(k) clearance pathways for new systems.
- Radiofrequency Devices:Non-ablative platforms generating dermal heating for collagen remodeling without epidermal disruption. Physician adoption of tightening protocols is expanding addressable patient populations beyond traditional ablative laser candidates in Germany and South Korea.
- Light Therapy Devices:LED and narrowband UV systems for inflammatory skin conditions. India's tier-1 private dermatology chains deploy imported units for skin rejuvenation procedures in Mumbai, Delhi, and Bangalore.
- Dermatoscopes:Digital imaging instruments for lesion examination with magnification and polarized light. Replacement cycles tie to imaging sensor upgrades rather than procedural volume expansion.
Mature deployment sits with Laser Devices. Newer deployment is concentrated in Radiofrequency Devices.
End User:
Capital deployment capacity and regulatory compliance burden shape customer segmentation across care settings.
- Dermatology Clinics:Specialized outpatient facilities performing elective cosmetic and medical dermatology procedures. United States clinic networks are expanding laser-based acne treatment capacity following FDA clearance pathways.
- Hospitals:Acute care institutions with dermatology departments handling complex cases and inpatient consultations. EMA MDR clinical evidence requirements extend certification timelines for laser classification upgrades in European hospital procurement.
- Research Laboratories:Academic and commercial R&D facilities investigating photobiomodulation and energy-based tissue interactions. Equipment sourcing prioritizes wavelength tunability and data capture capabilities.
- Home Care Settings:Consumer-directed use of low-energy LED masks and handheld devices for mild acne and anti-aging. Regulatory classification as cosmetic versus medical devices varies by jurisdiction.
Volume concentration rests with Dermatology Clinics. Margin expansion is fastest in Home Care Settings.
Technology:
Substrate materials and pulse delivery mechanisms determine thermal efficiency and clinical indication range.
- Diode Laser:Gallium arsenide-based semiconductor sources replacing silicon photonics for wavelength precision above 800 nm. India's CDSCO import licensing rules for Class C and D devices create registration bottlenecks favoring established multinationals with local subsidiary infrastructure.
- Intense Pulsed Light:Broadband flashlamp systems with cut-off filters for selective photothermolysis. Lower capital requirements compete for pigmentation and vascular lesion indications, compressing addressable market for single-wavelength laser platforms.
- Microdermabrasion:Mechanical exfoliation using crystal or diamond-tipped abrasion for superficial skin resurfacing. Procedure adoption concentrates in medical spas and aesthetic clinics with lower regulatory barriers.
- Cryotherapy:Liquid nitrogen or nitrous oxide delivery for lesion destruction through controlled freezing. Portable units expand access in primary care and rural settings with limited specialist coverage.
Installed base dominance belongs to Diode Laser. Technology transition is accelerating toward Intense Pulsed Light in cost-sensitive segments.
Application:
Clinical efficacy evidence and reimbursement status drive procedure volume distribution across dermatologic conditions.
- Skin Rejuvenation:Collagen stimulation and texture improvement through fractional or non-ablative energy delivery. Private dermatology chains in India's tier-1 cities deploy imported light therapy devices for elective procedures.
- Acne Treatment:Sebaceous gland targeting through photodynamic therapy or thermal destruction. United States clinics are expanding laser-based capacity following FDA clearance pathways for new diode systems.
- Scar Reduction:Fractional ablative and non-ablative protocols for traumatic and surgical scar remodeling. EMA MDR Article 10 requirements extend certification timelines for fractional ablative platforms.
- Psoriasis Management:Narrowband UVB and excimer laser delivery for plaque clearance. Treatment protocols favor clinic-based administration over home phototherapy units for severe cases.
Revenue concentration aligns with Skin Rejuvenation. Fastest volume gains are occurring in Acne Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology clinics are expanding laser-based acne treatment capacity following FDA 510(k) clearance pathways for new diode laser systems. Demand concentrates in India's tier-1 cities where private dermatology chains deploy imported light therapy devices for skin rejuvenation procedures. Germany's EMA-aligned medical device regulations are tightening electromagnetic compatibility standards for radiofrequency equipment.
United States
Dermatology clinic networks in Texas and Florida are standardizing technology platforms across private equity-backed rollups. FDA 510(k) clearance pathways for fractional radiofrequency platforms accelerate predicate device referencing for scar reduction protocols. Equipment leasing with bundled consumable contracts now intermediates procurement for mid-size practices with fifteen to fifty providers.
Germany
Physician adoption of non-ablative tightening protocols is expanding addressable patient populations beyond traditional ablative laser candidates. EMA MDR Article 10 clinical evidence requirements extend certification timelines for laser classification upgrades previously grandfathered under the MDD. Medical device manufacturers in Baden-Württemberg face electromagnetic compatibility retesting for existing radiofrequency product lines.
India
Private dermatology chains in Mumbai, Delhi, and Bangalore deploy imported light therapy devices for elective skin rejuvenation procedures. CDSCO import licensing rules for Class C and Class D medical devices create registration bottlenecks that favor established multinationals with local subsidiary infrastructure. Tier-1 city concentration drives concentrated demand pull for imported capital equipment.
South Korea
Dermatology clinics are replacing nanosecond Q-switched platforms with picosecond-domain pulse delivery systems for tattoo removal. MFDS regulatory alignment with international standards supports compressed replacement cycles for aesthetic laser platforms. Seoul-based clinic networks are rewriting treatment protocols for benign pigmented lesions with reduced session counts.
United Kingdom
Telemedicine-integrated dermatoscopy platforms with cloud-based diagnostic support enable remote lesion screening access. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel certification requirements for laser device manufacturers. London and Southeast England specialist clinics prioritize digital imaging sensor upgrades for dermatoscope replacement cycles.
Dermatology Devices Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers reconfigure semiconductor sourcing strategies for gallium arsenide substrate adoption. The vendor base splits between legacy laser platform specialists and emerging radiofrequency platform entrants. Three archetypes define competitive positioning: captive semiconductor fabricators with upstream substrate control, service infrastructure anchors with physician training networks, and fractional technology specialists targeting scar reduction protocols. M&A activity and strategic partnerships concentrate among mid-cap firms seeking geographic footprint expansion.
Within the captive supply tier, Alma Lasers exemplifies manufacturers stabilizing diode laser output consistency through controlled semiconductor sourcing. Cynosure occupies a position as a North American service infrastructure anchor, while Solta Medical represents the fractional radiofrequency specialization vector. These three entities collectively illustrate how competitive positioning diverges across substrate control, service density, and indication-specific technology development.
| Leading Market Players |
|---|
| Cynosure |
| Solta Medical |
| Alma Lasers |
| Syneron Medical |
| Hologic |
| Lumenis |
| Candela |
| Canfield Scientific |
| Cutera |
| Others |
Supply Flow & Price Mechanics
EU Green Deal medical device sustainability mandates gate both qualified supply and premium-tier pricing access, as energy efficiency and recyclability requirements favor manufacturers with modular hardware architectures while excluding non-compliant competitors from higher-margin procurement channels.
Pricing Analysis
The volume-vs-margin split stratifies across equipment tiers: capital-intensive laser platforms command premium positioning through bundled consumable contracts and physician training services, while lower-barrier diagnostic instruments compete on replacement-cycle pricing tied to imaging sensor upgrades. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Pricing pressure stems from intense pulsed light systems competing for pigmentation indications. Mid-size dermatology groups exhibit highest price sensitivity through third-party financing intermediation.
Supply Chain Analysis
EMA MDR Article 10 clinical evidence requirements gate supplier qualification, concentrating gallium arsenide substrate sourcing among legacy telecom semiconductor fabricators in Germany, Japan, and the United States. Diode laser manufacturing draws from captive semiconductor fabrication, specialized optical components, and precision thermal management systems. Single-source vulnerability concentrates in gallium arsenide wafer supply. Distribution runs through direct sales forces for capital equipment and third-party financing entities for mid-market practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: EMA MDR clinical evidence requirements create a barrier-to-entry moat that rewards players with established regulatory dossiers and punishes late entrants facing extended certification timelines.
For Market Incumbents: Anchor service infrastructure density in Texas and Florida where private equity-backed clinic rollups standardize technology platforms. Deepen captive gallium arsenide sourcing to insulate against substrate bottlenecks. Defend against picosecond-domain pulse substitution by accelerating fractional radiofrequency platform refreshes. For New Entrants and Emerging Players: Telemedicine-integrated dermatoscopy platforms offer the most penetrable white-space route, enabling rural and secondary city access without capital-intensive clinic infrastructure. Target India's tier-2 cities where CDSCO registration infrastructure gaps disadvantage established multinationals lacking local subsidiary legal entities. Pursue cloud-based diagnostic support partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: MFDS regulatory alignment with international standards is the leading indicator that South Korean aesthetic laser platforms will compress replacement cycles further, signaling acquisition timing for technology-specialist targets ahead of protocol standardization. Long-term viability favors fractional technology specialists with indication-specific IP and service infrastructure anchors with physician training networks. Watch for EMA MDR harmonization gaps with FDA laser product codes as the signal for dual-market certification cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined predicate device referencing accelerates US market entry for scar reduction platforms. |
| CE Marking Pathway | EMA MDR Article 10 compliance extends timelines but secures premium positioning in European hospital procurement. |
| Hospital System Partnership | Texas and Florida clinic network standardization creates captive demand pools for bundled consumable contracts. |
| Software Companion Development | Telemedicine-integrated dermatoscopy with cloud-based diagnostic support enables rural market penetration. |
| Reimbursement Strategy | Non-ablative tightening protocol coverage expansion broadens addressable patient populations beyond cosmetic payers. |
Methodological Framework
FDA 510(k) filings, EMA MDR submission databases, and CDSCO import licensing records formed the secondary backbone, combined with primary interviews with dermatology clinic operators, biomedical equipment procurement managers, GPO contracts administrators, and regulatory affairs specialists at device manufacturers. Bottom-up and top-down triangulation validated segment-level estimates against hospital procurement databases and private clinic capital expenditure disclosures.
Bottom-up modeling aggregated procedure volume by indication and equipment replacement cycles, while top-down analysis cross-checked manufacturer revenue disclosures against installed base estimates. Segmentation dimensions included product type, end-user setting, technology substrate, and application indication. CAGRs were derived from fitted growth curves calibrated to historical clearance timelines and adoption lag patterns. Forecast inputs incorporated gallium arsenide substrate supply constraints and EMA MDR certification timeline extensions.
Inputs from FDA, EMA, and CDSCO regulatory databases were available through the study window; gaps in real-time private clinic procurement transaction data introduce uncertainty bands around equipment leasing penetration estimates. Forecasts reflect assumptions regarding physician training certification standardization and electromagnetic compatibility retesting completion rates. A model refresh is warranted upon material change in EMA-FDA harmonization negotiations or gallium arsenide wafer supply allocation policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
China Scar Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Australia Skin Treatment Market
Dermatology
Impetigo Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Keloid Treatment Market
Dermatology
Global Rosacea Market
Dermatology
Europe Scar Treatment Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Darier Disease Drugs Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Global Dermatology Cro Market