
 Global Veterinary Telehealth Market | 2026-2036
Global Veterinary Telehealth Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Telehealth Market Foresight
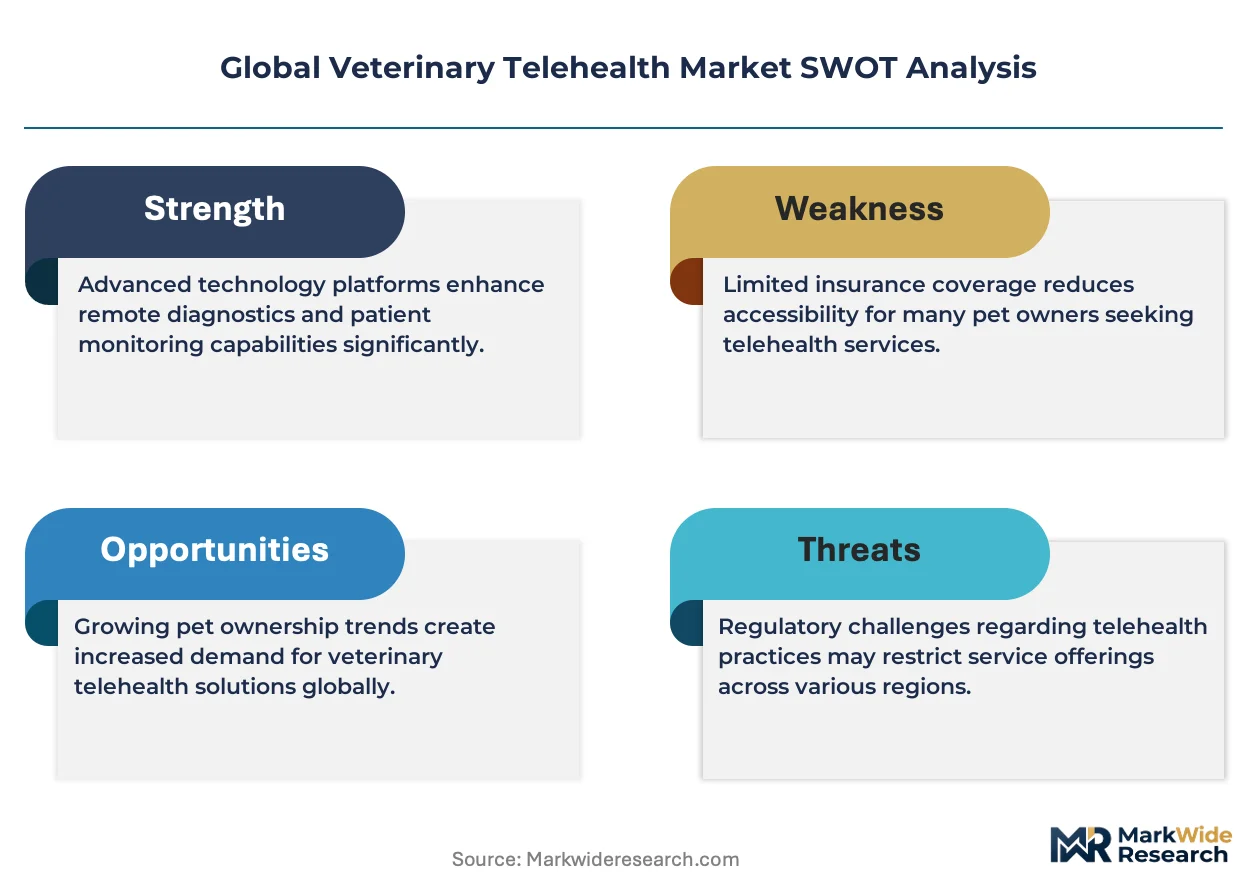
Buyer concentration among pet owners is hardening as subscription-based telehealth models replace one-off consultations. Vetster, Inc. leverages its marketplace architecture to connect independent veterinarians with direct-to-consumer demand. FirstVet anchors its position through insurance-integrated triage services that reduce emergency clinic overflow. Airvet, Inc. specializes in B2B clinic partnerships, embedding telehealth into existing practice workflows rather than displacing them.
Veterinary telehealth encompasses real-time video consultation, asynchronous messaging, and remote physiological monitoring delivered through internet-connected platforms, typically requiring bandwidth above 1 Mbps and integration with electronic health records for clinical continuity. Its primary commercial purpose is extending veterinary capacity beyond physical clinic boundaries while capturing revenue from non-urgent cases that previously went untreated. Teleconsultation platforms currently lead product type revenue as established players bundle diagnostics and pharmacy referrals. Pet Health Management dominates application-level demand, though Livestock Monitoring exhibits the fastest structural growth as precision agriculture capital flows into animal welfare compliance. Cloud-based deployment controls the deployment mode segment due to lower upfront infrastructure costs and faster scaling across multi-clinic networks.
FDA oversight of veterinary telemedicine prescribing and USDA engagement with livestock remote monitoring standards collectively shape platform design and interstate service legality. The EU Green Deal's animal welfare digitization incentives and REACH-aligned data handling requirements add compliance layers for platforms operating across European member states. Stakeholders must monitor whether national veterinary boards harmonize telehealth licensure rules or preserve fragmented state-by-state barriers that determine addressable market scope.
Market Dynamics
Veterinary workforce shortages in the United States are forcing platform operators to reconfigure care delivery models around asynchronous triage and AI-assisted pre-screening, compressing the traditional clinic visit into distributed digital touchpoints.
Growth Catalysts
- USDA Livestock Remote Monitoring Standards:Precision agriculture operators are deploying connected health sensors across cattle and poultry operations to satisfy animal welfare compliance mandates and reduce on-site veterinary labor.
- Smartphone Penetration in Pet Ownership:Mobile-first subscription models now dominate first-contact veterinary care, converting previously untreated minor conditions into billable teleconsultations.
- FDA Digital Prescribing Framework Engagement:Clarified interstate telemedicine prescribing rules are enabling platforms to scale pharmacy-integrated services across state lines without physical facility investments.
Market Restraints
- Veterinary Licensure Fragmentation:State-by-state credentialing requirements prevent seamless cross-border service delivery, forcing platforms to maintain redundant compliance infrastructure.
- Rural Broadband Infrastructure Gaps:Bandwidth thresholds above 1 Mbps for real-time video consultation exclude livestock operators in remote agricultural regions from platform access.
- Diagnostic Substitution Limitations:Physical examination requirements for certain conditions cap telehealth addressability, preserving in-clinic visits for complex cases.
Strategic Opportunities
- EU Green Deal Animal Welfare Digitization:European livestock producers face mandated welfare tracking requirements, creating demand for integrated telehealth-monitoring platforms with REACH-aligned data handling.
- Insurance-Integrated Triage Models:Pet insurers are embedding telehealth access into policy benefits, shifting first-contact care away from emergency clinics toward platform-based routing.
- Cloud-Based Multi-Clinic Networks:Veterinary practice aggregators are consolidating telehealth infrastructure across distributed locations, reducing per-clinic IT capital requirements.
Industry Challenges
- Veterinary Telemedicine Credentialing:Platforms must navigate divergent state board interpretations of the veterinarian-client-patient relationship, creating compliance uncertainty for interstate services.
- EHR Integration Complexity:Legacy practice management systems require costly API development to achieve clinical continuity between telehealth platforms and in-clinic records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Telehealth Market |
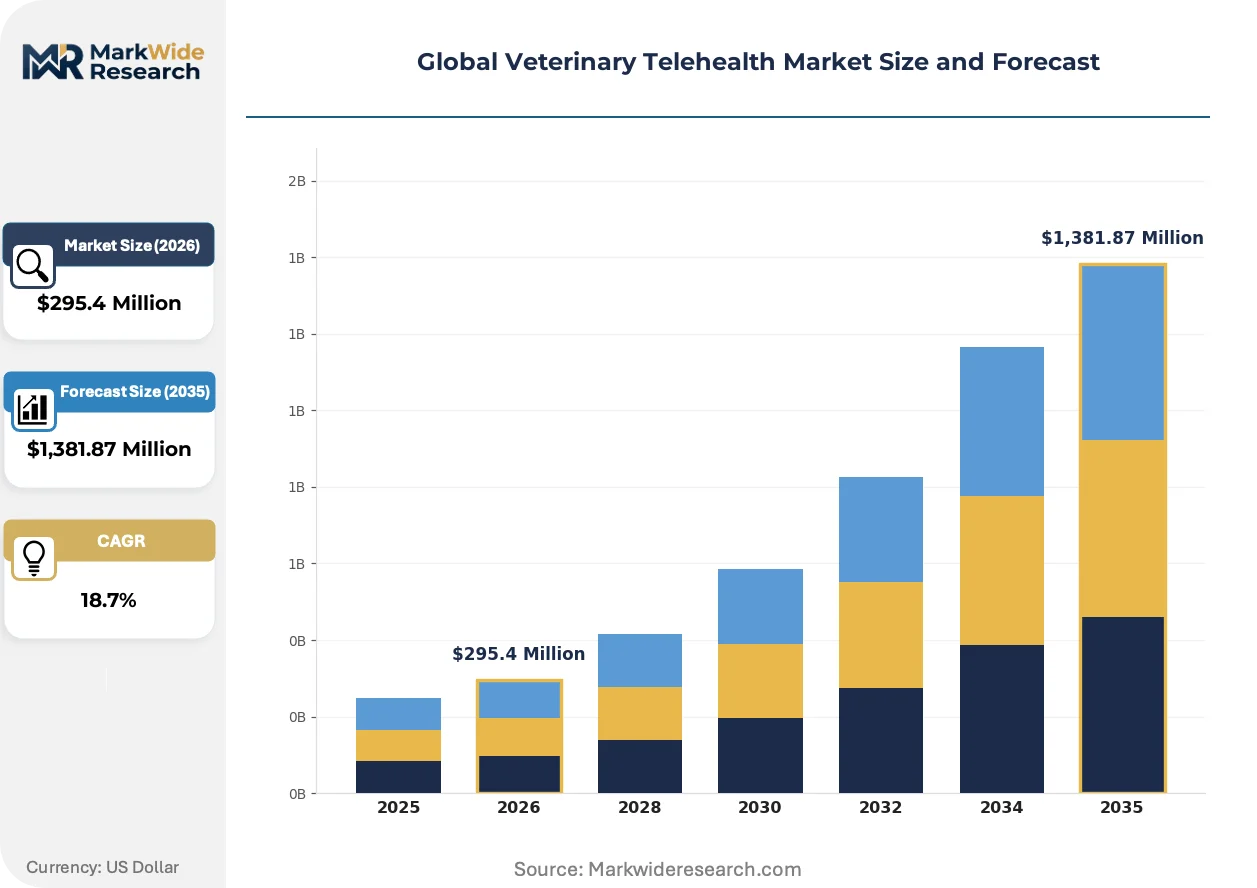
| Market Size in 2026 | $295.4 Million |
| Market Size in 2035 | $1,381.87 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Teleconsultation Platforms, Remote Monitoring Devices, Mobile Apps, Virtual Clinics Application: Pet Health Management, Livestock Monitoring, Emergency Consultation, Preventive Care End User: Veterinary Clinics, Animal Shelters, Farm Managers, Pet Owners Deployment Mode: Cloud-based, On-premises, Hybrid, SaaS |
| Companies Covered | Airvet, Inc., Vetster, Inc., Petriage, Inc., FirstVet, PetDesk, VitusVet, JustAnswer, PawSquad, Whiskers Worldwide, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Telehealth Market Shifts & Advancements
Artificial intelligence diagnostic assistance is penetrating veterinary telehealth workflows, compressing triage timelines while raising new questions about liability allocation between algorithms and supervising clinicians.
Asynchronous messaging platforms are expanding into chronic condition management for diabetic and renal disease patients, enabling pet owners in the United States to transmit glucose logs and symptom updates without synchronous scheduling. Specialty veterinary groups are adopting these tools to extend endocrinology and cardiology reach into underserved metropolitan peripheries. The structural consequence is a compression of routine follow-up revenue into lower-unit-value digital encounters that platforms must aggregate at scale.
EU AI Act risk classification requirements are reshaping algorithm deployment in European veterinary diagnostics, mandating human oversight protocols for AI-assisted symptom checkers and image analysis tools. Platform operators are restructuring their machine learning pipelines to satisfy conformity assessment procedures. Small animal telehealth services in Germany and France face the steepest compliance adaptation curves as national regulators align with Brussels-level harmonization timelines.
Subscription-based care bundling is displacing per-consultation pricing among urban pet owners, with annual membership models now capturing routine wellness and behavioral triage in consolidated fees. Veterinary clinics in coastal United States markets are unbundling after-hours telehealth from daytime practice revenue, creating separate P&L lines for virtual services. This shift is most visible in California and New York metropolitan corridors where labor costs have accelerated clinic operating hour restrictions.
Global Veterinary Telehealth Market Segmentation
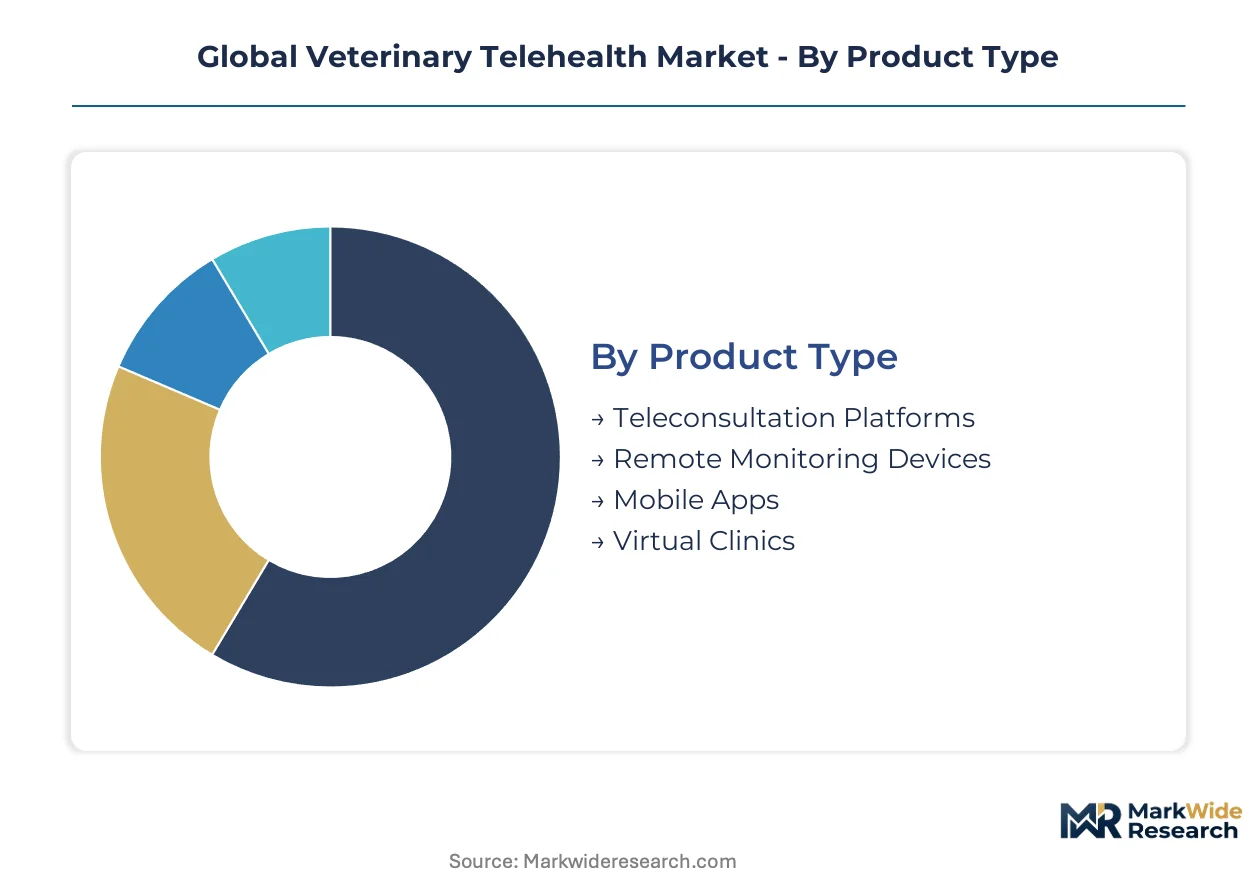
Telehealth platform architecture fragments across four distinct commercial configurations, each demanding different capital intensity and regulatory navigation. Supply-side specialization determines which segments capture margin versus volume in this expanding market.
Product Type:
Supply concentration clusters around platforms with integrated diagnostic workflows and pharmacy connectivity, while hardware-dependent segments face margin compression from component sourcing.
- Teleconsultation Platforms:Real-time video and asynchronous messaging systems bundled with EHR integration and prescription routing. Demand concentrates among United States veterinary groups seeking after-hours coverage without labor expansion, driven by workforce shortages compressing clinic capacity.
- Remote Monitoring Devices:Wearable sensors and connected diagnostic hardware transmitting physiological data to veterinary platforms. Livestock operators in Brazil and Australia deploy these for cattle welfare compliance, constrained by rural connectivity infrastructure gaps.
- Mobile Apps:Consumer-facing interfaces for symptom checking and appointment scheduling.
- Virtual Clinics:Fully digital practice models operating without physical facilities.
Today's leader: Teleconsultation Platforms. Tomorrow's challenger: Remote Monitoring Devices.
Application:
Cost tier differentiation separates high-frequency, low-acuity encounters from capital-intensive compliance monitoring in agricultural settings.
- Pet Health Management:Chronic disease tracking, behavioral triage, and wellness coaching for companion animals. United States urban pet owners drive volume through subscription models, with diabetes and renal disease management expanding fastest.
- Livestock Monitoring:Precision agriculture health tracking for cattle, poultry, and swine operations. European Union producers under Green Deal mandates represent the steepest expansion trajectory, requiring REACH-aligned data handling.
- Emergency Consultation:After-hours triage routing urgent cases to appropriate care levels.
- Preventive Care:Vaccination scheduling and routine wellness digitization.
Pet Health Management commands current revenue share. Livestock Monitoring is climbing the fastest as agricultural compliance tightens.
End User:
Customer type fragmentation creates divergent procurement patterns, from enterprise clinic networks to individual consumer subscriptions.
- Veterinary Clinics:Multi-location practices embedding telehealth into existing workflows. United States clinic aggregators are consolidating cloud infrastructure across distributed sites, reducing per-location IT capital requirements.
- Pet Owners:Direct-to-consumer demand accessed through marketplace platforms and insurer-embedded benefits. Smartphone penetration normalizes first-contact virtual care, converting untreated minor conditions into billable encounters.
- Animal Shelters:Non-profit and municipal facilities managing population health.
- Farm Managers:Commercial livestock operations deploying sensor networks for welfare compliance.
Pet Owners currently dominate addressable volume. Veterinary Clinics are gaining share fastest through B2B platform partnerships.
Deployment Mode:
Margin structure varies sharply between capital-light SaaS delivery and infrastructure-heavy on-premises installations.
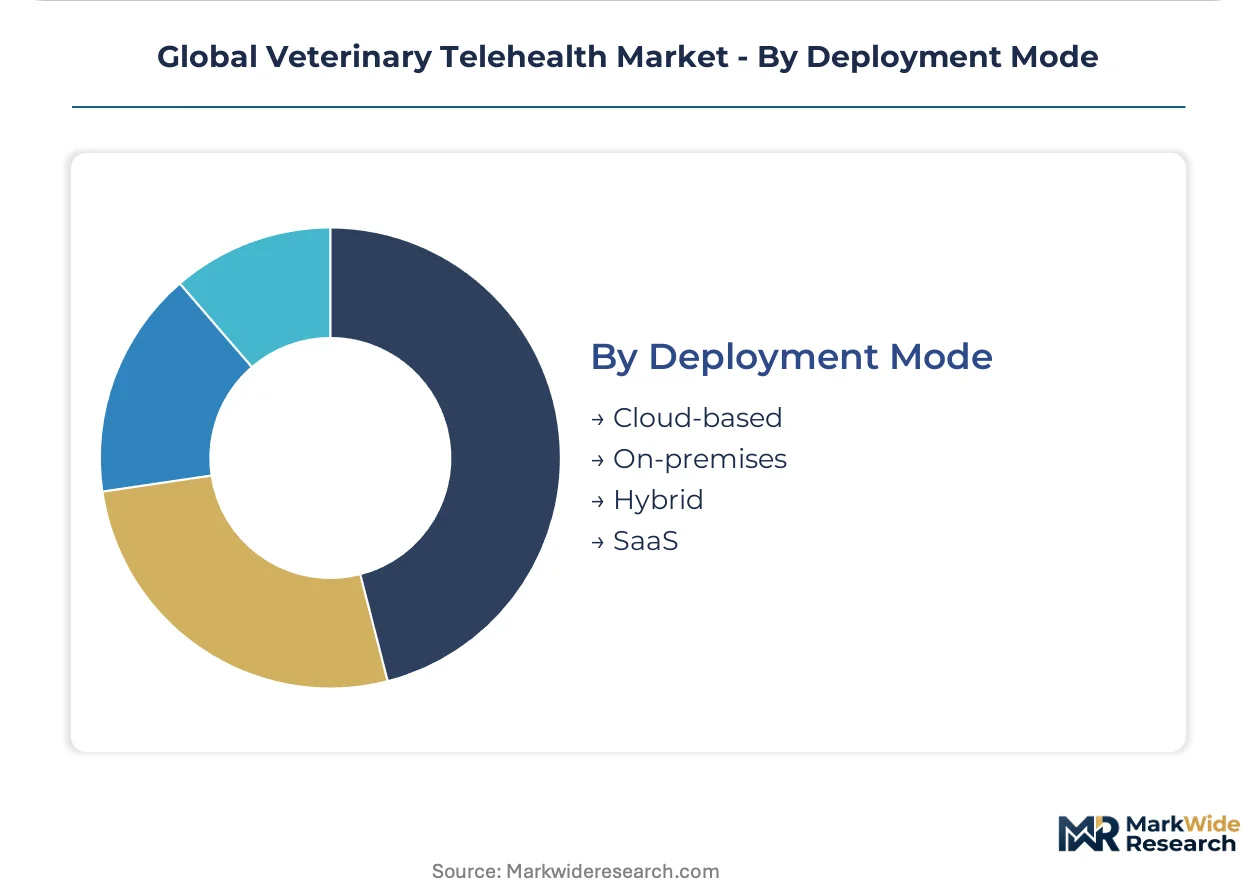
- Cloud-based:Multi-tenant architecture with subscription pricing and automatic scaling. United States and German veterinary networks favor this model for rapid multi-clinic rollout without server investment.
- SaaS:Software-as-a-service licensing with per-seat or per-practice fees. Smaller independent clinics in France and Canada adopt this for predictable operational expenditure.
- On-premises:Local server installation with full data control.
- Hybrid:Mixed cloud-local architecture for sensitive data retention.
Cloud-based deployment leads current adoption. SaaS is expanding most quickly among cost-sensitive independent practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger telehealth platform deployment than Germany, though both markets face divergent regulatory compliance burdens that reshape vendor market entry strategies.
United States
Veterinary workforce shortages and rural access gaps accelerate platform deployment across Texas and California metropolitan corridors. FDA engagement with digital prescribing standards reshapes interstate service legality for telemedicine platforms. The Southeast cluster spanning Florida and Georgia sees rapid subscription model adoption among urban pet owners seeking after-hours triage.
Germany
EU Green Deal animal welfare digitization mandates drive livestock monitoring platform demand across Bavarian and Lower Saxon agricultural zones. ECHA REACH-aligned data handling requirements add compliance layers for cloud-based veterinary platforms operating across member states. The Berlin-Brandenburg corridor anchors several telehealth software developers serving both companion animal and precision agriculture segments.
United Kingdom
Insurance-integrated triage models expand fastest among London and Southeast pet owners with comprehensive policy coverage. The national veterinary regulator maintains state-level licensure interpretations that complicate cross-border platform service delivery. Manchester and Birmingham veterinary groups consolidate cloud infrastructure across multi-clinic networks to reduce per-location IT capital requirements.
France
EU AI Act risk classification requirements reshape algorithm deployment for veterinary diagnostic assistance tools in Paris and Lyon metropolitan markets. ANSM oversight of digital health platforms intersects with national agricultural ministry welfare tracking mandates for livestock operators. The Occitanie region exhibits rising demand for remote monitoring devices among cattle producers facing tightened welfare compliance.
Australia
TGA regulatory frameworks for veterinary medical devices influence telehealth platform hardware certification requirements for remote physiological monitoring. Queensland and New South Wales livestock operators deploy connected health sensors across cattle stations to reduce on-site veterinary labor. Rural broadband infrastructure gaps in Western Australia constrain real-time video consultation access for remote agricultural producers.
Global Veterinary Telehealth Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the veterinary telehealth landscape, creating a tiered competitive structure where scale advantages clash with vertical expertise. The vendor base fragments across four distinct commercial configurations: marketplace platforms connecting independent veterinarians with consumers, insurance-embedded triage services, B2B clinic partnership embedders, and direct-to-consumer subscription operators. Two strategic archetypes dominate: technology-first platform builders and workflow-integrating practice enablers. Competitive moves concentrate on cloud infrastructure consolidation across multi-clinic networks and API development for EHR integration with legacy practice management systems.
Within the marketplace platform tier, Vetster, Inc. and Airvet, Inc. occupy positions representing divergent go-to-market approaches—direct-to-consumer marketplace architecture versus B2B clinic partnership embedding. FirstVet anchors the insurance-integrated triage archetype among European operators. These three entities exemplify how competitive positioning splits between displacing traditional clinic workflows and embedding virtual services within existing practice structures.
| Leading Market Players |
|---|
| Airvet, Inc. |
| Vetster, Inc. |
| Petriage, Inc. |
| FirstVet |
| PetDesk |
| VitusVet |
| JustAnswer |
| PawSquad |
| Whiskers Worldwide, LLC |
| Others |
Supply & Pricing Matrix
Subscription fatigue among United States pet owners is forcing platform operators to unbundle telehealth from wellness services, compressing SaaS pricing tiers and accelerating cloud infrastructure consolidation to preserve margins.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for EU-compliant telehealth platforms as REACH-aligned data handling requirements add compliance premiums. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated diagnostics from basic messaging tiers. Pricing pressure stems from veterinary clinic aggregators demanding volume discounts for multi-location cloud deployments. Independent practices in rural United States markets exhibit highest price sensitivity, while metropolitan specialty groups absorb premium tiers for EHR-integrated workflows.
Supply Chain Analysis
Domestic-content mandates in Brazil and Australia are reshaping sourcing for livestock monitoring hardware, pushing platform operators toward regional sensor assembly. Component supply concentrates in China for wearable devices, Taiwan for semiconductor modules, and Germany for precision agriculture sensors. Raw material dependencies span lithium-ion cells, medical-grade plastics, and veterinary-specific optical sensors. Single-source vulnerability in cloud server infrastructure creates concentration risk. Distribution runs through veterinary practice management system integrators and direct-to-consumer app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in veterinary telehealth rests on AI-assisted triage automation reducing per-consultation labor costs, while premium-tier subscription bundling captures chronic disease management revenue.
For Market Incumbents: Cement cloud infrastructure control across multi-clinic networks to lock in switching costs before EHR integration complexity rises. Defensive moves center on API development for legacy practice management systems and FDA digital prescribing framework pre-certification. Threat from AI-native entrants with lower compliance overhead demands accelerated algorithm deployment under veterinarian supervision protocols.
For New Entrants and Emerging Players: Enter via livestock monitoring white space in Brazil and Australia where USDA-equivalent welfare mandates create first-mover advantages without entrenched competitor density. Most penetrable segment combines remote physiological sensors with teleconsultation triage for cattle operations. Go-to-market angle pairs with agricultural cooperatives as channel partners rather than direct veterinary clinic sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with B2B clinic partnership embedders possessing established EHR integration capabilities and multi-state veterinary licensure infrastructure. Long-term viability favors platforms with insurance-embedded distribution and recurring revenue concentration above transactional consultation fees. Signal to watch is FDA finalization of interstate telemedicine prescribing rules as inflection indicator for scalable pharmacy-integrated models.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Integration | Automated triage compression reduces veterinarian labor cost per consultation across United States platforms. |
| Multi-Clinic Cloud Consolidation | Veterinary aggregators in Texas and California reduce per-location IT capital through shared infrastructure. |
| Insurance Partnership Embedding | FirstVet-style triage integration shifts pet owner first-contact behavior away from emergency clinics. |
| EU Green Deal Compliance Layer | REACH-aligned data handling opens livestock monitoring platforms to Bavarian agricultural procurement. |
| FDA Pre-Certification Investment | Interstate prescribing legality enables pharmacy-integrated scaling without physical facility expansion. |
Research Methodology
Direct dialogue with veterinary practice owners, telehealth platform CTOs, pet insurance product directors, and livestock operation managers anchored qualitative grounding. Secondary validation drew from FDA veterinary telemedicine guidance documents, USDA livestock remote monitoring standards, EU Green Deal animal welfare digitization mandates, and SEC filings of publicly traded veterinary service aggregators. Bottom-up consultation volume modeling and top-down market sizing triangulation produced convergent estimates.
Segment-level outputs across the projection horizon reflect deployment mode, application type, end-user category, and regional regulatory cluster variations. CAGRs were derived from weighted average growth trajectories incorporating smartphone penetration curves, veterinary workforce shortage projections, and cloud infrastructure adoption rates. Industry-specific inputs included state-by-state licensure fragmentation indices and precision agriculture capital flow patterns.
Inputs from veterinary medical boards and agricultural ministry officials were available through the study window; gaps in real-time broadband infrastructure deployment data introduce uncertainty bands for rural livestock monitoring adoption curves. Forecasts reflect documented assumptions regarding FDA regulatory timeline acceleration and EU AI Act veterinary diagnostic algorithm classification. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Europe Veterinarians Market
Veterinary
Veterinary Thermography Market
Veterinary
CBD Pet Market
Veterinary
Veterinary Excipients Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Vaccines Market
Veterinary
OTC Cat Medicines Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Otc Pet Medication Market
Veterinary
Global Swine Vaccines Market
Veterinary
Animal Antibiotics Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market