
 Lab Screening Test Kit Market | 2026-2036
Lab Screening Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Screening Test Kit Market Foresight
The gap between laboratory-grade and point-of-care molecular detection is narrowing as isothermal amplification chemistries and miniaturized optics converge in single-device platforms. Abbott Laboratories leverages its integrated diagnostics division to bridge centralized and decentralized workflows. Roche Diagnostics anchors its competitive stance through captive reagent ecosystems that lock in consumable pull-through.
Lab screening test kits comprise pre-configured reagent sets, calibrators, and detection substrates designed to identify target analytes in biological specimens through standardized biochemical reactions, typically requiring controlled temperature profiles and optical density thresholds for valid results. Their primary commercial purpose is to enable reproducible diagnostic or research outcomes without laboratory-developed method validation. Immunoassay-based formats sustain the largest revenue footprint given entrenched clinical chemistry infrastructure, while nucleic acid amplification technology captures the fastest expansion as PCR and isothermal methods displace culture-based identification in infectious disease panels. Point-of-care facilities represent a structurally distinct demand pocket where workflow speed overrides throughput economics.
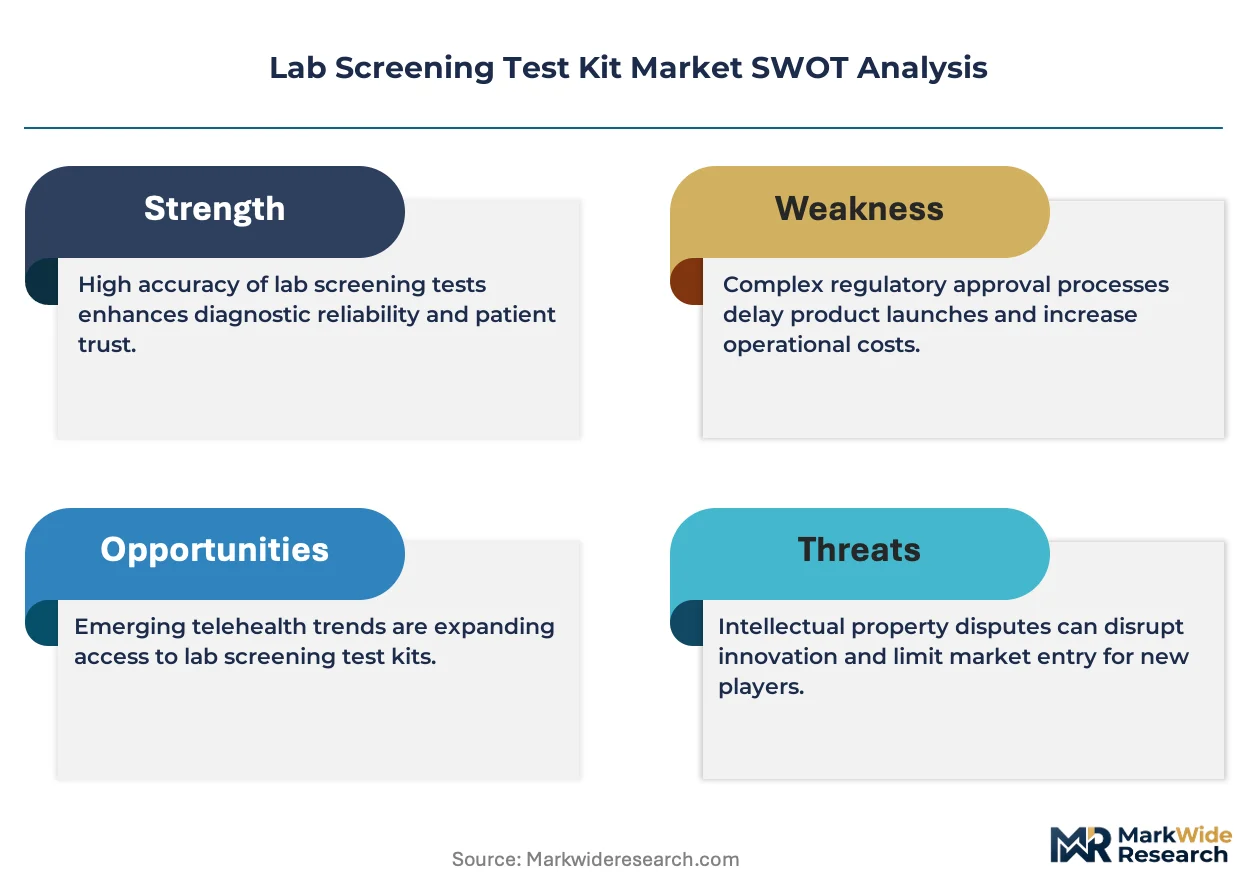
FDA oversight of in vitro diagnostics through premarket notification and quality system regulation shapes product development timelines and predicate device strategies for US market entrants. EMA's In Vitro Diagnostic Regulation in Europe imposes stricter clinical evidence and post-market surveillance requirements that favor well-capitalized manufacturers with established notified body relationships. Stakeholders must monitor how divergent transatlantic conformity pathways affect portfolio prioritization and manufacturing location decisions.
Market Dynamics
Isothermal amplification chemistries and miniaturized optics are converging to erase the performance gap between laboratory-grade and point-of-care molecular detection, compressing workflows and redrawing competitive boundaries.
Growth Catalysts
- Point-of-care testing expansion:Diagnostic centers across the United States are extending their testing menus into decentralized formats. This shift pulls demand toward rapid-result formats that bypass centralized laboratory logistics.
- EMA's In Vitro Diagnostic Regulation:Stricter clinical evidence requirements in Europe are consolidating manufacturer relationships with notified bodies. Well-capitalized firms capture market access advantages that smaller competitors cannot replicate.
- Isothermal amplification methods:Loop-mediated isothermal amplification and recombinase polymerase amplification are displacing traditional culture-based identification in infectious disease panels. These chemistries enable instrument-free or minimal-instrument detection at ambient temperatures.
Market Restraints
- Captive reagent lock-in:Closed-system architectures from dominant manufacturers tether users to proprietary consumable ecosystems. This concentration limits price competition and switching flexibility for clinical laboratories.
- Quality system validation costs:FDA premarket notification pathways impose documentation burdens that extend development timelines. Smaller developers face capital constraints that favor incumbent predicate-device strategies.
- Optical component supply concentration:Miniaturized photodetector and filter manufacturing concentrates in East Asian foundries. Geopolitical friction or logistics disruptions propagate through device production schedules.
Strategic Opportunities
- Home-use format regulatory pathway:FDA's evolving guidance on over-the-counter diagnostic devices is compressing approval timelines for consumer-accessible formats. Manufacturers that master usability validation and lay-user performance studies capture first-mover positioning.
- Integrated diagnostic workflows:Convergence of immunoassay and molecular detection on single platforms enables consolidated instrument footprints. Health systems pursuing laboratory consolidation value multi-analyte flexibility.
- Germany's clinical laboratory network:Demand concentration within Europe's largest diagnostic infrastructure creates anchor-customer relationships. Reagent rental and throughput-guarantee contracting models penetrate this concentrated buyer base.
Industry Challenges
- Multidisciplinary talent scarcity:Device development requires simultaneous mastery of microfluidics, biochemistry, and regulatory science. Compensation inflation for cross-functional teams strains development-stage company burn rates.
- Post-market surveillance infrastructure:EMA's strengthened vigilance requirements demand real-world performance tracking systems. Manufacturers must build data collection and adverse-event response capabilities that match pharmaceutical-grade expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Screening Test Kit Market |
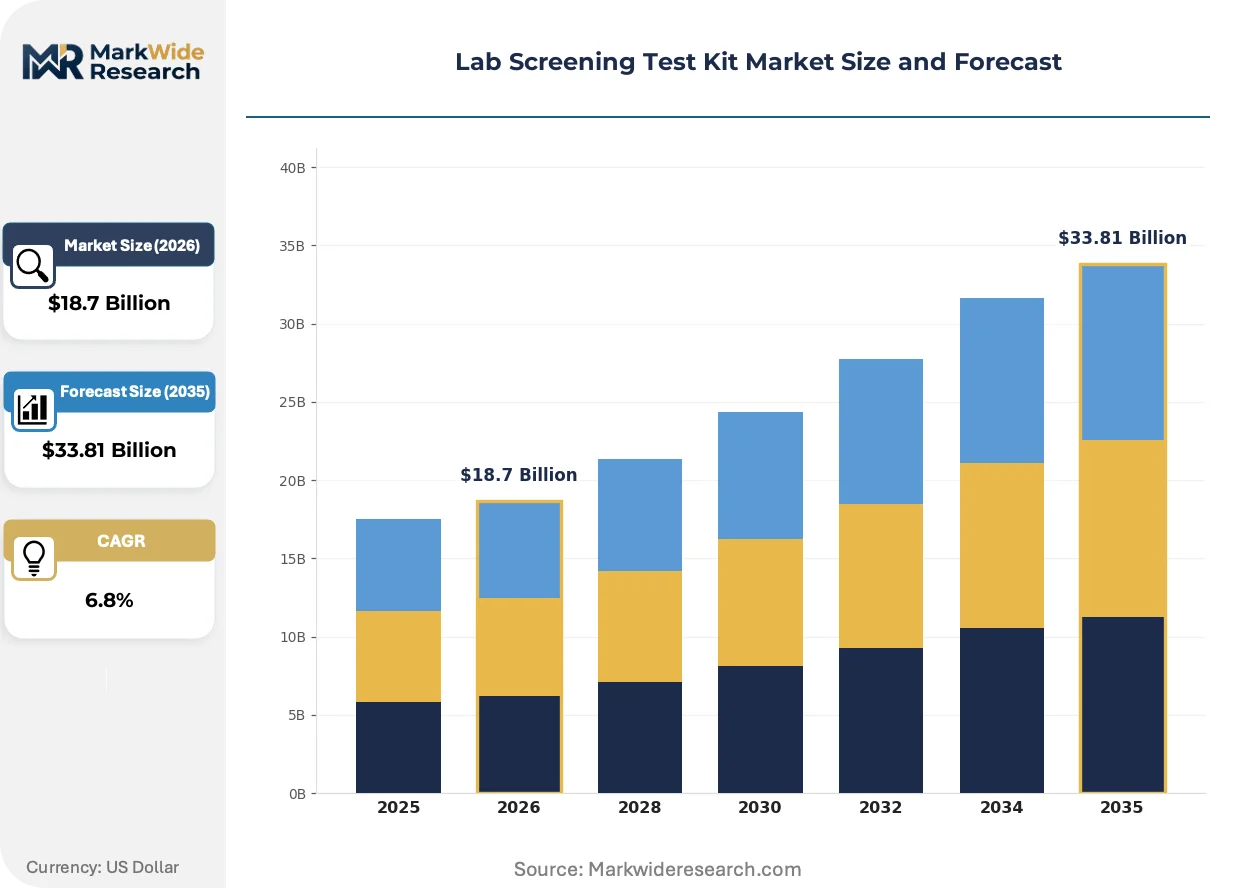
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, ELISA Kits, PCR Kits, Microarray Kits Technology: Immunoassay, Nucleic Acid Amplification, Electrophoresis, Chromatography End User: Clinical Laboratories, Diagnostic Centers, Research Institutions, Point-of-Care Facilities Delivery Mode: In vitro Diagnostics, Home Testing, Mobile Testing, Automated Systems |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Quest Diagnostics, Laboratory Corporation of America Holdings, Bio-Rad Laboratories, Danaher, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Screening Test Kit Market Shifts & Advancements
Workflow compression and detection sensitivity convergence are redefining where diagnostic decisions occur, shifting analytical capability toward the specimen collection point.
Loop-mediated isothermal amplification paired with smartphone-readable colorimetric endpoints is collapsing the equipment barrier for nucleic acid detection in resource-limited settings. Community health programs and pharmacy-based screening initiatives adopt these formats where capital budgets exclude thermal cycler infrastructure. The technology is collapsing the historical trade-off between analytical sensitivity and deployment flexibility.
EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements that parallel pharmaceutical approval standards. Manufacturers must generate prospective performance data and maintain post-market surveillance systems that track real-world device behavior. European notified body capacity constraints are extending certification timelines, favoring firms with established quality management infrastructure and predicate-device portfolios.
Health system procurement committees are consolidating vendor relationships around integrated platform contracts that bundle instruments, reagents, and service. Independent laboratory segments resist this concentration, but hospital-affiliated networks favor single-source accountability. This pattern is most visible in the United States, where health system consolidation has concentrated purchasing authority within integrated delivery networks.
Lab Screening Test Kit Market Segmentation
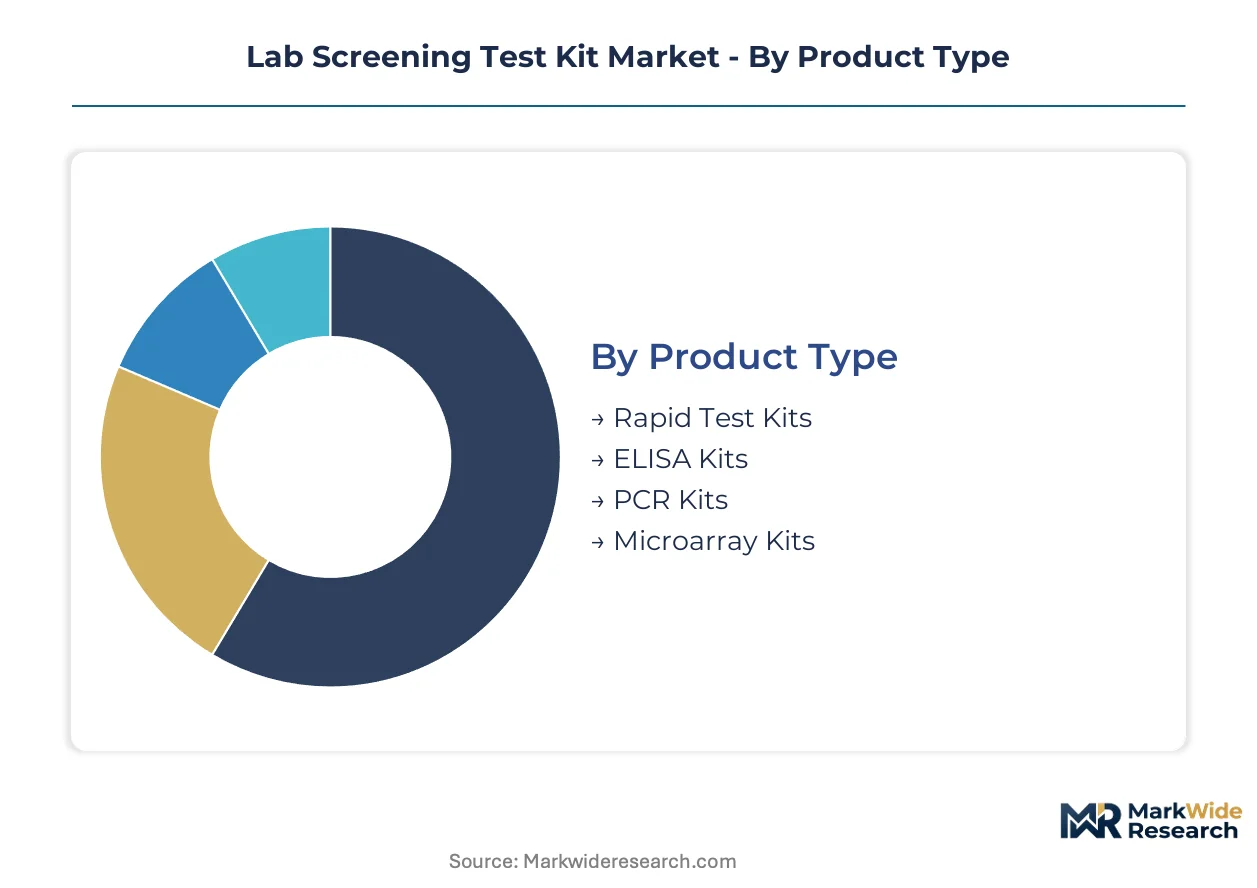
Segmentation in lab screening test kits reveals how technology maturation, regulatory pathways, and care delivery location jointly determine commercial viability. Each dimension carries distinct margin profiles and competitive entry barriers that shape portfolio construction.
Product Type:
Cost tier differentiation separates commodity reagent formats from precision-engineered molecular platforms requiring capital infrastructure.
- Rapid Test Kits:Lateral flow membranes and colorimetric substrates packaged for single-use deployment without thermal control. Demand concentrates in pharmacy-based screening programs across the United States where FDA's over-the-counter pathway accelerates commercialization timelines.
- ELISA Kits:Microplate-based enzyme-linked immunosorbent assays with optical density readouts requiring calibrated photometers. Clinical laboratories in Germany anchor procurement volumes through reagent rental contracts that guarantee throughput minimums.
- PCR Kits:Thermal cycling-dependent reagent sets with fluorescent probe chemistries for nucleic acid quantification.
- Microarray Kits:High-density probe arrays for multiplex analyte detection on single specimen inputs.
ELISA commands the established base. The steepest expansion runs through rapid formats bypassing centralized laboratory logistics.
Technology:
Application maturity stratifies between entrenched clinical chemistry infrastructure and emerging isothermal methods displacing legacy workflows.
- Immunoassay:Antigen-antibody binding reactions with enzymatic or chemiluminescent signal amplification. Diagnostic centers in the United States sustain volume concentration through integrated chemistry analyzers that lock in consumable pull-through.
- Nucleic Acid Amplification:PCR and isothermal chemistries including loop-mediated amplification for pathogen detection at reduced equipment thresholds. Point-of-care facilities in resource-limited settings adopt these formats where capital budgets exclude thermal cycler infrastructure.
- Electrophoresis:Charge-based separation methods for protein and nucleic acid fractionation.
- Chromatography:Partition-based separation for metabolite and hormone quantification.
Immunoassay retains the volume foundation. Nucleic acid methods are gaining share fastest as infectious disease panels shift from culture-based identification.
End User:
Customer type determines purchasing authority concentration versus fragmentation, with health system consolidation favoring integrated vendor relationships.
- Clinical Laboratories:High-throughput facilities with automated track systems and dedicated quality control personnel. Germany's clinical laboratory network concentrates European demand through centralized procurement committees.
- Diagnostic Centers:Decentralized testing sites extending menus into rapid-result formats. United States diagnostic centers are expanding point-of-care capabilities to bypass centralized laboratory logistics.
- Research Institutions:Academic and pharmaceutical laboratories with method development requirements and flexible validation standards.
- Point-of-Care Facilities:Physician offices, pharmacies, and community health sites prioritizing workflow speed over analytical throughput.
Clinical laboratories anchor revenue stability. Point-of-care facilities are expanding most quickly as FDA compresses approval timelines for decentralized formats.
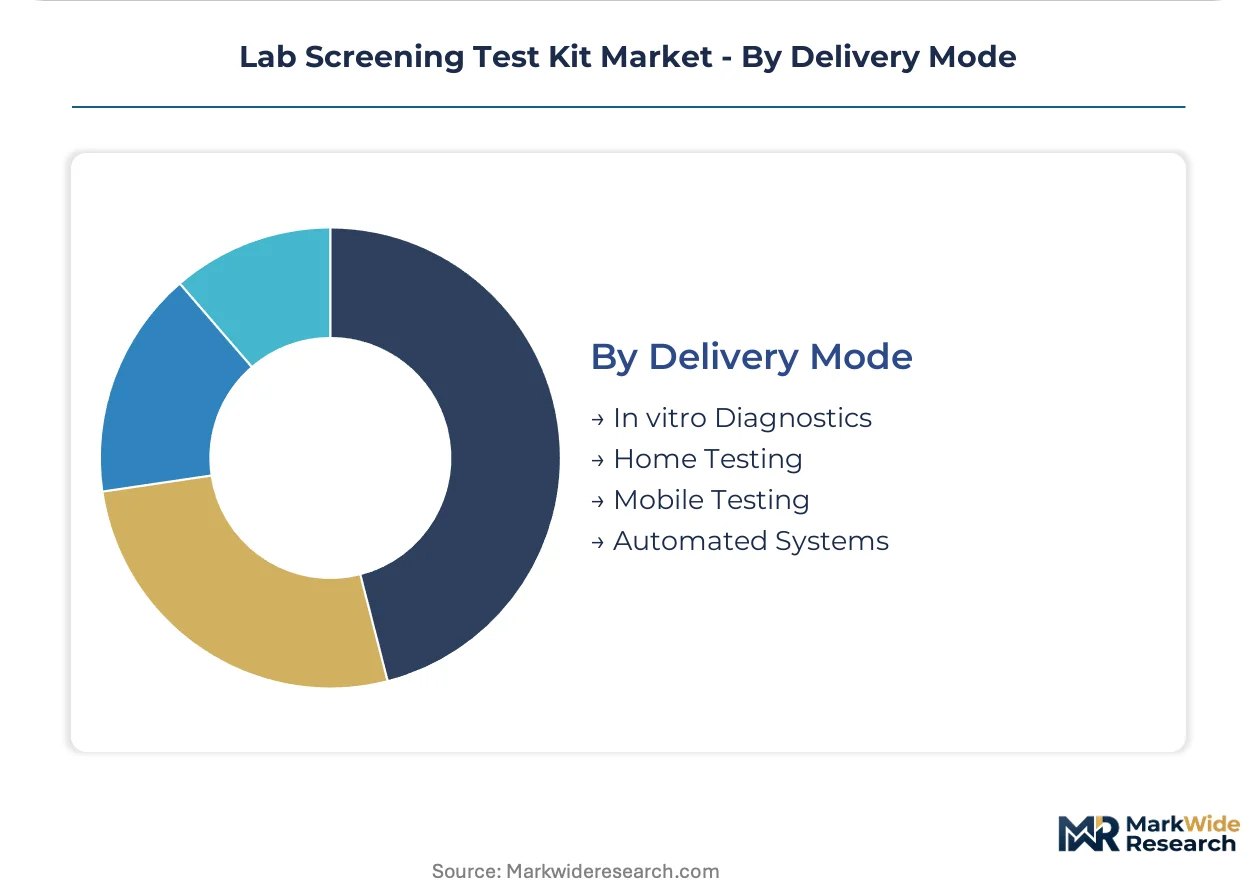
Delivery Mode:
Supply concentration varies sharply between regulated in vitro diagnostics and emerging direct-to-consumer channels with distinct liability frameworks.
- In vitro Diagnostics:Professional-use devices subject to FDA premarket notification or EMA's In Vitro Diagnostic Regulation with quality system requirements. EMA's stricter clinical evidence standards favor well-capitalized manufacturers with established notified body relationships.
- Home Testing:Over-the-counter formats requiring usability validation and lay-user performance studies. FDA's evolving guidance on consumer-accessible devices is compressing development timelines for manufacturers mastering human factors engineering.
- Mobile Testing:Deployable units for temporary screening events and remote population access.
- Automated Systems:Integrated platforms consolidating sample preparation, detection, and result reporting.
In vitro diagnostics maintains the revenue core. Home testing represents the steepest trajectory as regulatory pathways mature for consumer-directed screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports diagnostic reagent systems to clinical laboratory networks across France and the Netherlands, while the United States supplies point-of-care platforms to Canadian diagnostic centers and Mexican hospital chains.
United States
Diagnostic centers in California and Texas are extending point-of-care testing menus into pharmacy-based screening programs. FDA's evolving guidance on over-the-counter diagnostic devices compresses approval timelines for home-use formats. The Boston-Cambridge corridor concentrates molecular detection startups developing isothermal amplification platforms.
Germany
Clinical laboratory networks in Bavaria and North Rhine-Westphalia anchor European demand for high-throughput immunoassay systems. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements that favor established notified body relationships. The Rhine-Main cluster around Frankfurt hosts reagent manufacturers pursuing throughput-guarantee contracts with centralized buyers.
China
Domestic diagnostic chains in Shanghai and Guangzhou are adopting nucleic acid amplification platforms for infectious disease panels. NMPA oversight of in vitro diagnostics shapes predicate device strategies for market entrants. The Yangtze River Delta concentrates contract manufacturers of miniaturized optical components for point-of-care devices.
Japan
Hospital-affiliated laboratories in Tokyo and Osaka prioritize integrated platform contracts bundling instruments and consumables. PMDA quality system regulations extend development timelines for novel detection chemistries. The Kansai region hosts precision optics suppliers serving molecular detection device assemblers.
India
Diagnostic center chains in Maharashtra and Karnataka are expanding rapid-test capabilities for decentralized infectious disease screening. CDSCO regulation of medical devices requires import license pathways for foreign manufacturers. The Delhi-NCR corridor concentrates distributors bridging global reagent suppliers to regional laboratory networks.
Lab Screening Test Kit Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered competitive strata. The vendor base clusters around three structural positions: diversified conglomerates with integrated diagnostics divisions, pure-play reagent manufacturers with captive consumable ecosystems, and emerging platform developers attacking point-of-care workflows. Consolidation pressure operates through strategic partnerships and technology licensing rather than outright acquisition, as regulatory compliance capabilities become the scarcest competitive asset.
Among diversified health technology conglomerates, Abbott Laboratories and Roche Diagnostics occupy positions exemplifying the integrated diagnostics archetype, while Siemens Healthineers anchors the European-centered precision engineering tier. These entities represent channel-control strategies that bundle instrument placement with long-term reagent supply commitments, locking in clinical laboratory purchasing committees through total-cost-of-ownership contracting models.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Bio-Rad Laboratories |
| Danaher |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Optical component supply concentration in East Asian foundries creates tariff exposure and logistics chokepoints that compress margin spreads between premium molecular platforms and economy rapid-test formats while forcing manufacturers toward dual-source qualification strategies.
Pricing Analysis
The technology-generation pricing gap separates legacy ELISA microplate systems from current-generation isothermal amplification platforms and emerging smartphone-integrated colorimetric endpoints. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-cleared home-use formats commanding brand premiums over professional-use CE-marked equivalents. Pricing pressure stems from captive reagent lock-in tactics by dominant manufacturers, which limits switching flexibility and intensifies cost compression in the independent laboratory segment. Hospital-affiliated networks exhibit lowest price sensitivity due to total-cost-of-ownership contracting, while point-of-care facilities in resource-limited settings represent the most price-constrained buyer archetype.
Supply Chain Analysis
Contract-manufacturing concentration rests with precision optics foundries in Japan's Kansai region and microfluidic component specialists in China's Yangtze River Delta. Raw material dependencies center on photoresist chemicals, rare-earth doped optical fibers, and stabilized enzyme preparations sourced from Germany, Japan, and the United States. Single-source vulnerability concentrates in miniaturized photodetector arrays, where geopolitical friction propagates through device production schedules. Distribution runs through authorized distributor networks serving hospital purchasing committees and GPO contracts, with direct-to-laboratory fulfillment gaining share in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional mastery of microfluidics, biochemistry, and regulatory science represents the scarcest capability asset, with compensation inflation for multidisciplinary teams already straining development-stage company burn rates.
For Market Incumbents: Harden captive reagent ecosystems through throughput-guarantee contracting with Germany's centralized laboratory networks, while accelerating predicate-device portfolios to navigate EMA's extended certification timelines. Vertical integration into miniaturized optical component sourcing mitigates East Asian foundry concentration risk. For New Entrants and Emerging Players: Establish a beachhead in pharmacy-based screening programs across the United States, where FDA's compressed over-the-counter approval timelines create first-mover positioning. Loop-mediated isothermal amplification formats for infectious disease panels offer the most penetrable white space, with human factors engineering capabilities as the critical go-to-market differentiator. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors quality-management infrastructure over novel chemistry development, with notified body relationships and post-market surveillance capabilities commanding acquisition premiums. Long-term viability hinges on regulatory compliance assets rather than single-product innovation. Monitor FDA guidance evolution on home-use formats as the primary inflection signal for consumer-accessible segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Expansion | EMA's stricter clinical evidence requirements favor manufacturers with established European certification partnerships. |
| Isothermal Amplification Platform Launch | Instrument-free detection at ambient temperatures collapses capital barriers for point-of-care facilities. |
| Integrated Diagnostics Division Consolidation | Single-platform contracts bundling immunoassay and molecular detection capture health system procurement committees. |
| Home-Use Format Usability Validation | FDA's evolving over-the-counter guidance compresses timelines for manufacturers mastering lay-user performance studies. |
| Post-Market Surveillance Infrastructure Buildout | EMA's pharmaceutical-grade vigilance requirements demand real-world performance tracking systems matching adverse-event response capabilities. |
Research Methodology
The analysis maps immunoassay infrastructure, nucleic acid amplification platforms, point-of-care rapid formats, and home-use over-the-counter devices, each validated through purchasing committee directors at hospital-affiliated networks, regulatory affairs leads at diversified diagnostics conglomerates, GPO contracts managers, and point-of-care facility procurement officers. Secondary sources include FDA 510(k) premarket notification databases, EMA's EUDAMED vigilance system, hospital procurement databases, and CMS laboratory fee schedule data. Bottom-up reagent volume estimates triangulate against top-down health system expenditure tracking.
Assumptions hold regulatory pathway timelines and notified body capacity fixed at current constraints, with tariff exposure on East Asian optical components and EMA certification backlogs treated as variant scenarios across the projection horizon. Segmentation dimensions span product type, detection technology, end-user facility category, and delivery mode, with infectious disease panel shift rates from culture-based identification serving as a primary volume driver input.
Sensitivities concentrate around FDA guidance acceleration on home-use formats, EMA notified body capacity expansion, and geopolitical disruption to miniaturized photodetector supply chains. Quarterly review of regulatory submission volumes, certification timeline announcements, and optical component import data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Tuberculosis Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Active B12 Test Market
Testing Services
Diagnostic Shipper Market
Testing Services
Nipah Virus Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Allergy Skin Test Market
Testing Services
Osmometer Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Influenza Home Testing Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
US Viral Clearance Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market