
 Healthcare Information Software Market | 2026-2036
Healthcare Information Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Information Software Market Intelligence
Cloud infrastructure is consolidating around healthcare information software as health systems abandon capital-intensive server farms for subscription-based platforms. Epic Systems leverages its dominance in integrated care networks across large academic medical centers. Oracle Cerner sustains extensive installed bases through backward integration into database and cloud infrastructure. Siemens Healthineers anchors European hospital digitization with imaging-to-informatics workflows.
Healthcare information software encompasses systems that capture, store, manage, and transmit patient data through standardized protocols such as HL7 FHIR, with core functions spanning clinical documentation, order entry, and interoperability exchange between disparate care settings. Electronic health records occupy mature margin pools as established vendors defend recurring maintenance contracts, while cloud-based deployment captures fastest-growing procurement as health systems seek elastic capacity and reduced IT overhead. Clinical decision support segments specialize in algorithmic diagnostic assistance that reduces variability in physician judgment.
FDA oversees software-as-medical-device classifications that determine premarket pathways for clinical decision support tools, while HIPAA mandates encryption and access controls that shape product architecture requirements for any US-facing vendor. The EU AI Act introduces conformity obligations for machine-learning diagnostic modules that will fragment compliance costs across Atlantic and European product roadmaps. Stakeholders must monitor whether emerging liability frameworks assign accountability to software developers or deploying institutions when algorithmic recommendations contribute to adverse outcomes.
Market Dynamics
Cloud-native architecture is displacing legacy on-premises installations as health systems prioritize interoperability and remote access capabilities. This structural shift concentrates procurement power among integrated delivery networks seeking elastic capacity and reduced IT overhead.
Growth Catalysts
- HIPAA mandates:Encryption and access control requirements accelerate replacement of non-compliant legacy systems across US hospital networks.
- HL7 FHIR protocols:Standardized data exchange frameworks enable seamless interoperability between previously siloed clinical settings.
- German hospital digitization:Federal funding programs for electronic health records drive procurement cycles in Europe's largest healthcare market.
Market Restraints
- Specialized cybersecurity talent:Shortage of healthcare IT security professionals constrains deployment velocity for cloud migrations.
- EU AI Act fragmentation:Conformity obligations for machine-learning diagnostic modules create divergent product roadmaps across Atlantic markets.
- Legacy system entrenchment:Deep integration of existing electronic health records creates switching friction and extends replacement cycles.
Strategic Opportunities
- Japan's aging demographics:Chronic disease management platforms face underpenetrated demand in the world's oldest population.
- Clinical decision support algorithms:FDA software-as-medical-device pathways open premarket channels for diagnostic assistance tools.
- Remote patient monitoring:Convergence of wearable sensors and cloud analytics creates new reimbursement categories for continuous care.
Industry Challenges
- Interoperability engineering:Integration complexity with proprietary legacy databases consumes implementation timelines and budget.
- Liability framework ambiguity:Unclear accountability assignment between software developers and deploying institutions when algorithmic recommendations contribute to adverse outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Information Software Market |
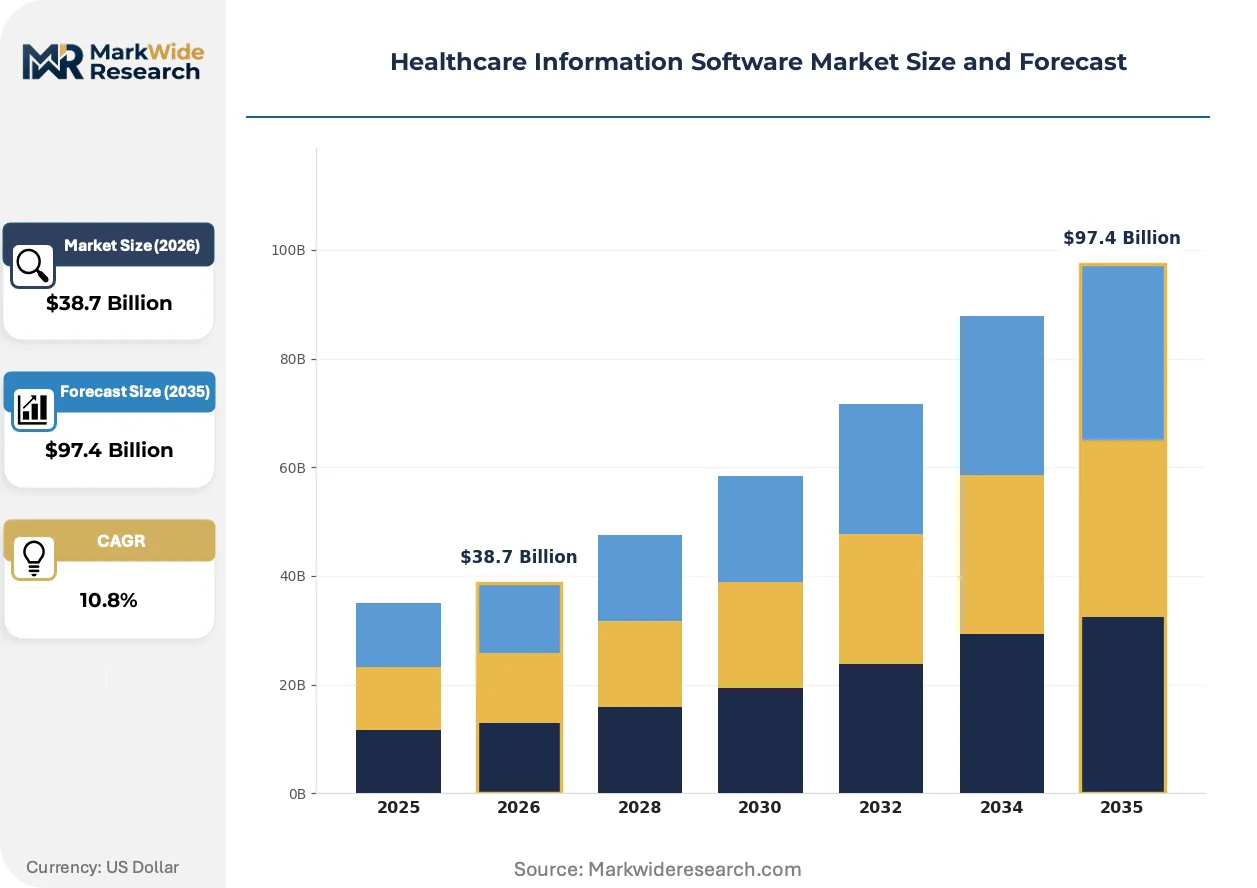
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $97.4 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Practice Management Software, Clinical Decision Support, Laboratory Information Systems, Radiology Information Systems, Patient Portals Application: Patient Data Management, Revenue Cycle Management, Diagnostic Support, Telemedicine, Appointment Scheduling, Billing Management End User: Hospitals, Clinics, Diagnostic Centers, Specialty Care Providers, Home Care Providers, Rehabilitation Centers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile-Based, Web-Based, SaaS |
| Companies Covered | athenahealth, Siemens Healthineers, Epic Systems, Cognizant, Accenture, Oracle Cerner, Philips Healthcare, Merative, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Information Software Market Strategic Shifts & Innovations
Healthcare information software is undergoing rapid architectural transformation as artificial intelligence capabilities mature and regulatory frameworks crystallize around algorithmic accountability.
Generative AI documentation tools automate clinical note generation from physician-patient encounters. Large academic medical centers pilot these systems to reduce administrative burden on clinicians. The technology is expanding into specialty workflows including radiology report drafting and pathology summaries.
The EU AI Act introduces risk-based conformity assessments for machine-learning diagnostic modules deployed in European hospitals. Manufacturers must maintain technical documentation and human oversight protocols for high-risk applications. Clinical decision support vendors are restructuring product roadmaps to segregate Atlantic and European compliance pathways.
Subscription-based procurement models displace perpetual licensing arrangements in health system purchasing. Chief information officers favor operational expenditure structures that align software costs with utilization. This behavioral shift is most visible in United States integrated delivery networks consolidating vendor relationships under enterprise agreements.
Healthcare Information Software Market Segmentation
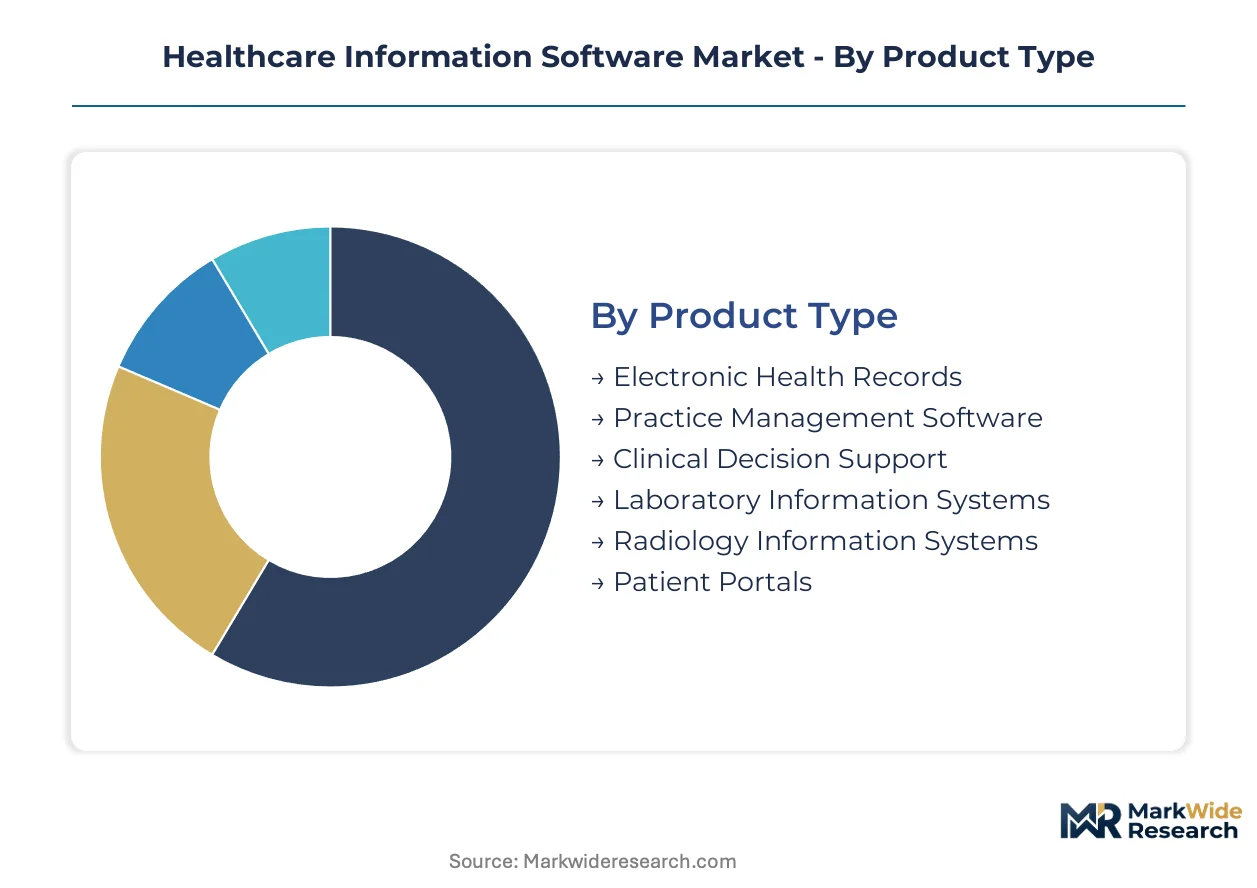
Segmentation in healthcare information software reveals how procurement patterns diverge across clinical workflows, infrastructure maturity, and regulatory exposure. Vendors configure product architectures differently for academic medical centers versus ambulatory networks. Understanding these divides illuminates where integration complexity concentrates and where standardization accelerates deployment velocity.
Product Type:
Supply concentration in this category tilts toward integrated suites that bundle documentation with revenue cycle functions, leaving standalone modules to serve specialized niches.
- Electronic Health Records:Core clinical repositories capturing longitudinal patient data through structured templates and interoperability protocols. United States hospital networks drive replacement demand as HIPAA mandates force retirement of non-compliant legacy installations.
- Clinical Decision Support:Algorithmic modules that surface diagnostic recommendations and alert clinicians to drug interactions or protocol deviations. FDA software-as-medical-device classifications determine premarket pathways, concentrating development investment in large academic centers with research infrastructure.
- Practice Management Software:Administrative platforms coordinating scheduling, registration, and referral workflows for ambulatory settings.
- Laboratory Information Systems:Specimen tracking and result management tools for pathology and clinical chemistry operations.
- Radiology Information Systems:Imaging workflow orchestrators integrating with PACS archives and dictation systems.
- Patient Portals:Consumer-facing interfaces enabling appointment booking, result access, and secure messaging with care teams.
Electronic Health Records absorbs the bulk of installed capacity; Clinical Decision Support is expanding most quickly.
Application:
Cost tier differentiation separates enterprise-grade platforms commanding annual subscriptions from lightweight modules targeting independent practices with per-provider pricing.
- Patient Data Management:Centralized repositories enabling longitudinal record access across care transitions. German hospital digitization programs accelerate procurement as federal funding subsidizes interoperability infrastructure.
- Revenue Cycle Management:Financial workflow engines optimizing claims submission, denial management, and patient collections. United States integrated delivery networks consolidate these functions under enterprise agreements to align software costs with utilization.
- Diagnostic Support:Algorithmic assistance for image interpretation and laboratory result correlation.
- Telemedicine:Virtual visit platforms with embedded documentation and prescribing capabilities.
- Appointment Scheduling:Calendar optimization tools reducing no-show rates through automated reminders.
- Billing Management:Charge capture and coding assistance ensuring documentation supports reimbursement claims.
Patient Data Management commands the largest addressable spend; Telemedicine is climbing the fastest as reimbursement categories mature for virtual care delivery.
End User:
Customer type fragmentation creates divergent sales cycles, with health systems demanding extensive customization while ambulatory buyers prioritize rapid deployment.
- Hospitals:Acute care facilities requiring enterprise-scale platforms with 24/7 uptime guarantees and disaster recovery protocols. Cloud-native architecture is displacing legacy on-premises installations as these institutions prioritize remote access for distributed clinical staff.
- Clinics:Outpatient settings favoring subscription models that convert capital expenditure to operational budgets aligned with patient volume fluctuations.
- Diagnostic Centers:Imaging and laboratory facilities needing specialized workflow integration with modality equipment.
- Specialty Care Providers:Cardiology, oncology, and orthopedics practices requiring disease-specific documentation templates.
- Home Care Providers:Mobile documentation tools supporting point-of-care data capture in patient residences.
- Rehabilitation Centers:Functional outcome tracking platforms for physical and occupational therapy workflows.
Hospitals absorb the bulk of installed capacity; Home Care Providers is gaining share fastest as aging demographics expand community-based service models.
Deployment:
Margin structure varies dramatically across delivery models, with SaaS platforms capturing recurring revenue streams while perpetual licenses concentrate maintenance fees in established vendor relationships.
- Cloud-Based:Multi-tenant architectures enabling elastic capacity scaling without capital-intensive server infrastructure. United States health systems lead migration as CIOs favor operational expenditure structures reducing IT overhead.
- SaaS:Subscription-native platforms with continuous feature delivery and automatic compliance updates. EU AI Act conformity obligations for machine-learning modules are restructuring product roadmaps to segregate Atlantic and European compliance pathways.
- On-Premises:Self-hosted installations retaining data within facility-controlled hardware environments.
- Hybrid:Mixed architectures preserving sensitive workloads on-premises while leveraging cloud analytics.
- Mobile-Based:Native applications for smartphone and tablet documentation at the point of care.
- Web-Based:Browser-accessible platforms minimizing client-side installation requirements.
Cloud-Based deployment absorbs the bulk of new procurement investment; SaaS is expanding most quickly as vendor business models shift from perpetual licensing to recurring revenue structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where regulatory mandates for electronic health records and data portability are accelerating procurement cycles. Health systems in these markets prioritize cloud-native platforms over legacy installations. Federal funding and compliance deadlines are compressing replacement timelines.
United States
Hospital networks across the United States are expanding adoption of integrated clinical platforms. HIPAA mandates encryption and access control requirements that accelerate replacement of non-compliant legacy systems. Large academic medical centers in Boston and the Research Triangle pilot generative AI documentation tools to reduce administrative burden on clinicians.
Germany
Federal funding programs for electronic health records drive procurement cycles in Europe's largest healthcare market. The country's hospital digitization initiative subsidizes interoperability infrastructure across state hospital networks. Siemens Healthineers anchors European hospital digitization with imaging-to-informatics workflows centered in Erlangen and Munich.
Japan
Chronic disease management platforms face underpenetrated demand in the world's oldest population. METI guidelines on healthcare data utilization are shaping platform architecture requirements for domestic vendors. Tokyo and Osaka medical centers are consolidating procurement under enterprise agreements that favor subscription-based operational expenditure models.
United Kingdom
NHS England's mandate for interoperable electronic health records is consolidating vendor relationships across integrated care systems. GDPR compliance obligations shape product architecture for any UK-facing deployment. London's academic health science centers serve as testbeds for clinical decision support algorithms seeking regulatory clearance.
India
CDSCO oversight of software-as-medical-device classifications is clarifying premarket pathways for diagnostic assistance tools. The country's national health stack initiative is standardizing data exchange protocols across public and private hospital networks. Bengaluru and Hyderabad health technology clusters are attracting investment in cloud-native platform development.
Healthcare Information Software Market Key Industry Players
Backward integration into cloud infrastructure dominates the current landscape as established vendors defend recurring maintenance contracts. The market structure tilts toward integrated suites that bundle documentation with revenue cycle functions, leaving standalone modules to serve specialized niches. Three archetypes prevail: academic medical center specialists, ambulatory network consolidators, and imaging-to-informatics workflow integrators. M&A activity and strategic partnerships are the dominant competitive moves as vendors seek elastic capacity and reduced IT overhead for health system clients.
Among US-based platform developers, Epic Systems and Oracle Cerner occupy positions within the integrated care network tier, while Siemens Healthineers represents the European imaging-to-informatics archetype. These three anchors exemplify how geographic origin and company structure shape competitive positioning: Epic Systems as a privately held developer of comprehensive clinical repositories, Oracle Cerner leveraging database and cloud infrastructure integration through its corporate parent, and Siemens Healthineers as a German AG anchoring European hospital digitization with modality-to-informatics workflows.
| Leading Market Players |
|---|
| athenahealth |
| Siemens Healthineers |
| Epic Systems |
| Cognizant |
| Accenture |
| Oracle Cerner |
| Philips Healthcare |
| Merative |
| GE HealthCare |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through subscription pricing tiers as health systems abandon capital-intensive server farms for operational expenditure models, with HIPAA compliance investments and HL7 FHIR integration complexity stratifying vendor offerings across academic medical centers, community hospitals, and ambulatory networks.
Pricing Analysis
Volume concentrates in subscription-native SaaS platforms while margin pools persist in maintenance contracts for legacy on-premises installations. Pricing stratifies across enterprise-grade integrated suites, mid-tier modular deployments, and lightweight per-provider arrangements for independent practices. Cost compression in cloud infrastructure tiers is intensifying because hyperscaler competition erodes hosting margins. Community hospitals exhibit highest price sensitivity due to constrained IT budgets, while large academic medical centers prioritize customization over cost.
Supply Chain Analysis
Dual-sourcing requirements from health system procurement committees mandate multi-cloud qualification across Amazon Web Services, Microsoft Azure, and Google Cloud Platform to mitigate single-provider downtime risk. Software development draws from engineering talent pools concentrated in the United States, India, and Germany. Supply chain risk centers on specialized healthcare IT security professional shortages constraining deployment velocity. Distribution runs through direct enterprise sales teams and value-added resellers serving regional hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare information software functions as a consolidation play where cloud migration costs and regulatory compliance burdens force weaker regional vendors toward acquisition or exit.
For Market Incumbents: Cement dominance through backward integration into cloud infrastructure and captive AI/ML development capabilities. Defend against emerging cloud-native challengers by locking hospital networks into enterprise agreements that bundle EHR with revenue cycle and population health modules. Prioritize FDA software-as-medical-device certification investment to create regulatory moats around clinical decision support offerings. For New Entrants and Emerging Players: Specialty care providers in cardiology and oncology represent the most penetrable buyer archetype, as these segments demand disease-specific documentation templates that incumbent integrated suites underserve. Japan's aging demographics and underpenetrated chronic disease management platforms offer geographic white space. Pursue partnership-first go-to-market angles with regional health technology distributors rather than direct hospital sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap clinical decision support specialists with FDA clearance pipelines in the United States and EU AI Act conformity documentation in progress. Long-term viability over a decade horizon hinges on recurring revenue share and interoperability certification depth. Watch FDA software-as-medical-device enforcement patterns as the inflection signal determining which algorithmic diagnostic modules achieve reimbursable status.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems and Oracle Cerner consolidate hospital network relationships through unified clinical and financial workflows. |
| Strategic Partnership | Siemens Healthineers anchors European digitization by bundling imaging modalities with informatics infrastructure. |
| Acquisition of Specialist Firm | Cloud-native clinical decision support vendors seek FDA-cleared algorithmic modules to accelerate regulatory pathways. |
| Geographic Expansion | Japan's METI guidelines on healthcare data utilization shape platform architecture for Tokyo and Osaka medical centers. |
| Reimbursement Strategy | Remote patient monitoring convergence with wearable sensors creates new CMS billing categories for continuous care delivery. |
Research Approach
Independent corroboration across hospital CIO interviews, health system procurement database analysis, and FDA software-as-medical-device filing review underwrites the qualitative findings. Primary fieldwork engaged chief information officers at integrated delivery networks, biomedical engineers at academic medical centers, GPO contracts managers, and cloud infrastructure specialists. Secondary validation drew from CMS Medicare reimbursement data, hospital capital expenditure disclosures, HL7 FHIR implementation registries, and hyperscaler healthcare vertical revenue reports. Bottom-up deployment estimates and top-down market sizing triangulate to constrain variance.
Comparable-period anchoring to historical EHR replacement cycles and cloud migration trajectories structured the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, organization scale, clinical workflow integration complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to procurement velocity indicators and vendor backlog disclosures. Forecast inputs incorporate HIPAA compliance deadline schedules and German hospital digitization subsidy program allocations.
Revisions become necessary when FDA software-as-medical-device reclassification actions, EU AI Act enforcement divergence, or hyperscaler healthcare cloud pricing realignments materialize. Deviation in health system capital expenditure prioritization away from clinical platforms toward revenue cycle consolidation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Global Medical Transcription Software Market