
 Global Dermatology Excimer Laser Market | 2026-2036
Global Dermatology Excimer Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatology Excimer Laser Market Foresight
Preventive maintenance contracts and software-defined fluence calibration is consolidating into standard equipment packages, shifting vendor revenue from pure hardware to recurring service streams. Lumenis leverages its installed base across academic medical centers to lock in multi-year service agreements. Alma Lasers competes through region-specific training certifications that bind clinicians to its technical support ecosystem.
Dermatology excimer lasers emit coherent ultraviolet B light at 308 nanometers, selectively targeting pathological skin tissue while sparing surrounding epidermis through monochromatic precision and controlled pulse duration. The 308 nm Excimer Laser segment dominates procedural volumes in psoriasis protocols, while Gas Laser technology sustains margin pools through xenon-chloride gas replacement cycles and chamber refurbishment revenue. UVB Excimer Laser configurations anchor growth in vitiligo repigmentation where narrowband delivery protocols command premium positioning against broadband alternatives.
FDA 510(k) clearance pathways govern commercial entry in the United States, while the EU Medical Device Regulation and CE marking requirements shape product standardization across European member states. The analysis indicates stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies as these determinations directly gate clinic-level procurement cycles and equipment replacement timelines.
Market Dynamics
The dermatology excimer laser market pivots on reimbursement pathway maturation, where Medicare coding decisions in the United States and national health technology assessments in Germany and France directly gate clinic procurement cycles and equipment replacement timelines.
Growth Catalysts
- Medicare Reimbursement Expansion:The United States Centers for Medicare and Medicaid Services continues refining billing codes for 308 nm psoriasis and vitiligo protocols, reducing out-of-pocket burdens and accelerating clinic adoption cycles.
- EU Medical Device Regulation Harmonization:The MDR framework streamlines CE marking pathways across Germany, France, and Italy, enabling faster product standardization and cross-border equipment deployment within the European single market.
- Gas Laser Refurbishment Economics:Xenon-chloride chamber replacement cycles generate recurring revenue streams that sustain vendor margins and incentivize long-term customer retention through service bundling.
Market Restraints
- Capital Equipment Intensity:Initial acquisition costs for 308 nm systems strain independent dermatology practices, particularly in price-sensitive secondary cities across India and Brazil.
- Gas Supply Concentration:Specialized xenon and chlorine gas purification capabilities concentrate among a limited supplier base in Germany and Japan, creating input vulnerability.
- Technical Limitation in Deep Tissue:Monochromatic 308 nm delivery achieves limited penetration depth, restricting efficacy in thick-plaque psoriasis presentations compared to systemic biologic alternatives.
Strategic Opportunities
- Underpenetrated Indian Metros:Tier-2 and Tier-3 cities in Maharashtra and Karnataka present white space for 308 nm system deployment as domestic medical tourism infrastructure expands.
- Software-Defined Fluence Convergence:Integration of real-time dosimetry algorithms with cloud-based treatment protocols enables remote calibration and predictive maintenance revenue models.
- Japan's Aging Demographics:METI-supported regional healthcare decentralization policies channel capital toward outpatient dermatology centers in prefectures outside Tokyo and Osaka.
Industry Challenges
- Laser Physicist Talent Scarcity:Xenon-chloride chamber engineering expertise concentrates among retiring specialists in Germany and the United States, constraining OEM technical support scaling.
- MDR Technical Documentation Burden:Clinical evidence requirements for CE marking under the EU Medical Device Regulation extend certification timelines and inflate regulatory affairs staffing costs.
- Legacy System Integration Friction:Electronic health record connectivity protocols vary across Epic, Cerner, and country-specific hospital information systems, complicating seamless workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatology Excimer Laser Market |
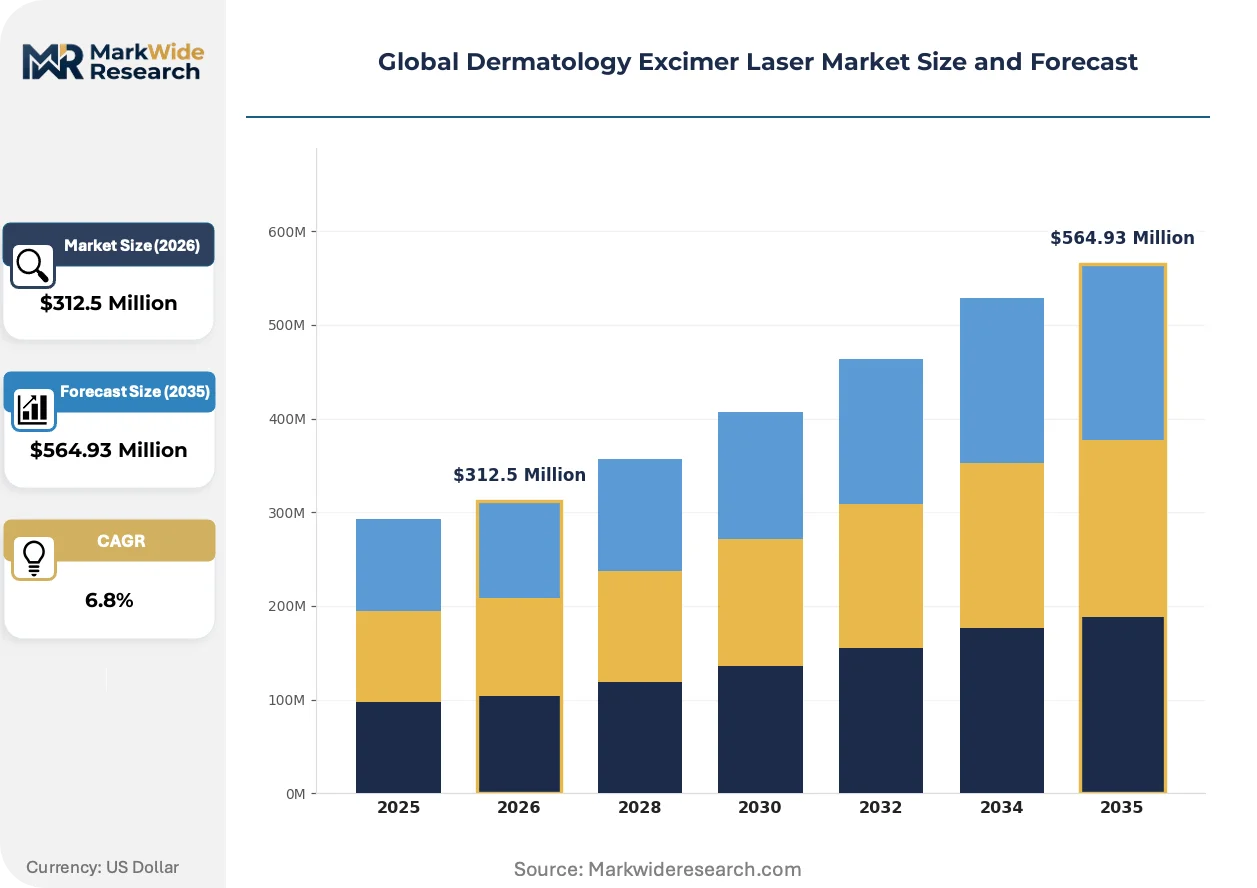
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 308 nm Excimer Laser, 308 nm Excimer Light Source, Pulsed Excimer Laser, UVB Excimer Laser, Others Application: Psoriasis, Vitiligo, Atopic Dermatitis, Alopecia Areata, Leukoderma End User: Dermatology Clinics, Ambulatory Surgical Centers, Research Institutes, Specialty Hospitals, Private Clinics Technology: Solid State Laser, Gas Laser, Diode Laser, Fiber Laser, Semiconductor Laser |
| Companies Covered | Ra Medical Systems, Strata Skin Sciences, Alma Lasers, Shenzhen GSD Tech Co., Ltd., The Daavlin Company, Lumenis, Fotona, DEKA Research & Development Corp., Beijing Sincoheren S&T Development Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatology Excimer Laser Market Shifts & Advancements
Real-time dosimetry systems and cloud-connected calibration protocols are compressing the traditional service model, shifting vendor economics from episodic maintenance toward continuous remote monitoring architectures.
Portable 308 nm LED-based alternatives are rewriting competitive boundaries in the vitiligo treatment segment. Academic medical centers in South Korea and university hospitals in the Netherlands are piloting handheld devices for home-based narrowband UVB delivery. This technology is compressing the addressable market for conventional excimer systems in mild-to-moderate cases while expanding total treatable patient populations.
REACH and F-Gas Regulation amendments in the European Union are tightening xenon and halogen gas handling requirements for medical device manufacturers. Industrial consequence includes mandatory supplier audit trails and extended substance safety documentation. German and French OEMs are responding by vertically integrating gas purification capabilities and lobbying for medical-use exemptions within the regulatory framework.
Subscription-based equipment access models are displacing outright purchase arrangements in North American dermatology groups. Private equity-backed clinic rollups in Texas and Florida negotiate fleet-wide service agreements that bundle hardware, preventive maintenance, and software updates into per-procedure fees. This restructuring concentrates buying power among fewer procurement decision-makers and extends vendor sales cycles.
Global Dermatology Excimer Laser Market Segmentation
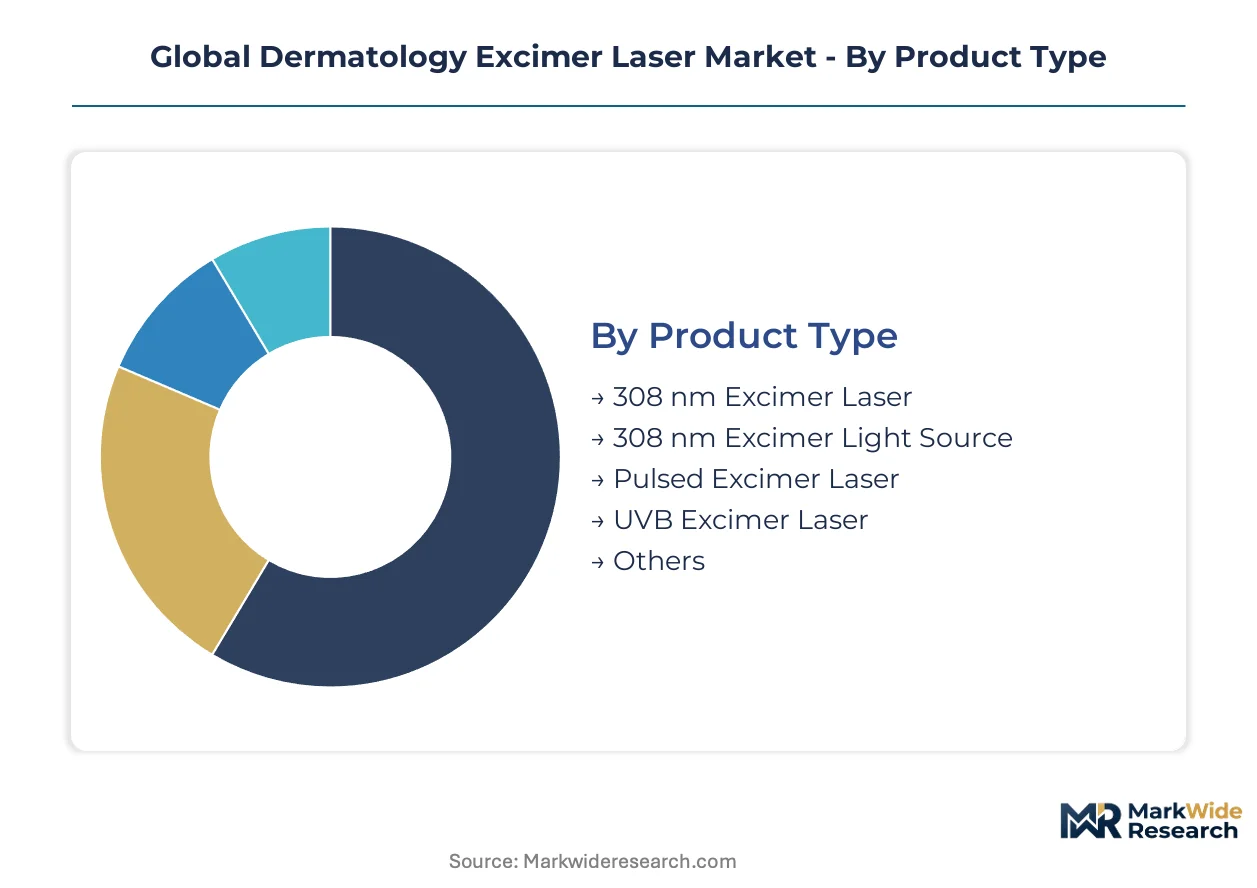
Segmentation in the dermatology excimer laser market reveals how regulatory pathways, clinical protocols, and facility economics fragment procurement decisions across equipment categories. Understanding these divides helps vendors align certification investments with addressable revenue pools.
Product Type:
FDA 510(k) clearance timelines vary substantially across product categories, with gas-based systems requiring additional EPA environmental compliance documentation that solid-state alternatives bypass entirely.
- 308 nm Excimer Laser:Gas discharge architecture generating coherent ultraviolet B radiation through xenon-chloride medium. Dermatology clinics in Germany and France concentrate procurement under MDR harmonized standards, driven by established reimbursement codes for psoriasis protocols.
- UVB Excimer Laser:Narrowband delivery configuration optimized for vitiligo repigmentation with enhanced melanocyte stimulation. Academic medical centers in South Korea and the Netherlands are piloting home-based alternatives, compressing addressable volumes for conventional cabinet systems.
- 308 nm Excimer Light Source:Non-laser LED-based emission mimicking therapeutic wavelength without coherent properties.
- Pulsed Excimer Laser:Q-switched delivery enabling controlled thermal relaxation for sensitive skin presentations.
- Others:Hybrid configurations and experimental wavelength variants in early clinical validation.
308 nm Excimer Laser sits at the top of the volume ranking, with UVB Excimer Laser climbing the fastest.
Application:
Reimbursement density determines segment attractiveness, with Medicare coverage expansion in the United States creating divergent economics across indication categories.
- Psoriasis:Chronic plaque indication commanding the largest installed base of 308 nm systems. United States dermatology groups prioritize these units given mature CPT coding and predictable per-procedure revenue streams.
- Vitiligo:Depigmentation disorder with expanding treatment protocols. Indian metros and Brazil's secondary cities are driving demand as medical tourism infrastructure broadens access to narrowband UVB therapies.
- Atopic Dermatitis:Eczema variant requiring modified fluence parameters for inflammatory control.
- Alopecia Areata:Autoimmune hair loss indication with emerging off-label utilization.
- Leukoderma:Post-inflammatory hypopigmentation presentations responding to localized phototherapy.
Psoriasis generates the highest procedure volumes, while vitiligo is gaining share fastest among newly adopting facilities.
End User:
Capital intensity thresholds and service contract sophistication separate institutional buyers from independent practice procurement patterns.
- Dermatology Clinics:Primary care setting for outpatient phototherapy. Private equity-backed rollups in Texas and Florida are consolidating fleet purchasing power through subscription-based equipment access models.
- Specialty Hospitals:Tertiary referral centers integrating excimer systems with multidisciplinary autoimmune protocols. Japan's METI-supported regional decentralization is channeling capital toward prefectural hospitals outside Tokyo and Osaka.
- Ambulatory Surgical Centers:Same-day procedure facilities with constrained capital budgets.
- Research Institutes:Academic centers validating novel wavelength applications and dosimetry algorithms.
- Private Clinics:Independent practices facing reimbursement timing pressures.
Dermatology Clinics dominate installed base, with Specialty Hospitals expanding most quickly under government decentralization policies.
Technology:
Supply chain concentration for specialized gas purification creates divergent margin profiles across laser architecture categories.
- Gas Laser:Xenon-chloride discharge technology sustaining vendor economics through recurring chamber refurbishment and gas replacement cycles. German and Japanese suppliers concentrate rare gas purification capabilities, creating input vulnerability for OEMs.
- Solid State Laser:Crystal-based emission eliminating consumable dependencies. Indian and Brazilian buyers favor these configurations where gas supply logistics strain maintenance reliability.
- Diode Laser:Semiconductor junction emission with compact form factor potential.
- Fiber Laser:Doped silica gain medium offering wavelength tunability.
- Semiconductor Laser:Integrated chip architecture for portable device integration.
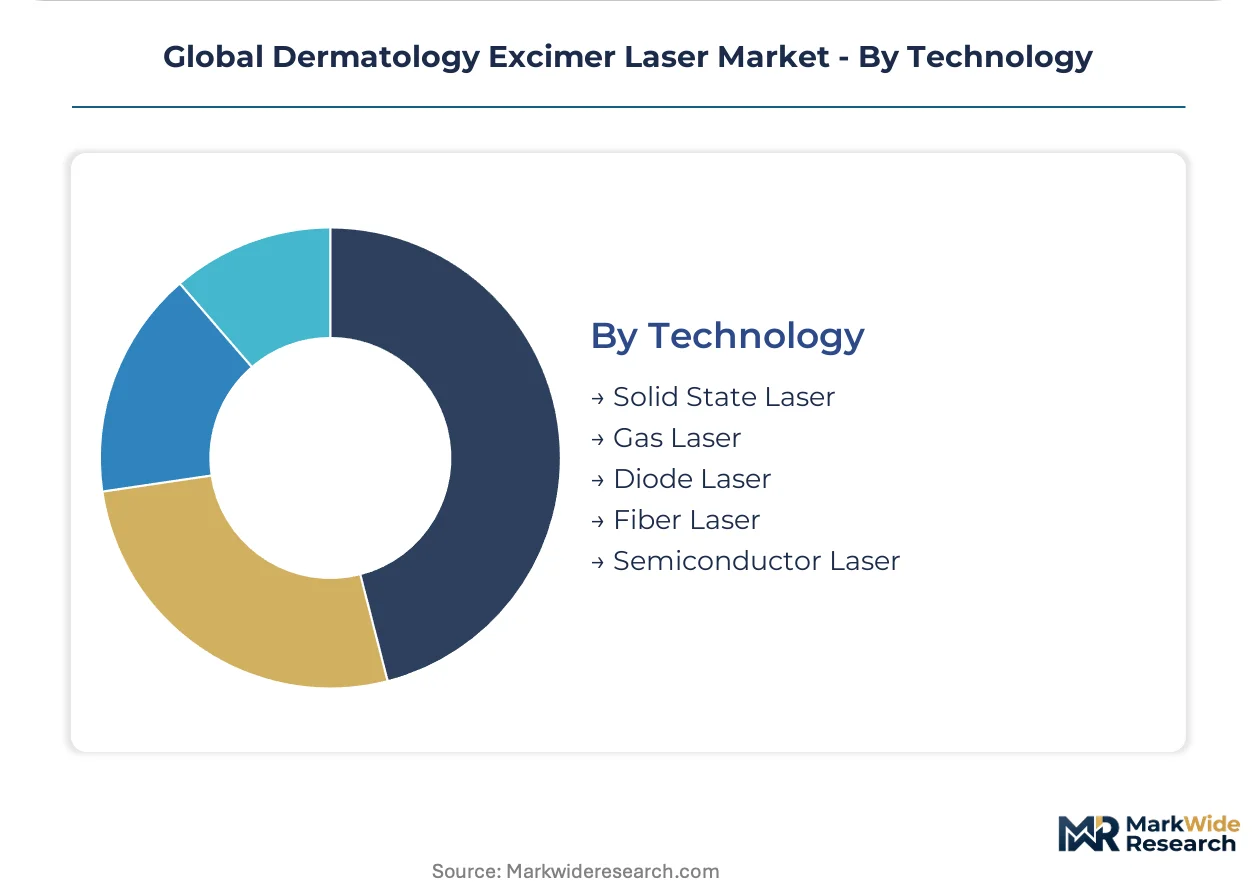
Gas Laser holds the largest revenue share, with Solid State Laser showing the steepest expansion trajectory as emerging markets prioritize supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States exhibit divergent procurement patterns for 308 nm systems, with German dermatology clinics accelerating adoption under harmonized EU Medical Device Regulation standards while United States buyers navigate evolving Medicare reimbursement coding.
United States
Private equity-backed dermatology rollups in Texas and Florida are consolidating fleet purchasing power through subscription-based equipment access models. The Centers for Medicare and Medicaid Services continues refining CPT billing codes for psoriasis and vitiligo protocols, reducing patient out-of-pocket burdens. Academic medical centers in Boston and Stanford anchor clinical validation networks for novel dosimetry algorithms.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia are expanding 308 nm system deployment under streamlined CE marking pathways. The EU Medical Device Regulation harmonization enables faster cross-border equipment standardization across the European single market. Xenon-chloride gas purification capabilities concentrate among specialized suppliers in Baden-Württemberg, creating regional supply chain advantages for domestic OEMs.
Japan
METI-supported regional healthcare decentralization policies channel capital toward outpatient dermatology centers in prefectures outside Tokyo and Osaka. The Pharmaceuticals and Medical Devices Agency maintains rigorous technical documentation requirements for laser therapeutic devices. University hospitals in Nagoya and Fukuoka are piloting home-based narrowband UVB delivery protocols for vitiligo repigmentation.
India
Tier-2 and Tier-3 cities in Maharashtra and Karnataka present white space for 308 nm system deployment as domestic medical tourism infrastructure expands. The Central Drugs Standard Control Organization governs medical device import licensing and local manufacturing standards. Specialty hospitals in Mumbai and Bangalore are integrating excimer systems with multidisciplinary autoimmune protocols for psoriasis management.
South Korea
Academic medical centers in Seoul are piloting handheld 308 nm LED-based alternatives for home-based narrowband UVB delivery. The Ministry of Food and Drug Safety oversees laser medical device registration with emphasis on clinical evidence requirements. Research institutes in Daegu-Gyeongbuk are validating novel wavelength applications and real-time dosimetry systems for sensitive skin presentations.
Global Dermatology Excimer Laser Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with gas laser refurbishment economics sustaining vendor margins in mature markets while solid-state alternatives gain traction in supply-constrained regions. The vendor base clusters around three strategic archetypes: integrated phototherapy platform builders, regional service bundlers, and component-focused gas chamber specialists. Dominant competitive moves include preventive maintenance contract bundling and software-defined fluence calibration integration.
Within the integrated platform tier, Lumenis and Alma Lasers exemplify archetypes leveraging installed base lock-in through multi-year service agreements and region-specific training certifications. Shenzhen GSD Tech Co., Ltd. represents Chinese manufacturing scale in solid-state configurations. These three occupy positions spanning premium academic medical center supply and emerging market accessibility, with each anchoring distinct geographic and technology positioning strategies.
| Leading Market Players |
|---|
| Ra Medical Systems |
| Strata Skin Sciences |
| Alma Lasers |
| Shenzhen GSD Tech Co., Ltd. |
| The Daavlin Company |
| Lumenis |
| Fotona |
| DEKA Research & Development Corp. |
| Beijing Sincoheren S&T Development Co., Ltd. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up dermatology groups in Texas and Florida are consolidating fleet purchasing power through subscription-based equipment access models, compressing vendor margins while extending payment timelines across multi-year service agreements.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for solid-state 308 nm alternatives, forcing traditional gas-laser vendors to bundle preventive maintenance and software updates into per-procedure fees. Three-tier pricing structure across premium academic medical centers, standard dermatology clinics, and economy-tier ambulatory surgical centers reflects certification grade and after-sales service intensity. Cost compression in the economy tier is intensifying because LED-based handheld alternatives are expanding treatable patient populations at lower capital intensity. Independent practices in Indian Tier-2 cities exhibit highest price sensitivity; academic medical centers in Germany and the United States show lowest sensitivity due to established reimbursement pathways.
Supply Chain Analysis
Single-source vulnerability sits with specialized xenon-chloride gas purification capabilities concentrated in Germany and Japan, constraining OEM technical support scaling as retiring laser physicist expertise concentrates among aging specialists. Manufacturing draws from German precision engineering clusters for gas discharge chambers, Japanese rare gas processing facilities, and Chinese solid-state component assembly lines. Tariff exposure runs through REACH and F-Gas Regulation amendments tightening halogen gas handling requirements for medical device manufacturers. Distribution runs through direct OEM sales teams for premium academic accounts and regional distributors serving price-sensitive emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software-defined fluence calibration convergence, shifting vendor economics from episodic hardware sales toward continuous remote monitoring revenue streams.
For Market Incumbents: Extend service contract bundling to lock in multi-year preventive maintenance agreements before portable LED alternatives capture mild-to-moderate vitiligo cases. Deepen backward integration into xenon-chloride gas purification capabilities to offset supply concentration risk from German and Japanese suppliers. Fortify region-specific training certifications that bind clinicians to technical support ecosystems, raising switching costs against emerging solid-state competitors from China and South Korea. For New Entrants and Emerging Players: The price-point gap between premium gas-laser systems and economy-tier LED alternatives creates entry space for mid-range solid-state configurations with simplified maintenance profiles. Target Tier-2 and Tier-3 cities in Maharashtra and Karnataka where domestic medical tourism infrastructure is expanding but gas supply logistics strain reliability. Pursue hospital system partnerships in Japan's prefectural centers outside Tokyo and Osaka where METI-supported regional healthcare decentralization is channeling capital toward outpatient dermatology. For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused gas chamber specialists facing expertise scarcity as retiring laser physicist talent concentrates in Germany and the United States. Long-term viability hinges on successful transition from hardware-dependent revenue to recurring service and software streams. Watch FDA 510(k) clearance timelines for handheld LED alternatives as the inflection indicator signaling accelerated compression of conventional excimer system addressable markets.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Fluence Integration | Enables remote calibration and predictive maintenance revenue models for Lumenis and Alma Lasers. |
| CE Marking Pathway Acceleration | EU MDR harmonization streamlines cross-border deployment for German and French OEMs. |
| Hospital System Partnership | Private equity-backed rollups in Texas and Florida consolidate fleet purchasing power through subscription models. |
| Backward Integration into Gas Purification | German OEMs respond to REACH amendments by capturing xenon-chloride supply chain control. |
| Reimbursement Strategy Development | Medicare coding refinement by CMS directly gates clinic procurement cycles and equipment replacement timelines. |
Research Methodology
Multiple input streams — primary interviews with dermatology equipment procurement managers, biomedical engineers at academic medical centers, and GPO contracts specialists; secondary validation against FDA 510(k) filings, EMA MDR technical documentation, and CMS Medicare reimbursement databases; plus customs and trade data for xenon-chloride gas flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, end user, technology, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from procedural volume modeling and per-procedure revenue assumptions, with specific inputs including Medicare coding expansion trajectories and METI regional healthcare decentralization capital allocation patterns.
The model assumes a particular technology adoption path; alternative pathways for handheld LED-based narrowband UVB delivery would alter the outlook if home-based protocols achieve clinical equivalence with cabinet systems. Forecasts reflect assumptions about reimbursement pathway maturation and gas supply logistics stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Scar Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Skin Cancer Market
Dermatology
Australia Skin Laser Market
Dermatology
Scar Treatment Oils Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Japan Scar Treatment Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Microdermabrasion Market
Dermatology
Keloid Treatment Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Radiation Dermatitis Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Dermal Facial Fillers Market