
 US Non-Invasive Prenatal Testing (NIPT) Market | 2026-2036
US Non-Invasive Prenatal Testing (NIPT) Market Size, Share, and Industry Trends Forecast 2026-2036
US Non-Invasive Prenatal Testing (NIPT) Market Insights
Recurring bioinformatics subscriptions is pivoting how NIPT vendors monetize sequencing platforms, shifting revenue from one-time consumables toward continuous data interpretation. Illumina, Inc. leverages its installed base of sequencers to anchor long-term service contracts. Natera, Inc. differentiates through proprietary algorithms that extend clinical utility beyond aneuploidy screening. Laboratory Corporation of America Holdings controls broad geographic access through its national laboratory network.
Non-invasive prenatal testing analyzes cell-free fetal DNA circulating in maternal blood, typically requiring minimum 4% fetal fraction for reliable results, to detect chromosomal abnormalities without amniocentesis risk. The technology serves obstetric decision-making by enabling early, safe screening for conditions like trisomy 21. Next-generation sequencing dominates test volumes due to superior sensitivity for chromosomal aneuploidy detection. Polymerase chain reaction retains cost advantages in resource-constrained settings and specific single-gene disorder applications. Diagnostic laboratories capture the largest end-user revenue pool, though obstetrics clinics represent the fastest-growing site-of-care shift.
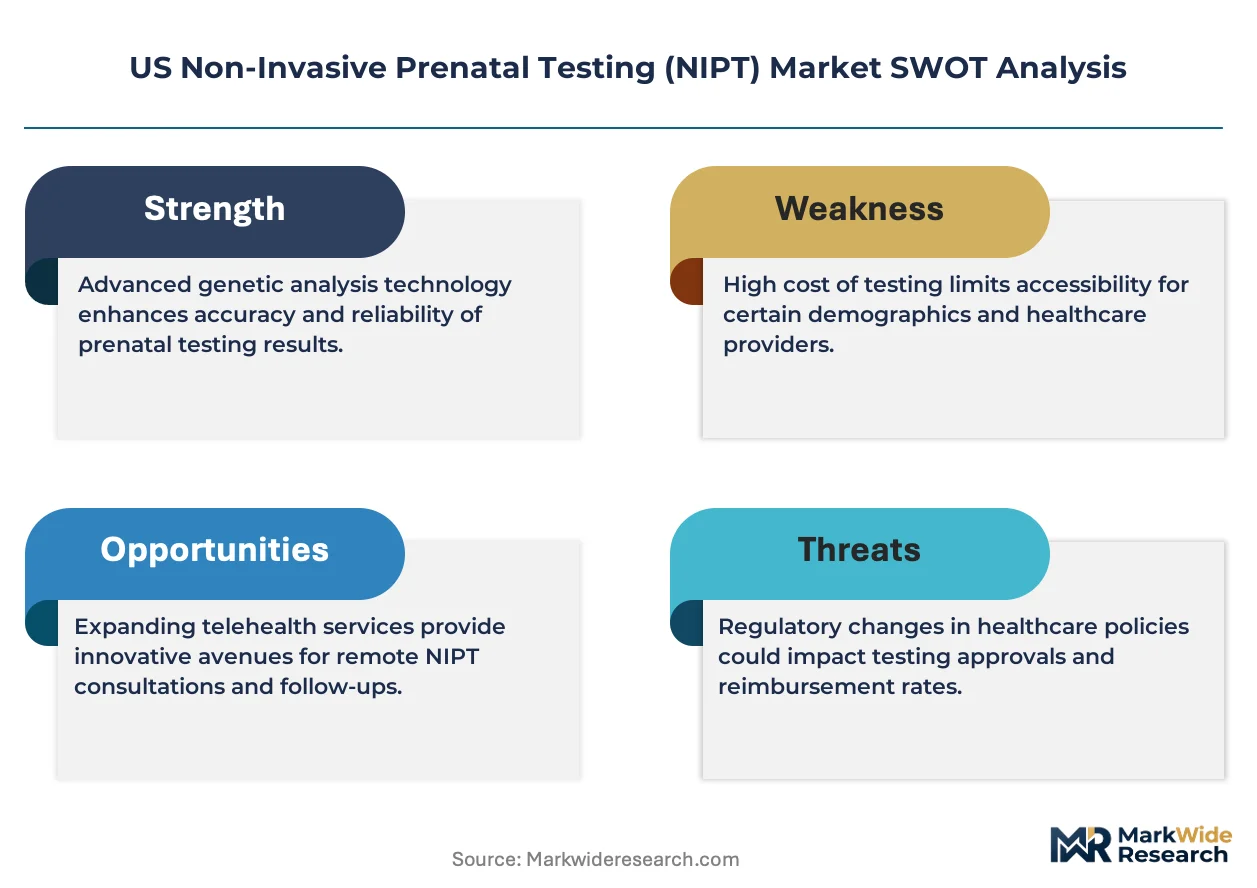
FDA oversight of laboratory-developed tests, alongside CLIA certification requirements and state-level genetic counselor licensing, determines market access and reimbursement pathways for NIPT providers. The Centers for Medicare & Medicaid Services' coverage decisions directly shape patient out-of-pocket exposure and test utilization rates. Stakeholders must monitor evolving FDA guidance on analytical validation standards and state-level scope-of-practice rules for genetic counseling.
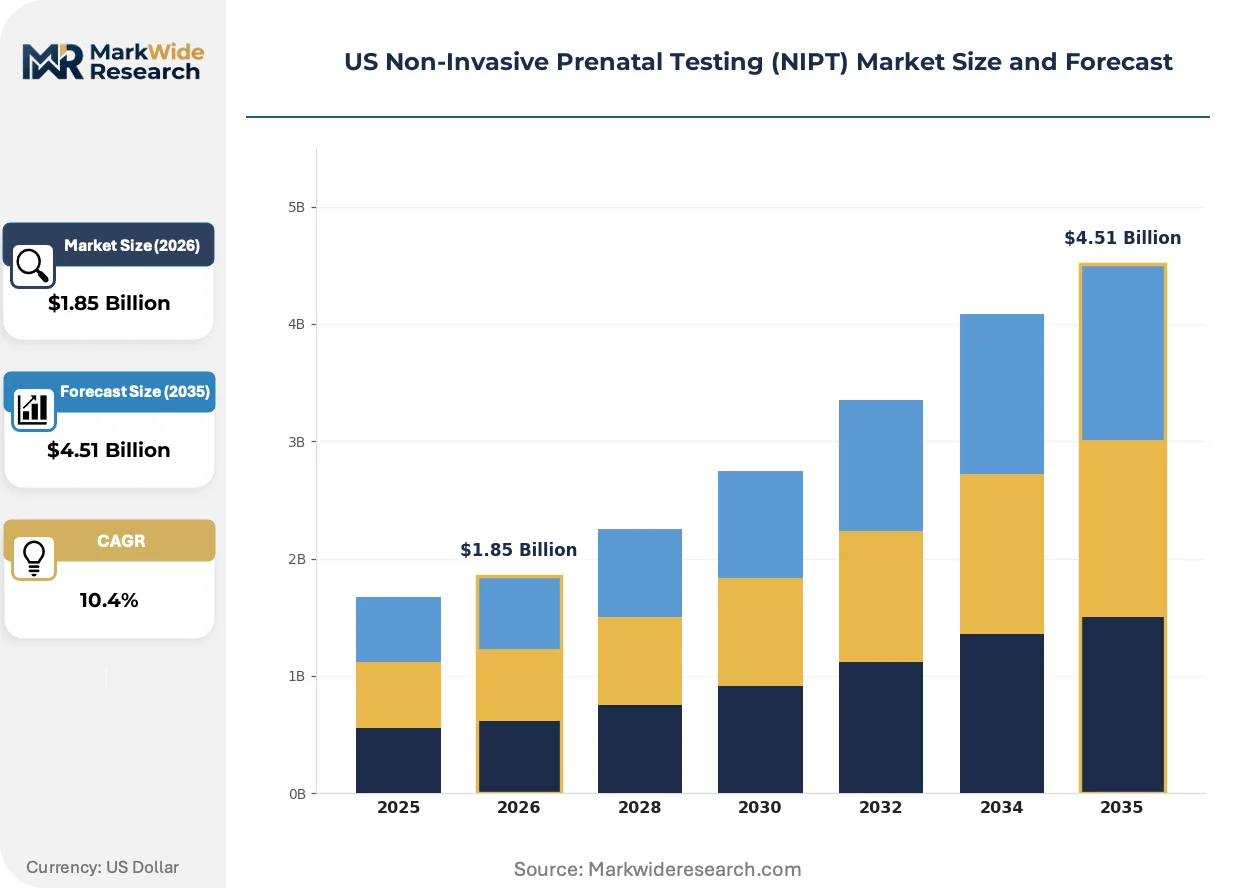
Market Dynamics
The US NIPT market is restructuring around bioinformatics platform economics, where sequencing hardware commoditizes while proprietary algorithms and recurring data subscriptions capture margin. This shift concentrates value capture among vendors with installed base scale and interpretive software lock-in.
Growth Catalysts
- CLIA Laboratory Certification:Federal quality standards for high-complexity testing validate analytical performance, enabling commercial laboratories to bill Medicare and private payers for cell-free DNA screening services.
- Obstetrics Clinic Site-of-Care Migration:Outpatient women's health practices are integrating phlebotomy and pre-test counseling into routine prenatal workflows, compressing referral friction and accelerating test ordering.
- Next-Generation Sequencing Cost Curves:Per-run reagent economics for chromosomal aneuploidy detection have fallen below polymerase chain reaction alternatives for multi-plexed panels, tilting platform procurement decisions.
Market Restraints
- Fetal Fraction Variability:Technical failure rates in early gestational windows due to insufficient circulating fetal DNA impose redraw costs and delay diagnostic clarity for high-risk pregnancies.
- FDA Laboratory-Developed Test Oversight Uncertainty:Evolving enforcement discretion for premarket review creates compliance timeline risk and capital allocation hesitation among test developers.
- Genetic Counselor Supply Constraints:State-level licensure requirements and limited training program throughput restrict pre-test informed consent capacity, capping clinic throughput in high-volume markets.
Strategic Opportunities
- Expanded Aneuploidy and Microdeletion Panels:Clinical validation of sub-chromosomal copy number variant detection opens reimbursement pathways beyond common trisomies into rare disease screening categories.
- Texas and Florida Obstetrics Networks:Underpenetrated metropolitan markets with high birth rates and independent physician practice structures offer first-mover platform installation advantages.
- State Medicaid NIPT Coverage Expansion:Beneficiary advocacy and cost-effectiveness data are pressuring program administrators to extend cell-free DNA screening to average-risk pregnancies in select jurisdictions.
Industry Challenges
- Bioinformatics Talent Acquisition:Competition for computational biologists with clinical variant interpretation expertise exceeds supply in Boston and San Francisco genomic clusters, inflating compensation and extending hiring cycles.
- Payer Prior Authorization Complexity:Multi-step documentation requirements for high-risk indication verification create administrative burden and delay revenue recognition for diagnostic laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Non-Invasive Prenatal Testing (NIPT) Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Chromosomal Aneuploidy, Single-Gene Disorders, Sex Chromosome Abnormalities, Microdeletion Syndromes Technology: Next-Generation Sequencing, Polymerase Chain Reaction, Array Comparative Genomic Hybridization, Digital PCR End User: Diagnostic Laboratories, Genetic Counseling Centers, Obstetrics Clinics, Research Institutions Sample Collection Method: Plasma-Based, Serum-Based, Whole Blood, Amniotic Fluid |
| Companies Covered | Illumina, Inc., Natera, Inc., Laboratory Corporation of America Holdings, F. Hoffmann-La Roche Ltd, Quest Diagnostics Incorporated, Revvity Inc., Myriad Genetics, Inc., Eurofins Scientific, BioReference Health, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Non-Invasive Prenatal Testing (NIPT) Market Trends and Innovations
Automation of wet-lab processing and algorithmic variant calling is compressing turnaround times while expanding test menu complexity. These developments are redefining operational benchmarks and competitive differentiation vectors across the US prenatal screening landscape.
Robotic liquid handling systems integrated with next-generation sequencing workflows are automating cell-free DNA extraction and library preparation steps. High-volume reference laboratories in California and Texas are deploying these platforms to achieve 24-hour sample-to-result intervals for routine aneuploidy screening. This automation is compressing labor cost structures while enabling overnight batch processing that supports next-day obstetrician consultation scheduling.
FDA draft guidance on analytical validation for non-invasive prenatal screening tests is tightening evidentiary standards for sensitivity and specificity claims. Commercial laboratories must now conduct larger prospective studies to support expanded indications, extending development timelines and raising clinical trial expenditure. The draft policy most acutely affects developers pursuing microdeletion syndrome panels, where lower prevalence conditions demand larger denominator populations for statistically powered validation.
Direct-to-consumer prenatal genetic information channels are fragmenting traditional obstetrician-mediated test ordering pathways. Expectant parents in metropolitan markets are initiating screening conversations through telehealth platforms and employer-sponsored benefits programs, bypassing conventional referral networks. This behavioral shift concentrates most visibly in technology sector employee populations with concierge health benefits, where same-day phlebotomy and digital result delivery are becoming baseline expectations.
US Non-Invasive Prenatal Testing (NIPT) Market Segmentation
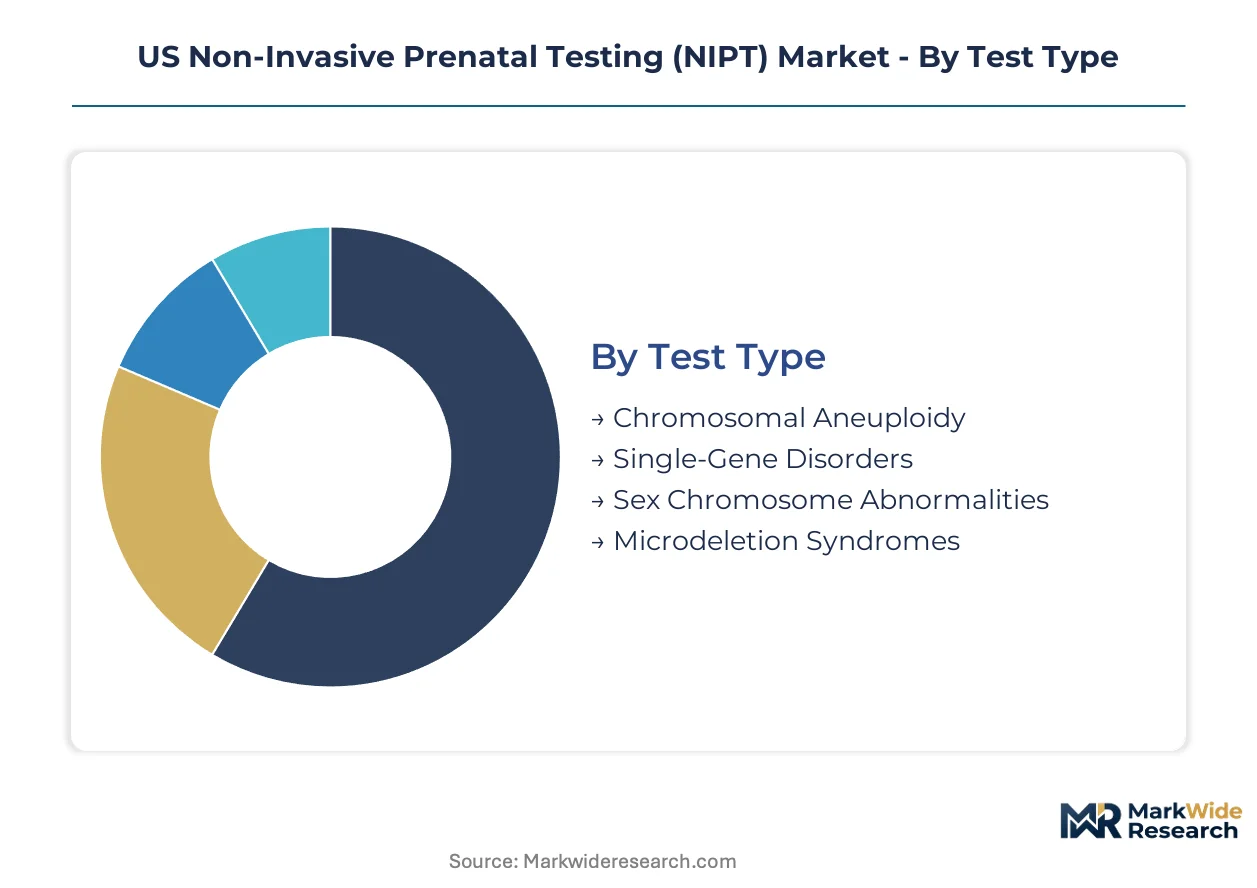
Test type, technology platform, and site-of-care configuration determine reimbursement pathways and margin structures across the US NIPT landscape. Vendors align R&D investment and commercial resources against segments where analytical validation requirements and clinical utility evidence intersect with payer coverage expansion.
Test Type:
Clinical indication breadth and prevalence rates shape test development priorities and regulatory submission strategies for NIPT developers.
- Chromosomal Aneuploidy:Screening for trisomies 21, 18, and 13 dominates commercial volumes through established sensitivity benchmarks exceeding 99% detection rates. California and Massachusetts academic medical centers drive utilization through integrated prenatal care pathways and genetic counselor staffing density.
- Single-Gene Disorders:Targeted analysis of Mendelian conditions such as cystic fibrosis and sickle cell disease requires higher fetal fraction thresholds and customized probe design. Demand concentrates in high-risk populations with known carrier status, particularly in metropolitan areas with diverse ethnic demographics.
- Sex Chromosome Abnormalities:Detection of Turner syndrome, Klinefelter syndrome, and related conditions addresses parental anxiety and pregnancy management decisions. Clinical uptake remains moderated by variable phenotypic expressivity and counseling complexity.
- Microdeletion Syndromes:Sub-chromosomal copy number variant detection for 22q11.2 deletion and related rare conditions demands larger validation cohorts under evolving FDA guidance. Reimbursement pathways remain fragmented across commercial payers.
Chromosomal aneuploidy leads on scale; microdeletion syndromes lead on momentum.
Technology:
Platform selection dictates capital intensity, reagent economics, and bioinformatics differentiation for laboratory service providers.
- Next-Generation Sequencing:Massively parallel sequencing of cell-free DNA fragments enables multiplexed aneuploidy detection with superior sensitivity. Per-run cost curves have fallen below competing platforms for high-volume operations in Texas and California reference laboratories.
- Polymerase Chain Reaction:Targeted amplification of specific loci retains cost advantages for single-gene disorder screening and resource-constrained settings. PCR workflows persist in smaller obstetrics practices without sequencer infrastructure.
- Array Comparative Genomic Hybridization:Microarray-based copy number profiling offers intermediate resolution for microdeletion detection without sequencing depth requirements. Deployment concentrates in cytogenetics laboratories with existing array infrastructure.
- Digital PCR:Absolute quantification of fetal DNA fractions through droplet partitioning enables precise aneuploidy calling with reduced sequencing overhead. Emerging adoption targets laboratories seeking rapid turnaround without full NGS workflow investment.
Next-generation sequencing commands installed base dominance; digital PCR is climbing the fastest as a point-of-care alternative.
End User:
Site-of-care economics and regulatory certification requirements fragment market access strategies across provider types.
- Diagnostic Laboratories:High-complexity CLIA-certified facilities capture the largest revenue pool through centralized processing scale and national payer contracts. Laboratory Corporation of America Holdings and Quest Diagnostics maintain geographic density advantages.
- Obstetrics Clinics:Outpatient women's health practices represent the steepest expansion trajectory through integrated phlebotomy and same-day counseling workflows. Independent physician groups in Florida and Texas metropolitan markets drive platform installation demand.
- Genetic Counseling Centers:Specialized pre-test informed consent and result interpretation services address supply constraints in high-volume markets. State-level licensure requirements in California and Massachusetts restrict capacity expansion.
- Research Institutions:Academic medical centers in genomic medicine clusters advance clinical validation studies and expanded indication development. NIH-funded prospective cohorts support FDA submission evidentiary standards.
Diagnostic laboratories lead on scale; obstetrics clinics lead on momentum.
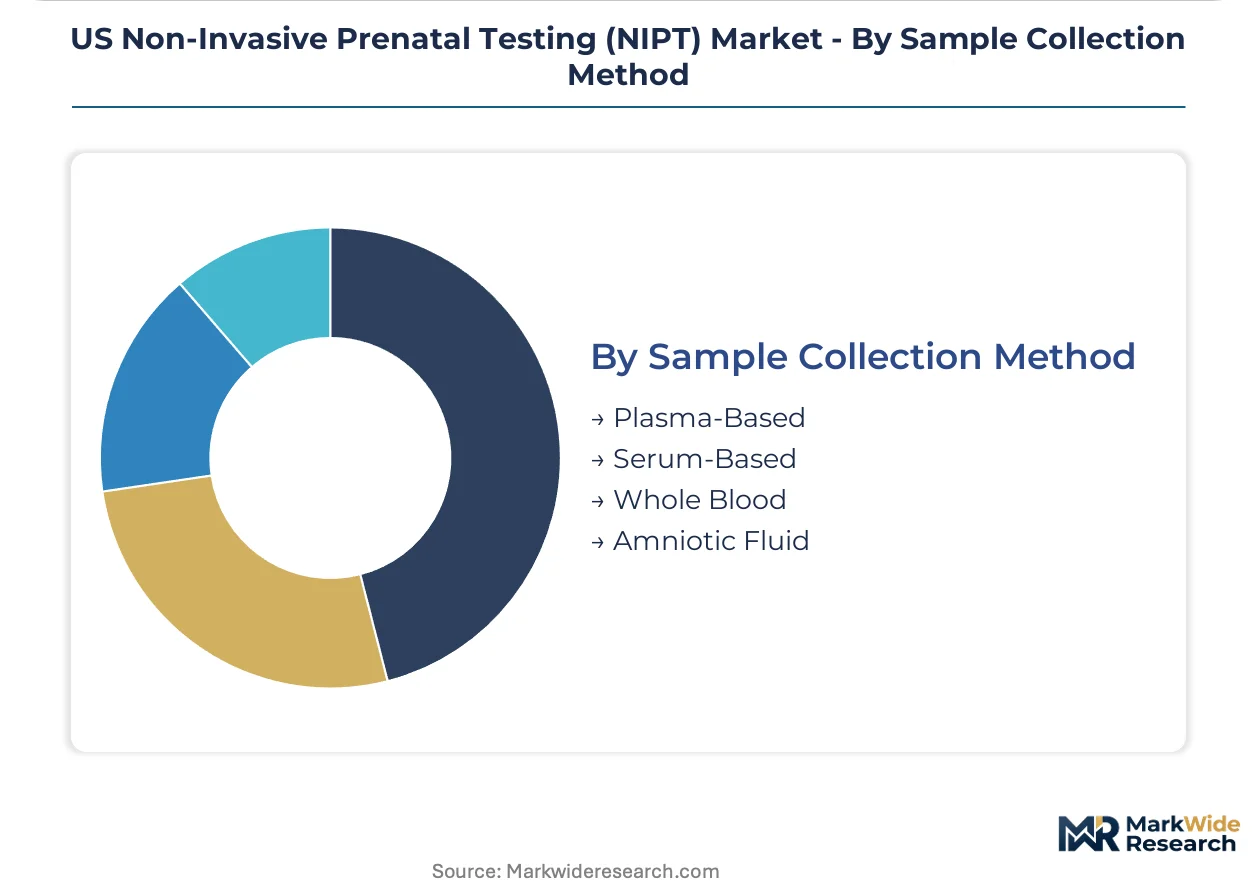
Sample Collection Method:
Specimen stability and processing logistics determine collection network design and patient convenience benchmarks.
- Plasma-Based:Cell-free DNA extraction from maternal plasma following centrifugation represents the standard-of-care workflow with established stability protocols. California and Massachusetts laboratories process the highest plasma specimen volumes.
- Serum-Based:Alternative centrifugation protocols yield comparable fetal fraction recovery with modified handling requirements. Limited deployment targets specific laboratory information system integrations.
- Whole Blood:Unprocessed specimen collection enables decentralized phlebotomy with laboratory-side processing, supporting obstetrics clinic site-of-care migration. Transport logistics concentrate in Texas and Florida independent practice networks.
- Amniotic Fluid:Invasive specimen type for confirmatory diagnostic testing following positive NIPT screening, not primary screening. Volume correlates with NIPT positive predictive value and referral patterns to maternal-fetal medicine specialists.
Plasma-based collection leads on scale; whole blood leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Massachusetts dominate US NIPT test volumes through genomic medicine clusters, while Texas and Florida emerge as high-growth frontiers where independent obstetrics networks drive platform installation demand.
California
Academic medical centers in San Francisco and Los Angeles anchor the nation's highest NIPT processing volumes through integrated prenatal care pathways. FDA oversight of laboratory-developed tests shapes compliance timelines for Bay Area reference laboratories expanding microdeletion panels. The state's genetic counselor licensure requirements concentrate expertise in metropolitan clusters, capping rural clinic throughput.
Massachusetts
Greater Boston's research institutions advance clinical validation studies for expanded aneuploidy indications through NIH-funded prospective cohorts. The state's high genetic counselor density supports pre-test informed consent capacity that exceeds national averages. Cambridge-area laboratories leverage proximity to sequencing technology developers to compress algorithmic validation cycles.
Texas
Independent obstetrics networks in Houston and Dallas metropolitan markets drive demand for decentralized phlebotomy and rapid turnaround workflows. CLIA laboratory certification requirements enable high-complexity testing facilities in San Antonio to bill Medicare for cell-free DNA screening services. The state's high birth rates and underpenetrated physician practice structures attract first-mover platform installations.
Florida
Miami and Tampa obstetrics clinics integrate same-day counseling into routine prenatal workflows, compressing referral friction for average-risk pregnancy screening. State Medicaid program administrators face beneficiary advocacy pressure to extend NIPT coverage beyond high-risk indications. The Gulf Coast's independent physician practice concentration supports site-of-care migration away from centralized laboratory networks.
New York
Manhattan academic medical centers coordinate multi-site clinical trials for FDA submission evidentiary standards on expanded test menus. The state's scope-of-practice regulations for genetic counseling create bottlenecks in pre-test consent capacity upstate. Buffalo and Rochester laboratories compete for regional specimen volumes through contracted payer relationships with commercial insurers.
US Non-Invasive Prenatal Testing (NIPT) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with sequencing platform vendors capturing recurring bioinformatics revenue while diagnostic laboratories monetize geographic access. The market structures around three tiers: integrated technology developers with installed base scale, national reference laboratories with payer network density, and regional specialists with obstetrics clinic relationships. Consolidation pressure concentrates among mid-scale laboratories seeking CLIA certification expansion. Competitive moves center on algorithmic differentiation for expanded panels and automation deployment for turnaround compression.
Within the technology developer tier, Illumina, Inc. and Natera, Inc. exemplify contrasting platform economics. Illumina anchors recurring service contracts through sequencer installed base dominance. Natera occupies a position defined by proprietary algorithmic differentiation extending beyond standard aneuploidy screening. Laboratory Corporation of America Holdings represents the national reference laboratory archetype, leveraging geographic density for payer contract breadth.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Natera, Inc. |
| Laboratory Corporation of America Holdings |
| F. Hoffmann-La Roche Ltd |
| Quest Diagnostics Incorporated |
| Revvity Inc. |
| Myriad Genetics, Inc. |
| Eurofins Scientific |
| BioReference Health, LLC |
| Others |
Pricing and Supply Chain Analysis
Algorithmic tier divergence between proprietary bioinformatics platforms and commoditized sequencing consumables manifests in contrasting margin structures and procurement strategies across the US NIPT landscape. Premium pricing attaches to interpretive software subscriptions anchored in CLIA-certified laboratory networks, while reagent costs compress through vendor consolidation and volume commitments.
Pricing Analysis
Capacity additions in Texas and Florida reference laboratories are reshaping price floors for routine aneuploidy screening, intensifying competition for obstetrics clinic contracts. Three-tier pricing structure across premium, standard, and economy levels segments by test complexity and turnaround guarantee, with microdeletion panels commanding premiums over basic trisomy screens. Cost compression in polymerase chain reaction alternatives is accelerating due to next-generation sequencing cost curves falling below legacy platforms. Obstetrics clinics in independent practice networks exhibit highest price sensitivity, while academic medical centers prioritize analytical sensitivity over per-test economics.
Supply Chain Analysis
Direct-to-laboratory channels handle high-volume reagent demand from California and Massachusetts reference facilities, while distributor-mediated fulfillment serves fragmented obstetrics clinic networks in emerging markets. Sequencing instrument manufacturing concentrates in the United States and China, with reagent production anchored in Singapore and Ireland pharmaceutical zones. Cell-free DNA extraction kits and library preparation chemistries draw from specialized biochemical suppliers in Germany and Switzerland. Single-source vulnerability around sequencing flowcell production creates procurement risk for laboratories without multi-platform redundancy. Distribution runs through national laboratory networks and regional specialty distributors to end-user sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US NIPT market functions as a regulatory compounder where FDA draft guidance on analytical validation standards is accelerating clinical trial investment and consolidation timelines among test developers.
For Market Incumbents: Deploy algorithmic differentiation as the primary defensive lever against emerging digital PCR point-of-care challengers. Deepen CLIA laboratory certification density in Texas and Florida through acquisition of independent obstetrics network processing contracts. Consolidate mid-scale regional laboratories facing bioinformatics talent acquisition constraints in Boston and San Francisco genomic clusters. Prioritize automation deployment to compress turnaround times below 24-hour benchmarks for routine screening volumes. For New Entrants and Emerging Players: Begin with Medicaid coverage expansion advocacy in Florida and Texas as the most penetrable reimbursement pathway for average-risk pregnancy screening. Target independent obstetrics practice networks in underpenetrated metropolitan markets lacking integrated phlebotomy infrastructure. Pursue white-label bioinformatics partnerships with established sequencing platform vendors to bypass capital-intensive instrument development. Emphasize same-day result delivery capabilities to differentiate against centralized laboratory incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated test developers possessing proprietary variant interpretation algorithms and installed base scale. Long-term viability over the projection horizon hinges on FDA submission progress for expanded microdeletion panels and state-level genetic counselor licensure relaxation. Acquisition target archetype: mid-scale CLIA-certified laboratories in high-birth-rate geographies with contracted payer relationships. Monitor CMS coverage determination timelines for average-risk indications as the critical inflection signal for volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Analytical Validation Submission | Prospective cohort studies for microdeletion panels establish evidentiary benchmarks under evolving guidance. |
| Obstetrics Clinic Network Partnership | Integrated phlebotomy and counseling workflows in Texas and Florida compress referral friction. |
| Bioinformatics Platform Integration | Proprietary algorithm lock-in extends clinical utility beyond standard aneuploidy screening categories. |
| State Medicaid Coverage Expansion | Beneficiary advocacy in Florida pressures program administrators to extend cell-free DNA screening. |
| Automation Infrastructure Deployment | Robotic liquid handling systems in California laboratories achieve 24-hour sample-to-result intervals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory operations directors, genetic counseling program leads, payer policy managers, and obstetrics clinic administrators with secondary validation against FDA guidance documents, CMS coverage determinations, CLIA certification databases, and state genetic counselor licensure records. Bottom-up test volume modeling triangulated against top-down market size estimates derived from sequencing platform installed base data and reagent consumption patterns.
Segment-weighting approaches applied differential growth assumptions across test type, technology platform, and site-of-care configuration throughout the forecast period. Chromosomal aneuploidy, single-gene disorder, and microdeletion syndrome categories received distinct volume projections based on clinical validation status and reimbursement pathway maturity. Next-generation sequencing and polymerase chain reaction platforms were modeled separately for cost-curve trajectory and substitution dynamics. CAGRs derived from historical volume trends adjusted for regulatory milestone impacts and payer coverage expansion scenarios.
Several conditions sit outside the modeled scope, including potential FDA enforcement discretion changes for laboratory-developed tests, state-level scope-of-practice modifications for genetic counseling, and sequencing technology disruptions beyond next-generation and digital PCR platforms. Forecasts reflect base-case assumptions regarding CLIA certification stability and commercial payer prior authorization complexity. Periodic stress-testing of base assumptions is recommended against CMS national coverage determination timelines and state Medicaid program expansion decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market