
 Hemoglobin Analyzer Market | 2026-2036
Hemoglobin Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobin Analyzer Market Analysis
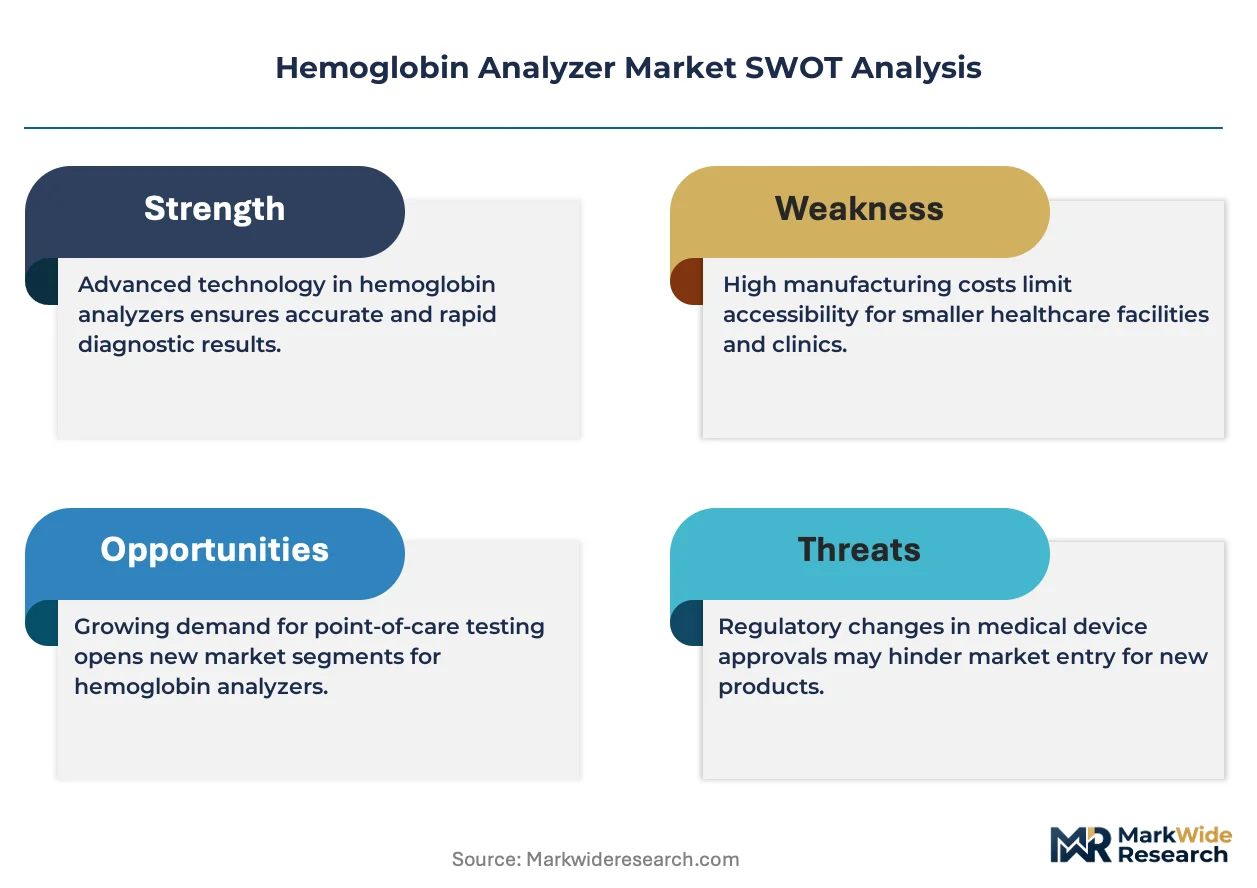
The gap between premium automated systems and commodity point-of-care devices is rebalancing as laboratories consolidate high-throughput testing while clinics decentralize screening. Danaher Corporation leverages its diagnostics platform breadth to anchor laboratory automation contracts. Sysmex Corporation dominates hematology analyzer supply chains through in-house production of precision optical components. Abbott Laboratories differentiates in point-of-care channels with handheld formats calibrated for capillary blood sources.
Hemoglobin analyzers are clinical instruments that quantify hemoglobin concentration in blood samples through photometric or electrochemical detection, typically reporting results in grams per deciliter with precision thresholds of ±0.2 g/dL for diagnostic-grade units. Their primary purpose spans anemia diagnosis, transfusion screening, and chronic disease monitoring in clinical and field settings. Automated systems and bench-top machines capture the dominant share of laboratory procurement budgets where throughput and LIS integration justify capital outlay. Portable analyzers and handheld devices represent the fastest-expanding delivery mode segment as point-of-care testing protocols extend into pharmacies, mobile clinics, and resource-limited settings where laboratory infrastructure remains sparse.
The FDA's CLIA categorization framework determines where specific analyzer complexity classes may operate, directly constraining placement in physician offices versus certified laboratories. The EMA's In Vitro Diagnostic Regulation and India's CDSCO medical device rules impose divergent conformity pathways that manufacturers must navigate for market access across jurisdictions. Stakeholders must monitor how WHO prequalification criteria evolve for anemia diagnostics, as these standards increasingly govern procurement eligibility in low- and middle-income health programs.
Market Dynamics
Laboratory consolidation and point-of-care decentralization are compressing the middle tier of hemoglobin analyzers, forcing manufacturers to choose between high-throughput automation for reference labs and ultra-portable formats for field deployment.
Growth Catalysts
- India's anemia screening mandates:The National Iron Plus Initiative and Anemia Mukt Bharat program drive bulk procurement of handheld devices for village health workers.
- WHO prequalification pathways:Eligibility for UNFPA and Global Fund tenders opens procurement channels across sub-Saharan Africa and South Asia.
- Photometric miniaturization:Solid-state LED sources and CMOS detectors enable laboratory-grade precision in battery-operated formats.
Market Restraints
- Optical component concentration:Precision interference filters and photodiode arrays depend on Japanese and German specialty suppliers.
- Reagent cold chain requirements:Liquid cyanmethemoglobin reagents need 2-8°C storage, limiting deployment in tropical clinics without refrigeration.
- FDA CLIA complexity barriers:Moderate-complexity analyzers face restricted placement in physician offices, capping addressable volume.
Strategic Opportunities
- Indonesia's primary health expansion:Puskesmas network upgrades create demand for ruggedized portable units with local language interfaces.
- Capillary blood calibration standards:Devices validated for fingerstick sampling bypass phlebotomy infrastructure requirements.
- Telemedicine integration:Bluetooth-enabled analyzers feeding mobile health platforms enable remote hematology monitoring.
Industry Challenges
- Biomedical engineer scarcity:Field maintenance of optical systems requires technicians trained in photometer alignment and reagent handling.
- Multi-jurisdiction certification lag:Parallel FDA 510(k), CE-IVDR, and CDSCO submissions extend time-to-revenue by 18-24 months.
- LIS interoperability fragmentation:Proprietary data protocols complicate integration with legacy laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobin Analyzer Market |
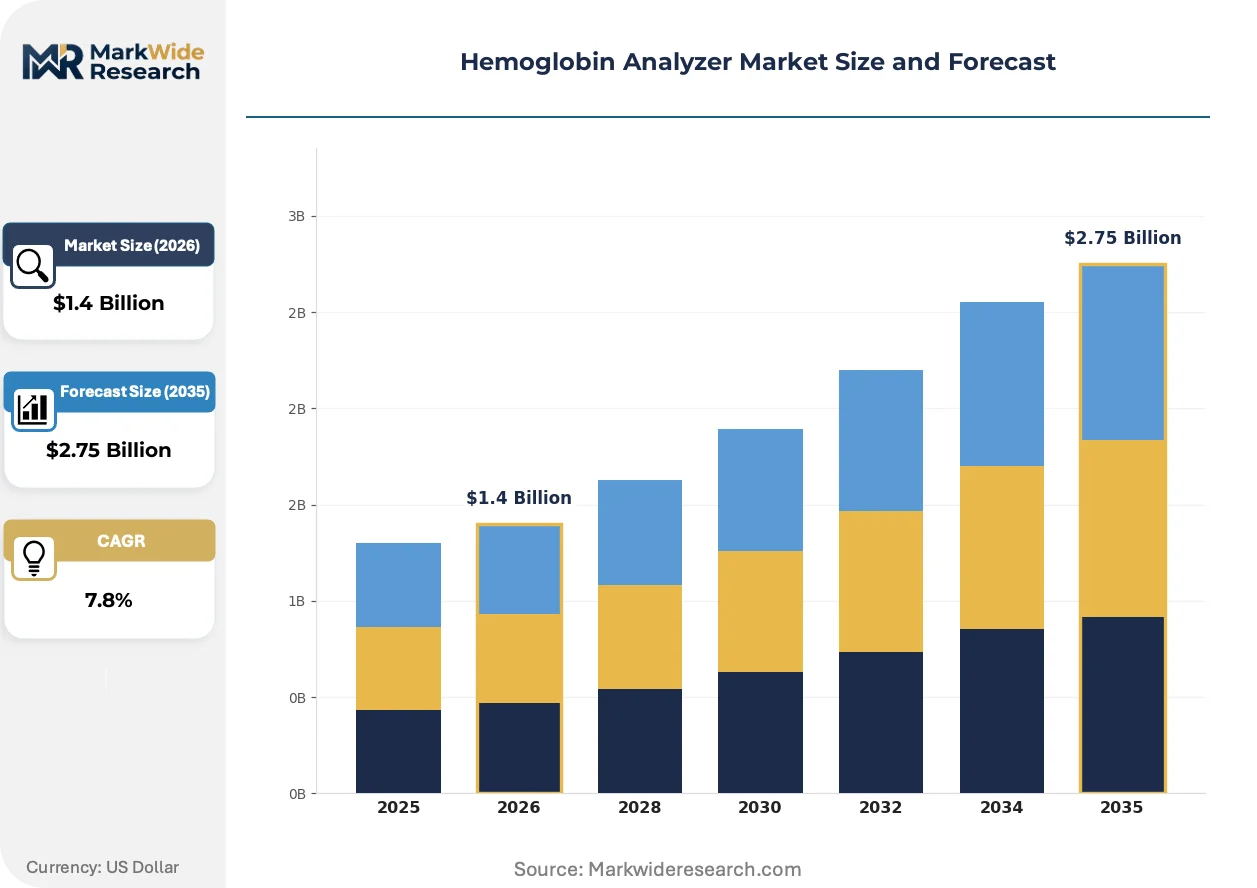
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Automated Systems, Handheld Devices, Bench-top Machines Technology: Colorimetric, Spectrophotometric, Electrochemical, Microfluidic End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutions Delivery Mode: Point-of-Care Testing, Laboratory Testing, Home Testing, Remote Monitoring |
| Companies Covered | Sysmex Corporation, Danaher Corporation, Abbott Laboratories, Siemens Healthineers, Shenzhen Mindray Bio-Medical Electronics, Beckman Coulter, Horiba, Bio-Rad Laboratories, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobin Analyzer Market Emerging Trajectories
Photometric detection architectures are fragmenting across three distinct performance tiers, each optimized for contrasting deployment environments rather than converging on a single dominant design.
Microfluidic cartridge systems are decentralizing hemoglobin testing from centralized laboratories to pharmacy counters and mobile screening vans. Retail pharmacy chains in Brazil and Mexico deploy these devices for walk-in anemia checks without venipuncture. The technology is compressing the traditional referral pathway from symptom presentation to laboratory diagnosis.
EMA's In Vitro Diagnostic Regulation (IVDR) reclassifies hemoglobin analyzers from self-certified to notified body-reviewed devices, elevating clinical evidence requirements. Manufacturers must now submit performance studies against predicate methods rather than analytical validation alone. The regulation is forcing smaller European distributors to abandon private-label sourcing and consolidate around established OEM partnerships.
Bundled reagent contracts are displacing instrument-only sales in high-volume hospital networks. Procurement teams negotiate multi-year commitments locking in per-test pricing with minimum volume guarantees. This shift is most visible in India's corporate hospital chains, where operational expenditure models favor predictable cash flows over capital equipment purchases.
Hemoglobin Analyzer Market Segmentation
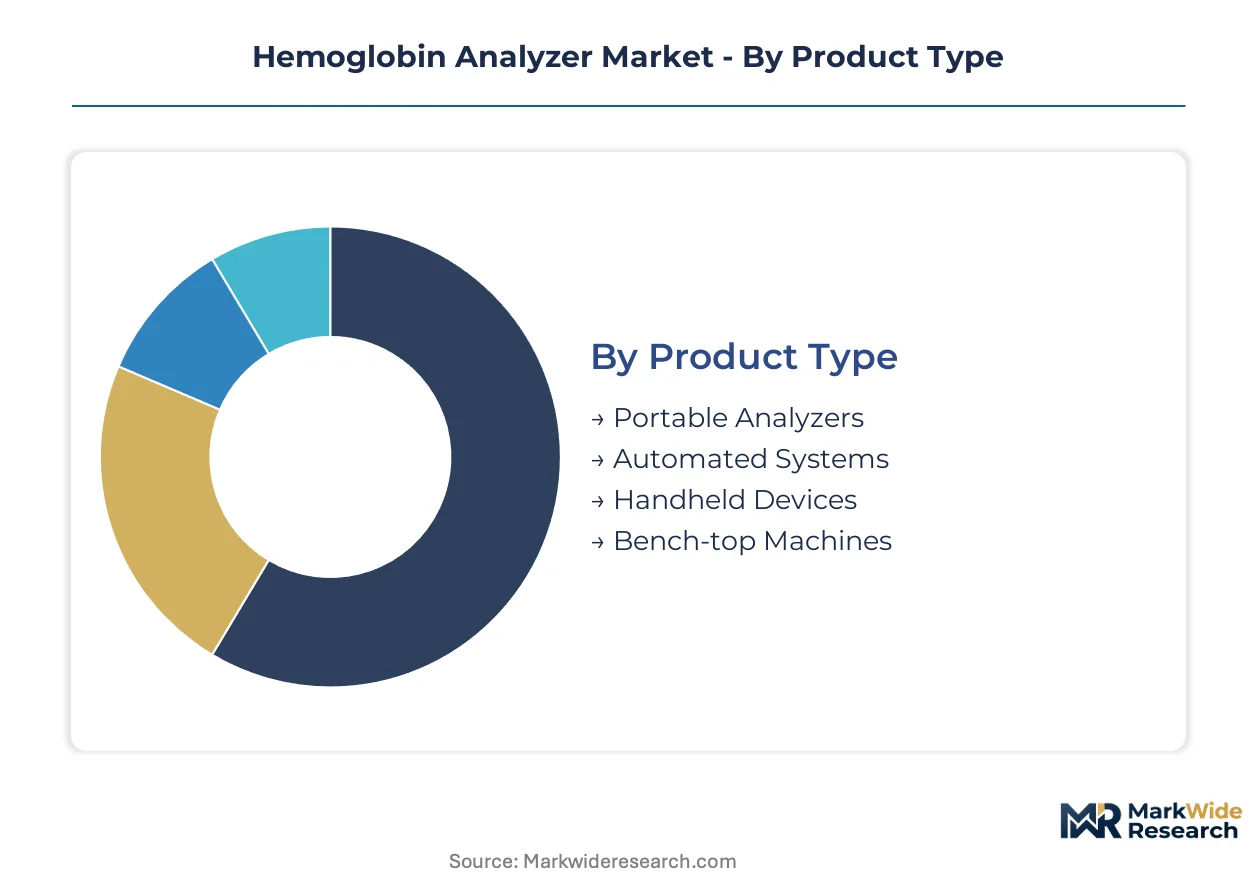
Procurement patterns in hemoglobin analyzers diverge sharply between capital-intensive laboratory infrastructure and distributed screening networks. Understanding segment boundaries reveals where upgrade cycles concentrate versus where first-time placements dominate.
Product Type:
Replacement cycles vary dramatically across the product hierarchy, with laboratory automation following 7-10 year depreciation schedules while portable units face 3-5 year obsolescence from battery and optical degradation.
- Portable Analyzers:Battery-operated units weighing under 5 kilograms deploy photometric or electrochemical methods with rechargeable power systems. India's village health workers under Anemia Mukt Bharat procure these for household screening where electrical infrastructure remains unreliable.
- Automated Systems:High-throughput platforms integrate sample handlers, barcode readers, and LIS connectivity for 100+ tests per hour. Corporate hospital chains in India favor these under reagent rental contracts that convert capital expenditure into predictable per-test operational costs.
- Handheld Devices:Single-operator units with capillary blood compatibility dominate pharmacy counter deployments in Brazil and Mexico.
- Bench-top Machines:Mid-tier systems without full automation serve smaller diagnostic laboratories in Indonesia's Puskesmas network upgrades.
Volume placements concentrate in Automated Systems; the faster expansion belongs to Handheld Devices.
Technology:
Cost tiers separate mature photometric methods from emerging microfluidic architectures, with reimbursement codes and regulatory pathways reinforcing these stratifications.
- Spectrophotometric:LED-illuminated systems with CMOS detectors now match laboratory-grade precision in portable formats. Sysmex Corporation's in-house optical component production anchors supply security for this dominant technology tier.
- Microfluidic:Cartridge-based platforms eliminate liquid reagent handling through lyophilized chemistry embedded in disposable cassettes. Retail pharmacy chains in Latin America deploy these for walk-in screening without venipuncture capabilities.
- Colorimetric:Cyanmethemoglobin formation with filter-based detection remains the reference method for regulatory submissions.
- Electrochemical:Amperometric sensors enable strip-based formats with minimal power requirements for remote monitoring applications.
Reimbursement concentration favors Spectrophotometric methods; Microfluidic formats are climbing the fastest as pharmacy channels expand.
End User:
Customer procurement sophistication spans from centralized tendering authorities to fragmented individual purchasers, shaping contract structures and service requirements.
- Diagnostic Laboratories:High-volume reference sites demand STAT processing capabilities and middleware integration with existing LIS architectures. India's diagnostic laboratory chains consolidate testing volumes through hub-and-spoke models that concentrate automated system procurement.
- Hospitals:Acute care settings prioritize turnaround time for transfusion decisions and pre-surgical screening. Blood bank integration requirements drive specifications for closed-tube sampling and positive patient identification systems.
- Blood Banks:Donor screening protocols mandate high-precision hemoglobin thresholds with documented traceability for regulatory compliance.
- Research Institutions:Method validation studies and clinical trial support generate demand for reference-grade analyzers with extended analytical ranges.
Instrument placements concentrate in Diagnostic Laboratories; Blood Banks show the steepest expansion trajectory as donation screening protocols tighten.
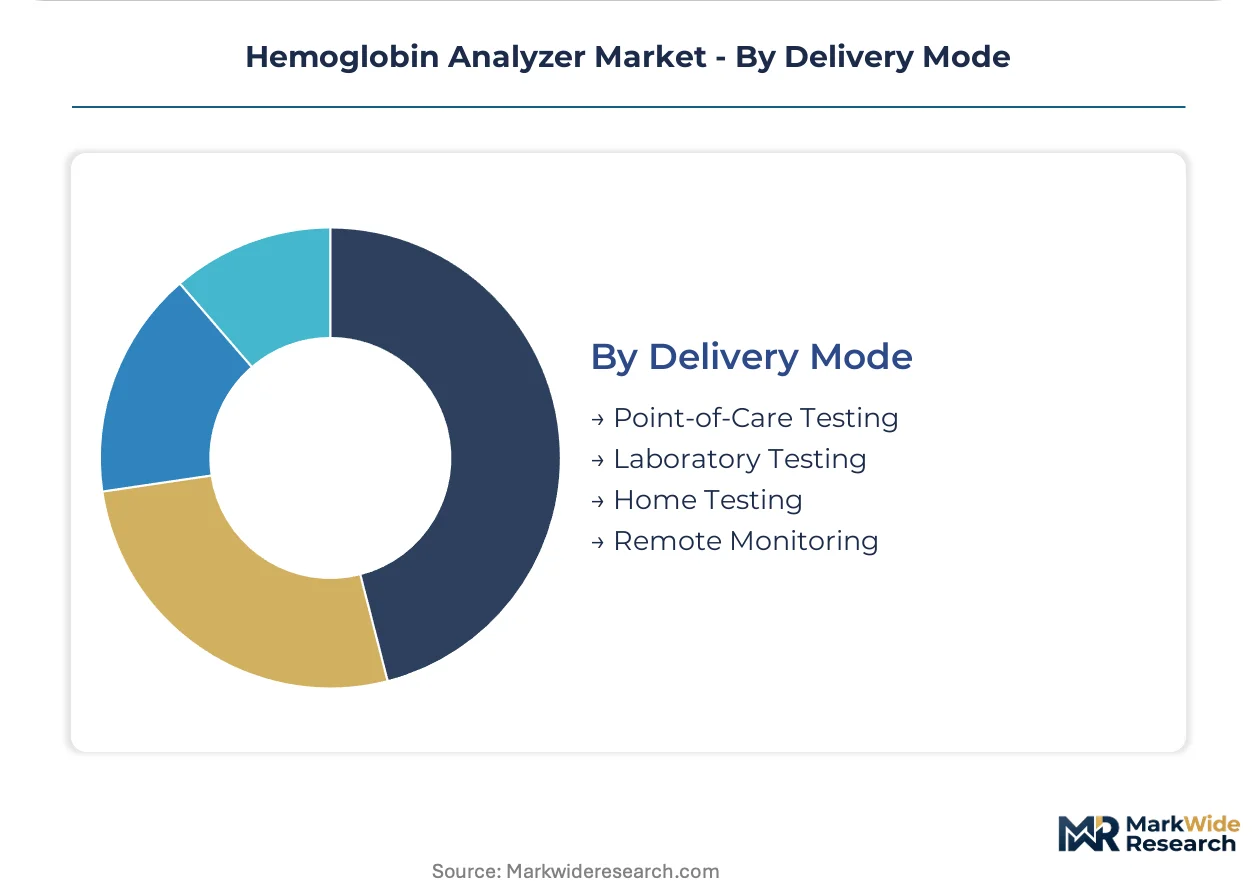
Delivery Mode:
Channel configuration determines regulatory complexity, with CLIA complexity classifications in the United States and CDSCO medical device rules in India constraining where specific formats may operate.
- Laboratory Testing:Centralized processing with venous blood collection and automated sample handling maintains diagnostic accuracy benchmarks. FDA moderate-complexity categorization restricts these systems to certified laboratories.
- Point-of-Care Testing:Capillary blood protocols with waived or near-patient complexity enable placement in physician offices and retail clinics. Bluetooth-enabled units feeding mobile health platforms support telemedicine integration for remote hematology monitoring.
- Home Testing:Over-the-counter formats with simplified operation target chronic disease self-management markets.
- Remote Monitoring:Connected devices with cloud data transmission enable longitudinal tracking for rural populations.
Test volumes concentrate in Laboratory Testing; Point-of-Care Testing is gaining share fastest as primary health infrastructure decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore's medical device corridor drives India's dominance in portable hemoglobin analyzer manufacturing, with clusters in Shenzhen and Boston anchoring complementary supply chains for optical components and laboratory automation.
India
Village health workers under Anemia Mukt Bharat procure handheld devices for household screening where electrical infrastructure remains unreliable. CDSCO medical device rules impose conformity pathways that manufacturers navigate for market access. Gujarat's industrial belt hosts assembly operations for battery-operated units destined for sub-Saharan Africa tender programs.
United States
Diagnostic laboratories expand automated system adoption as hematology testing volumes rise in reference lab networks. FDA CLIA complexity classifications determine instrument placement decisions, restricting moderate-complexity analyzers to certified laboratories. Boston's Route 128 corridor concentrates R&D for photometric miniaturization technologies.
Germany
Precision interference filter suppliers anchor European optical component supply security for laboratory-grade systems. EMA's In Vitro Diagnostic Regulation elevates clinical evidence requirements through notified body review. Baden-Württemberg's precision engineering clusters produce photodiode arrays for high-throughput platforms.
China
Domestic diagnostic laboratory chains consolidate testing volumes through hub-and-spoke models. NMPA regulatory pathways govern market entry for imported and locally manufactured devices. Shenzhen's electronics manufacturing ecosystem enables cost-competitive production of CMOS detector modules.
Brazil
Retail pharmacy chains deploy microfluidic cartridge systems for walk-in anemia checks without venipuncture capabilities. ANVISA medical device regulations structure import and local production requirements. São Paulo's metropolitan health network upgrades Puskesmas-equivalent primary care facilities with bench-top machines.
Hemoglobin Analyzer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory certification tiers. Laboratory automation contracts concentrate among diversified diagnostics platforms, while point-of-care channels fragment across specialized portable device manufacturers. Three archetypes dominate: integrated diagnostics conglomerates with hematology analyzer portfolios, precision optics specialists with captive component supply, and emerging microfluidic platform developers. Competitive moves center on reagent rental contract structures and multi-jurisdiction certification acceleration.
Within the integrated diagnostics tier, Danaher Corporation and Siemens Healthineers exemplify platform breadth strategies that anchor laboratory automation contracts through bundled service offerings. Sysmex Corporation occupies a distinctive position as a precision optics specialist with in-house production capabilities for critical photometric components. Abbott Laboratories represents the point-of-care archetype with handheld formats calibrated for capillary blood sources.
| Leading Market Players |
|---|
| Sysmex Corporation |
| Danaher Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Shenzhen Mindray Bio-Medical Electronics |
| Beckman Coulter |
| Horiba |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| Others |
Supply Flow & Price Mechanics
Corporate hospital chains in India anchor procurement volumes through reagent rental contracts that convert capital expenditure into predictable per-test operational costs. This buyer concentration shapes pricing power toward bundled service models rather than discrete instrument sales.
Pricing Analysis
Throughput-based pricing anchors contract negotiations, with automated systems commanding premium rates tied to hourly test capacity and uptime guarantees. Price differentiation rests on CLIA complexity classification and optical precision grade, with FDA-waived handheld units facing steeper compression than moderate-complexity laboratory platforms. Cost compression in portable tiers intensifies as Indian and Indonesian government tenders standardize specifications. Blood bank procurement committees show lowest price sensitivity due to traceability mandates; retail pharmacy chains exhibit highest sensitivity as margin-thin screening services compete with laboratory referrals.
Supply Chain Analysis
Biomedical engineer scarcity in Bangalore and Shenzhen assembly corridors constrains field service capacity for optical system maintenance. Precision interference filters and photodiode arrays draw from German and Japanese specialty suppliers; CMOS detector modules feed from Shenzhen's electronics ecosystem. Single-source vulnerability concentrates in photometric component tiers where Sysmex Corporation maintains captive production. Distribution runs through diagnostic laboratory chains in India, GPO contracts in the United States, and UNFPA tender programs across sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where optical component supply security determines margin defense. Players pursue backward integration into precision filter manufacturing to reduce dependency on Japanese and German specialty suppliers.
For Market Incumbents: Cement laboratory automation contracts through multi-year reagent rental commitments with minimum volume guarantees. Lock in GPO relationships with diagnostic laboratory chains before EMA IVDR compliance costs elevate competitive barriers. Prioritize in-house production of LED illumination modules to offset photodiode array supply volatility from German precision engineering clusters.
For New Entrants and Emerging Players: The gap between premium automated systems and economy handheld devices offers white-space entry through microfluidic cartridge platforms calibrated for capillary blood. Target Brazil's retail pharmacy channel where ANVISA regulations favor novel venipuncture-free formats. Pursue WHO prequalification pathways to unlock UNFPA and Global Fund tender eligibility across sub-Saharan Africa.
For Investors and Strategic Acquirers: The window for entry favors precision optics specialists with captive component supply and established CDSCO regulatory dossiers. Five-to-ten year viability hinges on consolidation around laboratory automation platforms as mid-tier bench-top machines face compression. Monitor FDA CLIA complexity reclassifications as inflection indicators for point-of-care addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contract Expansion | Converts capital expenditure into predictable operational flows for Indian hospital chains. |
| CDSCO Regulatory Dossier Completion | Unlocks procurement eligibility under Anemia Mukt Bharat village health worker programs. |
| Optical Component Backward Integration | Secures supply of precision interference filters against Japanese supplier concentration. |
| Bluetooth-Enabled Telemedicine Integration | Feeds hemoglobin data into mobile health platforms for rural population monitoring. |
| Lyophilized Reagent Cartridge Development | Eliminates cold chain dependencies that constrain tropical clinic deployment. |
Methodological Framework
Independent corroboration across biomedical engineers at Indian diagnostic laboratory chains, procurement managers at corporate hospital networks, and regulatory affairs specialists at CDSCO and FDA underwrites the qualitative findings. Primary interviews with hematology instrument service technicians, GPO contracts managers, and WHO prequalification officers combined with secondary validation from FDA 510(k) filings, EMA IVDR submissions, UNFPA tender databases, and CDSCO medical device registrations. Bottom-up instrument placement estimates triangulate against top-down laboratory infrastructure spending projections.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon. Segmentation dimensions model product type hierarchy, technology tier, end-user procurement sophistication, and delivery mode regulatory classification. CAGRs derive from installed base depreciation schedules, replacement cycle analysis, and tender pipeline visibility. Forecast inputs incorporate India's National Iron Plus Initiative procurement timelines and Indonesia's Puskesmas network upgrade commitments.
Inputs from hospital purchasing committees and diagnostic laboratory chain executives were available through the study window; gaps in village health worker utilization rates introduce uncertainty bands around portable analyzer penetration assumptions. Forecasts reflect documented assumptions regarding CLIA complexity stability and EMA IVDR implementation timelines. Material deviation in WHO prequalification criteria or CDSCO medical device rule amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hematology Analyzers Market
Hematology
Hematologic Malignancies Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Single Blood Drop Analysis Market
Hematology
Polycythemia Vera Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Global Hemoglobin Meter Market
Hematology
Thalassemia Treatment Market
Hematology
Sickle Cell Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Hemostatic Spray Market
Hematology
Polycythemia Vera Treatment Market