
 Mexico Computed Tomography Market | 2026-2036
Mexico Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Computed Tomography Market Foresight
The Mexico Computed Tomography Market is pivoting on a widening gap between premium multi-slice systems and commodity standalone units serving rural clinics. Siemens Healthineers AG leverages its service infrastructure to dominate high-end hospital installations. Canon Medical Systems Corporation anchors the mid-tier segment through channel partnerships with regional distributors. GE Healthcare differentiates via AI-embedded reconstruction software that reduces scan times.
Computed tomography is a diagnostic imaging modality that uses rotating X-ray sources and detector arrays to generate cross-sectional anatomical reconstructions, with modern multi-slice systems achieving sub-millimeter spatial resolution through helical acquisition protocols. The technology serves primarily for non-invasive detection of tumors, vascular pathologies, and traumatic injuries across outpatient and inpatient settings. Multi-slice CT occupies the largest revenue pool due to throughput requirements at major hospitals, while cone beam CT grows fastest in dental and maxillofacial imaging clinics. AI-based imaging commands premium pricing as radiology groups seek automated lesion detection and workflow optimization.
COFEPRIS, Mexico's national health regulator, enforces medical device safety standards that align with FDA and IEC 60601-1 frameworks for electrical safety and radiation emission controls. NOM-229-SSA1-2002 establishes specific technical requirements for CT installation, maintenance, and operator certification that shape procurement criteria for public sector buyers. Stakeholders must monitor how impending updates to Mexican digital health regulations affect AI algorithm validation requirements for diagnostic software.
Market Dynamics
COFEPRIS regulatory streamlining is compressing approval timelines for AI-integrated CT systems, accelerating procurement cycles across Mexico's public hospital networks and forcing incumbent vendors to reconfigure service delivery models.
Growth Catalysts
- NOM-229-SSA1-2002 compliance mandates:Public sector buyers must meet specific CT installation and operator certification standards, creating recurring equipment refresh demand across Mexico City, Guadalajara, and Monterrey hospital networks.
- Oncology diagnostic volume expansion:Central Mexico states face aging population clusters requiring tumor detection protocols, concentrating CT utilization in diagnostic centers serving Querétaro, Aguascalientes, and San Luis Potosí.
- Helical acquisition protocol adoption:Sub-millimeter spatial resolution capabilities are absorbing radiology group investment as throughput requirements intensify at major tertiary facilities.
Market Restraints
- Import dependency for detector arrays:Mexico lacks domestic manufacturing for solid-state detector components, exposing procurement costs to currency volatility and international supply chain disruptions.
- Radiologist training pipeline constraints:The country's medical education system produces insufficient board-certified imaging specialists to operate expanded CT capacity, creating utilization bottlenecks.
- Capital intensity of multi-slice systems:Public hospital budgets face competing priorities for surgical robotics and magnetic resonance equipment, fragmenting available funding for CT procurement.
Strategic Opportunities
- AI algorithm validation pathways:COFEPRIS is developing expedited review frameworks for diagnostic software, enabling faster market entry for automated lesion detection tools.
- Cone beam CT dental expansion:Maxillofacial imaging clinics in Baja California and Nuevo León represent underpenetrated demand for compact systems outside traditional hospital settings.
- Service contract unbundling:Independent technical service providers can capture maintenance revenue from aging installed base units as original manufacturer agreements expire.
Industry Challenges
- Technician certification backlogs:NOM-229-SSA1-2002 requires specialized operator credentials that training institutions cannot deliver at pace with equipment deployment schedules.
- Legacy system integration complexity:PACS interoperability gaps between new AI-embedded CT platforms and existing hospital information systems delay productive utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Computed Tomography Market |
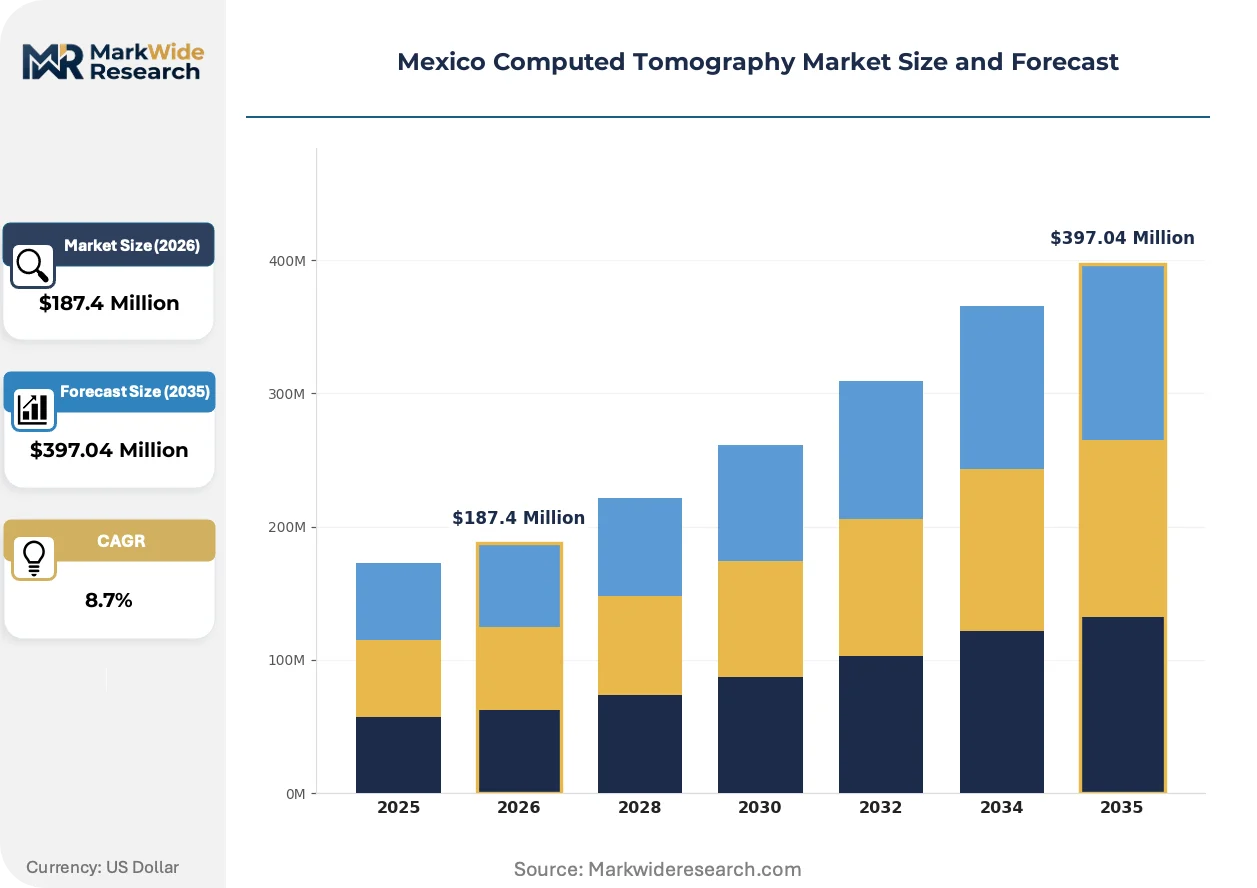
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone CT, Integrated CT, Cone Beam CT, Multi-Slice CT End User: Hospitals, Diagnostic Centers, Research Institutes, Imaging Clinics Application: Oncology, Cardiovascular, Neurology, Orthopedics Technology: Ultrasound-CT Integration, AI-Based Imaging, Portable CT, Dual-Energy CT |
| Companies Covered | Planmeca Group, Canon Medical Systems Corporation, GE Healthcare, Neusoft Medical Systems Co. Ltd, Siemens Healthineers AG, Koninklijke Philips NV, Dentsply Sirona Inc., Samsung Electronics Co. Ltd, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Computed Tomography Market Shifts & Advancements
Deep learning reconstruction algorithms are compressing scan protocols while radiation dose monitoring frameworks reshape operator workflows across Mexican diagnostic networks.
Photon-counting detector technology is absorbing investment from premium hospital installations seeking spectral imaging capabilities for tissue characterization. Tertiary care centers in Mexico City are piloting these systems for cardiovascular plaque analysis. The technology is absorbing market share from conventional energy-integrating detectors as reimbursement frameworks evolve to reward diagnostic specificity.
COFEPRIS alignment with FDA pre-certification pathways for software-as-medical-device is accelerating validation timelines for AI-embedded reconstruction tools. Mexican regulators now accept predicate device approvals from US 510(k) clearances for algorithm updates. Radiology groups in Jalisco and Nuevo León are leveraging this convergence to deploy automated lung nodule detection ahead of national availability.
Public hospital consortia are consolidating procurement through centralized purchasing agreements that aggregate volume across state health systems. The Instituto de Salud para el Bienestar and state ministries are replacing fragmented facility-level tenders with multi-year framework contracts. Chihuahua and Veracruz have adopted this model, compressing vendor negotiation cycles and standardizing service level specifications across their networks.
Mexico Computed Tomography Market Segmentation
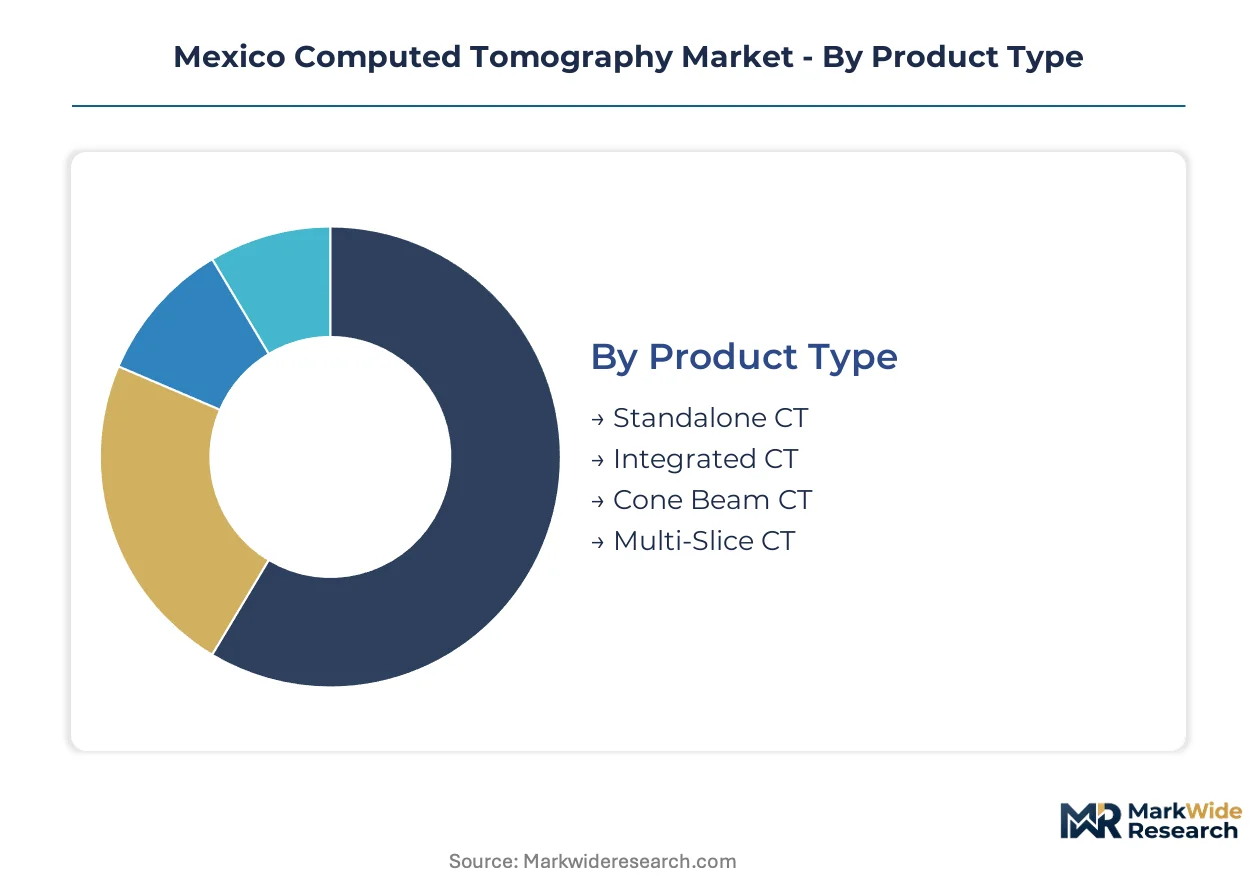
CT procurement patterns across Mexico diverge sharply by facility infrastructure and clinical throughput requirements. Public hospital networks prioritize multi-slice throughput for oncology backlogs, while private imaging clinics optimize for capital efficiency in satellite locations.
Product Type:
Capital allocation intensity separates procurement decisions across Mexico's hospital tiers, with tertiary facilities absorbing premium equipment costs against constrained rural clinic budgets.
- Multi-Slice CT:Helical acquisition systems achieve sub-millimeter spatial resolution through rotating detector arrays and continuous patient table movement. Mexico City, Guadalajara, and Monterrey hospital networks concentrate demand here as oncology diagnostic volumes strain throughput capacity at Instituto Nacional de Cancerología and comparable tertiary centers.
- Cone Beam CT:Compact systems deploy flat-panel detectors and cone-shaped X-ray beams for maxillofacial and dental applications with reduced radiation exposure. Maxillofacial imaging clinics in Baja California and Nuevo León represent underpenetrated demand outside traditional hospital procurement channels.
- Standalone CT:Single-slice systems serve basic trauma screening and rural clinic deployment where infrastructure constraints limit power and cooling requirements.
- Integrated CT:Hybrid configurations combine CT with PET or SPECT modalities for metabolic-functional imaging at specialized oncology centers.
Multi-Slice CT leads on scale; Cone Beam CT leads on momentum.
End User:
Facility reimbursement structures and patient volume economics determine equipment configuration choices across Mexico's fragmented provider landscape.
- Hospitals:Public sector networks anchor procurement volume through centralized purchasing agreements aggregating demand across state health systems. The Instituto de Salud para el Bienestar and state ministries in Chihuahua and Veracruz deploy multi-year framework contracts compressing vendor negotiation cycles.
- Diagnostic Centers:Independent imaging facilities concentrate in central Mexico states serving aging population clusters requiring tumor detection protocols across Querétaro, Aguascalientes, and San Luis Potosí.
- Imaging Clinics:Outpatient settings prioritize throughput efficiency and rapid patient turnaround for elective screening procedures.
- Research Institutes:Academic medical centers deploy advanced spectral and photon-counting configurations for cardiovascular plaque analysis and tissue characterization studies.
Hospitals command procurement volume; Diagnostic Centers are expanding most quickly.
Application:
Disease prevalence patterns and reimbursement specificity shape modality investment priorities across Mexican healthcare regions.
- Oncology:Tumor detection protocols drive the largest installed base utilization as central Mexico states face concentrated aging demographics. NOM-229-SSA1-2002 operator certification requirements create recurring equipment refresh demand tied to workforce training pipelines.
- Cardiovascular:Coronary artery calcium scoring and plaque characterization absorb premium technology investment from tertiary care centers piloting photon-counting detector capabilities.
- Neurology:Stroke imaging protocols and traumatic brain injury assessment concentrate demand at emergency department installations.
- Orthopedics:Trauma and pre-surgical planning applications favor mid-tier slice configurations with rapid reconstruction algorithms.
Oncology leads on scale; Cardiovascular gains share fastest.
Technology:
Regulatory validation pathways and workflow integration complexity determine adoption velocity for emerging CT capabilities.
- AI-Based Imaging:Deep learning reconstruction algorithms compress scan protocols while automated lesion detection tools absorb radiology group investment. COFEPRIS alignment with FDA pre-certification pathways accelerates validation timelines for software-as-medical-device deployments.
- Dual-Energy CT:Spectral imaging capabilities enable material decomposition for tissue characterization and cardiovascular plaque analysis at premium hospital installations.
- Portable CT:Mobile configurations serve intensive care units and intraoperative settings where patient transport risks outweigh equipment mobility constraints.
- Ultrasound-CT Integration:Hybrid systems remain nascent in Mexican installations due to PACS interoperability gaps and training infrastructure limitations.
AI-Based Imaging leads on scale; Dual-Energy CT shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologist training programs concentrate in Mexico City, Guadalajara, and Monterrey, anchoring CT utilization density to these metropolitan corridors. State health ministries channel equipment procurement through these workforce hubs. Regional divergence stems from NOM-229-SSA1-2002 certification backlogs and infrastructure financing gaps.
Mexico City Metro
Oncology diagnostic volumes strain throughput at Instituto Nacional de Cancerología and tertiary hospital networks. COFEPRIS regulatory streamlining accelerates AI-integrated CT approvals for public sector buyers. The metropolitan corridor absorbs premium multi-slice system deployments as centralized purchasing agreements aggregate demand across federal health institutions.
Nuevo León
Maxillofacial imaging clinics drive cone beam CT adoption for dental and craniofacial applications. State health ministry framework contracts standardize service specifications across public hospital networks. Monterrey anchors northern Mexico's diagnostic infrastructure with photon-counting detector pilots at academic medical centers.
Jalisco
Diagnostic centers serving aging populations concentrate in Guadalajara's metropolitan zone. COFEPRIS alignment with FDA pre-certification pathways enables faster AI algorithm validation for radiology groups. The state's medical device distribution channels extend equipment reach into Michoacán and Colima satellite markets.
Bajío Region
Querétaro and Aguascalientes face concentrated demand for cardiovascular and oncology screening protocols. NOM-229-SSA1-2002 operator certification requirements create equipment refresh cycles tied to workforce training pipelines. Manufacturing corridor prosperity funds private diagnostic center expansion outside traditional hospital procurement channels.
Northern Border States
Chihuahua and Baja California deploy portable CT configurations for trauma screening near industrial accident zones. State ministry consolidated purchasing compresses vendor negotiation timelines. Tijuana and Ciudad Juárez imaging clinics capture cross-border patient flows seeking reduced diagnostic wait times.
Mexico Computed Tomography Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Mexico's CT procurement landscape. Equipment manufacturers with captive service infrastructure dominate high-end hospital installations, while regional distributors capture mid-tier volume through channel partnerships. Three archetypes define competitive positioning: integrated multinationals with full-service networks, imaging specialists leveraging technology licensing, and diversified electronics conglomerates extending healthcare verticals. Market consolidation proceeds through multi-year framework contracts with state health systems and strategic partnerships with independent technical service providers.
Among integrated healthcare technology multinationals, Siemens Healthineers AG and GE Healthcare exemplify the full-service archetype with established Mexico City service infrastructure. Canon Medical Systems Corporation occupies a mid-tier position through regional distributor relationships. Chinese equipment manufacturers including Neusoft Medical Systems Co. Ltd represent cost-competitive alternatives penetrating price-sensitive diagnostic center segments. Samsung Electronics Co. Ltd anchors the diversified conglomerate vector, leveraging consumer electronics distribution reach into medical imaging channels.
| Leading Market Players |
|---|
| Planmeca Group |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Neusoft Medical Systems Co. Ltd |
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| Dentsply Sirona Inc. |
| Samsung Electronics Co. Ltd |
| Carestream Health |
| Others |
Supply & Pricing Matrix
Sovereign-backed hospital procurement consortia anchor Mexico's CT equipment financing, compressing vendor margins through multi-year framework contracts while concentrating pricing power among service-integrated multinationals. This ownership pattern forces equipment manufacturers to absorb currency volatility on imported detector arrays while competing for maintenance revenue from aging installed bases.
Pricing Analysis
Bundled service contracts dominate premium hospital installations, while unbundled equipment-only sales penetrate price-sensitive diagnostic centers. Three-tier pricing structure across premium multi-slice, standard mid-tier, and economy standalone configurations separates Siemens Healthineers and GE Healthcare service-integrated offerings from Canon's distributor-channel mid-market positioning and Chinese manufacturers' capital-only economy plays. Pricing pressure stems from COFEPRIS streamlining compressing approval timelines and intensifying vendor competition for public sector volume. Diagnostic centers in central Mexico states exhibit highest price sensitivity due to constrained capital access, whereas tertiary hospitals in Mexico City prioritize throughput reliability over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with solid-state detector manufacturing concentrated in Germany, Japan, and the United States, exposing Mexican procurement to euro-yen-dollar currency swings and trans-Pacific logistics disruptions. X-ray tube assemblies, high-voltage generators, and scintillator crystals draw from these same geographies with limited dual-sourcing alternatives. Tariff exposure on precision electronics amplifies landed cost volatility for public hospital buyers operating under fixed peso budgets. Distribution runs through regional medical device distributors in Guadalajara and Monterrey who warehouse inventory and provide first-line technical support, with direct manufacturer relationships reserved for premium multi-slice installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's CT market functions as a geographic-arbitrage play for equipment manufacturers seeking regulatory pathway efficiency: COFEPRIS alignment with FDA pre-certification compresses validation timelines versus European MDR pathways, lowering cost-to-market for AI-embedded systems.
For Market Incumbents: Deploy service contract unbundling to capture maintenance revenue from aging installed base units as original manufacturer agreements expire. Siemens Healthineers and GE Healthcare should consolidate high-end hospital positions through captive technical infrastructure in Mexico City, while preempting Chinese manufacturer encroachment via accelerated AI algorithm localization. The threat rests with Neusoft and comparable cost competitors penetrating diagnostic center segments through capital-only pricing. For New Entrants and Emerging Players: COFEPRIS expedited review frameworks for diagnostic software in Mexico open a window for AI-native imaging specialists to enter ahead of full FDA 510(k) clearance cycles. White-space targets concentrate in cone beam CT for maxillofacial clinics across Baja California and Nuevo León, plus portable CT configurations for northern border trauma screening. A service-partnership go-to-market angle with established regional distributors bypasses captive infrastructure requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among independent technical service providers with NOM-229-SSA1-2002 certification capabilities and established relationships with state health ministry procurement officers. Long-term viability hinges on consolidation of fragmented maintenance networks serving Mexico's aging single-slice installed base. The signal to watch is COFEPRIS publication of final AI algorithm validation guidelines, which will determine regulatory capital requirements for software-as-medical-device entrants.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Pre-Certification Alignment | Accelerates AI-embedded CT market entry via FDA predicate device acceptance. |
| State Health Ministry Framework Contracts | Aggregates procurement volume across Chihuahua and Veracruz public networks. |
| Photon-Counting Detector Pilot Programs | Positions tertiary centers for cardiovascular plaque analysis reimbursement. |
| Independent Service Provider Partnerships | Captures maintenance revenue from expiring manufacturer service agreements. |
| Cone Beam CT Dental Channel Expansion | Penetrates underdeveloped maxillofacial imaging clinics in northern Mexico. |
Research Methodology
Multiple input streams — structured interviews with hospital biomedical engineers and GPO contracts managers, regulatory filing analysis through COFEPRIS databases, and customs trade data on detector array imports — were reconciled against secondary validation from SEC 10-K disclosures and hospital procurement databases. Bottom-up equipment deployment tracking across Mexico City, Guadalajara, and Monterrey networks was triangulated with top-down market sizing from centralized purchasing agreement values.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation by product type (multi-slice, cone beam, standalone, integrated), end user (hospitals, diagnostic centers, imaging clinics, research institutes), application (oncology, cardiovascular, neurology, orthopedics), and technology tier (AI-based, dual-energy, portable). CAGRs were derived from equipment refresh cycles tied to NOM-229-SSA1-2002 certification requirements and public sector budget allocation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under peso depreciation scenarios or COFEPRIS regulatory delays. Forecasts reflect assumptions about AI algorithm validation pathway finalization and state health ministry procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Contrast Media Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Radiology Services Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Global Dental Panoramic Radiography Market