
 Brazil Digital Radiology Market | 2026-2036
Brazil Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Digital Radiology Market Insights
Modular detector-panel bundling with software subscription tiers is realigning how Brazilian hospital procurement committees evaluate total cost of ownership. Siemens Healthineers leverages its service infrastructure across southeastern states to anchor long-term contracts with large hospital federations. GE Healthcare competes through localized assembly partnerships that reduce import-duty exposure on high-end CT gantries. Fujifilm Holdings Corporation differentiates via specialized digital radiography retrofit kits that extend the useful life of existing X-ray rooms in budget-constrained municipal facilities.
Brazil digital radiology encompasses electronic image capture, processing, storage, and transmission systems that replace conventional film-based diagnostic imaging, typically employing flat-panel detectors with cesium iodide or amorphous silicon layers achieving spatial resolution below 150 micrometers for clinical-grade chest and musculoskeletal studies. These systems serve primarily to reduce radiation dose exposure, eliminate chemical processing costs, and enable teleradiology workflows connecting remote municipalities to specialist interpretation hubs in state capitals. CT scanners command the dominant share of product-type revenue given their indispensability in trauma and oncology staging protocols across Brazil's unified health system, while direct radiography technology outpaces computed radiography in new installations as detector-panel costs decline and image-acquisition speed becomes decisive for high-volume outpatient clinics. Cloud-based solutions represent the fastest-expanding technology segment, though data-localization requirements under Brazil's General Data Protection Law constrain pure SaaS architectures and favor hybrid on-premise configurations.
ANVISA governs medical device registration and post-market surveillance, with recent resolution updates streamlining equivalence pathways for digital radiology systems already approved by FDA or EMA, while the Brazilian Association of Technical Standards maintains electromagnetic compatibility and electrical safety benchmarks aligned with IEC 60601 family specifications. These regulatory frameworks shape demand by extending procurement cycles for novel technologies while creating compliance cost barriers for smaller domestic distributors lacking dedicated regulatory affairs departments. Stakeholders must monitor forthcoming ANVISA guidance on artificial-intelligence-enabled diagnostic algorithms, as classification uncertainties for computer-aided detection software could reshape vendor competitive dynamics and hospital capital-planning horizons.
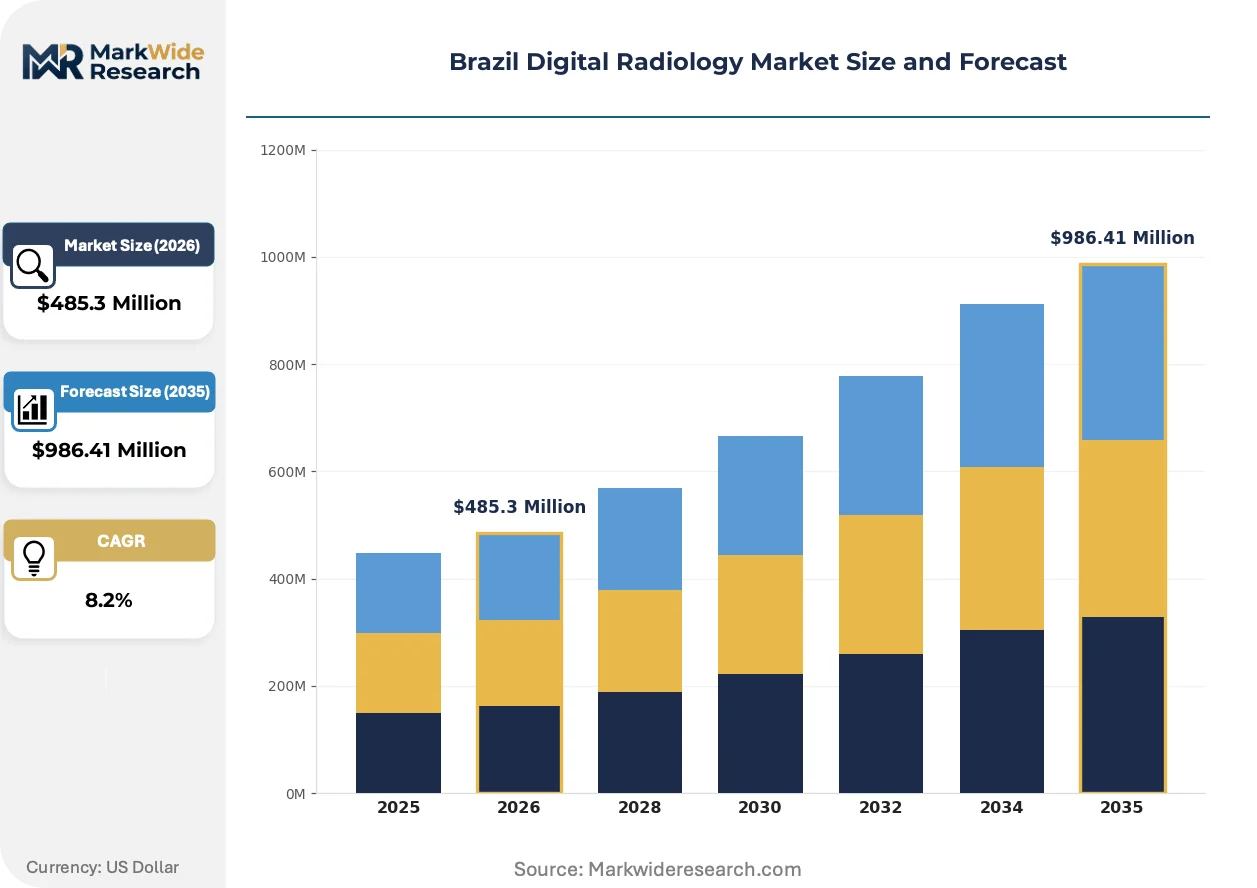
Market Dynamics
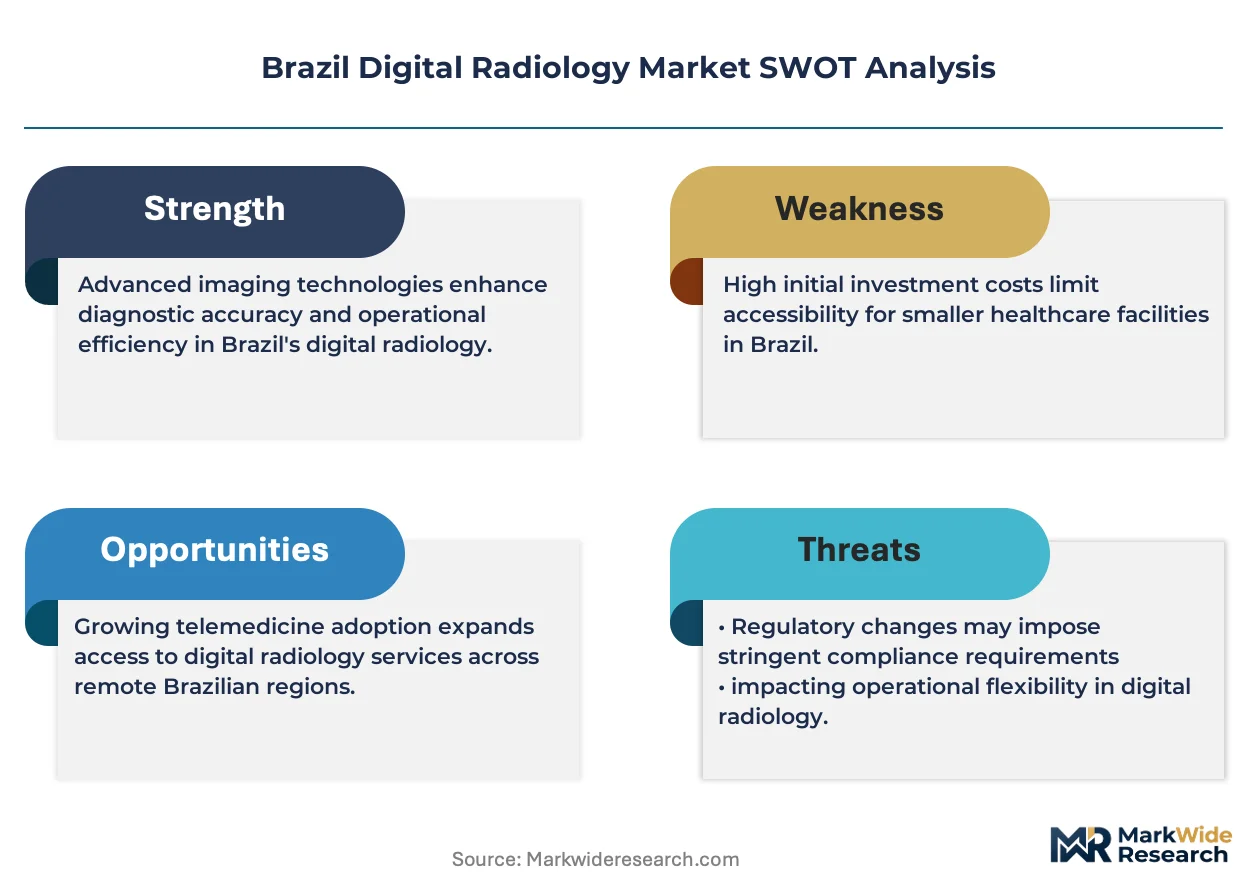
ANVISA's compressed equivalence pathways for FDA and EMA approved equipment are accelerating replacement cycles for legacy analog systems across southeastern hospital networks, while municipal budget constraints in northern states perpetuate equipment fragmentation.
Growth Catalysts
- ANVISA Resolution Updates:Streamlined registration for imported digital radiology systems already cleared by FDA or EMA reduces approval timelines from 18 months to under 12 months, accelerating procurement decisions by large hospital federations.
- Flat-Panel Detector Cost Decline:Amorphous silicon and cesium iodide panel prices have fallen sufficiently to make direct radiography economically viable for mid-sized diagnostic clinic chains previously limited to computed radiography.
- Southeast Diagnostic Density:São Paulo and Minas Gerais hospital networks are expanding centralized procurement of digital imaging suites, creating volume anchors that pull vendor service infrastructure into the region.
Market Restraints
- Import Duty Exposure:High-end CT gantries face 14% industrialized product tax plus state VAT, compressing margins for distributors without localized assembly partnerships.
- Data Localization Mandates:Brazil's General Data Protection Law constrains pure cloud SaaS architectures, forcing hybrid on-premise configurations that raise total cost of ownership for teleradiology platforms.
- Specialized Technical Labor Scarcity:Biomedical engineers trained in flat-panel calibration and DICOM integration concentrate in state capitals, leaving remote municipalities dependent on vendor fly-in maintenance.
Strategic Opportunities
- Retrofit Kit Penetration:Budget-constrained municipal facilities in northern and northeastern states present white space for digital radiography retrofit solutions that extend existing X-ray room useful life.
- AI-Enabled Detection Software:Pending ANVISA guidance on computer-aided diagnostic algorithms will clarify classification pathways, enabling vendors to bundle detection tools with base imaging hardware.
- Teleradiology Hub Expansion:Cloud-hybrid platforms connecting Amazonas and Pará remote clinics to Belo Horizonte and São Paulo interpretation centers address radiologist geographic maldistribution.
Industry Challenges
- DICOM-Legacy System Integration:Analog-to-digital migration in older municipal hospitals requires custom middleware development, extending deployment timelines and raising project risk.
- Biomedical Engineer Training Gap:Universities in northern Brazil lack PACS administration and detector calibration curricula, forcing vendors to absorb training costs or limit service coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Digital Radiology Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $986.41 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, MRI Machines, CT Scanners, Ultrasound Devices End User: Hospitals, Diagnostic Clinics, Imaging Centers, Research Institutions Technology: Computed Radiography, Direct Radiography, Analog Imaging, Cloud-Based Solutions Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Shimadzu Corporation, Agfa HealthCare, Carestream Health, Philips Healthcare Informatics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Digital Radiology Market Trends and Innovations
Digital radiology in Brazil is converging around three vectors: detector technology economics, regulatory pathway efficiency, and procurement model restructuring that favors operational expenditure over capital commitment.
Direct radiography flat-panel systems is overtaking computed radiography in new installations across high-volume outpatient clinics. Detector-panel cost declines below the threshold for mid-tier diagnostic chains have compressed payback periods from five years to under three. Southeast region clinic networks are now specifying direct radiography as standard in replacement tenders, marginalizing phosphor-plate computed radiography to budget-constrained municipal facilities.
ANVISA's forthcoming guidance on artificial-intelligence-enabled diagnostic algorithms is reshaping vendor competitive positioning. Classification uncertainties for computer-aided detection software have delayed product launches, forcing manufacturers to prepare dual regulatory submissions. Large hospital federations in São Paulo are now requiring AI-readiness clauses in imaging suite procurement contracts.
Equipment-as-service contracting is displacing outright purchase in public hospital networks. São Paulo and Minas Gerais state health departments now structure radiology procurements around per-study fees that bundle hardware, software, maintenance, and radiologist interpretation. This shift transfers obsolescence risk to vendors while compressing capital expenditure approval cycles from 24 months to under 12 months.
Brazil Digital Radiology Market Segmentation
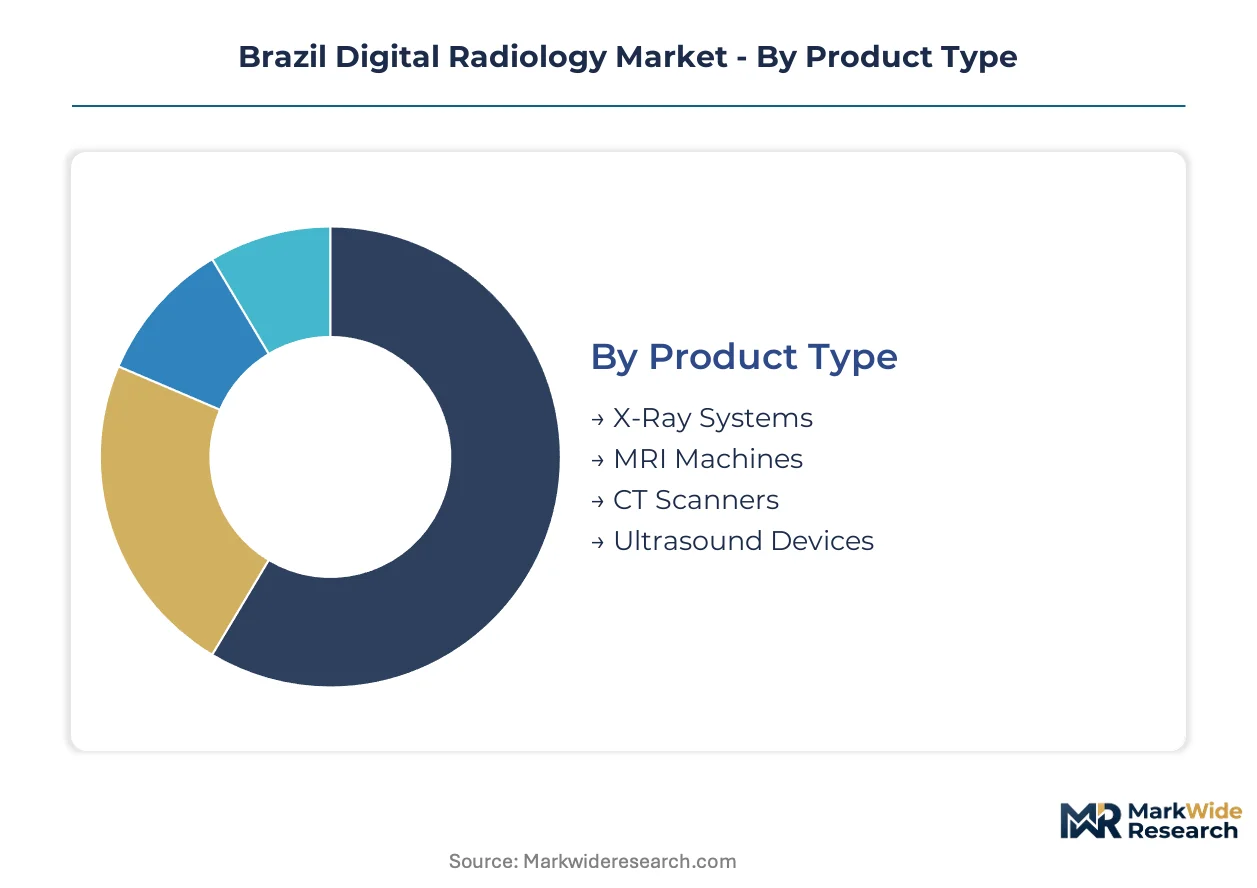
Segmentation in Brazil's digital radiology market reveals how procurement patterns diverge across facility types and technology generations. Understanding these divides helps vendors align product portfolios with the distinct budget cycles and clinical priorities governing public hospital networks versus private diagnostic chains.
Product Type:
Supply concentration in high-end imaging hardware centers on CT gantries and MRI magnets, where import duty exposure and service infrastructure requirements create steep barriers for distributors lacking localized assembly partnerships.
- CT Scanners:Multi-slice CT gantries with 64-to-128 detector rows dominate trauma and oncology staging protocols across São Paulo's unified health system hospitals. Municipal procurement committees in Minas Gerais prioritize these systems for their indispensability in emergency department throughput.
- X-Ray Systems:Flat-panel direct radiography systems employing cesium iodide or amorphous silicon layers achieve spatial resolution below 150 micrometers for chest and musculoskeletal studies. Diagnostic clinic chains in the Southeast region specify these as standard in replacement tenders, marginalizing legacy computed radiography.
- MRI Machines:Superconducting magnet systems face extended ANVISA approval timelines and specialized installation requirements that limit penetration outside state capitals.
- Ultrasound Devices:Portable and cart-based systems serve point-of-care applications in remote municipalities lacking fixed imaging infrastructure.
Today's leader: CT Scanners. Tomorrow's challenger: X-Ray Systems.
End User:
Cost tier differentiation separates capital-intensive public hospital federations from operational-expenditure-focused diagnostic chains, reshaping how vendors structure hardware-software-service bundles.
- Hospitals:Public hospital networks in São Paulo and Minas Gerais anchor centralized procurement of digital imaging suites, creating volume anchors that pull vendor service infrastructure into the Southeast region. Equipment-as-service contracting now displaces outright purchase, transferring obsolescence risk to manufacturers.
- Diagnostic Clinics:High-volume outpatient chains drive replacement cycles for legacy analog systems, specifying direct radiography as standard when detector-panel economics compress payback periods below three years.
- Imaging Centers:Specialized facilities concentrate on teleradiology hub operations connecting remote municipalities to specialist interpretation centers in Belo Horizonte and São Paulo.
- Research Institutions:University hospitals pilot AI-enabled detection software and hybrid cloud configurations constrained by Brazil's General Data Protection Law data-localization mandates.
The installed base concentrates in Hospitals. The steepest expansion trajectory belongs to Diagnostic Clinics.
Technology:
Volume dynamics favor direct radiography uptake as flat-panel detector costs decline, while cloud-hybrid architectures navigate regulatory constraints on pure SaaS deployment.
- Direct Radiography:Amorphous silicon and cesium iodide panel prices have fallen sufficiently to make this technology economically viable for mid-sized diagnostic clinic chains previously limited to computed radiography. Image-acquisition speed becomes decisive for high-volume outpatient workflows.
- Cloud-Based Solutions:Hybrid on-premise configurations address data-localization requirements under Brazil's General Data Protection Law, raising total cost of ownership but enabling teleradiology workflows connecting Amazonas and Pará remote clinics to state capital interpretation hubs.
- Computed Radiography:Phosphor-plate systems persist in budget-constrained municipal facilities in northern and northeastern states where capital replacement cycles extend beyond typical depreciation schedules.
- Analog Imaging:Film-based systems remain fragmented across remote municipalities awaiting federal budget allocations for digital migration.
Direct Radiography commands new installations. Cloud-Based Solutions face regulatory headwinds but retain long-term displacement potential.
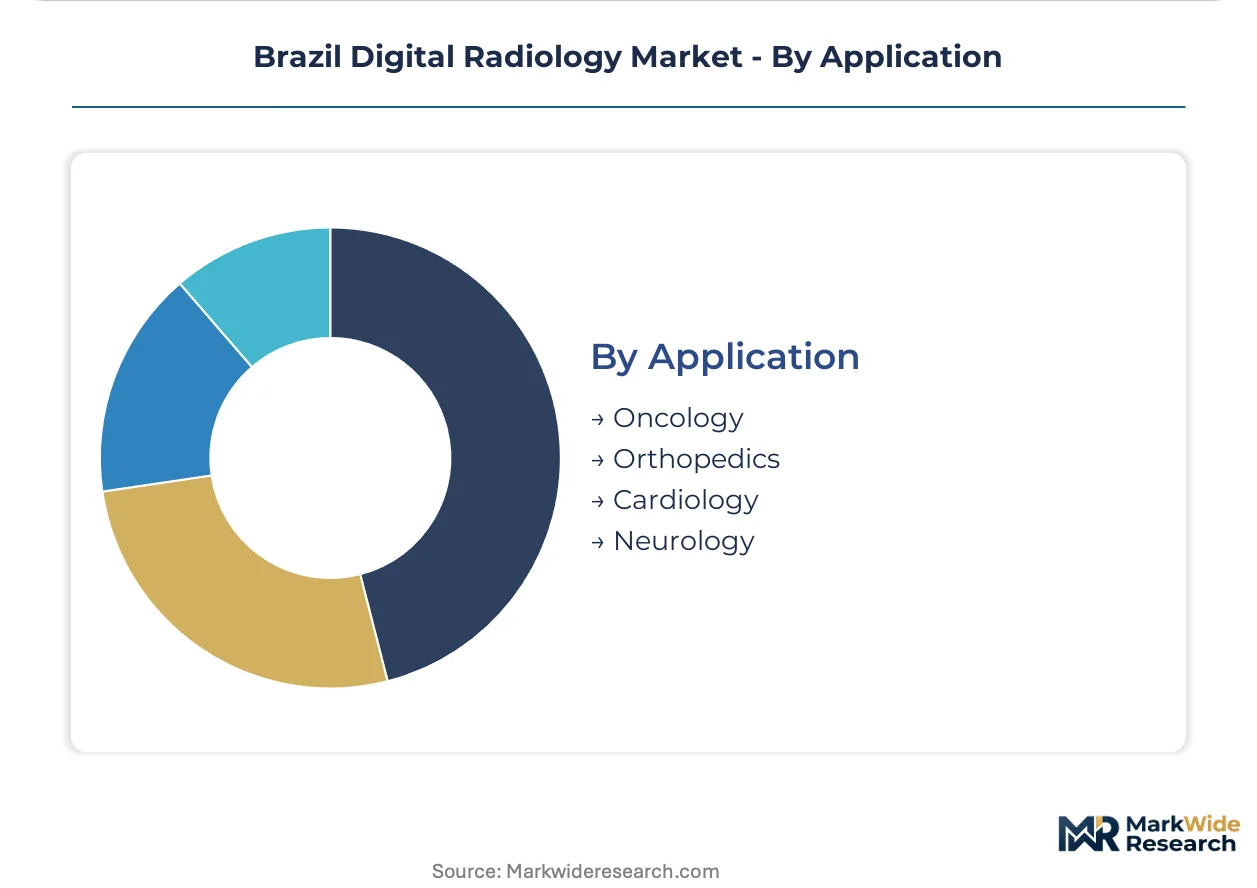
Application:
Customer type priorities diverge between trauma-driven emergency protocols and elective screening programs, with oncology staging commanding the most intensive imaging suite specifications.
- Oncology:CT-based staging protocols across Brazil's unified health system drive the dominant share of high-end scanner demand, with multi-slice gantries required for treatment planning and response monitoring.
- Orthopedics:Digital radiography retrofit kits extend existing X-ray room useful life in municipal facilities performing high volumes of fracture and joint imaging.
- Cardiology:Specialized CT coronary angiography and cardiac MRI applications concentrate in university hospitals and large private hospital federations with interventional capabilities.
- Neurology:MRI-based brain and spine imaging localizes in state capitals where biomedical engineers trained in magnet maintenance and coil calibration concentrate.
Oncology anchors hardware specifications. Orthopedics presents the broadest addressable base for retrofit solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's digital radiology infrastructure originated in the Southeast's academic medical centers during the 1990s, with São Paulo university hospitals pioneering PACS adoption before spreading to public hospital networks and private diagnostic chains.
São Paulo
The state anchors national demand through Hospital das Clínicas and Albert Einstein networks driving multi-slice CT procurement. ANVISA's streamlined equivalence pathways accelerate equipment registration for FDA-cleared systems entering through São Paulo's port infrastructure. The metropolitan corridor concentrates vendor service hubs and biomedical engineering talent pools.
Minas Gerais
Belo Horizonte-based hospital federations structure equipment-as-service contracts that bundle hardware, software, and maintenance. State health department procurement committees prioritize direct radiography for high-volume outpatient networks. The regional teleradiology hub connects remote municipalities to specialist interpretation centers.
Rio de Janeiro
Research institutions including Fiocruz pilot AI-enabled detection algorithms pending ANVISA classification guidance. Municipal hospitals face extended replacement cycles for legacy analog systems due to budget constraints. The state lacks the procurement scale of southeastern neighbors, fragmenting vendor service coverage.
Rio Grande do Sul
Porto Alegre's hospital networks maintain older installed bases of computed radiography systems. State-level procurement lacks centralized coordination seen in São Paulo and Minas Gerais. Southern distributors rely on fly-in technical support from São Paulo-based service teams.
Bahia
Salvador's public hospital networks represent emerging demand for digital radiography retrofit kits. Federal budget allocations for SUS infrastructure expansion target the Northeast for equipment modernization. Biomedical engineer scarcity constrains deployment timelines for complex imaging suites.
Brazil Digital Radiology Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with established service infrastructure. Siemens Healthineers anchors southeastern state contracts through localized maintenance networks, while GE Healthcare leverages assembly partnerships to reduce import-duty exposure. Fujifilm occupies a distinct position with retrofit-focused solutions for budget-constrained municipalities. Consolidation pressures favor vendors bundling hardware, software, and per-study service contracts over equipment-only suppliers.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Koninklijke Philips NV exemplify the integrated-service archetype dominating public hospital procurement. These Netherlands, German, and US-origin entities anchor long-term contracts through equipment-as-service models that transfer obsolescence risk from hospital balance sheets. Specialized players including Fujifilm Holdings Corporation and Canon Medical Systems Corporation occupy positions targeting mid-tier diagnostic chains and retrofit opportunities. The vendor mix reflects a bifurcation between scale-driven service bundlers and technology-focused specialists navigating ANVISA registration pathways.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| Agfa HealthCare |
| Carestream Health |
| Philips Healthcare Informatics |
| Others |
Pricing and Supply Chain Analysis
Flat-panel detector manufacturing automation is compressing production costs while concentrating supply among East Asian component specialists, simultaneously enabling price competition in Brazil's mid-tier diagnostic segment and tightening margins for distributors lacking direct supplier relationships. This dual dynamic reshapes how vendors structure equipment-as-service contracts versus outright purchase models.
Pricing Analysis
Per-study subscription pricing now dominates public hospital procurement in São Paulo and Minas Gerais, bundling hardware, software, maintenance, and radiologist interpretation into single operational expenditure lines. Price differentiation hinges on detector-panel resolution tiers and ANVISA registration status, with FDA-cleared systems commanding premium positioning. Cost compression in direct radiography hardware is intensifying because amorphous silicon panel oversupply from Taiwanese fabs has collapsed detector costs. Municipal facilities in northern states exhibit highest price sensitivity, while university hospitals in the Southeast prioritize AI-readiness and service infrastructure over upfront cost.
Supply Chain Analysis
Regional distribution centers in São Paulo and Rio de Janeiro anchor hub-and-spoke service networks that extend spare-part availability to Minas Gerais and Rio Grande do Sul within 48 hours. Manufacturing concentration rests on Japan, South Korea, and Germany for high-end CT gantries and MRI magnets, while flat-panel detectors draw primarily from Taiwan and South Korea. Single-source vulnerability persists for cesium iodide scintillator crystals, where Japanese suppliers control specialized crystal-growth capacity. Distribution runs through authorized distributor partnerships that absorb import-duty exposure and maintain ANVISA compliance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's digital radiology market represents a late-cycle quality story where replacement demand for legacy analog systems is shifting toward premium direct radiography specifications with embedded AI-readiness. Hospital procurement committees now weight total cost of ownership over acquisition price alone.
For Market Incumbents: Anchor long-term contracts through localized service infrastructure investments across southeastern states, particularly biomedical engineer training programs that address talent scarcity in Belo Horizonte and São Paulo corridors. Defend against retrofit-kit specialists by bundling detector-panel upgrades with software subscription tiers. Prioritize ANVISA pre-submission consultations for AI-enabled detection algorithms to secure first-mover positioning ahead of classification guidance. For New Entrants and Emerging Players: Begin with digital radiography retrofit solutions targeting budget-constrained municipal facilities in Bahia and northern states where federal SUS expansion allocations are concentrating. The white space in teleradiology hub operations connecting Amazonas remote clinics to state capital interpretation centers offers penetrable entry points. Pursue partnerships with existing PACS vendors rather than direct hospital sales to bypass incumbent service network advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized retrofit-kit manufacturers and regional distributors lacking national scale but holding ANVISA registration expertise. Long-term viability over the next decade hinges on AI-software bundling capabilities rather than hardware margins alone. Monitor ANVISA guidance publication on computer-aided detection classification as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-Service Contracting | Transfers obsolescence risk to vendors while accelerating São Paulo procurement cycles. |
| AI-Enabled Detection Software Development | Positions vendors for ANVISA classification clarity and hospital federation requirement clauses. |
| Biomedical Engineer Training Programs | Addresses specialized labor scarcity constraining deployment in northern Brazil municipalities. |
| Retrofit Kit Market Expansion | Captures federal SUS budget allocations targeting analog-to-digital migration in Northeast states. |
| Cloud-Hybrid Teleradiology Platforms | Navigates Brazil's General Data Protection Law constraints while connecting remote Amazonas clinics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, diagnostic clinic chain executives, and ANVISA regulatory affairs specialists with secondary validation against hospital procurement databases, GPO contracts, and equipment import records. Bottom-up facility-level demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Comparable-period anchoring linked historical replacement-cycle data to forward projection assumptions, with segmentation modeling across product type, end-user facility category, technology generation, and application area. CAGRs were derived from installed-base depreciation schedules and procurement pipeline visibility. Forecast inputs incorporated ANVISA registration timeline assumptions and detector-panel cost curves from East Asian supplier disclosures.
Several conditions sit outside the modeled scope, including unforeseen ANVISA regulatory delays, abrupt import-duty policy shifts, and radiologist labor strike actions affecting teleradiology hub economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Japan Computed Tomography Market