
 Global Point of Care Ultrasound Market | 2026-2036
Global Point of Care Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Global Point of Care Ultrasound Market Foresight
The EU Medical Device Regulation is realigning procurement criteria across European hospital networks, forcing manufacturers to revalidate clinical evidence packages. GE Healthcare leverages its installed base of cart-based systems to sustain service revenue streams across acute care settings. Koninklijke Philips N.V. anchors its position through R&D intensity in miniaturized transducer arrays. Siemens Healthineers competes on integrated diagnostics workflows that embed ultrasound data into enterprise imaging platforms.
Point of care ultrasound encompasses compact diagnostic imaging systems operating at frequencies between 2-15 MHz, designed for immediate clinical assessment at the patient's location without requiring dedicated radiology infrastructure. Handheld devices and portable systems command the fastest expansion trajectories as semiconductor advances shrink beam-forming electronics into pocket-sized formats. Emergency medicine and critical care applications concentrate margin pools where rapid triage decisions justify premium pricing for wireless probes and Doppler imaging capabilities.
The FDA's 510(k) clearance framework governs US market entry while the EU MDR and Japan's PMDA impose divergent clinical evidence requirements that fragment registration strategies. ISO 13485 quality management certification operates as a baseline filter for supplier qualification across all major jurisdictions. Stakeholders must monitor evolving AI-enabled diagnostic software classifications that threaten to reclassify hardware vendors as software-as-medical-device entities.
Market Dynamics
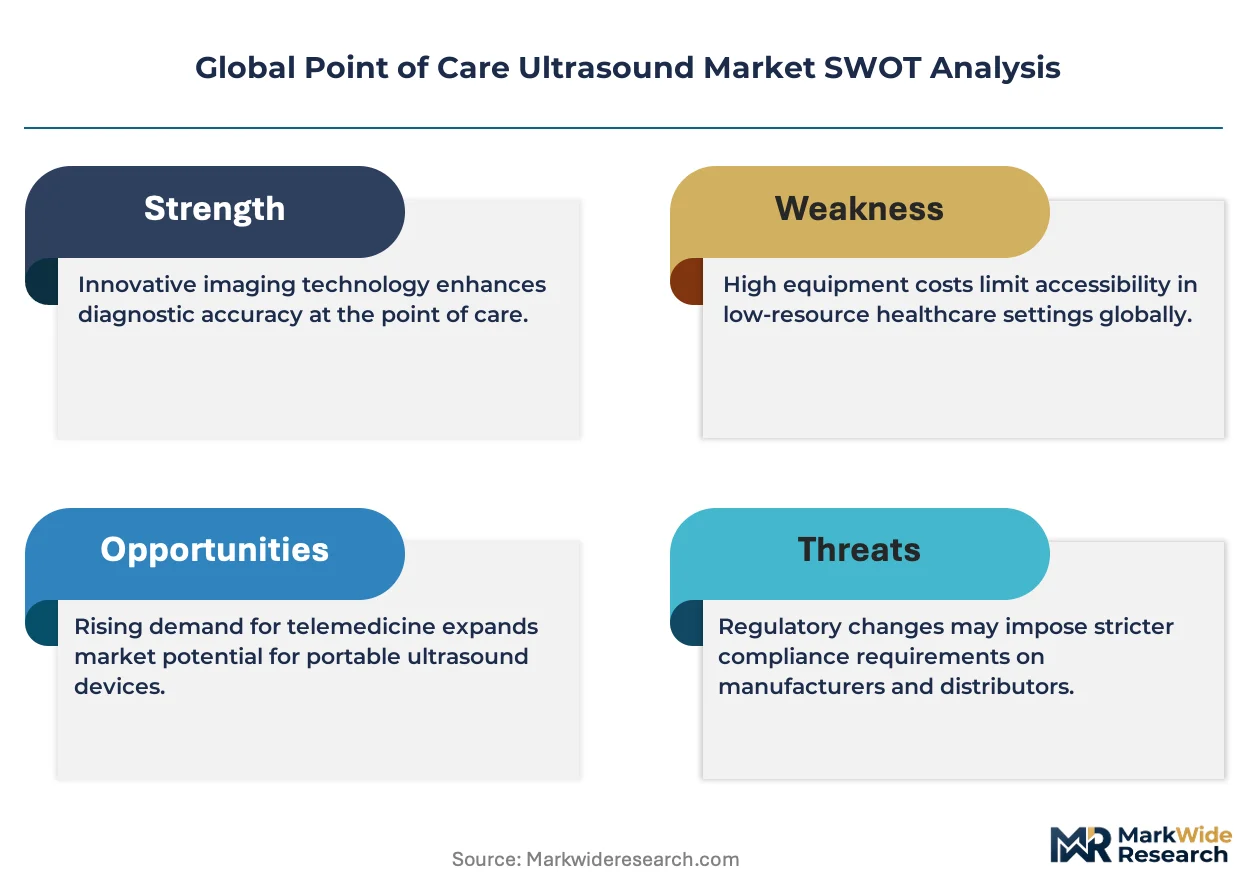
Semiconductor miniaturization is compressing beam-forming electronics into pocket-sized formats, collapsing the historical trade-off between image quality and portability that once segmented handheld and cart-based ultrasound systems.
Growth Catalysts
- Emergency medicine workflow integration:Rapid triage protocols in trauma centers now mandate bedside imaging capabilities, creating pull-through demand for wireless probe systems across hospital networks.
- EU MDR certification alignment:Tighter quality thresholds for device certification are filtering out marginal suppliers and consolidating procurement toward validated clinical evidence packages.
- Japan PMDA reimbursement pathways:Mature bedside imaging reimbursement codes in tertiary care institutions reduce total cost-of-ownership barriers for portable system adoption.
Market Restraints
- Transducer array supply concentration:Piezoelectric material processing capabilities cluster in East Asian manufacturing hubs, exposing OEMs to input cost volatility and single-source risk.
- FDA 510(k) clinical evidence requirements:Divergent evidentiary standards between US and EU regulatory frameworks fragment registration strategies and extend time-to-market for multi-jurisdictional launches.
- AI diagnostic software reclassification threat:Evolving FDA guidance on software-as-medical-device classifications risks imposing additional validation burdens on hardware vendors integrating algorithmic decision support.
Strategic Opportunities
- Rural India primary care penetration:Underpenetrated district hospital networks present white space for handheld systems operating without dedicated radiology infrastructure or specialist interpretation.
- Critical care Doppler capability expansion:Hemodynamic monitoring applications in intensive care units justify premium pricing for advanced portable systems with spectral Doppler functionality.
- ISO 13485 supplier qualification consolidation:Baseline quality management certification requirements are compressing the vendor base and creating acquisition opportunities for compliant mid-scale manufacturers.
Industry Challenges
- Sonographer training pipeline constraints:Competency certification programs for point-of-care ultrasound interpretation lag behind device deployment rates, creating utilization bottlenecks in expanded clinical settings.
- Enterprise imaging platform integration complexity:Embedding ultrasound data into hospital information systems requires API development and workflow reconfiguration that strains IT implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Point of Care Ultrasound Market |
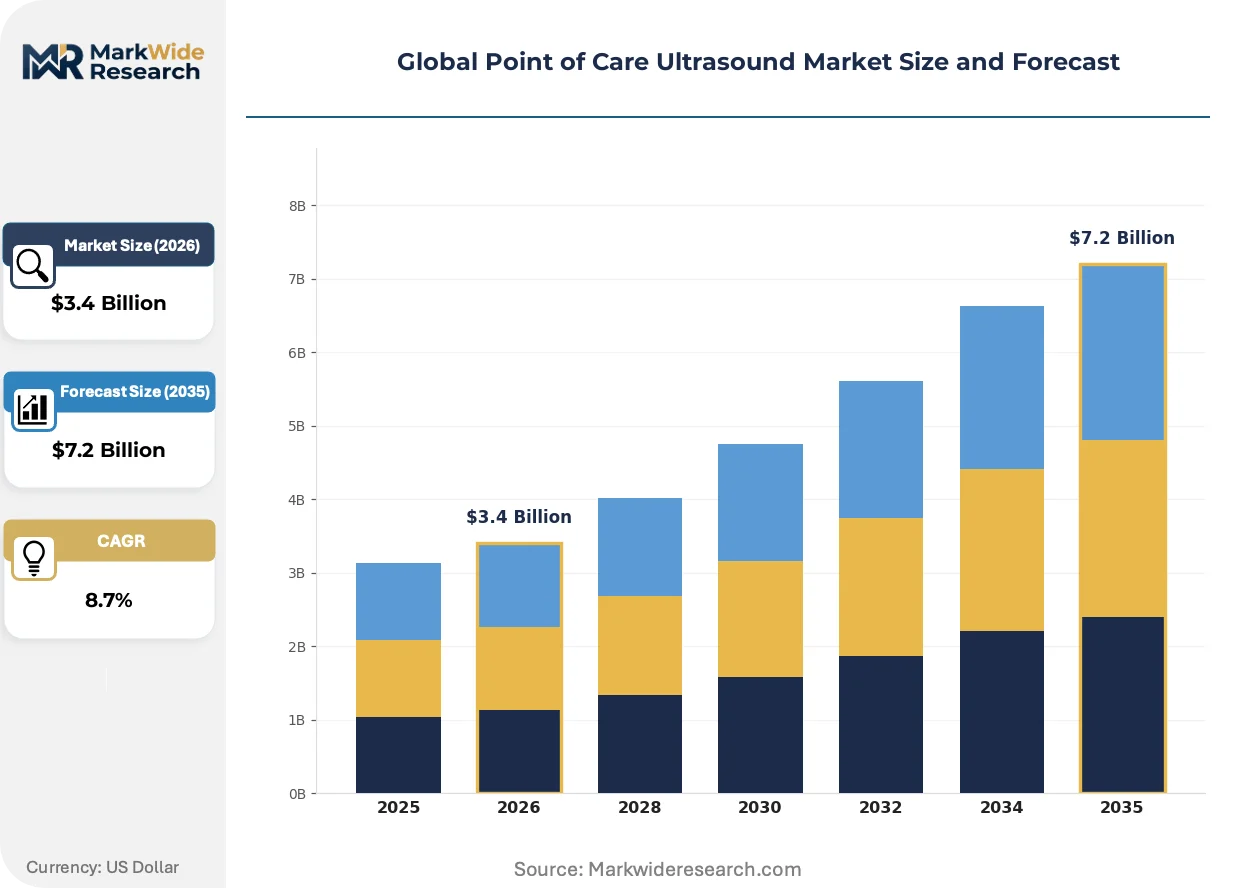
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Portable Systems, Cart-Based Units, Wearable Ultrasound, Wireless Probes Application: Emergency Medicine, Critical Care, Anesthesiology, Sports Medicine, Obstetrics & Gynecology End User: Ambulatory Care Centers, Surgical Centers, Diagnostic Laboratories, Mobile Clinics, Primary Care Providers Technology: Doppler Imaging, 3D Ultrasound, Elastography, Contrast-Enhanced Ultrasound, B-Mode Imaging |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems, Fujifilm Sonosite, Shenzhen Mindray Bio-Medical Electronics, Analogic Corporation, Esaote S.p.A., Butterfly Network, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Point of Care Ultrasound Market Shifts & Advancements
Active matrix addressing in capacitive micromachined ultrasound transducers is collapsing the cost-performance frontier, enabling diagnostic-grade imaging from semiconductor-fabricated arrays rather than precision-machined piezoelectrics.
Capacitive micromachined ultrasound transducer (CMUT) technology replaces bulk piezoelectric crystals with silicon-fabricated membranes, eliminating precision dicing and manual assembly steps. Emergency medicine departments and critical care units are piloting CMUT-based handheld systems for rapid cardiac and thoracic assessments. The technology is unifying manufacturing economics across diagnostic tiers, compressing price differentials between premium cart-based systems and entry-level portable devices.
The EU Medical Device Regulation's enhanced clinical evidence requirements are forcing manufacturers to revalidate legacy product portfolios with prospective outcome data rather than predicate device equivalence. This regulatory friction is extending certification timelines and raising R&D intensity thresholds for market participation. Japanese and US regulators are observing MDR implementation outcomes, with PMDA and FDA considering analogous evidentiary standard elevations for Class II diagnostic imaging devices.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisition, negotiating separate pricing for warranty extensions, training packages, and software maintenance. This purchasing pattern shift compresses vendor margins on initial system sales while creating competitive battlegrounds around service attach rates and renewal pricing. German hospital networks and US integrated delivery networks are most advanced in this disaggregation, with procurement teams using total cost-of-ownership models spanning five-year operational horizons.
Global Point of Care Ultrasound Market Segmentation
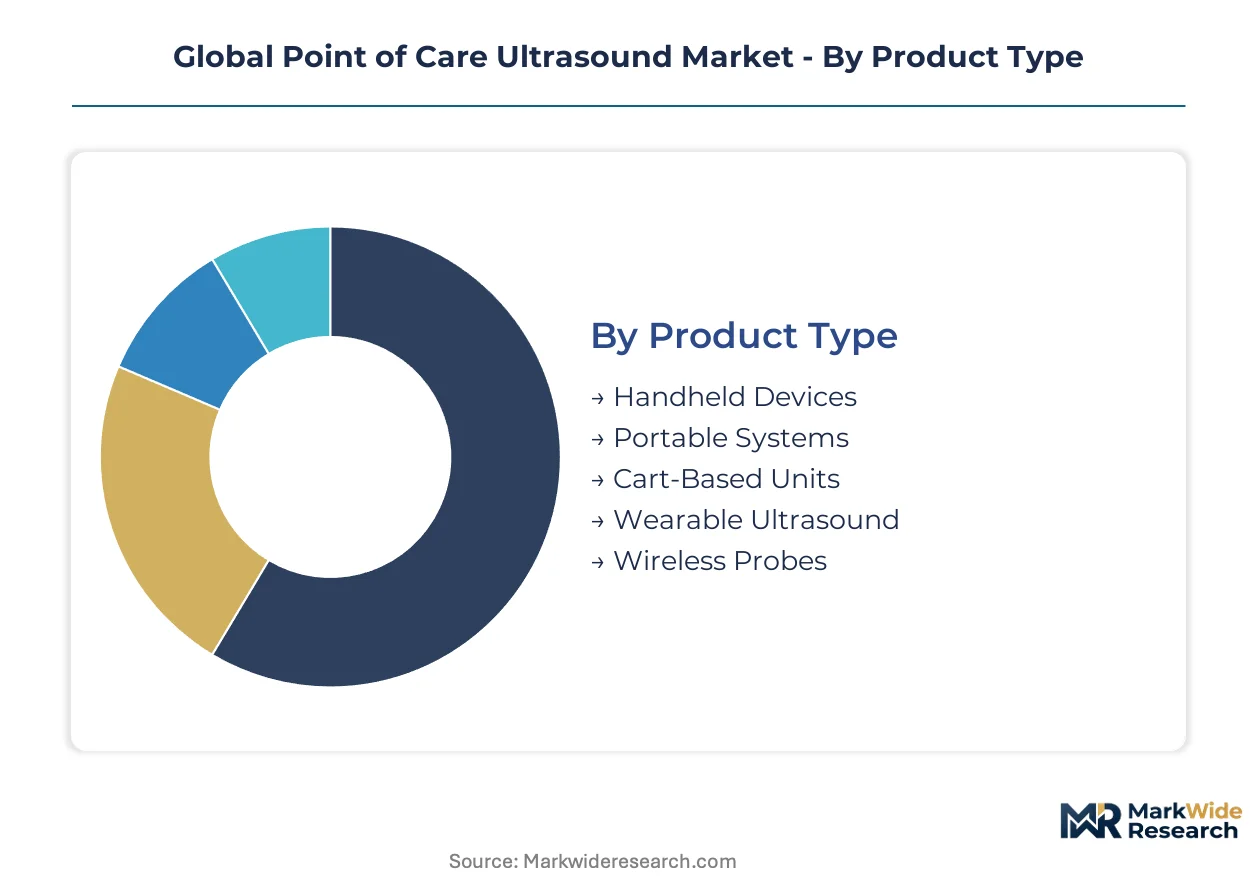
Point of care ultrasound devices fragment across multiple technical and clinical dimensions that shape procurement decisions, reimbursement pathways, and vendor competitive strategies. Semiconductor advances and regulatory divergence across FDA, EU MDR, and Japan PMDA frameworks create asymmetric growth trajectories across product tiers and application settings.
Product Type:
Replacement cycles accelerate as beam-forming electronics shrink and wireless connectivity matures, compressing the functional gap between legacy cart-based installations and emerging handheld formats.
- Handheld Devices:Pocket-sized systems operating at 2-15 MHz integrate capacitive micromachined ultrasound transducer arrays fabricated through semiconductor processes rather than precision-machined piezoelectrics. Emergency medicine departments in US trauma centers and German hospital networks deploy these for rapid cardiac and thoracic triage where radiology infrastructure is unavailable.
- Portable Systems:Mid-format devices balance image quality with mobility through advanced battery architectures and miniaturized transducer connectors. Critical care units in Japan's tertiary institutions favor these for bedside hemodynamic monitoring where PMDA reimbursement codes reduce total cost-of-ownership barriers.
- Cart-Based Units:Full-featured systems with premium transducer arrays and enterprise imaging integration capabilities dominate established radiology workflows.
- Wearable Ultrasound:Emerging form factors embed transducer arrays into garments or adhesive patches for continuous monitoring applications.
- Wireless Probes:Probe-only devices transmit imaging data to tablets or smartphones, eliminating dedicated console hardware from procurement budgets.
Volume placements concentrate in portable systems; the faster expansion belongs to handheld devices.
Application:
Clinical workflow integration requirements vary sharply across specialties, with reimbursement maturity and training infrastructure determining adoption velocity.
- Emergency Medicine:Rapid triage protocols mandate bedside imaging for trauma, chest pain, and undifferentiated hypotension presentations. US hospital networks and German emergency departments drive procurement volume where workflow integration justifies premium pricing for wireless probe systems with Doppler capabilities.
- Critical Care:Hemodynamic monitoring applications in intensive care units require spectral Doppler functionality for cardiac output assessment and fluid responsiveness evaluation. Japanese tertiary institutions lead adoption where mature bedside imaging reimbursement pathways reduce economic friction.
- Anesthesiology:Regional anesthesia and vascular access guidance represent established use cases with dedicated training curricula.
- Sports Medicine:Musculoskeletal assessment applications concentrate in specialized clinics and professional athletic organizations.
- Obstetrics & Gynecology:Limited adoption in point-of-care settings due to liability concerns and specialist referral preferences.
Emergency medicine generates the highest placement volumes; critical care applications are climbing the fastest as hemodynamic monitoring protocols expand.
End User:
Capital expenditure constraints and reimbursement pathway maturity create tiered demand patterns across care delivery settings.
- Ambulatory Care Centers:Outpatient facilities with limited radiology infrastructure deploy portable systems for same-day diagnostic completion. US integrated delivery networks and German ambulatory networks concentrate procurement where total cost-of-ownership models favor five-year operational horizons.
- Surgical Centers:Pre-operative assessment and procedural guidance applications justify dedicated system acquisition where case volume supports utilization.
- Diagnostic Laboratories:Traditional imaging centers maintain cart-based system dominance for comprehensive examination protocols.
- Mobile Clinics:Outreach and disaster response operations prioritize handheld device formats for field deployment without electrical infrastructure.
- Primary Care Providers:Rural district hospitals in underpenetrated networks present white space for handheld system penetration where specialist interpretation is unavailable.
Ambulatory care centers anchor current demand; primary care providers in rural India and similar markets are gaining share fastest as handheld technology matures.
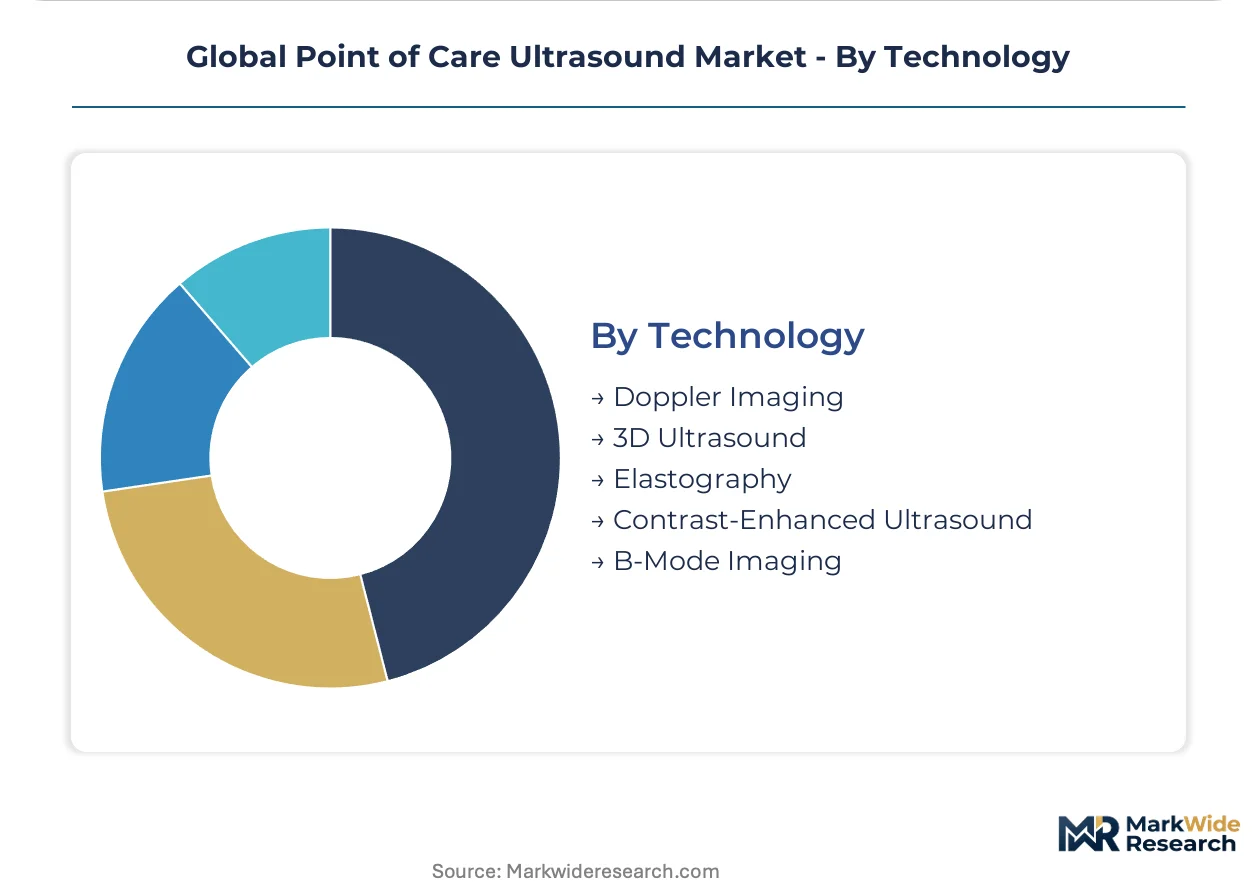
Technology:
Algorithmic enhancement and hardware miniaturization are displacing traditional imaging modalities across diagnostic tiers.
- Doppler Imaging:Spectral and color flow capabilities enable hemodynamic assessment and vascular patency evaluation without invasive monitoring. Critical care applications in US and Japanese tertiary institutions justify premium system pricing where rapid therapeutic decisions depend on real-time flow quantification.
- B-Mode Imaging:Grayscale anatomical visualization remains the foundational modality across all product tiers and clinical applications.
- 3D Ultrasound:Volume rendering capabilities concentrate in obstetric and cardiac applications where spatial relationships guide intervention planning.
- Elastography:Tissue stiffness measurement applications expand in hepatology and musculoskeletal assessment where mechanical property quantification guides diagnosis.
- Contrast-Enhanced Ultrasound:Microbubble-based perfusion imaging advances under evolving FDA and EU MDR regulatory frameworks for contrast agent approval.
B-Mode imaging dominates current installed base; Doppler capabilities are expanding most quickly as hemodynamic monitoring protocols penetrate critical care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical device corridor anchors North American point of care ultrasound innovation, while manufacturing scale concentrates in Shenzhen's electronics ecosystem and regulatory validation centers on Tokyo's tertiary hospital networks.
United States
Emergency medicine departments in US trauma centers drive handheld system procurement where rapid triage protocols mandate bedside imaging capabilities. The FDA's 510(k) clearance framework governs market entry with divergent evidentiary standards that extend registration timelines for multi-jurisdictional launches. The Boston-Cambridge medical technology cluster concentrates R&D activity for miniaturized transducer arrays and wireless probe development.
Germany
German hospital networks disaggregate after-sales service contracts from hardware acquisition, compressing vendor margins on initial system sales. The EU MDR tightens quality thresholds for device certification, filtering out marginal suppliers and consolidating procurement toward validated clinical evidence packages. The Baden-Württemberg industrial corridor hosts precision manufacturing capabilities for piezoelectric material processing.
Japan
Japanese tertiary care institutions lead critical care adoption where mature PMDA reimbursement pathways reduce total cost-of-ownership barriers for portable system deployment. The PMDA observes EU MDR implementation outcomes, considering analogous evidentiary standard elevations for Class II diagnostic imaging devices. The Tokyo-Osaka metropolitan corridor concentrates demand for spectral Doppler functionality in intensive care hemodynamic monitoring.
China
Rural district hospital networks present white space for handheld system penetration where specialist interpretation remains unavailable. The NMPA governs domestic market entry with regulatory frameworks that increasingly align with international quality management standards. Shenzhen's electronics manufacturing ecosystem supplies semiconductor-fabricated CMUT arrays and beam-forming chipsets.
India
Primary care providers in underpenetrated district hospital networks drive fastest-growing demand for handheld formats operating without dedicated radiology infrastructure. The CDSCO regulates medical device imports with evolving quality certification requirements that compress the qualified vendor base. The Karnataka-Telangana medical technology corridor emerges as a hub for affordable portable system assembly and regional distribution.
Global Point of Care Ultrasound Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with installed base leverage. Three archetypes dominate: established imaging system vendors sustaining service revenue streams, semiconductor specialists miniaturizing transducer arrays, and emerging handheld disruptors collapsing price-performance trade-offs. Consolidation pressure intensifies through ISO 13485 supplier qualification requirements and EU MDR clinical evidence revalidation burdens that favor scaled R&D investment.
Among diversified medical technology conglomerates, GE Healthcare, Koninklijke Philips N.V., and Siemens Healthineers occupy positions that exemplify distinct competitive vectors. GE Healthcare represents the installed base archetype leveraging cart-based system footprints to sustain acute care service revenues. Koninklijke Philips N.V. anchors the miniaturization specialist tier with R&D intensity in semiconductor-fabricated transducer technology. Siemens Healthineers exemplifies the integrated diagnostics workflow approach, embedding ultrasound data capture into enterprise imaging platforms that span hospital information systems.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems |
| Fujifilm Sonosite |
| Shenzhen Mindray Bio-Medical Electronics |
| Analogic Corporation |
| Esaote S.p.A. |
| Butterfly Network |
| Others |
Supply & Pricing Matrix
Captive integration into CMUT semiconductor fabrication anchors both supply security and pricing power for point of care ultrasound manufacturers, compressing cost differentials between premium cart-based systems and handheld formats while insulating compliant vendors from piezoelectric material volatility.
Pricing Analysis
Value-based pricing anchored to clinical throughput outcomes dominates procurement negotiations, with emergency medicine departments in US trauma centers and German hospital networks paying premiums for wireless probe systems with spectral Doppler capabilities. Price differentiation rests on EU MDR certification tier and after-sales service bundling, with unbundling trends compressing margins on initial hardware sales. Cost compression in handheld tiers is intensifying because CMUT semiconductor economics collapse legacy piezoelectric cost structures. Primary care providers in rural India exhibit highest price sensitivity; Japanese tertiary institutions with mature PMDA reimbursement pathways show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Tokyo, and Baden-Württemberg operate hub-and-spoke patterns for beam-forming chipsets, transducer arrays, and precision-machined components. Manufacturing concentrates in China, Japan, and Germany, drawing from piezoelectric ceramics, silicon wafers, and lithium-ion battery cells. Single-source vulnerability in East Asian piezoelectric material processing exposes OEMs to input cost volatility. Distribution runs through hospital procurement committees and GPO contracts in US integrated delivery networks, with German hospital networks advancing total cost-of-ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point of care ultrasound operates as a supply-constrained market where transducer array fabrication capacity bottlenecks prop pricing power for qualified vendors.
For Market Incumbents: Lock in service attach rates through multi-year training and software maintenance contracts that resist unbundling pressures from German hospital networks and US integrated delivery networks. Deepen backward integration into CMUT semiconductor fabrication to neutralize piezoelectric supply concentration risks. Prioritize EU MDR clinical evidence revalidation to filter marginal competitors.
For New Entrants and Emerging Players: FDA 510(k) clearance pathway in the United States opens a window for handheld disruptors targeting rural India primary care networks where specialist interpretation remains unavailable. Focus on district hospital white space with simplified B-mode imaging formats. Pursue ISO 13485 certification early to qualify for supplier consolidation opportunities.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified medical technology conglomerates seeking CMUT technology capabilities. Long-term viability favors vendors with captive semiconductor fabrication and validated clinical evidence packages under EU MDR. Watch PMDA evidentiary standard elevation signals as inflection indicator for Japanese market entry costs.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Revalidation | Filters marginal suppliers and consolidates procurement toward validated device portfolios. |
| CMUT Semiconductor Fabrication Scale-Up | Collapses cost-performance frontier between handheld and cart-based diagnostic tiers. |
| Hospital System Partnership | Secures workflow integration for emergency medicine triage protocols in US trauma centers. |
| Software Companion Development | Addresses FDA software-as-medical-device reclassification risks for algorithmic decision support. |
| Reimbursement Strategy | Unlocks PMDA pathway adoption in Japanese tertiary care institutions. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings in this study. Primary interviews with emergency medicine clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR submissions, PMDA approval records, and hospital procurement databases. Bottom-up placement estimates and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical emergency medicine adoption curves and critical care hemodynamic monitoring protocol expansion frames the projection horizon. Segmentation dimensions modeled include product format, clinical application, end-user setting, technology modality, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and penetration rate trajectories. Forecast inputs incorporate semiconductor miniaturization curves and reimbursement pathway maturity indicators.
Caveats apply where AI diagnostic software reclassification, transducer array supply disruptions, or EU MDR implementation delays could materially shift the outlook. Forecasts reflect documented assumptions on regulatory timelines and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Immunoassay Instruments Market