
 Global Medical Cameras Market | 2026-2036
Global Medical Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Cameras Market Foresight
Silicon carbide thermal substrates is decoupling from traditional ceramic heat-spreader assemblies in high-resolution surgical camera heads, reducing unit weight and improving signal fidelity during prolonged procedures. Olympus Corporation leverages captive optical foundry capacity to sustain margin structures on endoscope camera modules. Sony Corporation anchors supply security through in-house CMOS wafer fabrication for diagnostic imaging sensors. Stryker Corporation competes on integrated visualization-to-resection workflow control in arthroscopic suites.
Medical cameras are precision electro-optical instruments engineered to capture anatomical imagery across visible, infrared, and fluorescence spectra, typically resolving at 1920x1080 pixels or higher with sub-40ms latency for real-time surgical guidance. Endoscope cameras command the largest revenue pool within product type segmentation due to procedural volume in gastroenterology and urology, while 3D imaging technology captures the fastest expansion trajectory as robotic surgery platforms proliferate. CMOS technology dominates new system designs by enabling lower power draw and on-chip image processing, whereas CCD retains niche positions in fluorescence microscopy where quantum efficiency thresholds remain critical.
FDA 510(k) clearance timelines shape product launch cadences for manufacturers targeting US hospital procurement cycles, while EU MDR conformity requirements extend documentation burdens for CE-marked surgical camera systems. Japan's PMDA enforces stringent electromagnetic compatibility standards that filter non-domestic suppliers from reimbursement-eligible device categories. Stakeholders must monitor evolving ISO 13485 quality management expectations and regional cybersecurity annexes for networked imaging equipment as hospital IT integration deepens.
Market Dynamics
CMOS sensor architectures are compressing legacy CCD supply chains while FDA 510(k) clearance timelines extend product development cycles for manufacturers targeting US hospital procurement windows. This dual pressure reshapes competitive positioning across diagnostic and surgical camera segments.
Growth Catalysts
- Minimally Invasive Procedural Volume:Tertiary hospital endoscopic surgery suites in the United States, Germany, and Japan are expanding camera procurement as reimbursement frameworks favor laparoscopic and arthroscopic interventions over open surgery.
- EU MDR Conformity Requirements:Extended documentation burdens for CE-marked surgical camera systems are filtering marginal suppliers from the European market, concentrating demand among established manufacturers with regulatory infrastructure.
- Silicon Carbide Thermal Substrates:This material is decoupling from traditional ceramic heat-spreader assemblies in high-resolution surgical camera heads, reducing unit weight and improving signal fidelity during prolonged procedures.
Market Restraints
- CMOS Wafer Supply Concentration:Captive in-house fabrication at dominant sensor suppliers limits second-source options for mid-tier camera module manufacturers in Japan and South Korea.
- Fluorescence Microscopy Technical Thresholds:CCD sensors retain irreplaceable positions where quantum efficiency requirements exceed current CMOS capabilities, fragmenting R&D investment across dual technology tracks.
- Japan PMDA Electromagnetic Compatibility Standards:Stringent EMC testing protocols filter non-domestic suppliers from reimbursement-eligible device categories, creating regulatory moats around the Japanese market.
Strategic Opportunities
- India Diagnostic Imaging Expansion:CDSCO regulatory pathways for Class B and C medical devices are streamlining, opening procurement channels for mid-range endoscope cameras in tier-2 and tier-3 hospital networks.
- 3D Imaging-Robotic Surgery Convergence:Stereo vision modules are integrating with da Vinci and comparable platforms, creating premium pricing tiers for camera systems with real-time depth mapping capabilities.
- ISO 13485 Cybersecurity Annexes:Evolving quality management expectations for networked imaging equipment are creating compliance service opportunities for camera manufacturers with embedded IT security architectures.
Industry Challenges
- Multi-Spectral Image Processing Talent Scarcity:Shortages of firmware engineers capable of optimizing visible-infrared-fluorescence fusion algorithms are extending development timelines for next-generation surgical cameras.
- Legacy Hospital IT Integration Friction:PACS and EMR interoperability requirements are forcing camera manufacturers to maintain backward-compatible data formats, increasing software maintenance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Cameras Market |
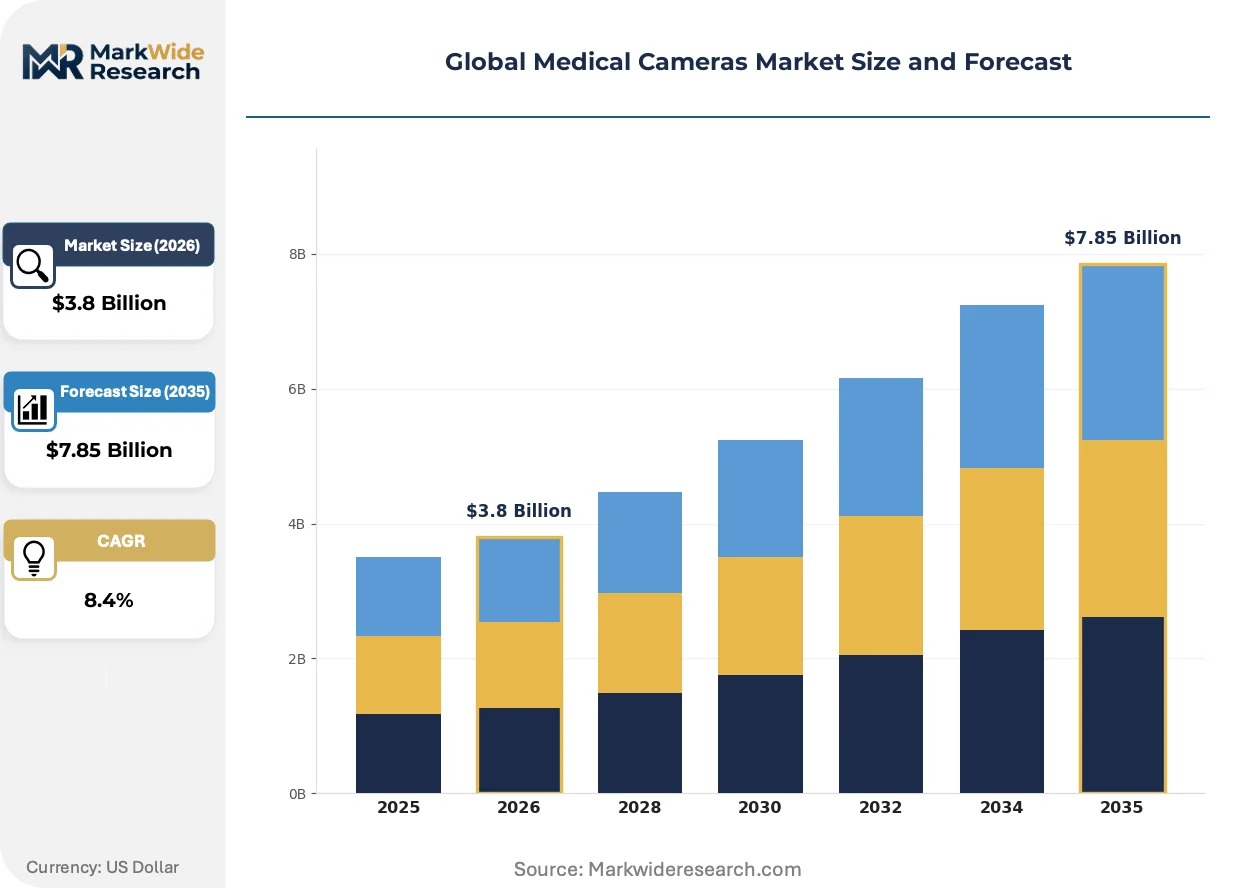
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscope Cameras, Microscope Cameras, Surgical Cameras, Diagnostic Cameras, Dental Cameras Technology: CCD, CMOS, 3D Imaging, Infrared Imaging, Fluorescence Imaging Therapy Area: Cardiology, Neurology, Gastroenterology, Dermatology, Ophthalmology End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics, Research Institutes |
| Companies Covered | Sony Corporation, Carl Zeiss AG, Olympus Corporation, Danaher, TOPCON Corporation, Stryker Corporation, Canon Inc., Smith & Nephew, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Cameras Market Shifts & Advancements
Computational imaging pipelines and on-chip AI processing are redefining performance benchmarks for medical cameras, shifting competitive advantage from optical hardware to embedded software architectures.
Deep learning-based image enhancement is integrating into CMOS sensor die designs, enabling real-time noise reduction and edge sharpening without external processing hardware. Tertiary hospital radiology departments in Germany and the United States are piloting these modules for low-light endoscopic procedures. This integration is compressing the traditional separation between sensor fabrication and image processing subsystems.
EU MDR post-market surveillance requirements are extending clinical evidence obligations for surgical camera systems beyond initial CE marking, forcing manufacturers to maintain longitudinal safety databases. This regulatory expansion is elevating compliance costs for mid-cap suppliers without established post-market infrastructure. High-risk Class III camera categories face the steepest documentation burdens, with notified bodies in Germany and the Netherlands extending review timelines.
Hospital procurement committees are consolidating vendor relationships around integrated visualization-to-resection workflow platforms rather than standalone camera hardware. This bundling preference is displacing point-product suppliers in arthroscopic and laparoscopic suites across US academic medical centers. The shift is most visible in multi-hospital health systems pursuing standardization across affiliated surgical facilities.
Global Medical Cameras Market Segmentation
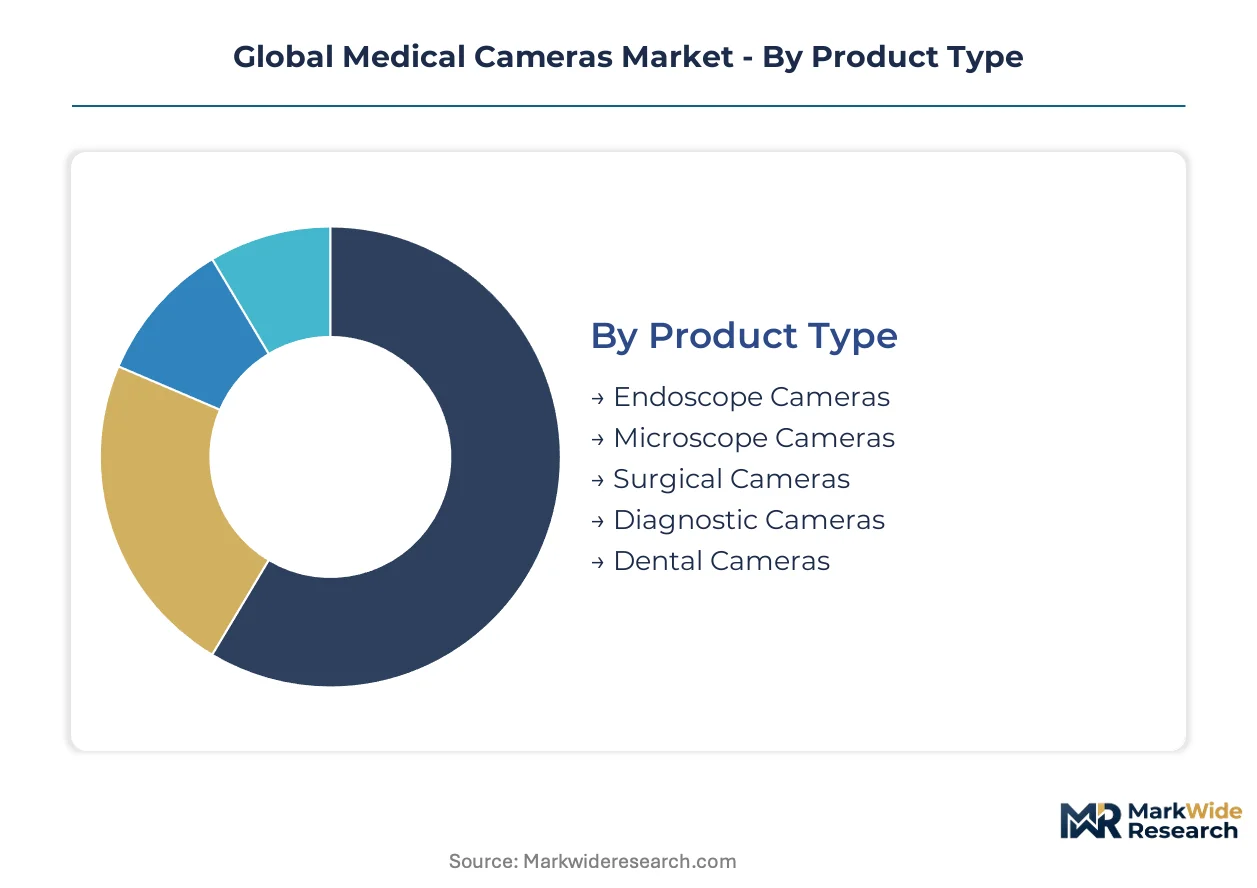
Medical camera procurement decisions hinge on procedural specificity, spectral requirements, and integration depth with surgical workflows. Each segmentation dimension reveals distinct buyer priorities across tertiary hospital systems and specialized care facilities.
Product Type:
Hospital procurement committees prioritize imaging fidelity and sterilization compatibility when selecting camera hardware for integrated surgical suites.
- Endoscope Cameras:These fiber-optic or chip-on-tip systems transmit visual data through narrow insertion tubes, resolving at 1920x1080 pixels or higher for gastroenterology and urology procedures. Demand concentrates in United States academic medical centers where laparoscopic volume drives replacement cycles. CMOS sensor migration is compressing unit costs while maintaining quantum efficiency thresholds.
- Surgical Cameras:Head-mounted and boom-suspended configurations capture open-field anatomy with sub-40ms latency for real-time guidance. German hospital procurement favors these systems in arthroscopic suites where visualization-to-resection workflow integration determines vendor selection. Silicon carbide thermal substrates are displacing ceramic heat-spreaders to reduce head weight.
- Microscope Cameras:C-mount adapters integrate with optical pathology workstations for histological documentation.
- Diagnostic Cameras:Portable configurations serve dermatology and wound care applications in outpatient settings.
- Dental Cameras:Intraoral variants prioritize moisture resistance and LED ring illumination for chairside imaging.
Volume sits with Endoscope Cameras; growth tilts toward Surgical Cameras.
Technology:
Sensor architecture selection determines power budgets, thermal profiles, and signal processing requirements for specific clinical applications.
- CMOS:Complementary metal-oxide-semiconductor designs enable on-chip analog-to-digital conversion and lower power draw than legacy alternatives. Sony Corporation's captive wafer fabrication secures supply for diagnostic imaging platforms across Japan and South Korea. Deep learning integration into sensor die designs permits real-time noise reduction without external hardware.
- 3D Imaging:Stereo vision modules with dual-lens configurations generate depth-mapped anatomical models for robotic surgery platforms. United States health systems with da Vinci installations drive premium pricing tiers for these systems. Real-time depth mapping capabilities differentiate vendors in multi-hospital standardization initiatives.
- CCD:Charge-coupled devices retain dominance in fluorescence microscopy where quantum efficiency thresholds exceed current CMOS capabilities.
- Infrared Imaging:Near-infrared spectra support perfusion assessment and tissue oxygenation monitoring in cardiovascular applications.
- Fluorescence Imaging:Indocyanine green and similar contrast agents require specialized excitation-emission synchronization.
Procurement volume favors CMOS architectures; 3D Imaging captures the steepest expansion trajectory as robotic platforms proliferate.
Therapy Area:
Clinical application dictates spectral range, resolution requirements, and regulatory classification for camera system deployment.
- Gastroenterology:Colonoscopy and upper endoscopy procedures generate the highest camera utilization rates per installed base. Japanese hospital networks under PMDA reimbursement frameworks prioritize high-definition white-light and narrow-band imaging capabilities. Olympus Corporation leverages captive optical foundry capacity to sustain margin structures in this segment.
- Cardiology:Intravascular ultrasound and optical coherence tomography demand miniaturized distal sensors for coronary catheterization. German interventional cardiology departments favor integrated imaging-to-intervention workflows. Fluorescence angiography capabilities are displacing standalone systems in hybrid operating rooms.
- Neurology:Surgical microscopes with integrated camera heads document neurovascular and tumor resection procedures.
- Dermatology:Dermoscopy systems with polarized light and digital dermoscopy mapping support melanoma screening protocols.
- Ophthalmology:Fundus cameras and slit-lamp adapters require specialized optics for retinal and anterior segment examination.
Procedure volume concentrates in Gastroenterology; Cardiology exhibits the fastest technology refresh cycles.
End User:
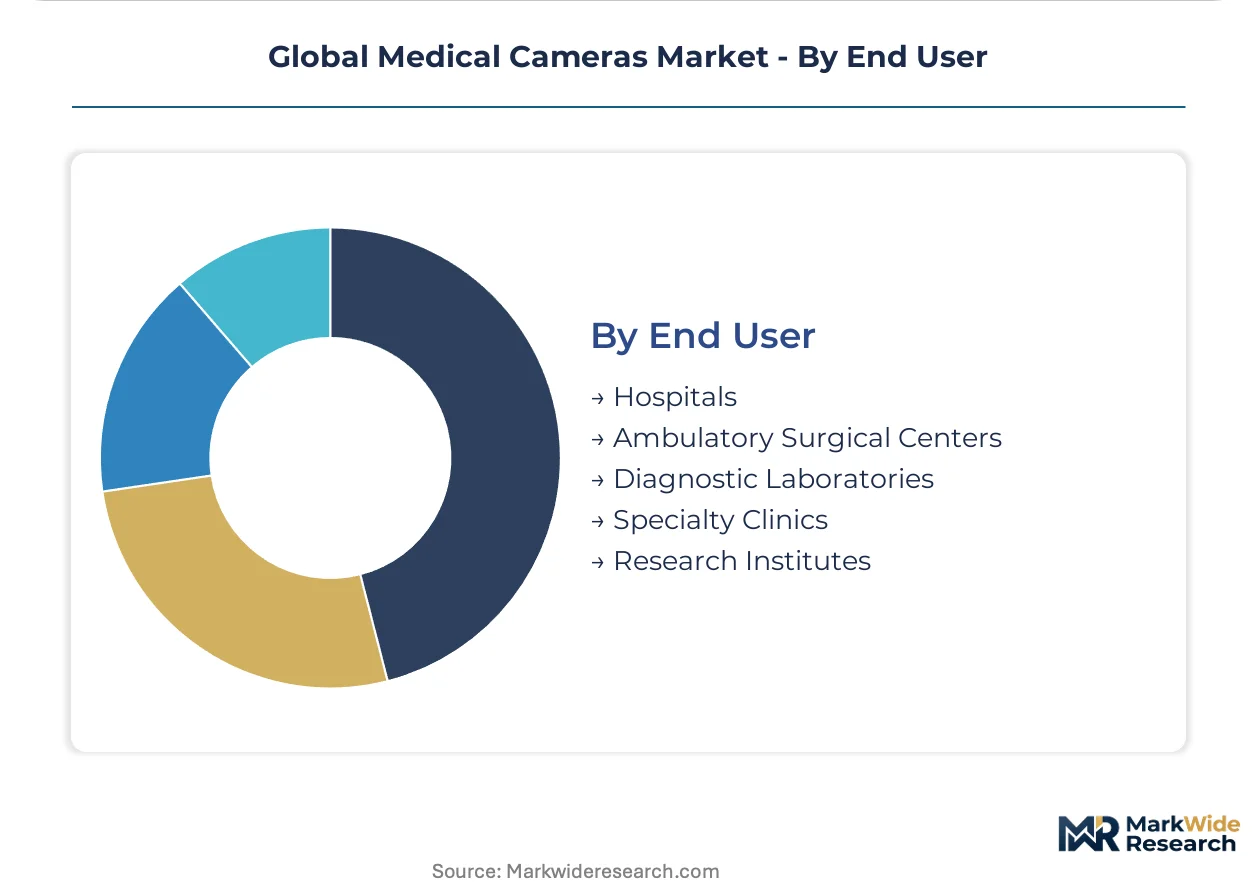
Facility type determines capital allocation thresholds, utilization intensity, and vendor relationship structures for camera acquisition.
- Hospitals:Tertiary and quaternary centers with endoscopic surgery suites command the largest procurement budgets and longest replacement cycles. United States academic medical centers consolidate vendor relationships around integrated visualization platforms rather than standalone hardware. FDA 510(k) clearance timelines shape product launch cadences for manufacturers targeting these buyers.
- Ambulatory Surgical Centers:Freestanding facilities prioritize capital efficiency and rapid turnover compatibility for high-volume arthroscopic and laparoscopic procedures. German and Japanese reimbursement frameworks favor minimally invasive interventions in these settings. Compact camera heads with streamlined sterilization protocols gain preference.
- Diagnostic Laboratories:Pathology workstations require color-calibrated microscopy cameras for histological documentation.
- Specialty Clinics:Dermatology and ophthalmology practices favor portable configurations for point-of-care imaging.
- Research Institutes:Preclinical and clinical trial applications demand spectral flexibility and raw data output capabilities.
Capital deployment concentrates in Hospitals; Ambulatory Surgical Centers are gaining share fastest as procedural volume shifts to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers command the largest procurement budgets for endoscopic surgery suites, while German and Japanese hospital networks filter vendor selection through distinct reimbursement and regulatory frameworks. CMOS sensor supply chains concentrate fabrication in East Asia, yet demand-side purchasing decisions remain anchored in North American and Western European tertiary care facilities.
United States
FDA 510(k) clearance timelines shape product launch cadences for manufacturers targeting hospital procurement cycles in academic medical centers. Reimbursement frameworks through CMS favor minimally invasive procedural volumes, expanding camera replacement cycles in laparoscopic and arthroscopic suites. The Cleveland Clinic and Mayo Clinic networks consolidate vendor relationships around integrated visualization-to-resection workflow platforms.
Germany
EU MDR conformity requirements extend documentation burdens for CE-marked surgical camera systems, filtering marginal suppliers from procurement channels. Notified bodies in Germany and the Netherlands extend review timelines for high-risk Class III camera categories, elevating compliance costs. The Stuttgart and Munich metropolitan clusters anchor endoscope camera module assembly operations serving continental European hospital networks.
Japan
PMDA electromagnetic compatibility standards enforce stringent testing protocols that filter non-domestic suppliers from reimbursement-eligible device categories. METI industrial policy supports captive CMOS wafer fabrication capacity for diagnostic imaging sensors. The Tokyo-Yokohama and Osaka-Kobe corridors concentrate optical foundry operations and sensor module integration facilities.
India
CDSCO regulatory pathways for Class B and C medical devices are streamlining, opening procurement channels for mid-range endoscope cameras in tier-2 and tier-3 hospital networks. Government health insurance expansion through Ayushman Bharat drives diagnostic imaging infrastructure deployment. The Maharashtra and Karnataka state clusters host assembly operations for surgical camera heads serving domestic and export markets.
South Korea
MFDS medical device approval frameworks align with international harmonization initiatives, accelerating market access for CMOS-based diagnostic platforms. National health insurance reimbursement rates for endoscopic procedures sustain replacement demand in Seoul metropolitan hospital networks. The Suwon and Gwangju industrial corridors concentrate sensor packaging and camera module subassembly operations.
Global Medical Cameras Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies commanding surgical suite procurement while component suppliers anchor diagnostic imaging supply chains. The vendor base organizes around three strategic archetypes: captive sensor fabricators with in-house wafer capacity, optical system integrators leveraging foundry partnerships, and workflow platform vendors bundling hardware with surgical navigation software. Dominant competitive moves include backward integration into CMOS wafer fabrication and strategic partnerships with robotic surgery platform developers.
Among Japanese-headquartered sensor specialists, Sony Corporation exemplifies the captive fabrication archetype through in-house CMOS wafer operations. Olympus Corporation occupies a position within the optical system integrator tier, leveraging endoscope manufacturing heritage. Stryker Corporation represents the workflow platform archetype, competing on visualization-to-resection integration in arthroscopic suites.
| Leading Market Players |
|---|
| Sony Corporation |
| Carl Zeiss AG |
| Olympus Corporation |
| Danaher |
| TOPCON Corporation |
| Stryker Corporation |
| Canon Inc. |
| Smith & Nephew |
| Richard Wolf GmbH |
| Others |
Supply & Pricing Matrix
Academic medical center procurement committees in the United States, Germany, and Japan command pricing power through consolidated vendor relationships around integrated visualization platforms. Three-tier pricing structure across premium, standard, and economy levels reflects sensor architecture, regulatory certification tier, and workflow integration depth.
Pricing Analysis
High-volume endoscope camera modules compete on unit economics while 3D stereo vision systems for robotic surgery platforms sustain premium positioning. Price differentiation hinges on FDA 510(k) clearance tier and CMOS wafer fabrication source. Cost compression in mid-tier diagnostic cameras is intensifying because Sony Corporation's captive supply limits second-source options. Ambulatory surgical centers exhibit highest price sensitivity; tertiary hospitals with bundled workflow contracts show lowest.
Supply Chain Analysis
Japan's METI industrial policy and local-content preferences for PMDA-reimbursed devices are reshaping sourcing patterns for electromagnetic compatibility-certified components. CMOS sensor fabrication concentrates in Japan, South Korea, and Taiwan; optical foundry operations for endoscope modules anchor in Germany and Japan. Raw material dependencies include silicon carbide thermal substrates, specialized optical glass, and indium tin oxide coatings. Single-source vulnerability around Sony's captive wafer capacity threatens mid-tier camera module manufacturers. Distribution runs through hospital GPO contracts, specialized medical device distributors, and direct OEM relationships with robotic surgery platform developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMOS sensor architectures are displacing legacy CCD across diagnostic and surgical platforms, compressing development timelines for manufacturers maintaining dual technology tracks.
For Market Incumbents: Cement supply security through backward integration into CMOS wafer fabrication or exclusive foundry partnerships. Deepen regulatory infrastructure investment to navigate extended EU MDR review timelines for Class III camera categories. Threat of emerging workflow platform vendors bundling hardware with surgical navigation software demands defensive consolidation around integrated visualization-to-resection offerings. For New Entrants and Emerging Players: The gap between premium robotic surgery camera systems and economy-tier diagnostic cameras offers white-space entry. Target India's tier-2 and tier-3 hospital networks where CDSCO regulatory streamlining opens procurement channels for mid-range endoscope cameras. Go-to-market through government health insurance expansion programs like Ayushman Bharat minimizes direct sales infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors optical system integrators with endoscope manufacturing heritage and established CE marking infrastructure. Long-term viability rests on post-market surveillance capabilities under evolving EU MDR requirements. Watch FDA 510(k) clearance velocity for next-generation CMOS-based surgical cameras as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates hospital procurement cycles in United States academic medical centers. |
| CE Marking Pathway | Unlocks access to German and Dutch hospital networks under EU MDR. |
| Hospital System Partnership | Enables bundled visualization-to-resection workflow platform deployment. |
| Software Companion Development | Supports real-time AI image enhancement on CMOS sensor die designs. |
| Reimbursement Strategy | Secures PMDA eligibility in Japan's electromagnetic compatibility-filtered categories. |
Research Methodology
FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases formed the secondary backbone. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors at sensor manufacturers combined with secondary validation. Bottom-up and top-down triangulation anchored market size estimates.
Bottom-up modeling of installed base, replacement cycles, and average selling prices across product type, technology, therapy area, and end user segments fed into top-down cross-checks against healthcare capital equipment spending patterns. CAGRs were derived from procedure volume trajectories and technology refresh timelines. Inputs included minimally invasive surgical adoption curves, robotic surgery platform deployment rates, and CMOS sensor migration patterns.
Inputs from regulatory filings and hospital procurement systems were available through the study window; gaps in real-time inventory data and confidential contract pricing introduce uncertainty bands around average selling price assumptions. Forecasts reflect documented assumptions about reimbursement framework stability and technology transition velocity. Sensor supply concentration and regulatory review timeline extension represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market