
 Eye Melanoma Market | 2026-2036
Eye Melanoma Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Melanoma Market Analysis
Adjuvant therapy revenue is rewriting profit distribution across the Eye Melanoma Market, pulling margins from surgical intervention toward pharmaceutical maintenance protocols. Merck & Co., Inc. leverages its checkpoint inhibitor portfolio to anchor position in metastatic disease management. F. Hoffmann-La Roche Ltd sustains R&D intensity across ocular oncology biomarkers. Novartis AG dominates targeted therapy development for GNAQ/GNA11-mutant tumors.
Eye melanoma comprises malignant neoplasms arising from melanocytes within the uveal tract, choroid, ciliary body, or iris, with primary treatment goals encompassing globe preservation, vision retention, and metastatic risk reduction. Surgical procedures retain the largest share by product type, though immunotherapy captures the fastest expansion as tebentafusp and similar agents redefine metastatic treatment paradigms. By treatment method, plaque brachytherapy leads localized disease management while enucleation occupies a narrowing but persistent role for large, vision-compromising tumors.
FDA orphan drug designations and EMA priority medicines pathways compress development timelines for uveal melanoma therapies, while NMPA reforms in China accelerate market entry for innovative ocular oncology drugs. The EU AI Act and FDA guidance on artificial intelligence in radiology are reshaping diagnostic imaging standards for early lesion detection. Stakeholders must monitor regulatory convergence across FDA, EMA, and PMDA frameworks as biomarker-driven trial designs become the gatekeeper for accelerated approvals.
Market Dynamics
The Eye Melanoma Market pivots on biomarker-driven trial designs that compress regulatory timelines and redirect investment from surgical hardware toward pharmaceutical maintenance protocols.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses development timelines for rare cancer indications, enabling faster commercialization of novel immunotherapies in uveal melanoma.
- EMA Priority Medicines:This designation streamlines access for innovative ocular oncology drugs across European markets, reducing time-to-reimbursement.
- AI-Assisted Diagnostics:Machine learning algorithms embedded in ophthalmology workflows are shortening time-to-diagnosis and expanding screening reach in specialized ocular oncology centers.
Market Restraints
- Specialized Infrastructure:Plaque brachytherapy requires dedicated radiation oncology-ophthalmology coordination that concentrates in urban academic medical centers, limiting geographic access.
- Clinical Trial Complexity:Small patient populations and GNAQ/GNA11 mutation stratification requirements extend enrollment timelines and inflate per-patient study costs.
- Reimbursement Fragmentation:Divergent coding practices across Medicare, Medicaid, and commercial payers create administrative friction for novel adjuvant therapies.
Strategic Opportunities
- Companion Diagnostic Integration:Pairing targeted therapies with validated biomarker tests opens premium pricing tiers and streamlines payer negotiations.
- Home-Based Monitoring:Teleophthalmology platforms enable remote surveillance of treated lesions, reducing visit burden and expanding addressable patient pools in rural geographies.
- Real-World Evidence Programs:Post-market registries mandated by EMA and FDA generate durable competitive moats through longitudinal outcome data.
Industry Challenges
- Ocular Oncology Workforce:Fellowship-trained specialists remain concentrated in fewer than fifty academic centers across the United States, Germany, and Japan, creating patient access bottlenecks.
- Cold Chain Logistics:Temperature-sensitive biologics require specialized distribution networks that fragment supply chain control and inflate last-mile costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Melanoma Market |
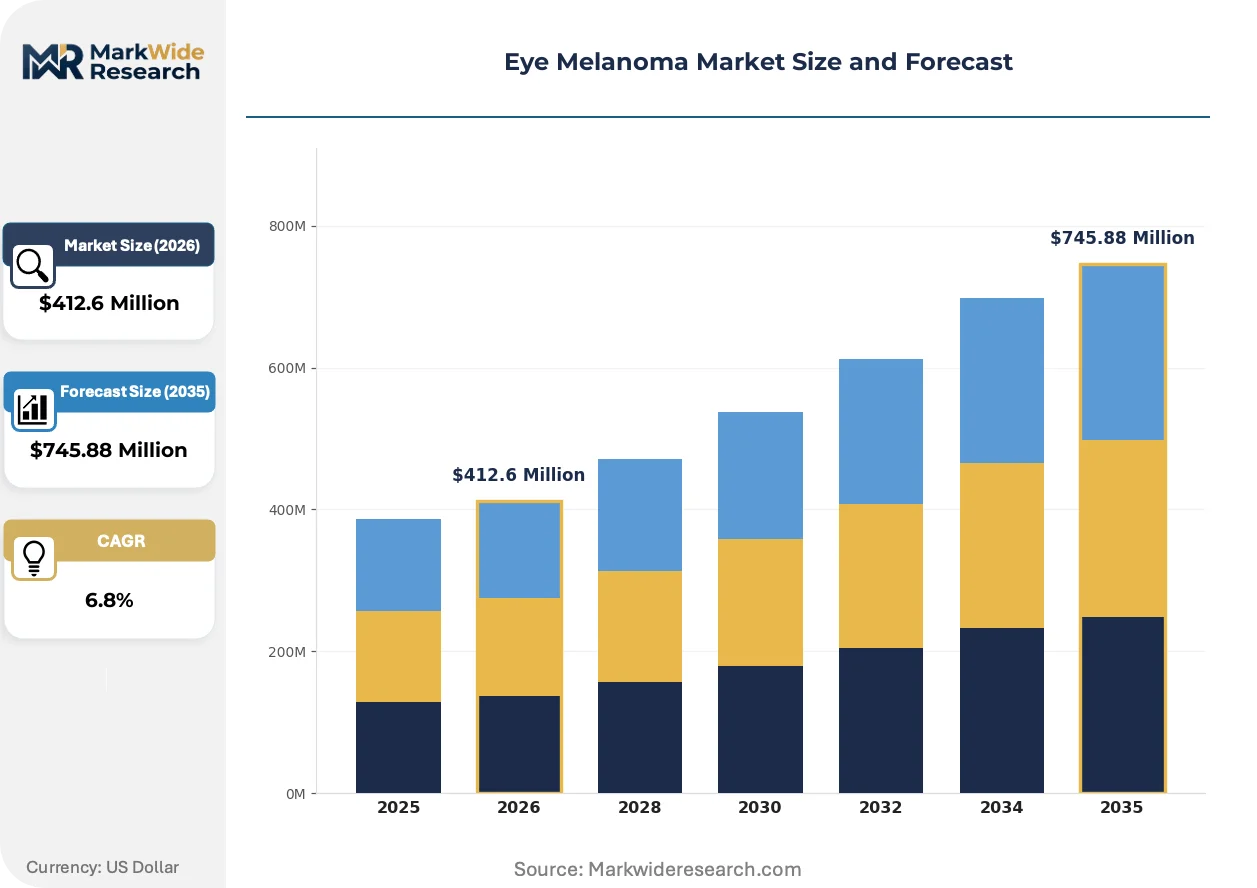
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Procedures, Radiation Therapy, Chemotherapy, Immunotherapy End User: Ophthalmology Clinics, Hospitals, Research Institutions, Ambulance Services Treatment Method: Laser Treatment, Cryotherapy, Enucleation, Plaque Brachytherapy Stage: Localized Stage, Advanced Stage, Recurrent Stage, Metastatic Stage |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, AbbVie Inc., Amgen Inc., AstraZeneca, Immunocore Holdings plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Melanoma Market Emerging Trajectories
Treatment paradigms in ocular oncology are converging on precision medicine frameworks that link genomic stratification to therapy selection, compressing the gap between diagnostic confirmation and targeted intervention.
Tebentafusp, a bispecific T-cell engager, is hybridizing metastatic uveal melanoma management by bridging gp100 peptide presentation with CD3 T-cell recruitment. Academic medical centers in the United States and Germany are adopting this agent as first-line standard, displacing conventional chemotherapy regimens. The technology is compressing median overall survival benchmarks and forcing surgical centers to build in-house immuno-oncology capabilities.
The EU AI Act imposes conformity assessment requirements on diagnostic algorithms that classify ocular lesions from fundus photography and optical coherence tomography. Device manufacturers must now document clinical validation across diverse populations before CE marking. Ophthalmology clinics in France and Germany are prioritizing vendors with pre-certified AI modules to accelerate procurement cycles.
Consolidated buying by integrated delivery networks is compressing vendor margins and favoring suppliers offering bundled diagnostic-therapy packages. Large hospital systems in the United States are negotiating multi-year contracts spanning imaging equipment, molecular testing, and pharmaceutical access. This procurement compression is most visible in California and Texas, where dominant health systems command substantial patient volume leverage.
Eye Melanoma Market Segmentation
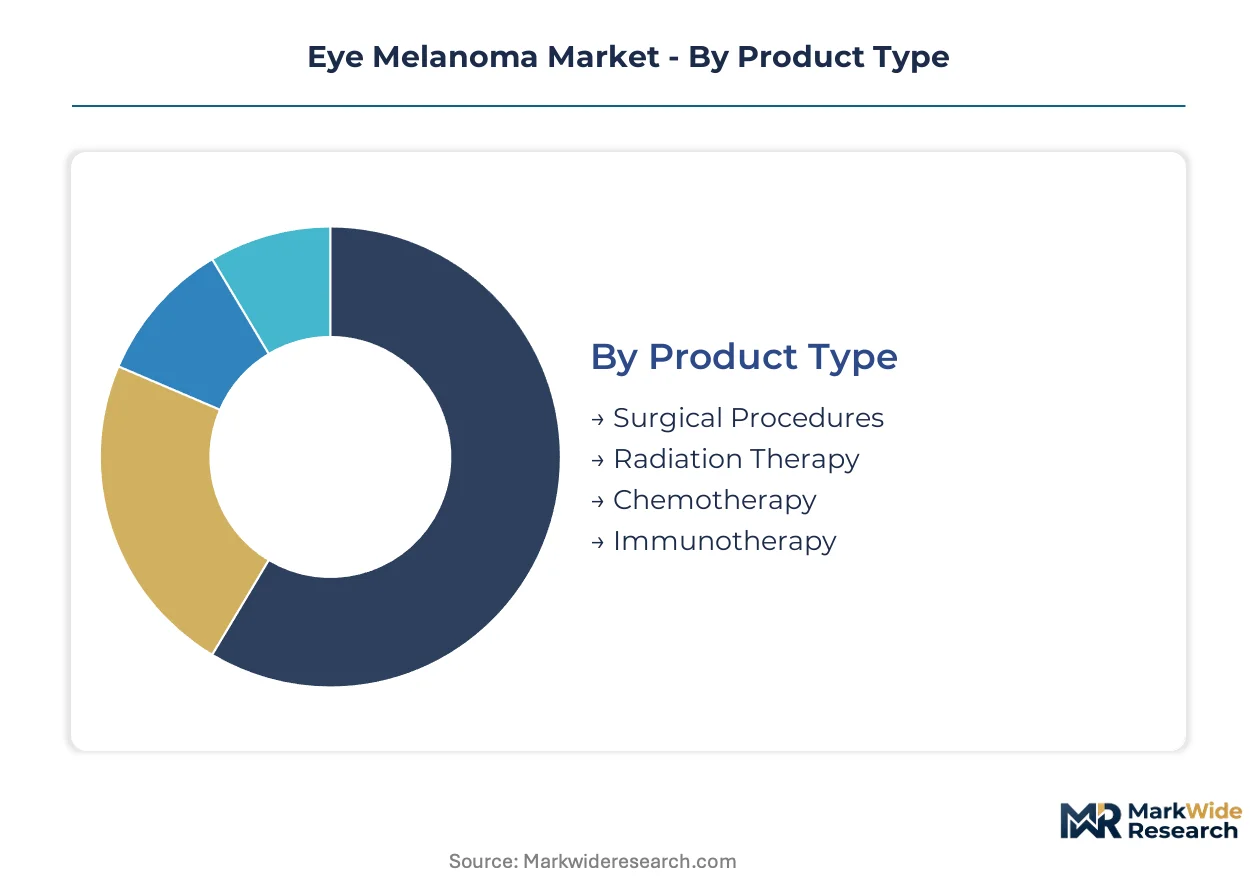
Segmentation in the Eye Melanoma Market reflects divergent clinical priorities across globe preservation, metastatic risk reduction, and vision retention. Treatment modality selection hinges on tumor size, anatomical location, and GNAQ/GNA11 mutation status, creating distinct demand pools for surgical, radiological, and pharmaceutical interventions.
Product Type:
Cost tier stratification separates high-acuity surgical and radiation interventions from pharmaceutical maintenance protocols in uveal melanoma management.
- Surgical Procedures:Enucleation, local resection, and exenteration procedures remove tumor tissue while preserving orbital anatomy when feasible. Academic medical centers in the United States and Germany concentrate demand for globe-sparing surgical techniques. Reimbursement complexity across Medicare and commercial payers constrains adoption in community settings.
- Radiation Therapy:Plaque brachytherapy and proton beam irradiation deliver targeted dose deposition with tissue-sparing precision. Specialized ocular oncology centers in Japan and the United States deploy these modalities for medium-sized choroidal lesions. Capital equipment requirements and radiation oncology-ophthalmology coordination limit geographic penetration.
- Chemotherapy:Systemic cytotoxic regimens occupy a narrowing role in metastatic disease management as immunotherapy displaces first-line protocols. Academic centers in Germany retain limited chemotherapy capacity for salvage indications.
- Immunotherapy:Checkpoint inhibitors and bispecific T-cell engagers are redefining metastatic uveal melanoma standards. FDA accelerated approval pathways compress development timelines for novel agents targeting gp100 and HLA-A*02:01.
Surgical Procedures command the established base. The steepest expansion runs through Immunotherapy.
End User:
Application concentration varies across institutional capabilities, with complex interventions clustering in academic centers and follow-up care dispersing to community settings.
- Ophthalmology Clinics:Specialized ocular oncology practices in the United States, Germany, and Japan perform diagnostic confirmation, treatment planning, and longitudinal surveillance. Tebentafusp administration and plaque brachytherapy coordination require fellowship-trained specialists concentrated in fewer than fifty academic centers.
- Hospitals:Integrated delivery networks in California and Texas negotiate bundled contracts spanning imaging, molecular testing, and pharmaceutical access. Consolidated procurement compresses vendor margins while favoring suppliers offering diagnostic-therapy packages.
- Research Institutions:Biomarker-driven trial designs and real-world evidence generation concentrate in National Cancer Institute-designated centers. EMA and FDA post-market registry mandates create durable competitive moats through longitudinal outcome data.
- Ambulance Services:Emergency transport plays a limited role in this elective oncology indication, with occasional deployment for acute complications requiring tertiary center transfer.
Hospitals anchor the revenue base. Ophthalmology Clinics capture the fastest volume gains.
Treatment Method:
Volume distribution reflects tumor size and anatomical location, with minimally invasive modalities dominating small lesions and radical surgery persisting for advanced disease.
- Laser Treatment:Transpupillary thermotherapy and photocoagulation ablate small iris and posterior segment lesions. Community ophthalmology practices in the United States deploy these modalities for early-stage disease with low metastatic potential.
- Cryotherapy:Trans-scleral freezing destroys ciliary body and anterior choroidal tumors. Limited adoption reflects narrow indications and vision-compromising side effect profiles.
- Enucleation:Radical globe removal remains necessary for large, vision-compromising tumors exceeding brachytherapy size limits. Urban academic centers in Germany and Japan perform these procedures with integrated orbital implant reconstruction.
- Plaque Brachytherapy:Iodine-125 and ruthenium-106 plaques deliver conformal radiation for medium-sized choroidal melanomas. Specialized infrastructure requirements concentrate delivery in radiation oncology-ophthalmology coordinated centers.
Plaque Brachytherapy commands the established base. Laser Treatment shows the steepest expansion trajectory.
Stage:
Customer type stratification separates curative-intent localized disease management from chronic metastatic protocols, with profound implications for pricing power and treatment duration.
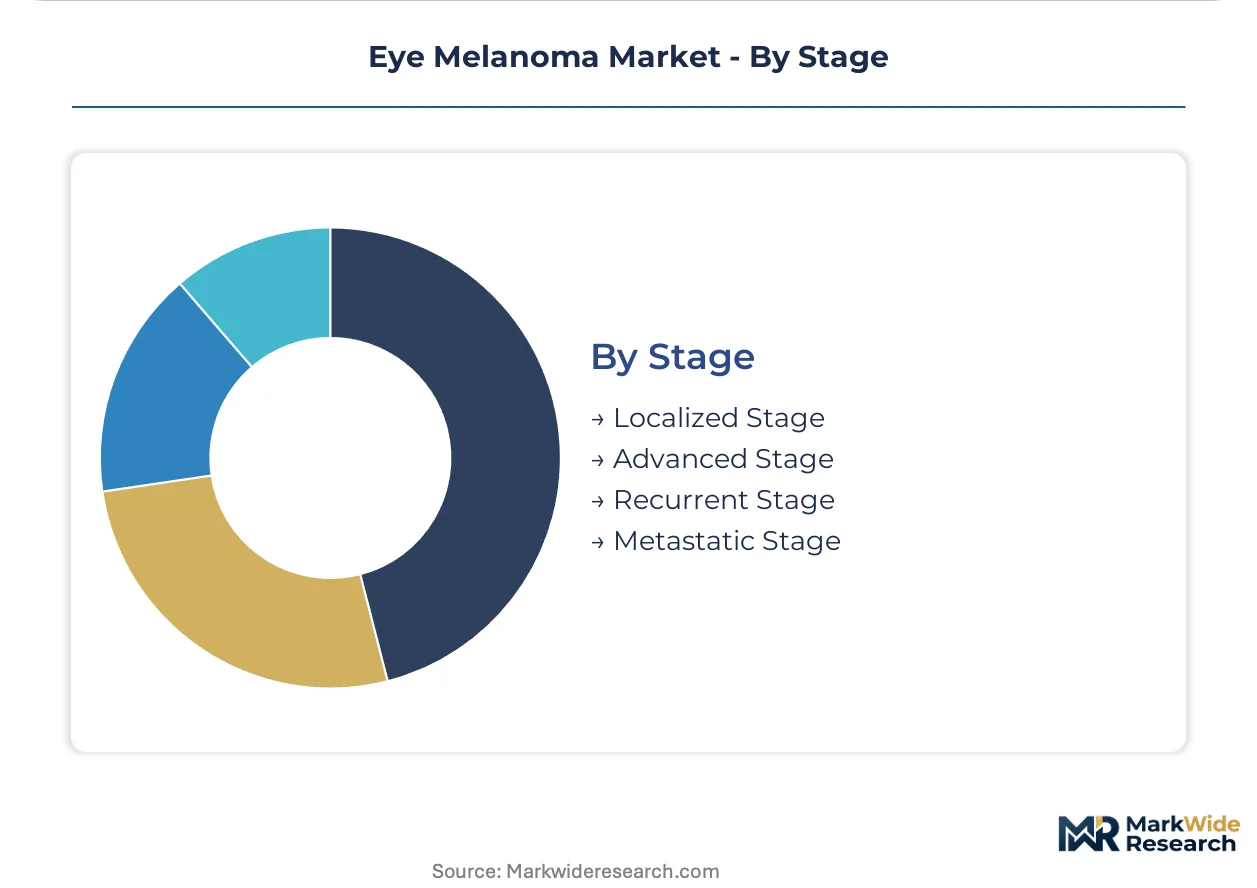
- Localized Stage:Small to medium uveal melanomas confined to the globe drive demand for globe-preserving radiation and laser modalities. Early detection programs in Japan and Germany expand the addressable pool.
- Advanced Stage:Large primary tumors with extrascleral extension require multimodal approaches combining surgery, radiation, and emerging adjuvant immunotherapy.
- Recurrent Stage:Second-line interventions after primary treatment failure concentrate in specialized centers with salvage brachytherapy and enucleation capabilities.
- Metastatic Stage:Hepatic and extrahepatic spread drives pharmaceutical revenue concentration. Tebentafusp and checkpoint inhibitors command premium pricing in HLA-A*02:01-positive populations across the United States and Europe.
Localized Stage commands the established base. Metastatic Stage captures the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Treatment modality preferences diverge sharply across geographies: the United States and Germany favor pharmaceutical maintenance protocols for metastatic disease, while Japan retains stronger surgical intervention rates for localized tumors.
United States
Academic medical centers in Philadelphia and New York City drive tebentafusp adoption for HLA-A*02:01-positive metastatic patients. FDA accelerated approval pathways compress development timelines for novel immunotherapies. The Wills Eye Hospital and Memorial Sloan Kettering Cancer Center anchor ocular oncology training and clinical trial enrollment.
Germany
Specialized ocular oncology centers in Heidelberg and Essen concentrate plaque brachytherapy capacity for medium-sized choroidal lesions. EMA priority medicines designation streamlines reimbursement for innovative therapies across statutory health insurance funds. The University Hospital Essen and Heidelberg University Hospital coordinate pan-European biomarker-driven trials.
Japan
National Cancer Center Hospital in Tokyo and Osaka International Cancer Institute perform high volumes of enucleation for large, vision-compromising tumors. PMDA reforms accelerate market entry for innovative ocular oncology drugs through sakigake designation. The Kanto and Kansai regions cluster fellowship-trained specialists and proton beam irradiation infrastructure.
United Kingdom
Royal Liverpool University Hospital and Moorfields Eye Hospital in London coordinate specialized ocular oncology referrals from across England. NICE technology appraisals determine NHS England access to checkpoint inhibitors for metastatic disease. The NHS England specialized commissioning framework concentrates complex procedures in designated supra-regional centers.
China
Top-tier hospitals in Beijing and Shanghai deploy AI-assisted diagnostic imaging for early lesion detection from fundus photography. NMPA reforms accelerate innovative drug approvals through breakthrough therapy designation. The Peking Union Medical College Hospital and Fudan University Eye and ENT Hospital anchor clinical research for GNAQ/GNA11-mutant targeted therapies.
Eye Melanoma Market Vendor Landscape
Capability concentration sits with specialized biopharmaceutical developers possessing bispecific T-cell engager platforms; scale advantage sits with diversified oncology majors leveraging checkpoint inhibitor portfolios across rare cancer indications. The market structure stratifies into three tiers: large-cap pharmaceutical conglomerates with immuno-oncology franchises, mid-cap biotechs with targeted therapy pipelines, and emerging specialists in ocular oncology biomarkers. Dominant competitive moves include strategic partnerships for companion diagnostic development and geographic licensing agreements for tebentafusp distribution.
Within the large-cap tier, Merck & Co., Inc. and F. Hoffmann-La Roche Ltd occupy positions anchored by checkpoint inhibitor portfolios that extend into rare cancer management. Novartis AG sits within the targeted therapy specialist archetype, with development focus on GNAQ/GNA11-mutant tumor pathways. These three companies represent the competitive core around which smaller biotechs and diagnostic partners orbit.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Amgen Inc. |
| AstraZeneca |
| Immunocore Holdings plc |
| Others |
Supply Flow & Price Mechanics
Specialized ocular oncology centers in the United States, Germany, and Japan concentrate demand for tebentafusp and plaque brachytherapy, anchoring premium pricing power for manufacturers while fragmenting procurement leverage among dispersed community ophthalmology practices. This geographic concentration of fellowship-trained specialists and radiation oncology coordination infrastructure shapes where margin pools accumulate across the value chain.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and immunotherapy suppliers dominate metastatic disease management, with California and Texas health systems negotiating multi-year contracts bundling imaging, molecular testing, and pharmaceutical access. Price differentiation hinges on HLA-A*02:01 biomarker status and companion diagnostic integration, with premium tiers commanding substantial markups for validated gp100-targeted protocols. Cost compression in surgical hardware is intensifying because consolidated procurement favors bundled diagnostic-therapy packages over standalone device purchases. Community ophthalmology practices exhibit the highest price sensitivity, while academic medical centers with dedicated ocular oncology fellowships demonstrate inelastic demand for tebentafusp and specialized radiation modalities.
Supply Chain Analysis
Export control regimes on bispecific T-cell engager manufacturing technology limit technology transfer to contract development organizations outside the United States, Switzerland, and the United Kingdom, constraining geographic diversification of active pharmaceutical ingredient production. Cold chain logistics for temperature-sensitive biologics draws from specialized distribution networks concentrated in North America and Western Europe, with last-mile delivery resting on validated thermal packaging and real-time monitoring infrastructure. Single-source vulnerability permeates the supply base for iodine-125 and ruthenium-106 plaque sources used in brachytherapy, with production concentrated in fewer than three nuclear medicine suppliers globally. Distribution runs through hospital specialty pharmacies and integrated delivery network central fill operations, bypassing traditional wholesale channels for high-value oncology biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained ocular oncologists number fewer than two hundred across all major markets, creating acute bottlenecks in patient access and concentrating treatment decisions within a narrow specialist cadre. This human capital scarcity shapes competitive dynamics more profoundly than manufacturing scale or R&D expenditure.
For Market Incumbents: Entrench position by acquiring companion diagnostic developers with validated HLA-A*02:01 and GNAQ/GNA11 testing platforms, securing preferred formulary status through integrated diagnostic-therapy submissions to FDA and EMA. Build backward integration into cold chain logistics to capture distribution margins currently leaking to third-party specialty pharmacies, while expanding tebentafusp administration capacity through hub-and-spoke models that extend reach from flagship academic centers into affiliated community sites. For New Entrants and Emerging Players: Rural and semi-urban geographies in the United States Mountain West and Southern Germany present the most penetrable white space, where teleophthalmology platforms can bypass the specialist concentration bottleneck through remote surveillance and tebentafusp infusion partnerships with regional hospitals. Target second-line metastatic protocols where checkpoint inhibitor resistance creates salvage therapy demand, leveraging real-world evidence generation to accelerate payer negotiations without requiring de novo clinical trial infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap biotechs with bispecific T-cell engager platforms already in ocular oncology or adjacent rare cancer indications, where FDA accelerated approval experience compresses regulatory risk and platform expandability supports pipeline optionality. The long-term viability window favors developers with companion diagnostic partnerships and EMA post-market registry commitments that create durable competitive moats through longitudinal outcome data. Watch for NMPA breakthrough therapy designations as the signal indicating when China market entry timelines for innovative ocular oncology drugs have compressed sufficiently to justify geographic expansion investment.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA and EMA submissions pairing tebentafusp with validated HLA-A*02:01 testing streamline payer negotiations and accelerate formulary access. |
| Real-World Evidence Generation | EMA-mandated post-market registries create durable competitive moats through longitudinal outcome data that barriers generic entrants. |
| Teleophthalmology Platform Deployment | Remote surveillance capabilities expand addressable patient pools beyond the fifty academic centers with fellowship-trained ocular oncologists. |
| Cold Chain Infrastructure Investment | In-house temperature-controlled distribution captures margins currently extracted by third-party specialty pharmacy intermediaries. |
| Biomarker-Driven Trial Design | GNAQ/GNA11 mutation stratification compresses enrollment timelines and reduces per-patient study costs in small uveal melanoma populations. |
Methodological Framework
Initial hypotheses were tested against primary input from ocular oncology fellowship directors, pharmaceutical regulatory affairs leads, hospital formulary directors, and payer access specialists, then refined through secondary validation against FDA accelerated approval filings, EMA priority medicines designations, ClinicalTrials.gov enrollment data, and CMS Medicare reimbursement coding. Bottom-up patient flow modeling across the United States, Germany, and Japan was triangulated with top-down pharmaceutical revenue estimates to anchor market sizing.
Demand-supply balance across treatment modalities was assessed through analysis of plaque brachytherapy capacity constraints, tebentafusp manufacturing scale-up timelines, and fellowship program graduation rates. Segmentation modeling incorporated treatment line, tumor anatomical location, GNAQ/GNA11 mutation status, and regional regulatory cluster. CAGRs were derived from patient incidence projections, therapy adoption curves, and pricing trajectory assumptions across the analysis window, with particular weighting given to immunotherapy displacement rates in metastatic disease management.
Practitioners should monitor FDA breakthrough therapy designations, EMA accelerated assessment conversions, and NMPA sakigake approvals for early signals of competitive entry timing. Forecasts reflect documented assumptions regarding tebentafusp reimbursement durability and biomarker testing penetration. Material shifts in checkpoint inhibitor efficacy data or hepatic-directed therapy outcomes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Vision Care Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Astigmatism Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Aesthetic Ophthalmology Device Market