
 Global Aesthetic Dermatology Market | 2026-2036
Global Aesthetic Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aesthetic Dermatology Market Foresight
Multi-source procurement of laser handpieces and consumable tips is broadening as clinics diversify vendor relationships to secure supply continuity and pricing leverage. Galderma leverages its hyaluronic acid R&D pipeline to sustain leadership in injectable portfolios across European and Latin American markets. Johnson & Johnson anchors its position through deep channel control in professional skincare, while Alma Lasers competes on technology leadership in fractional radiofrequency platforms for scar revision.
Aesthetic dermatology encompasses minimally invasive and non-invasive procedures using energy-based systems, biologic injectables, and mechanical resurfacing tools to modify skin appearance, texture, or subcutaneous contour, typically operating at wavelengths between 532 nm and 10,600 nm depending on chromophore targeting. Injectables command the largest revenue pool due to recurring treatment cycles and high margin per procedure, while energy-based devices for body contouring represent the fastest-expanding category as cryolipolysis and high-intensity focused ultrasound gain clinical adoption for non-surgical fat reduction.
The FDA regulates aesthetic laser and light-based products as medical devices under 21 CFR 1040, with the Center for Devices and Radiological Health enforcing performance standards that shape product development timelines and clinical trial requirements for market entry. The EU Medical Device Regulation and REACH chemical safety frameworks impose additional conformity burdens on injectable formulations and device materials, creating differentiated compliance costs across jurisdictions. Stakeholders must monitor evolving AI-enabled diagnostic integrations and tightening advertising standards for before-and-after claims as these forces reshape competitive differentiation and liability exposure.
Market Dynamics
Fractional radiofrequency and picosecond laser platforms are compressing treatment cycles from quarterly to bi-annual intervals, reshaping clinic capacity planning and consumable revenue models across the installed base.
Growth Catalysts
- EU MDR pathway acceleration:Streamlined conformity assessment for Class IIa energy-based devices is shortening time-to-market for novel wavelength systems targeting vascular lesions.
- Medical spa channel expansion:Hybrid clinic-spa formats in Brazil and South Korea are broadening addressable patient populations beyond traditional dermatology practices.
- Biostimulatory injectables:Poly-L-lactic acid and calcium hydroxylapatite formulations are extending treatment intervals and capturing patients seeking gradual volumetric correction.
Market Restraints
- Handpiece supply concentration:German and Israeli component suppliers control critical diode laser bar fabrication, creating single-source vulnerability for fractional device manufacturers.
- FDA 510(k) clinical burden:Substantial equivalence determinations for novel energy delivery modes require predicate device comparisons that delay iterative innovation.
- Substitution by topical retinoids:High-potency prescription retinoid pipelines from Korean pharmaceutical developers are capturing mild photodamage cases previously routed to laser resurfacing.
Strategic Opportunities
- Men's aesthetic segment:Hair restoration and jawline contouring procedures remain underpenetrated among male demographics in the United States and Germany.
- AI-assisted treatment planning:Machine learning algorithms for melanin density mapping are converging with robotic injection systems to standardize outcomes across operator skill levels.
- India's medical tourism corridor:Cost arbitrage in Mumbai and Delhi clinics is attracting Middle Eastern and Southeast Asian patients for multi-procedure packages.
Industry Challenges
- Operator certification fragmentation:Lack of harmonized training standards for energy-based devices across state medical boards in the United States creates liability exposure and variable outcomes.
- Legacy EMR integration:Aesthetic-specific practice management platforms require costly middleware development to interface with hospital-system electronic records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aesthetic Dermatology Market |
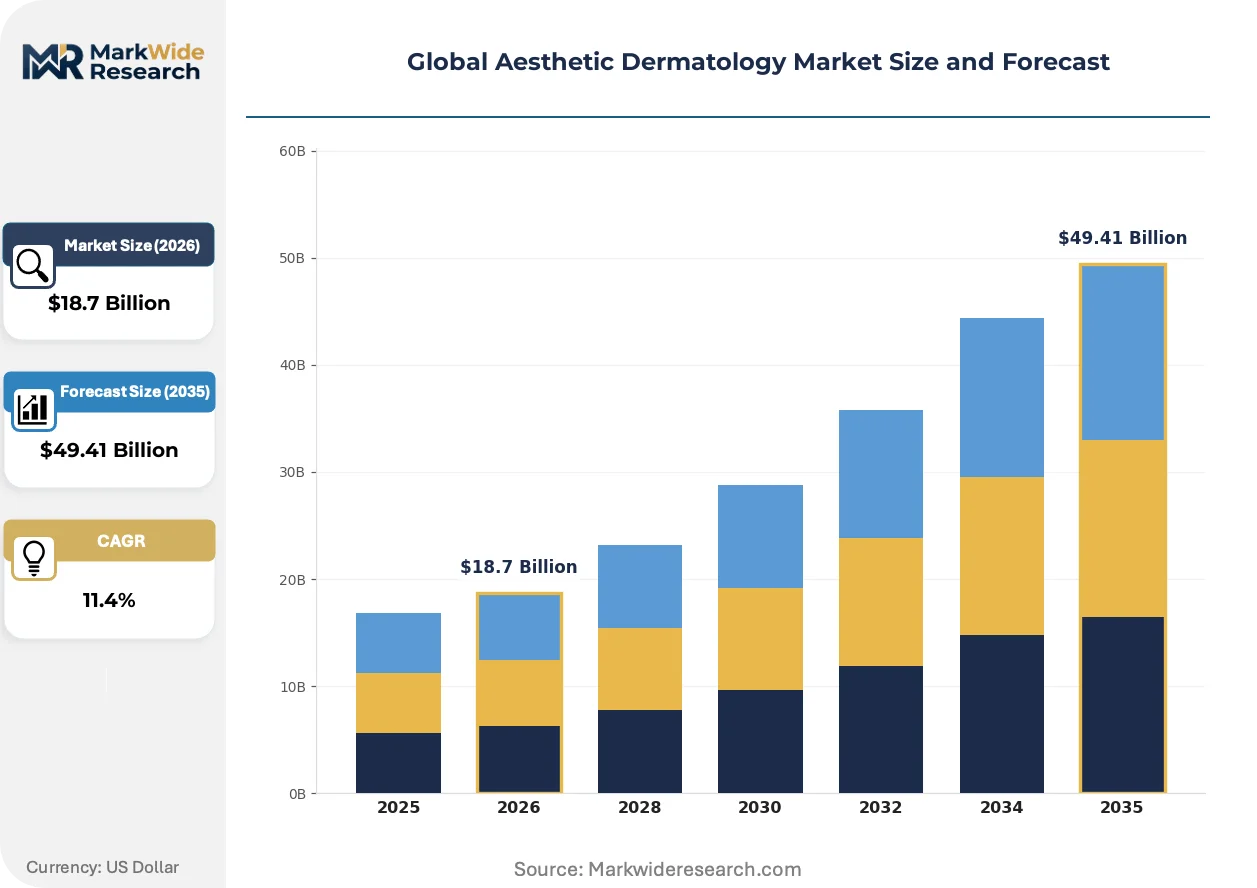
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Devices, Skin Tightening Equipment, Energy-Based Devices, Body Contouring Tools Application: Wrinkle Reduction, Scar Treatment, Pigmentation Correction, Acne Management, Hair Removal End User: Dermatology Clinics, Medical Spas, Cosmetic Surgeons, Beauty Salons, Wellness Centers Technology: Radiofrequency, Intense Pulsed Light, Ultrasound, Cryotherapy, Microdermabrasion |
| Companies Covered | AbbVie, Galderma, Johnson & Johnson, Merz Aesthetics, Bausch Health Companies, Alma Lasers, Cynosure, Lumenis, Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aesthetic Dermatology Market Shifts & Advancements
Convergence between diagnostic imaging and therapeutic delivery is collapsing the consultation-to-treatment timeline, while regulatory frameworks struggle to keep pace with software-enabled device modifications.
Picosecond-domain lasers with diffractive optical elements are integrating real-time melanin feedback sensors to automate fluence adjustment during tattoo removal and pigmented lesion treatments. High-volume chain clinics in Texas and Florida are adopting these systems to reduce operator-dependent variability and compress training curves for non-physician technicians. The technology is integrating predictive maintenance algorithms that flag optical component degradation before output drift compromises clinical outcomes.
REACH Annex XVII restrictions on certain chemical peel formulations are forcing European manufacturers to reformulate medium-depth trichloroacetic acid solutions using buffered delivery systems. The regulation is compressing the supplier base as smaller compounders lack toxicology dossier resources for substance registration. German and French dermatology clinics are responding by shifting procedure mix toward mechanical resurfacing modalities that fall outside chemical substance scope.
Subscription-based consumable purchasing is replacing spot-market handpiece acquisitions among multi-site clinic groups in California and São Paulo. Aggregated procurement platforms are disintermediating traditional device distributors and capturing 15-20 point margin compression through direct manufacturer contracting. This model is most visible in cryolipolysis applicator supply chains, where utilization-based billing aligns clinic cash flows with seasonal demand fluctuation.
Global Aesthetic Dermatology Market Segmentation
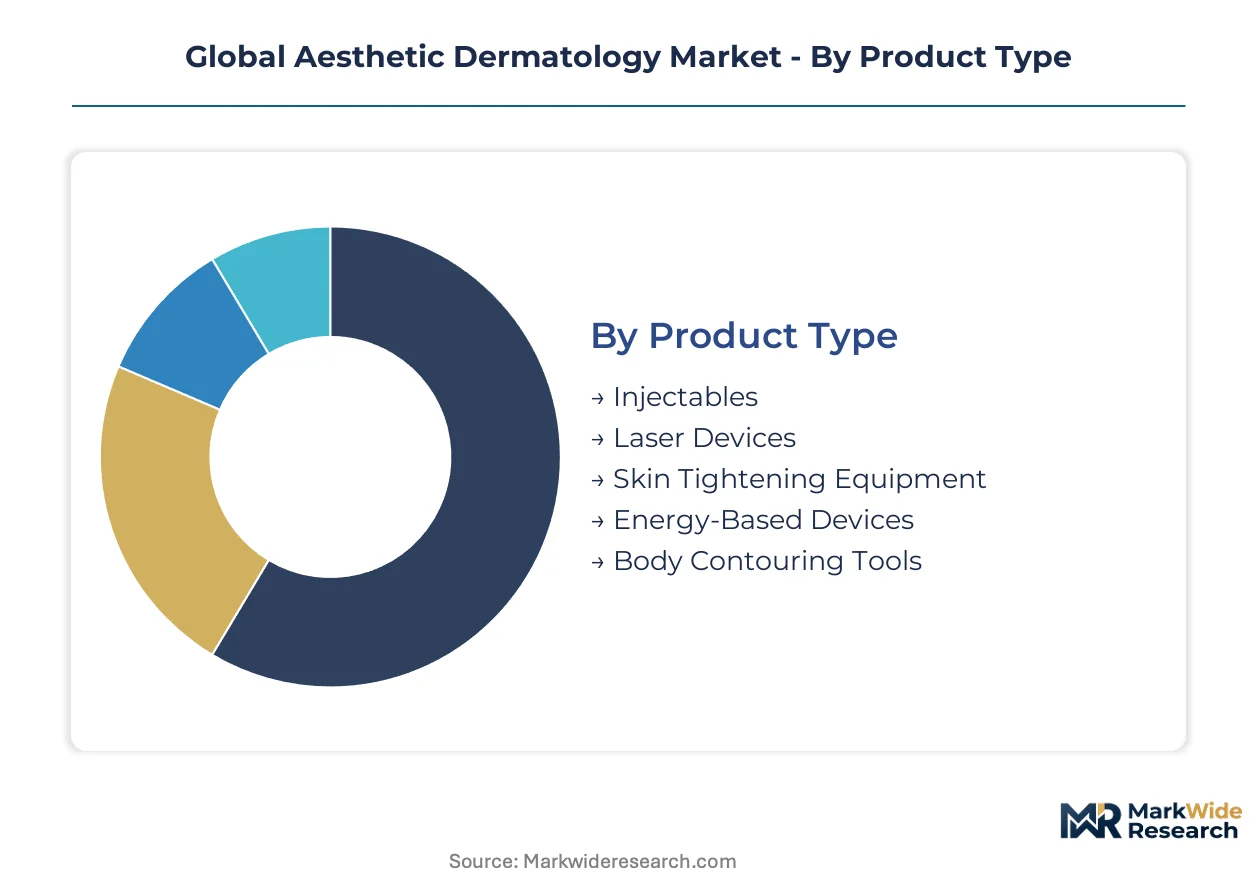
Aesthetic dermatology segmentation reveals how technology specialization, treatment indication, and delivery setting each create distinct competitive arenas with differentiated margin profiles and regulatory exposure. Understanding these boundaries helps stakeholders allocate R&D resources and channel investments against specific patient acquisition costs and reimbursement dynamics.
Product Type:
Technology platforms define the core specification axis, with each modality carrying distinct capital intensity, consumable attach rates, and operator certification requirements.
- Injectables:Hyaluronic acid, poly-L-lactic acid, and calcium hydroxylapatite formulations deliver volumetric correction through standardized injection protocols. Demand concentrates in medical spas across Brazil and South Korea, where recurring treatment cycles generate predictable revenue streams offset by high raw material purity standards enforced under REACH and FDA biologics pathways.
- Energy-Based Devices:Multi-platform systems combining radiofrequency, laser, and light sources address diverse indications through modular handpiece configurations. Clinics in Texas and Florida are expanding installed bases fastest, driven by patient preference for non-invasive alternatives to surgical intervention and compressed recovery timelines.
- Laser Devices:Solid-state and diode architectures operating at specific chromophore-targeting wavelengths.
- Skin Tightening Equipment:Monopolar and bipolar radiofrequency systems with integrated temperature monitoring.
- Body Contouring Tools:Cryolipolysis applicators and high-intensity focused ultrasound platforms for adipose tissue disruption.
Injectables lead on scale; energy-based devices lead on momentum.
Application:
Clinical indication segmentation tracks how patient demographics and severity thresholds route demand across device categories and price tiers.
- Wrinkle Reduction:Neurotoxin and filler protocols targeting glabellar lines, nasolabial folds, and periorbital regions. Dermatology clinics in Germany and the United States capture premium pricing through combination approaches layering biostimulatory injectables with fractional resurfacing, though substitution pressure from high-potency topical retinoids is intensifying in mild photodamage cases.
- Scar Treatment:Fractional ablative lasers, microneedling radiofrequency, and subcision techniques addressing acne and surgical scars. Demand is climbing fastest in South Korea's chain clinic networks, where standardized outcome photography and social media documentation drive patient volume for revision procedures previously considered refractory.
- Pigmentation Correction:Picosecond and Q-switched laser platforms targeting melanin dysregulation.
- Acne Management:Photodynamic therapy, blue-light devices, and isotretinoid adjunct protocols.
- Hair Removal:Diode laser and intense pulsed light systems with skin-type-specific fluence parameters.
Wrinkle reduction commands the largest patient volume; scar treatment is climbing fastest as social documentation norms intensify revision demand.
End User:
Delivery setting segmentation reflects divergent regulatory oversight, capital access, and patient acquisition economics across practice formats.
- Dermatology Clinics:Physician-supervised facilities with full diagnostic capability and hospital-system EMR integration. These settings dominate complex case routing in France and Switzerland, where national health insurance frameworks partially reimburse medically indicated procedures and malpractice liability shapes technology procurement decisions.
- Medical Spas:Hybrid clinical-aesthetic environments staffed by nurse practitioners and physician extenders under remote supervision. São Paulo and Mumbai clusters are expanding fastest, leveraging cost arbitrage and streamlined regulatory pathways to capture price-sensitive patients seeking multi-procedure packages.
- Cosmetic Surgeons:Board-certified plastic surgery practices with surgical suite capabilities.
- Beauty Salons:Non-medical settings limited to superficial mechanical and topical treatments.
- Wellness Centers:Integrated health facilities combining aesthetic services with nutrition and lifestyle programming.
Dermatology clinics lead on procedure complexity; medical spas lead on geographic expansion velocity.
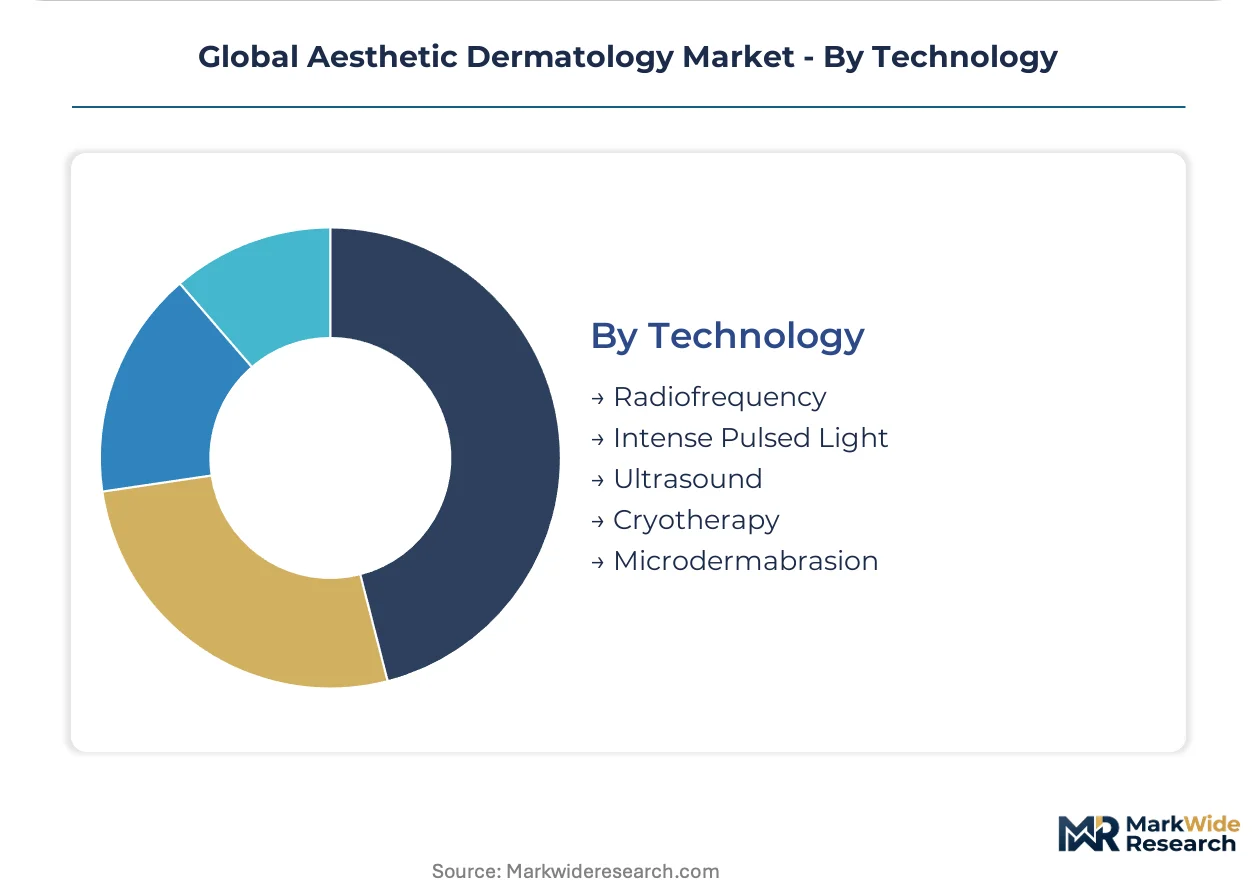
Technology:
Energy delivery mechanism segmentation captures the physics underlying clinical efficacy, safety margins, and equipment depreciation profiles.
- Radiofrequency:Alternating current tissue heating through resistive impedance, deployed in monopolar, bipolar, and fractional configurations. Alma Lasers and competing Israeli manufacturers dominate platform supply, with FDA 510(k) clearance timelines and predicate device requirements creating bottlenecks for novel electrode geometries targeting subdermal fat layers.
- Intense Pulsed Light:Broadband filtered flashlamp output for photorejuvenation and vascular lesion targeting. Demand is expanding most quickly in India's medical tourism corridor, where Mumbai clinics bundle IPL with laser hair removal at price points attracting Middle Eastern patients.
- Ultrasound:High-intensity focused and micro-focused transducers for non-invasive lifting and fat reduction.
- Cryotherapy:Controlled cooling protocols for adipocyte apoptosis and skin lesion destruction.
- Microdermabrasion:Mechanical exfoliation through aluminum oxide crystal or diamond-tip abrasion.
Radiofrequency leads on installed base; intense pulsed light leads on patient accessibility in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the aesthetic dermatology industry through its dense concentration of chain clinic networks and medical tourism infrastructure serving patients from across the Asia-Pacific.
United States
Texas and Florida drive device procurement through high-volume chain clinic expansion targeting non-surgical facial rejuvenation. FDA 510(k) clearance pathways for energy-based systems shape product development timelines for fractional radiofrequency platforms. Dallas and Miami clusters specialize in subscription-based consumable purchasing models that disintermediate traditional distributors.
Germany
Dermatology practices in Bavaria and Baden-Württemberg capture premium pricing through combination approaches layering biostimulatory injectables with resurfacing protocols. EU Medical Device Regulation conformity assessment for Class IIa laser systems imposes toxicology dossier requirements on medium-depth chemical peel formulations. Frankfurt and Munich clinics shift procedure mix toward mechanical resurfacing as REACH Annex XVII restricts trichloroacetic acid solutions.
Brazil
São Paulo's hybrid clinic-spa formats broaden addressable patient populations through cost arbitrage and streamlined regulatory pathways under ANVISA medical device frameworks. Poly-L-lactic acid and calcium hydroxylapatite formulations extend treatment intervals for patients seeking gradual volumetric correction. The city's multi-site clinic groups pioneer utilization-based billing models for cryolipolysis applicator supply chains.
South Korea
Seoul Capital Area clinics dominate scar revision demand through standardized outcome photography and social media documentation driving patient volume for previously refractory cases. MFDS regulates biologic injectables and energy-based devices through accelerated approval pathways for novel wavelength systems. Gangnam district anchors global technology adoption for picosecond-domain lasers with real-time melanin feedback sensors.
India
Mumbai and Delhi medical tourism corridors attract Middle Eastern and Southeast Asian patients for multi-procedure packages leveraging cost arbitrage against Western markets. CDSCO device registration requirements create compliance differentiation between hospital-system dermatology practices and independent medical spas. Maharashtra's clinic clusters bundle intense pulsed light with laser hair removal at price points capturing seasonal demand fluctuation.
Global Aesthetic Dermatology Market Competitive Landscape
Global majors compete with regional champions across technology platforms and distribution reach, creating a tiered structure where scale-driven pharmaceutical conglomerates anchor injectable portfolios while specialized device manufacturers compete on wavelength innovation. Market structure consolidates around three strategic archetypes: diversified healthcare conglomerates with deep channel control, dedicated aesthetics pure-plays with technology leadership, and emerging regional champions leveraging cost arbitrage. Dominant competitive moves include portfolio diversification into adjacent biostimulatory formulations and geographic expansion through direct-to-clinic consumable subscription models.
Within the pharmaceutical conglomerate tier, AbbVie and Johnson & Johnson occupy positions reflecting diversified healthcare portfolios with professional skincare and injectable capabilities. Galderma represents the dedicated aesthetics pure-play archetype, anchoring hyaluronic acid R&D pipelines across European and Latin American markets. Alma Lasers sits within the technology leadership segment, competing on fractional radiofrequency platforms for scar revision with Israeli manufacturing origins evident in its name structure.
| Leading Market Players |
|---|
| AbbVie |
| Galderma |
| Johnson & Johnson |
| Merz Aesthetics |
| Bausch Health Companies |
| Alma Lasers |
| Cynosure |
| Lumenis |
| Cutera |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up clinic chains in Texas and Florida anchor pricing discipline through aggregated procurement platforms that compress distributor margins while securing multi-year consumable commitments. This ownership pattern concentrates buying power among fewer decision-makers, forcing device manufacturers to absorb cost volatility in diode laser components rather than pass through to end-users.
Pricing Analysis
Input-cost pass-through from German and Israeli diode laser bar suppliers runs through subscription-based consumable purchasing rather than spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared devices from CE-marked alternatives and unregulated grey-market imports. Pricing pressure stems from Korean pharmaceutical developers capturing mild photodamage cases with high-potency topical retinoids. Medical spas in São Paulo and Mumbai exhibit highest price sensitivity; Swiss dermatology clinics in Geneva and Zurich show lowest.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Tel Aviv, and Seoul anchor hub-and-spoke patterns for fractional radiofrequency handpieces and cryolipolysis applicators. Manufacturing concentrates in Germany, Israel, and South Korea for solid-state laser architectures and diode fabrication. Raw material dependencies include rare-earth doped crystals, medical-grade hyaluronic acid, and biocompatible calcium hydroxylapatite. Single-source vulnerability in diode laser bar fabrication from Israeli component suppliers creates supply chain risk. Distribution runs through direct-to-clinic subscription platforms disintermediating traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aesthetic dermatology market functions as a stable compounder anchored by recurring treatment cycles for biostimulatory injectables that generate predictable revenue streams resistant to economic cyclicality.
For Market Incumbents: Extend platform stickiness through backward integration into hyaluronic acid raw material production to offset REACH purity standard compliance costs. Add captive service capacity in Mumbai and Delhi to defend against Indian medical tourism competitors capturing Middle Eastern patient flows. Certification investment in FDA 510(k) predicate device libraries creates moats against iterative innovation delays.
For New Entrants and Emerging Players: Launch via direct-to-clinic subscription models targeting cryolipolysis applicator supply chains in São Paulo and California where utilization-based billing aligns with seasonal demand fluctuation. Men's aesthetic segments in Germany and the United States remain most penetrable white-space targets for hair restoration and jawline contouring procedures. AI-assisted treatment planning partnerships with robotic injection system developers offer differentiated go-to-market positioning against operator skill variability.
For Investors and Strategic Acquirers: Pharmaceutical conglomerates with professional skincare portfolios are the most active acquirers in this space, seeking injectable capabilities to complement dermatology channel control. Long-term viability over a multi-year horizon rests on biostimulatory formulation pipelines extending treatment intervals beyond quarterly cycles. Acquisition targets should demonstrate installed base density in medical spa channels and consumable attach rates above category averages. Watch FDA 510(k) clearance velocity for novel wavelength systems as inflection indicator for technology leadership shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Biostimulatory Formulation Pipeline Expansion | Poly-L-lactic acid R&D at Galderma extends treatment intervals and captures gradual volumetric correction demand in Brazil. |
| AI-Enabled Diagnostic Integration | Real-time melanin feedback sensors in picosecond lasers reduce operator-dependent variability in Texas chain clinics. |
| Medical Spa Channel Penetration | Hybrid clinic-spa formats in São Paulo broaden addressable patient populations beyond traditional dermatology practices. |
| Subscription-Based Consumable Purchasing | Aggregated procurement platforms in California capture margin compression through direct manufacturer contracting. |
| Regulatory Certification Investment | EU MDR streamlined conformity assessment for Class IIa devices accelerates time-to-market for Alma Lasers in Germany. |
Research Methodology
Direct dialogue with dermatology clinic operators, biomedical engineers at device manufacturers, GPO contracts managers, and regulatory affairs specialists at FDA and MFDS grounds qualitative findings in practitioner experience. Secondary validation draws from FDA 510(k) filings, MFDS accelerated approval pathway documentation, EU MDR conformity assessment records, and hospital procurement database extracts. Bottom-up triangulation across clinician interview data and top-down reconciliation against manufacturer shipment records ensures cross-verified market sizing.
Market value outputs incorporate segmentation across product type, application, end user, and technology dimensions throughout the forecast period. CAGRs derive from procedure volume growth rates in named country clusters weighted by average selling price trajectories for injectables versus energy-based devices. Forecast inputs include regulatory approval timelines for novel wavelength systems and medical spa expansion velocity in Brazil and South Korea.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA 510(k) predicate device shortages or REACH Annex XVII chemical peel formulation restrictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
UAE Laser Hair Removal Market