
 Medical Imaging Software Market | 2026-2036
Medical Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Imaging Software Market Outlook
Subscription-based software-defined feature layers is realigning how imaging vendors monetize diagnostic capabilities. GE HealthCare leverages its installed base of scanners to bundle AI-powered reconstruction tools into recurring service contracts. Siemens Healthineers anchors its competitiveness through deep integration of advanced visualization software with hardware fleets. Aidoc specializes in radiology workflow automation, competing on detection speed for critical findings across hospital networks.
Medical imaging software comprises coded instructions, algorithmic protocols, and graphical interfaces that process raw scanner output into clinically actionable visual datasets, typically operating within DICOM interoperability standards to ensure cross-platform compatibility. The technology serves to accelerate diagnosis, standardize image quality, and enable remote specialist consultation across distributed care settings. Cloud-based deployment is capturing expanding share as hospitals seek to reduce on-site server overhead and enable multi-site image sharing. AI-based technology leads innovation intensity, with 3D imaging representing a mature but still critical segment for surgical planning applications.
FDA software-as-a-medical-device guidelines, EU MDR classification rules for diagnostic algorithms, and HIPAA data security mandates collectively determine product development roadmaps and market entry timelines for vendors. These frameworks elevate compliance costs but simultaneously create barriers that favor established players with regulatory affairs infrastructure. Stakeholders must monitor how FDA pre-certification pilots and EU AI Act risk classifications reshape competitive access for algorithm-first entrants.
Market Dynamics
AI-enhanced diagnostic suites are electrifying radiology workflows, forcing hospitals to restructure capital allocation toward algorithmic reconstruction tools and cloud-native infrastructure. This technological pivot compresses hardware replacement cycles while elevating software licensing to strategic priority status.
Growth Catalysts
- FDA software-as-a-medical-device framework:The pathway accelerates algorithm-based tool commercialization, reducing time-to-revenue for diagnostic AI developers seeking hospital network contracts.
- Enterprise imaging infrastructure modernization:United States health systems are retiring PACS silos in favor of vendor-neutral archives that demand interoperable software layers.
- Cloud-based deployment architectures:Multi-site hospital networks are eliminating on-site server overhead through centralized image processing platforms.
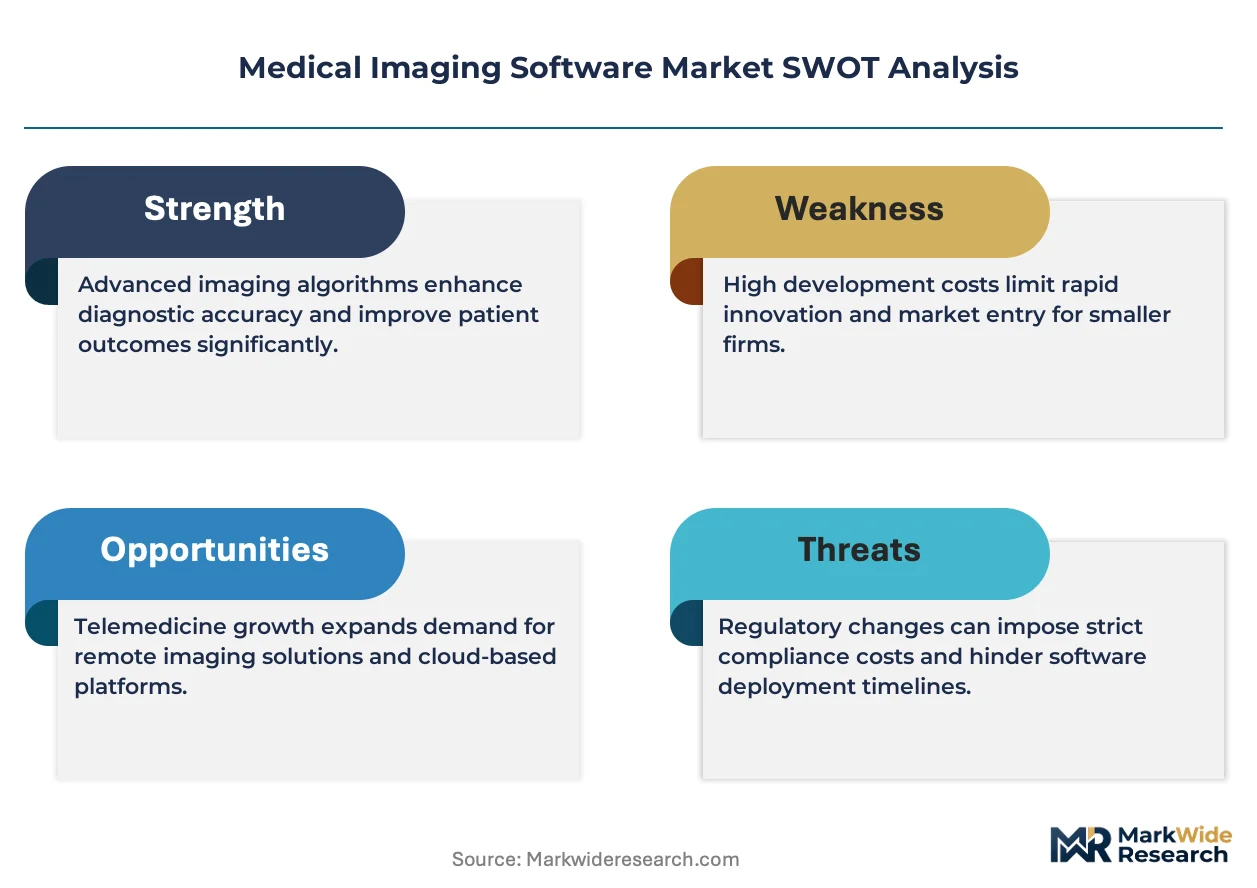
Market Restraints
- EU MDR classification complexity:Diagnostic algorithm reclassification under stricter conformity assessment procedures extends regulatory timelines and elevates compliance expenditure.
- Specialized radiologist training deficits:AI-augmented interpretation requires dual competency in clinical validation and algorithmic oversight, constraining workforce scalability.
- Legacy DICOM interoperability gaps:Scanner fleet heterogeneity creates data format friction that slows AI model standardization across equipment vintages.
Strategic Opportunities
- Remote specialist consultation networks:Teleradiology platforms enable asynchronous diagnosis across distributed care settings, opening rural and emerging market penetration.
- EU AI Act risk classification alignment:Early compliance positioning creates preferential access to European hospital procurement frameworks as mandatory requirements phase in.
- 3D surgical planning software integration:Preoperative visualization tools are converging with robotic surgical systems, creating bundled value propositions in orthopedic and cardiovascular service lines.
Industry Challenges
- Algorithm validation dataset bias:Training data skewed toward specific demographics or scanner manufacturers produces diagnostic performance degradation in underrepresented populations.
- HIPAA-compliant cloud architecture complexity:Encryption key management and audit trail maintenance across hybrid environments demand specialized cybersecurity infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Imaging Software Market |
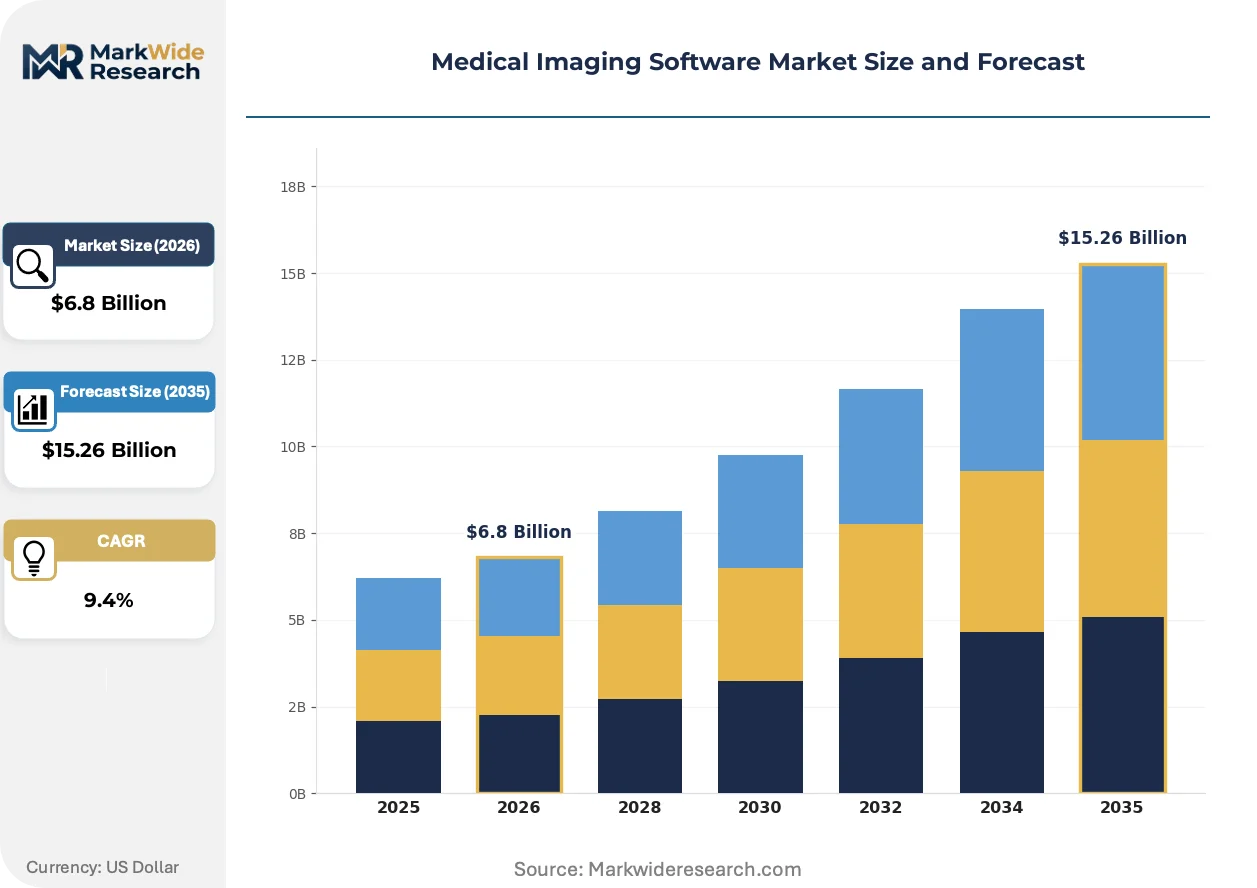
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scan, Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Laboratories Deployment: On-premises, Cloud-based, Hybrid, Mobile Technology: AI-based, 3D Imaging, DICOM, Visualization Tools |
| Companies Covered | Aidoc, Advantis Medical Imaging, GE HealthCare, AIVIS, QUIBIM, Philips Healthcare, Subtle Medical, Medivis, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Imaging Software Market Strategic Shifts
Computational reconstruction algorithms are displacing traditional filtered back-projection methods, compressing scan times while preserving diagnostic fidelity. This shift elevates software engineering capabilities above hardware specification in vendor competitive positioning.
Deep learning-based image denoising is electrifying low-dose CT protocols, enabling radiation exposure reduction without sacrificing lesion detectability. Academic medical centers in the United States are piloting these tools for pediatric and oncology screening applications. The technology is compressing the historical trade-off between patient safety and image quality that governed scanner procurement decisions.
FDA pre-certification pilot programs are restructuring how algorithm-first vendors secure market access, replacing pre-market submission bottlenecks with continuous performance monitoring frameworks. The industrial consequence accelerates iterative model deployment but elevates post-market surveillance infrastructure requirements. Radiology AI specialists are responding by building internal regulatory affairs capabilities that mirror pharmaceutical compliance operations.
Hospital procurement committees are unbundling software licenses from hardware service contracts, creating discrete budget lines for AI modules and visualization tools. This pattern disrupts traditional scanner OEM bundling power and elevates third-party algorithm vendors to direct negotiation status. The behavior is most pronounced in United States integrated delivery networks consolidating purchasing authority across multiple facilities.
Medical Imaging Software Market Segmentation
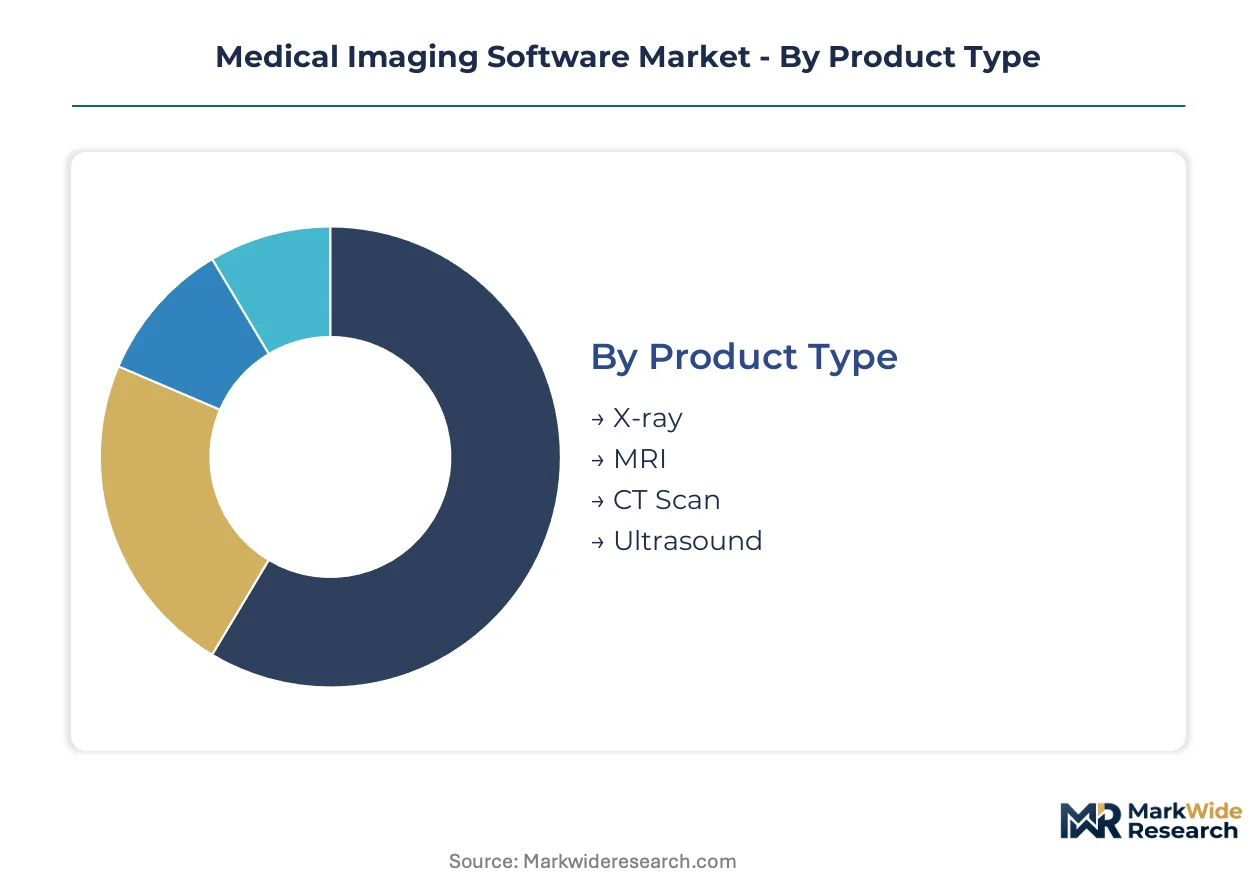
Medical imaging software vendors architect product roadmaps around four distinct segmentation axes. Each dimension governs different procurement criteria, integration complexity, and margin structures across hospital networks and diagnostic facilities.
Product Type:
CT Scan and MRI software layers embed most deeply into scanner hardware, while X-ray and ultrasound modules often deploy as standalone workstations.
- CT Scan:Computational reconstruction algorithms process raw detector data into cross-sectional anatomical datasets. United States academic medical centers prioritize CT software with FDA-cleared AI denoising for low-dose pediatric protocols.
- MRI:Pulse sequence programming and k-space reconstruction form the core software stack. Demand concentrates in tertiary hospitals upgrading to quantitative imaging biomarker extraction for oncology staging.
- X-ray:Digital radiography software handles detector calibration, image enhancement, and PACS routing. Primary care networks in rural geographies favor lightweight, cloud-connected X-ray workstations.
- Ultrasound:Beamforming algorithms and real-time speckle reduction dominate development priorities. Point-of-care ultrasound software sees expanding deployment in emergency departments.
Volume placements concentrate in CT Scan; the faster expansion belongs to MRI.
End User:
Procurement authority and integration requirements vary sharply across institutional settings, with hospitals demanding enterprise-scale architectures.
- Hospitals:Enterprise imaging infrastructure demands vendor-neutral archive compatibility and multi-site federation capabilities. Integrated delivery networks in the United States consolidate AI module purchasing across radiology, cardiology, and oncology service lines.
- Diagnostic Centers:High-throughput outpatient facilities prioritize workflow automation and rapid report turnaround. Teleradiology platforms serving these centers require asynchronous reading capabilities.
- Clinics:Limited IT infrastructure drives preference for cloud-native deployment with minimal on-site server footprint. Specialty clinics favor procedure-specific visualization packages.
- Research Laboratories:Quantitative imaging biomarker development and clinical trial imaging core labs demand research-use-only software with flexible algorithm modification rights.
Revenue concentration sits with Hospitals; Research Laboratories are climbing the fastest.
Deployment:
Architecture choices determine cybersecurity burden, scalability limits, and total cost of ownership across facility networks.
- Cloud-based:Centralized image processing eliminates on-site server overhead while enabling multi-site sharing. HIPAA-compliant encryption key management remains the primary adoption barrier.
- Hybrid:Edge preprocessing with cloud archival balances latency sensitivity against storage economics. United States health systems favor hybrid models for stroke and trauma networks.
- On-premises:Air-gapped installations persist in defense medical facilities and certain critical infrastructure-adjacent hospitals. Capital expenditure requirements constrain refresh cycles.
- Mobile:Tablet-optimized viewing and limited reconstruction tools serve bedside consultation and surgical navigation. FDA software-as-a-medical-device frameworks govern standalone mobile diagnostic apps.
Installed base dominance belongs to On-premises; Cloud-based is gaining share fastest.
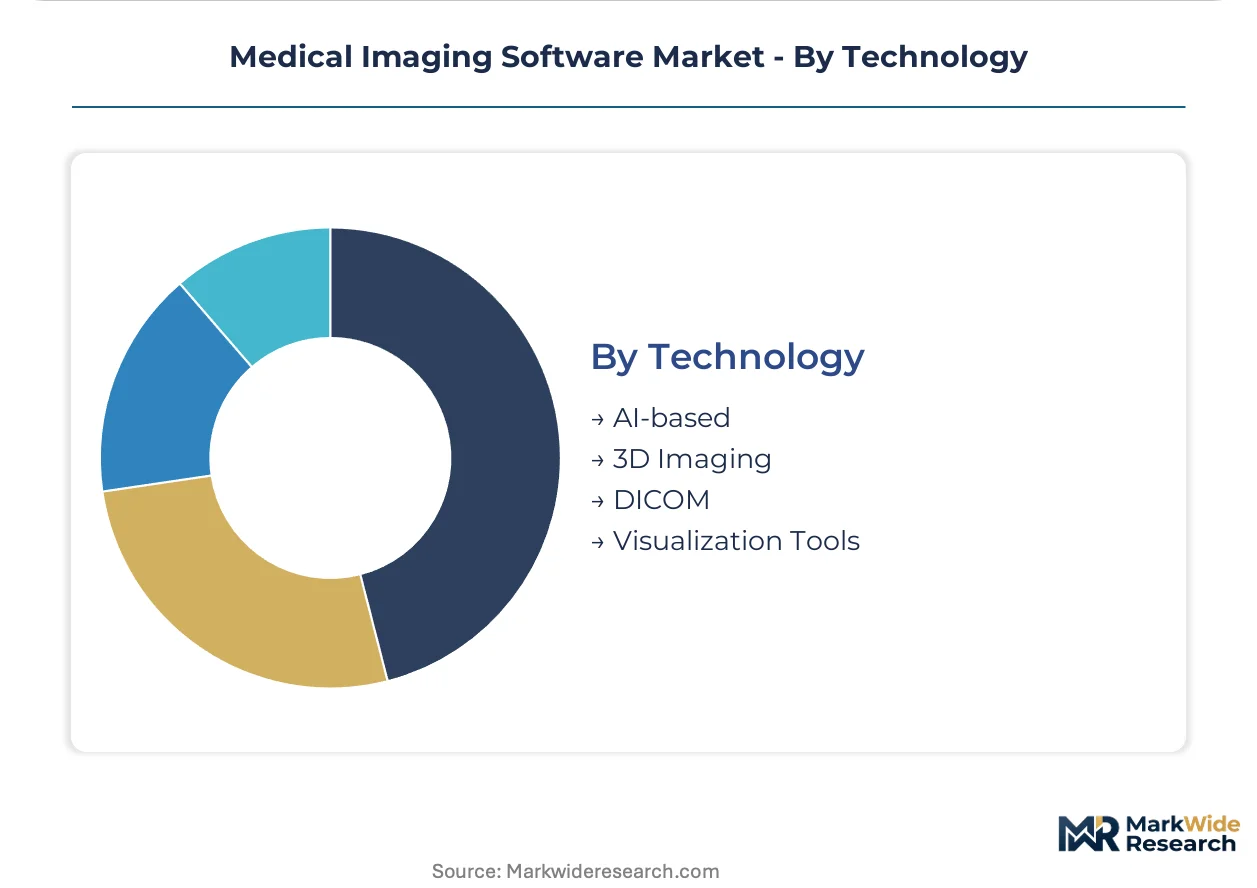
Technology:
Technology layers stack from foundational interoperability protocols through advanced algorithmic capabilities.
- AI-based:Deep learning models automate detection, segmentation, and quantification tasks. FDA pre-certification pilots accelerate iterative deployment for radiology workflow vendors.
- 3D Imaging:Volume rendering and multiplanar reconstruction represent mature capabilities essential for surgical planning. Orthopedic and cardiovascular service lines drive sustained demand.
- DICOM:Interoperability standards ensure cross-platform compatibility across heterogeneous scanner fleets. Legacy DICOM variant gaps create integration friction.
- Visualization Tools:Advanced rendering, fusion imaging, and augmented reality overlays support interventional guidance. Academic medical centers pilot holographic surgical planning interfaces.
Commercial maturity centers on Visualization Tools; AI-based shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors concentrated demand for AI-enhanced diagnostic suites, with Massachusetts General Hospital and Brigham and Women's Hospital piloting FDA-cleared algorithmic reconstruction tools. This cluster exemplifies how academic medical centers drive procurement patterns for enterprise imaging infrastructure.
United States
Integrated delivery networks in Texas and California are consolidating AI module purchasing across radiology, cardiology, and oncology service lines. FDA software-as-a-medical-device frameworks accelerate commercialization timelines for algorithm-based vendors. The Research Triangle in North Carolina hosts clinical validation partnerships between health systems and emerging AI developers.
Germany
Baden-Württemberg's industrial corridor concentrates MRI software development alongside precision engineering clusters. EU MDR classification rules for diagnostic algorithms extend regulatory timelines but elevate compliance infrastructure barriers. Munich's university hospital network pilots quantitative imaging biomarker extraction for oncology staging protocols.
Japan
Tokyo's metropolitan hospital systems prioritize low-dose CT protocols with deep learning-based image denoising for pediatric applications. PMDA regulatory pathways govern AI-based medical device approvals with distinct performance monitoring requirements. Osaka's medical device manufacturing belt supplies visualization hardware with embedded software layers.
United Kingdom
London's NHS trusts are retiring PACS silos in favor of vendor-neutral archives demanding interoperable software layers. MHRA post-Brexit regulatory frameworks diverge from EU MDR timelines, creating dual compliance obligations. Cambridge's biomedical cluster hosts algorithm development for radiology workflow automation.
India
Hyderabad's health-tech corridor drives teleradiology platform deployment across distributed care settings in southern states. CDSCO medical device regulations govern diagnostic software classification with evolving AI-specific guidance. Maharashtra's private hospital chains in Mumbai and Pune procure cloud-native imaging workstations for outpatient networks.
Medical Imaging Software Market Competitive Environment
Capital-heavy scanner OEMs compete with asset-light algorithm developers across divergent margin structures and capital intensity profiles. Market structure tilts toward consolidated hardware-software bundling power among established imaging equipment manufacturers, with fragmented specialization among AI-native entrants. Three archetypes dominate: integrated equipment vendors leveraging installed bases, pure-play AI developers competing on detection speed, and visualization specialists anchoring surgical planning workflows. M&A activity concentrates on algorithm acquisitions by hardware incumbents, while strategic partnerships proliferate between cloud infrastructure providers and workflow automation vendors.
Within the integrated equipment tier, GE HealthCare and Siemens Healthineers occupy positions defined by scanner fleet penetration and recurring service contract structures. Aidoc exemplifies the AI-native archetype, representing radiology workflow automation specialists competing on critical finding detection velocity. Philips Healthcare sits at the convergence point, bridging hardware manufacturing with software-defined diagnostic capabilities. These three anchors illustrate how competitive positioning fragments across capital intensity, regulatory affairs scale, and cloud-native deployment readiness.
| Leading Market Players |
|---|
| Aidoc |
| Advantis Medical Imaging |
| GE HealthCare |
| AIVIS |
| QUIBIM |
| Philips Healthcare |
| Subtle Medical |
| Medivis |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up AI imaging specialists anchor supply-side concentration while enforcing subscription-based pricing discipline across hospital networks. This ownership pattern feeds algorithm development pipelines and locks in recurring revenue structures that resist transactional commoditization.
Pricing Analysis
Outcome-tied pricing anchors software monetization, with hospitals paying per-scan fees for AI detection modules validated against diagnostic accuracy benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared algorithms from CE-marked equivalents and research-use-only tools. Cost compression in the economy tier is intensifying because cloud-native entrants undercut on-premises licensing. Diagnostic centers exhibit highest price sensitivity; academic medical centers prioritize certification tier over cost.
Supply Chain Analysis
Machine-learning engineering talent scarcity in Germany, Japan, and the United States constrains algorithm development velocity and elevates compensation costs. The supply chain draws from GPU semiconductor fabrication in Taiwan, cloud infrastructure provisioning in Ireland and Singapore, and clinical validation partnerships with academic medical centers. Single-source vulnerability clusters around NVIDIA tensor core availability for training workloads. Distribution runs through direct enterprise sales teams serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA software-as-a-medical-device framework erects a cost-of-compliance moat that favors established players with regulatory affairs infrastructure. This barrier-to-entry dynamic concentrates margin capture among pre-certified vendors while elevating capital requirements for algorithm-first entrants.
For Market Incumbents: Acquire FDA pre-certification pilot participants to absorb continuous performance monitoring capabilities and compress algorithm deployment timelines. Consolidate cloud-native workflow automation vendors before they achieve direct hospital procurement committee status. Cloud infrastructure control represents the priority defensive lever against margin erosion.
For New Entrants and Emerging Players: Enter via teleradiology platforms serving rural diagnostic centers in India and Southeast Asia, where price sensitivity outstrips brand preference. Target cloud-native deployment for clinics with minimal IT infrastructure. Pursue research laboratory partnerships for clinical validation data generation ahead of regulatory submission.
For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithm-native specialists with EU AI Act risk classification compliance in Germany and France. Long-term viability hinges on regulatory affairs scalability across FDA and EU MDR frameworks. Watch FDA pre-certification pilot expansion as inflection signal for algorithm deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates algorithm deployment while elevating post-market surveillance infrastructure requirements for vendors. |
| Hospital System Partnership | Unlocks enterprise imaging infrastructure procurement across radiology, cardiology, and oncology service lines simultaneously. |
| Cloud Infrastructure Integration | Enables multi-site image federation while reducing on-premises server overhead for hospital networks. |
| EU AI Act Compliance Positioning | Creates preferential access to European hospital procurement frameworks as mandatory risk classifications phase in. |
| 3D Surgical Planning Software Development | Converges preoperative visualization with robotic surgical systems in orthopedic and cardiovascular service lines. |
Study Parameters
FDA 510(k) clearance databases, EU MDR conformity assessment records, and hospital procurement contract filings formed the secondary backbone for algorithm commercialization tracking. Primary interviews with radiology department chairs, biomedical informatics officers, GPO contracts managers, and diagnostic AI product directors validated deployment timelines and pricing structures. Bottom-up and top-down triangulation cross-checked vendor-reported installation counts against health system IT expenditure disclosures.
Bottom-up modeling aggregated scanner fleet data, software licensing attach rates, and service contract renewal patterns across deployment architectures. Segmentation dimensions spanned imaging modality, end-user institution type, cloud versus on-premises architecture, and AI versus conventional technology layers. CAGRs derived from fitted growth curves applied to validated base-year estimates, with sensitivity testing around FDA pre-certification pilot expansion and EU AI Act implementation pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR reclassification delays or HIPAA enforcement actions affecting cloud architectures. Projections reflect assumptions regarding algorithm validation dataset standardization and radiologist workforce training scalability. A small set of named triggers—FDA pre-certification program scope expansion, EU AI Act high-risk system designations, and cloud infrastructure security incident frequency—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Spain Digital Radiology Market