
 US Magnetic Resonance Imaging Market | 2026-2036
US Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Magnetic Resonance Imaging Market Intelligence
Hospital end-use demand is consolidating around integrated delivery networks that standardize imaging platforms across multiple sites. Siemens Healthineers leverages its superconducting magnet supply chain to sustain installed-base loyalty. GE Healthcare anchors its position through AI-embedded reconstruction software that reduces scan times. Canon Medical Systems competes on extremity MRI specialization for orthopedic-focused ambulatory surgery centers.
Magnetic Resonance Imaging deploys superconducting electromagnets generating field strengths from 1.5 to 7 Tesla, using radiofrequency pulses and gradient coils to excite hydrogen nuclei and reconstruct tomographic images without ionizing radiation. Closed MRI systems dominate hospital procurement for high-resolution neurovascular and abdominal studies, while open MRI architectures serve claustrophobic and bariatric patient populations where accessibility constraints limit conventional bore designs. Superconducting MRI technology leads the technology segment due to its field stability and spectral fidelity, though permanent magnet MRI retains share in lower-field extremity applications where helium scarcity and operating costs pressure total cost of ownership.
FDA 510(k) clearance requirements govern new system introductions, while CMS physician fee schedule updates directly influence imaging center capital commitment cycles. State-level certificate-of-need regulations in New York, Illinois, and Washington constrain equipment duplication and protect incumbent provider margins. Stakeholders must monitor helium supply chain restructuring and AI diagnostic billing code development as these forces reshape deployment economics and service line profitability.
Market Dynamics
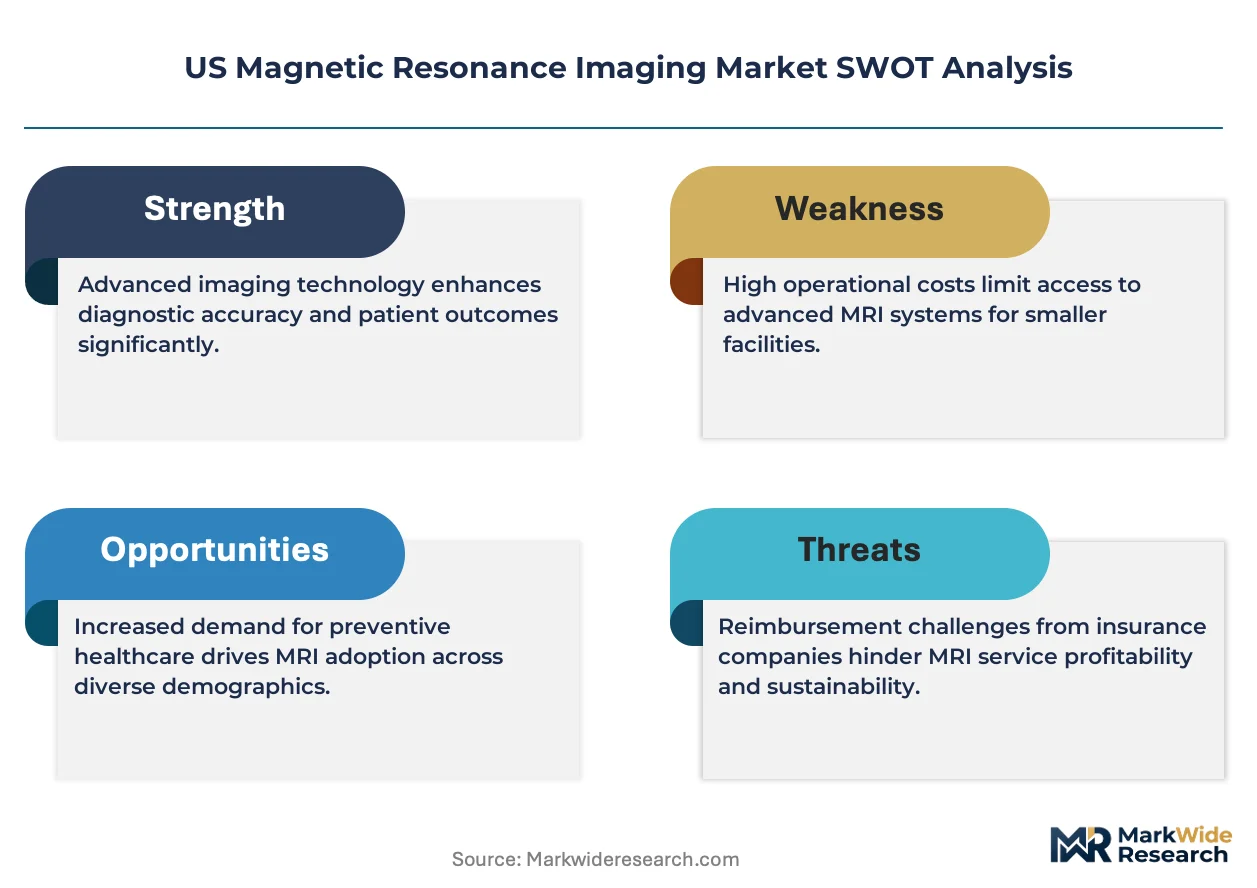
CMS reimbursement compression and helium supply volatility are forcing hospital systems to consolidate MRI procurement around total-cost-of-ownership metrics rather than upfront capital expenditure alone.
Growth Catalysts
- Outpatient imaging migration:Ambulatory surgery centers in Texas and Florida are expanding MRI capacity to capture federally qualified health center referrals.
- AI-embedded reconstruction:Deep learning algorithms reduce scan durations by reconstructing undersampled k-space data, improving patient throughput.
- Certificate-of-need exemptions:Rural hospital exceptions in multiple states enable equipment deployment without incumbent protection.
Market Restraints
- Helium scarcity:Qatar and Algeria supply concentration creates price volatility for superconducting magnet cooling.
- High-field magnet manufacturing:Niobium-titanium superconductor supply is concentrated among three specialized foundries globally.
- Claustrophobia limitations:Closed-bore 3 Tesla systems exclude 10-15% of patient populations, capping addressable volume.
Strategic Opportunities
- Extremity MRI specialization:Dedicated wrist, knee, and ankle systems serve orthopedic-focused ambulatory networks in California.
- Remote scanning protocols:Cloud-based image reconstruction enables rural hospital teleradiology partnerships with academic medical centers.
- Permanent magnet resurgence:Zero-helium designs address supply chain risk for lower-field musculoskeletal applications.
Industry Challenges
- Specialized service engineering:Superconducting magnet maintenance requires cryogenics expertise that health systems struggle to retain in-house.
- FDA 510(k) pathway complexity:AI diagnostic software submissions face evolving evidentiary standards for clinical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Magnetic Resonance Imaging Market |
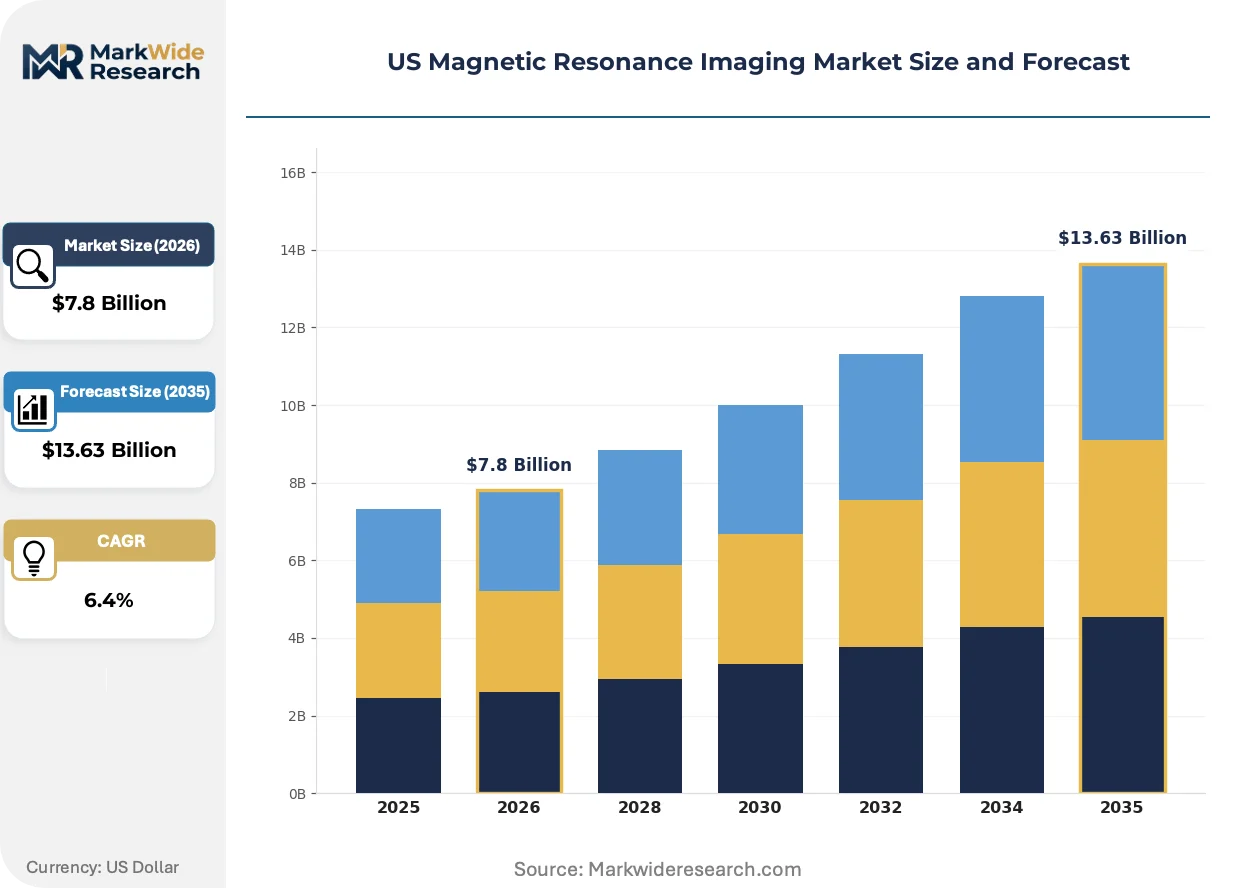
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Imaging Centers, Research Institutions, Diagnostic Laboratories Technology: Superconducting MRI, Permanent Magnet MRI, Hybrid MRI, Pulsed Gradient MRI Application: Neurology, Orthopedics, Cardiology, Oncology |
| Companies Covered | Canon Medical Systems, United Imaging Healthcare, Siemens Healthineers, Fonar Corp., Hitachi, GE Healthcare, FUJIFILM, Hyperfine, Inc., Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Magnetic Resonance Imaging Market Strategic Shifts & Innovations
Artificial intelligence is compressing scan protocols while helium-free magnet architectures are redefining site requirements. These forces are redrawing competitive boundaries between hospital-based and distributed imaging models.
Portable low-field MRI systems are decentralizing neuroimaging delivery. These battery-powered units operate at 0.064 Tesla without cryogens, enabling bedside deployment in intensive care units. Neurology departments at academic medical centers in Massachusetts and Pennsylvania are piloting these systems for stroke protocol acceleration. The technology is decentralizing emergency department triage by eliminating patient transport to radiology suites.
FDA software-as-a-medical-device guidance is reshaping AI diagnostic deployment pathways. The 2022 final guidance clarifies predetermined change control plans for machine learning algorithms. Radiology information system vendors must now submit modification protocols alongside initial clearances. PACS-integrated AI tools face heightened post-market surveillance obligations.
After-sales service unbundling is fragmenting vendor revenue streams. Health systems in Illinois and New York are separating hardware maintenance from software subscription agreements. Third-party independent service organizations are capturing magnet cryogen management contracts previously held by original equipment manufacturers. This pattern is most visible among integrated delivery networks with multi-site standardization mandates.
US Magnetic Resonance Imaging Market Segmentation
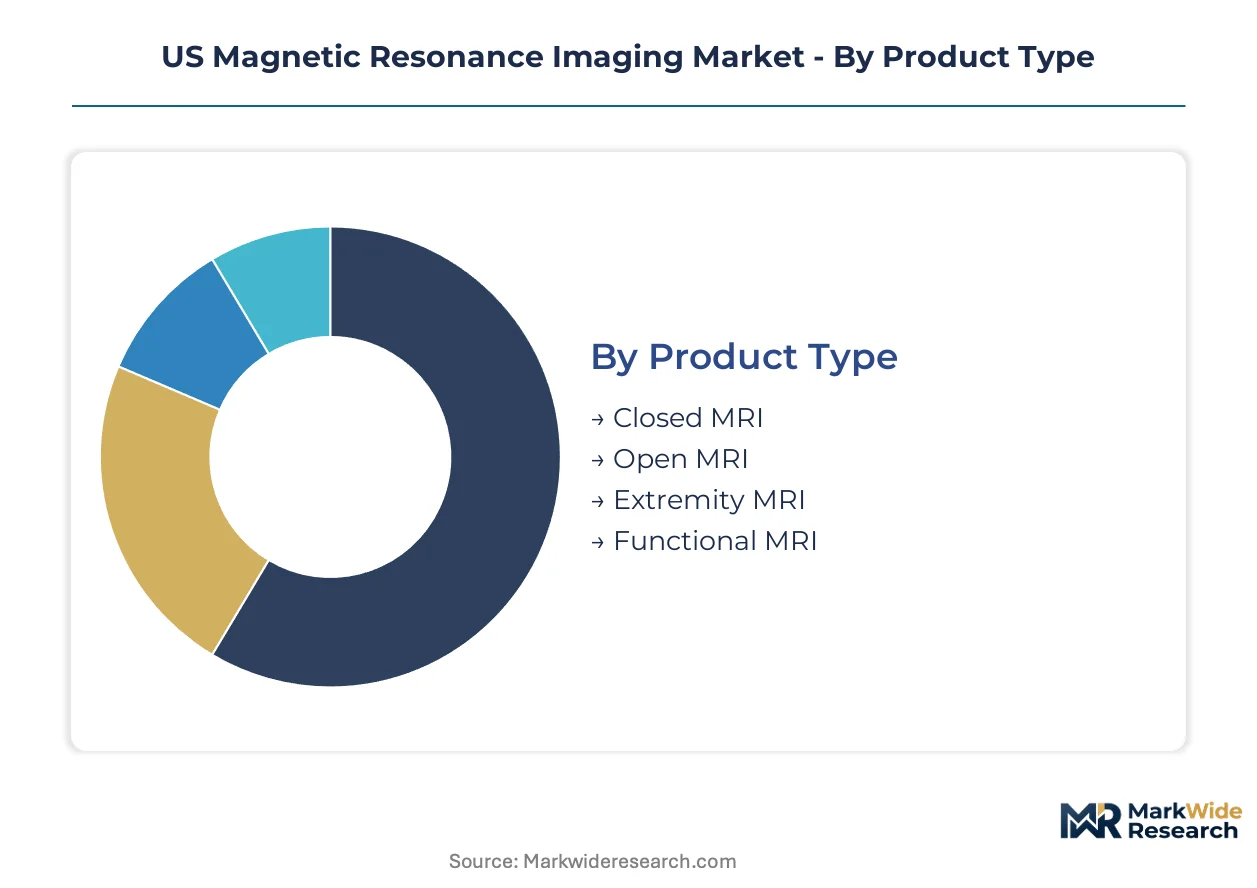
Standardization versus customization tensions define MRI procurement across US health systems. Field strength specifications, bore configurations, and software architectures create distinct service line economics that reshape capital allocation priorities.
Product Type:
Customization intensity varies sharply across this category, from fully configurable research platforms to fixed-configuration extremity units.
- Closed MRI:Superconducting cylindrical bore systems generate 1.5 to 3 Tesla field strengths with active shielding. Hospital networks in Texas and California standardize on 3 Tesla platforms for neurovascular throughput, though claustrophobia exclusions cap addressable patient volume at 10-15%.
- Open MRI:Vertical-field or C-shaped magnet geometries eliminate enclosed bore constraints. Demand concentrates in Florida ambulatory surgery centers serving bariatric and pediatric populations where patient comfort drives referral loyalty.
- Extremity MRI:Dedicated limb imaging systems operate at lower field strengths with targeted coil arrays. Orthopedic-focused surgery centers in California deploy these for wrist, knee, and ankle protocols.
- Functional MRI:Blood-oxygen-level-dependent imaging sequences map neural activation patterns. Academic medical centers in Massachusetts and Pennsylvania utilize these for pre-surgical eloquent cortex mapping.
Most installed capacity flows through Closed MRI. Expansion is steepest in Extremity MRI.
End User:
Procurement authority and total-cost-of-ownership metrics diverge across institutional scales in this category.
- Hospitals:Integrated delivery networks consolidate fleet standardization across multi-site radiology operations. Large health systems in Texas anchor centralized magnet maintenance contracts and AI-embedded reconstruction software subscriptions.
- Imaging Centers:Independent diagnostic facilities optimize throughput per square foot with extended operating hours. Certificate-of-need exemptions in rural hospital zones enable equipment deployment without incumbent protection.
- Research Institutions:Academic medical centers prioritize 7 Tesla ultra-high-field systems for spectroscopy applications. NIH-funded neuroscience programs in Massachusetts drive specialized magnet procurement.
- Diagnostic Laboratories:Reference laboratory networks integrate MRI with multi-modal pathology workflows. Federally qualified health center referrals in Florida expand outpatient imaging migration into this channel.
Hospitals retain the dominant installed base. Imaging Centers are gaining share fastest through ambulatory surgery center partnerships.
Technology:
Supply chain risk and operating cost structures create divergent deployment economics across magnet architectures.
- Superconducting MRI:Niobium-titanium coil windings operate at 4 Kelvin with liquid helium cryogen baths. FDA 510(k) clearance pathways govern new system introductions while helium scarcity from Qatar and Algeria concentrates creates price volatility.
- Permanent Magnet MRI:Ferrite or rare-earth magnetic assemblies require zero cryogenic cooling. Lower-field musculoskeletal applications in Illinois and New York address supply chain risk through helium-free designs.
- Hybrid MRI:Combined PET-MRI or CT-MRI configurations enable simultaneous functional and anatomical imaging. Oncology departments at academic medical centers deploy these for radiation therapy planning.
- Pulsed Gradient MRI:Advanced diffusion-weighted imaging sequences require specialized gradient coil engineering. Neuroimaging protocols for stroke triage drive adoption in Pennsylvania emergency departments.
Superconducting MRI dominates current installations. Permanent Magnet MRI is climbing the fastest as helium supply restructuring accelerates.
Application:
Reimbursement intensity and scan protocol complexity shape capital commitment cycles across clinical specialties.
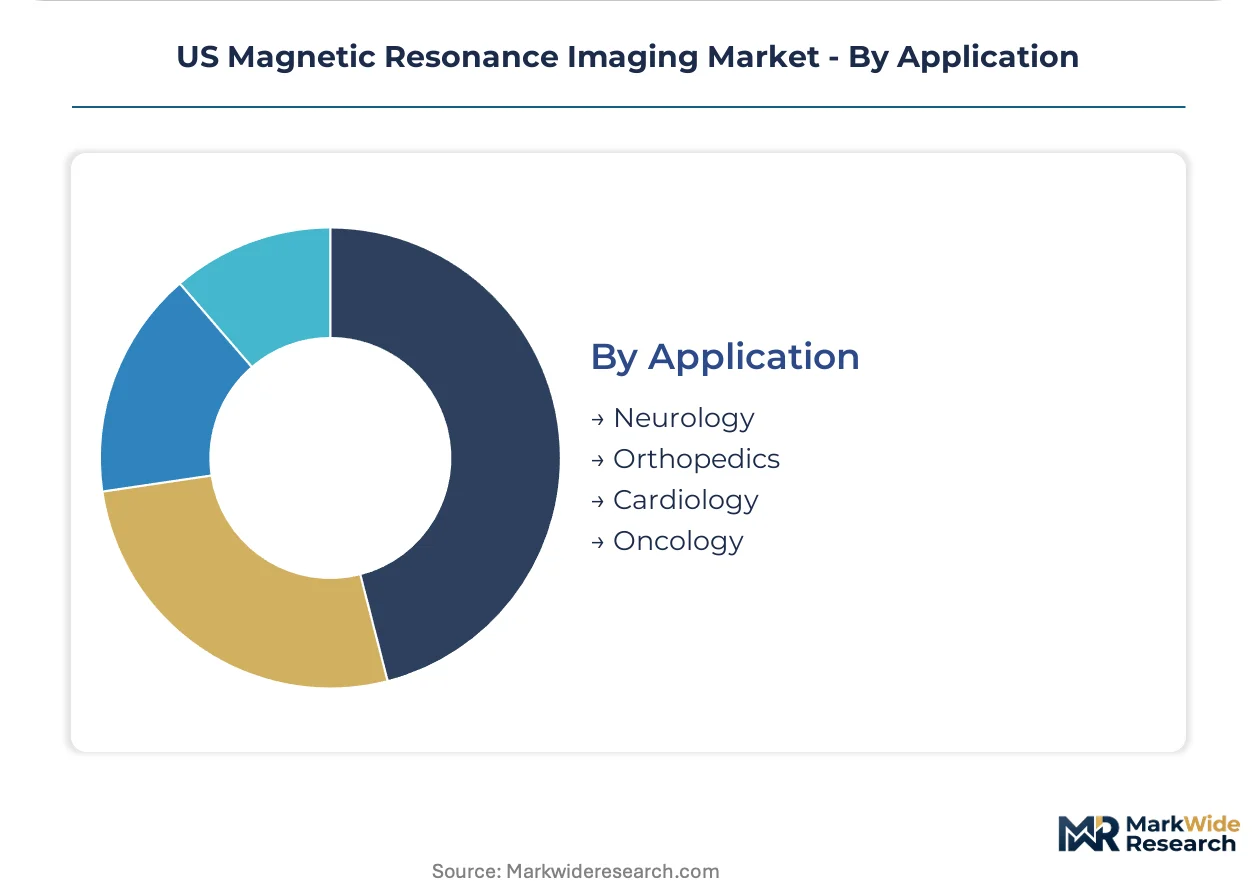
- Neurology:High-resolution brain imaging for tumor, stroke, and demyelinating disease protocols. CMS physician fee schedule updates directly influence imaging center capital commitment cycles for this segment.
- Orthopedics:Cartilage, ligament, and bone marrow imaging for sports medicine and joint replacement planning. Extremity MRI specialization serves ambulatory surgery center networks in California.
- Cardiology:Cardiac MRI with cine sequences and late gadolinium enhancement. Technical complexity limits deployment to academic medical centers with specialized training programs.
- Oncology:Staging and treatment response assessment across solid tumor types. Hybrid PET-MRI configurations enable simultaneous metabolic and anatomical characterization.
Neurology commands the largest procedure volume. Orthopedics shows the steepest expansion trajectory through outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways and CMS reimbursement adjustments create compliance-cost arbitrage that concentrates MRI procurement in states with certificate-of-need exemptions and favorable reimbursement climates. Health systems migrate capital deployment toward jurisdictions where regulatory friction is lowest.
Texas
Integrated delivery networks in Houston and Dallas anchor multi-site radiology standardization around 3 Tesla platforms. Rural hospital exceptions under state CON regulations enable equipment deployment without incumbent protection. Ambulatory surgery centers in the Texas Medical Center corridor capture federally qualified health center referrals through extended operating hours.
California
Orthopedic-focused surgery centers in Los Angeles and San Francisco Bay Area deploy extremity MRI systems for wrist, knee, and ankle protocols. Kaiser Permanente and Sutter Health consolidate fleet procurement across northern and southern regions. Academic medical centers at Stanford and UCLA drive 7 Tesla ultra-high-field research installations.
Florida
Bariatric and pediatric patient populations in Miami and Tampa fuel open MRI demand where patient comfort drives referral loyalty. CON exemptions for rural hospitals accelerate equipment placement in the Panhandle. Federally qualified health center partnerships expand outpatient imaging migration into diagnostic laboratory networks.
Massachusetts
NIH-funded neuroscience programs at Harvard-affiliated hospitals anchor specialized magnet procurement for functional MRI applications. Portable low-field MRI pilots at Boston academic medical centers accelerate stroke protocol triage. FDA software-as-a-medical-device guidance shapes AI diagnostic deployment pathways through predetermined change control plans.
Pennsylvania
Neurology departments in Philadelphia and Pittsburgh adopt pulsed gradient MRI for emergency department stroke triage. Cloud-based image reconstruction enables rural hospital teleradiology partnerships with academic medical centers. Third-party independent service organizations capture magnet cryogen management contracts from original equipment manufacturers.
US Magnetic Resonance Imaging Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with superconducting magnet supply chain control determining vendor stickiness. Three to five original equipment manufacturers anchor hospital procurement through installed-base loyalty programs. Strategic archetypes include magnet technology specialists, AI-embedded software integrators, and extremity-focused niche players. Competitive moves concentrate on after-sales service unbundling and third-party service organization partnerships.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify scale-driven archetypes with integrated magnet and software portfolios. Canon Medical Systems occupies a position within the specialization tier focused on orthopedic imaging configurations. Hyperfine, Inc. represents the portable low-field disruption vector with battery-powered bedside deployment systems.
| Leading Market Players |
|---|
| Canon Medical Systems |
| United Imaging Healthcare |
| Siemens Healthineers |
| Fonar Corp. |
| Hitachi |
| GE Healthcare |
| FUJIFILM |
| Hyperfine, Inc. |
| Koninklijke Philips |
| Others |
Cost & Logistics Intelligence
Helium spot price volatility from Qatar and Algeria cascades through superconducting magnet manufacturing into three-tier pricing structures across premium 3 Tesla hospital systems, standard 1.5 Tesla imaging centers, and economy-tier permanent magnet extremity units. CMS reimbursement compression forces buyers toward total-cost-of-ownership metrics that privilege service bundling over upfront capital expenditure.
Pricing Analysis
Original equipment manufacturer direct-to-hospital discounts compress distributor margins while third-party independent service organizations capture aftermarket cryogen management contracts. Three-tier pricing structure across premium, standard, and economy levels reflects field strength differentiation, with 7 Tesla research systems commanding brand premiums and open MRI architectures discounting for bariatric accessibility. Pricing pressure stems from helium supply scarcity forcing buyers toward zero-helium permanent magnet alternatives. Federally qualified health center partnerships exhibit highest price sensitivity; academic medical centers with NIH funding show lowest.
Supply Chain Analysis
Refurbished magnet cores and remanufactured gradient coil assemblies flow back to specialized foundries in Germany, Japan, and the United States for requalification and redeployment. Niobium-titanium superconductor wire, liquid helium cryogen, and rare-earth magnetic materials anchor raw material dependencies. Single-source vulnerability concentrates in Qatar-Algeria helium extraction. Distribution runs through integrated delivery network centralized procurement with multi-site standardization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Magnetic Resonance Imaging Market represents a late-cycle quality story as hospital networks consolidate procurement around AI-embedded reconstruction platforms that reduce scan durations and improve throughput economics. Demand shifts toward 3 Tesla specifications with active shielding and deep learning software integration.
For Market Incumbents: Cement installed-base loyalty through superconducting magnet supply chain control and AI-embedded reconstruction software subscriptions that lock in multi-site standardization. Defend against portable low-field disruption by accelerating FDA 510(k) pathways for bedside deployment systems. Prioritize backward integration into niobium-titanium coil winding capacity to secure magnet manufacturing against foundry concentration risk. For New Entrants and Emerging Players: Rural hospital exceptions under state certificate-of-need regulations offer underserved buyer archetypes with expedited equipment deployment timelines and reduced competitive friction. Target ambulatory surgery center networks in Texas and Florida seeking extremity MRI specialization for orthopedic protocols. Pursue cloud-based image reconstruction partnerships with academic medical centers as go-to-market validation. For Investors and Strategic Acquirers: Consolidation pressure builds where third-party independent service organizations fragment aftermarket revenue streams previously captured by original equipment manufacturers. Five-to-ten year viability favors vendors with helium-free magnet architectures and FDA software-as-a-medical-device clearance pathways. Monitor CMS physician fee schedule updates for neuroimaging reimbursement codes as inflection indicator for imaging center capital commitment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Development | Zero-cryogen designs address Qatar-Algeria supply concentration for lower-field musculoskeletal applications. |
| FDA 510(k) AI Software Submission | Predetermined change control plans for machine learning algorithms accelerate diagnostic deployment timelines. |
| Hospital System Partnership | Integrated delivery network fleet standardization locks in multi-site maintenance and software subscription revenue. |
| Third-Party Service Organization Alliance | Cryogen management outsourcing captures aftermarket revenue from original equipment manufacturer unbundling. |
| Reimbursement Strategy | CMS physician fee schedule navigation directly influences imaging center capital commitment cycle timing. |
Research Approach
Bottom-up hospital and imaging center procurement modeling reconciled against top-down superconducting magnet production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and radiology department chairs combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare physician fee schedule archives, and hospital procurement system records. Triangulation across stakeholder inputs and regulatory filings ensures segment-level precision.
Input-output matrices map niobium-titanium superconductor supply through magnet manufacturing to end-use deployment across field strength tiers, bore configurations, and software architectures. Segmentation dimensions include product type, end user institution scale, magnet technology, and clinical application with geographic clustering by state regulatory environment. CAGRs derive from equipment shipment tracking and reimbursement-adjusted utilization rates. Forecast inputs incorporate helium supply restructuring timelines and AI diagnostic billing code development trajectories.
Underlying measurement precision varies by segment; closed MRI and hospital end-use categories carry tighter precision than emerging portable low-field and research institution segments. Forecasts reflect assumptions around CMS reimbursement stability and FDA software-as-a-medical-device guidance evolution. Practitioners should monitor certificate-of-need exemption expansions and helium spot price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
North America Digital Pathology Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Ultrasound Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Robotic X-Ray Scanner Market