
 Dental Implantology Software Market | 2026-2036
Dental Implantology Software Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Implantology Software Market Outlook
Subscription-based access to AI-powered treatment planning modules is realigning how dental software vendors monetize clinical workflows. 3Shape leverages its scanner-to-software ecosystem to anchor digital impression pipelines across European dental laboratories. Straumann Group competes through vertical control over implant hardware and companion planning software. Planmeca sustains Nordic market dominance with integrated CBCT-to-surgery navigation platforms.
Dental implantology software comprises specialized applications that process three-dimensional radiographic datasets to design osteotomy trajectories, abutment selections, and prosthetic restorations with submillimeter precision. These systems interface with intraoral scanners, cone-beam computed tomography units, and computer-aided manufacturing equipment to execute digitally guided implant placement. Cloud-based platforms represent the fastest-expanding deployment mode as practices seek reduced capital expenditure and remote collaboration with dental laboratories. Treatment planning applications command concentrated margin pools because regulatory validation requirements for surgical guidance create defensible competitive moats. Software-as-a-Service delivery is displacing perpetual licensing in mid-sized dental group practices across North America and Western Europe.
FDA software-as-a-medical-device oversight and the EU Medical Device Regulation impose clinical evidence thresholds on surgical planning algorithms, elevating compliance costs for entrants while protecting established vendors with quality management infrastructure. ISO 13485 certification and IEC 62304 software lifecycle standards function as baseline market access requirements for commercial distribution in regulated jurisdictions. Stakeholders must monitor evolving predicate device pathways for AI-augmented outcome prediction tools as regulatory science struggles to keep pace with machine learning model iteration cycles.
Market Dynamics
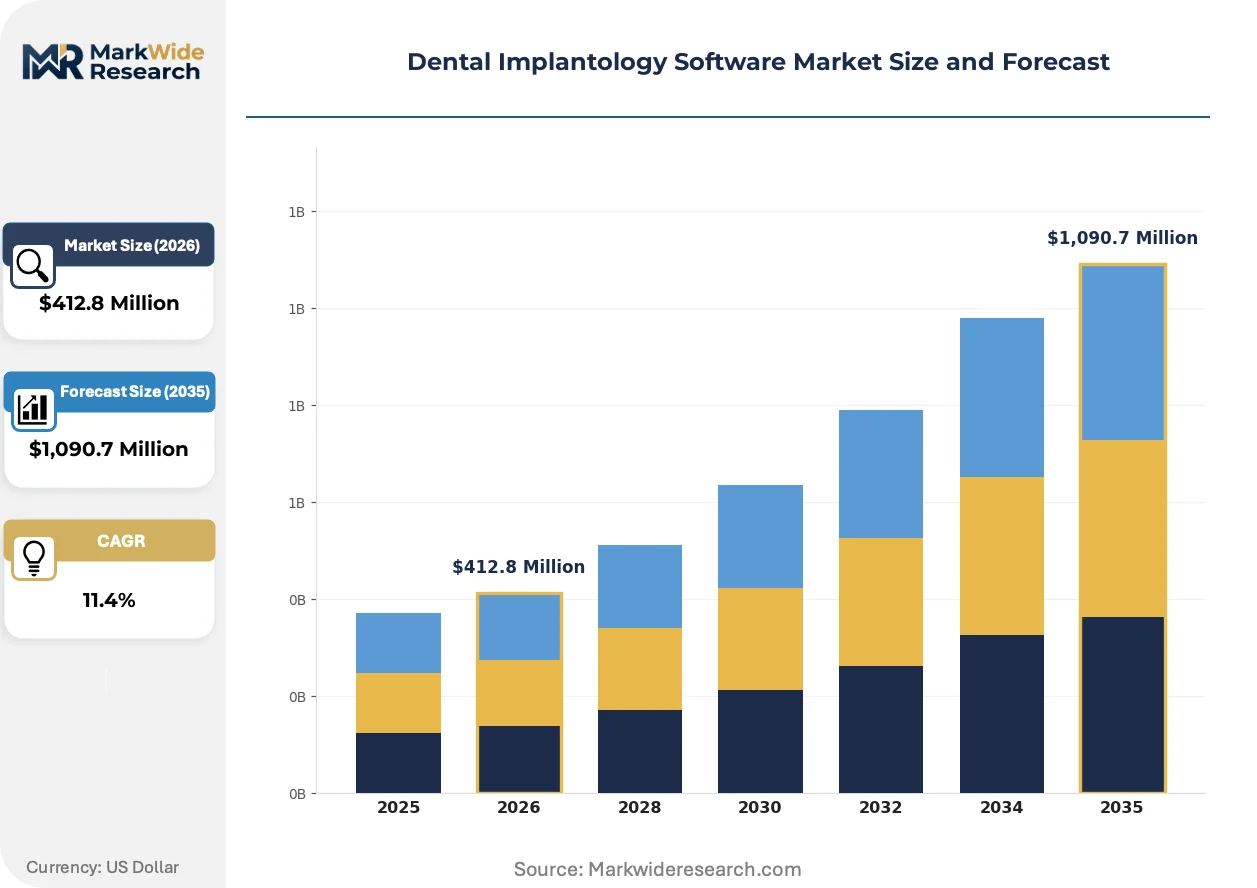
Cloud-based delivery models are restructuring capital deployment across dental practices, converting upfront license purchases into recurring operational expenditures while compressing implementation timelines from months to weeks.
Growth Catalysts
- FDA Software-as-a-Medical-Device guidance:The framework clarifies validation pathways for surgical planning algorithms, accelerating regulatory submissions from established vendors with quality management infrastructure already in place.
- Cone-beam computed tomography unit proliferation:Dental clinics in Germany, the United States, and South Korea are deploying CBCT hardware at accelerating rates, creating captive demand for companion treatment planning software.
- Digital impression pipeline maturation:Intraoral scanner adoption in European dental laboratories is generating structured datasets that feed directly into implant planning modules, reducing manual data entry friction.
Market Restraints
- ISO 13485 certification costs:Small software developers face six-figure quality management system investments before commercial distribution becomes legally permissible in regulated jurisdictions.
- EU Medical Device Regulation transition:The MDR's tightened clinical evidence thresholds for surgical guidance tools have extended time-to-market for new algorithmic features by twelve to eighteen months.
- Legacy hardware incompatibility:Practices with five-plus-year-old CBCT units encounter integration failures with modern cloud-native planning platforms, forcing premature capital equipment replacement.
Strategic Opportunities
- Mid-sized dental group practices:North American and Western European multi-location chains represent underpenetrated SaaS subscribers seeking centralized treatment planning oversight across distributed clinical sites.
- AI-augmented outcome prediction:Machine learning models trained on longitudinal implant survival datasets are converging with real-time surgical navigation, opening premium pricing tiers for predictive analytics modules.
- Remote laboratory collaboration:Cloud platforms enable asynchronous case review between clinicians and dental technicians, reducing chair time and expanding addressable markets for laboratory service providers.
Industry Challenges
- IEC 62304 software lifecycle compliance:Development teams must document traceability matrices linking requirements to verification activities, consuming engineering resources that otherwise advance feature development.
- Interoperability certification bottlenecks:DICOM-RT and STL format validation across scanner, planning, and milling equipment vendors creates integration testing backlogs that delay product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Implantology Software Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $1,090.7 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Imaging, Software-as-a-Service, Treatment Planning, Digital Workflow End User: Dental Clinics, Oral Surgeons, Orthodontists, Research Institutions Technology: AI-Powered Solutions, Augmented Reality, Cloud-Based Platforms, Virtual Simulation Application: Patient Management, Treatment Simulation, Surgical Planning, Outcome Prediction |
| Companies Covered | Planmeca, Blue Sky Bio, 3Shape, CareStack, Adit, Dentsply Sirona, Exocad, Dental Wings, Straumann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Implantology Software Market Strategic Shifts
Artificial intelligence architectures are penetrating treatment planning workflows at the point of diagnostic interpretation, compressing radiographic analysis timelines while elevating precision thresholds for osteotomy trajectory design.
Real-time surgical navigation systems are integrating haptic feedback mechanisms with augmented reality overlays, allowing implantologists to visualize drill depth and angulation without diverting attention from the operative field. Academic medical centers in South Korea and university hospitals in Germany are piloting these platforms for complex full-arch reconstructions. The technology is integrating previously separate hardware categories—tracking arrays, display systems, and instrument calibration—into unified ergonomic consoles that reduce cognitive load during procedures.
The EU Medical Device Regulation's classification of AI-augmented planning software as Class IIa or higher devices imposes notified body involvement for algorithmic updates that modify clinical outputs. Manufacturers must submit substantial equivalence documentation for each model iteration, creating friction between machine learning development velocity and regulatory review cadence. European vendors with established quality management infrastructure are responding by partitioning AI modules into locked, validated versions rather than continuous deployment pipelines.
Subscription pricing for treatment planning modules is displacing perpetual licenses in mid-sized dental group practices across North America and Western Europe. Finance departments prefer operational expenditure classification for software costs, while clinical directors value automatic feature updates without capital approval cycles. This shift is most visible in United States-based dental service organizations managing fifty-plus locations, where centralized procurement negotiates enterprise agreements spanning hundreds of practitioner seats.
Dental Implantology Software Market Segmentation
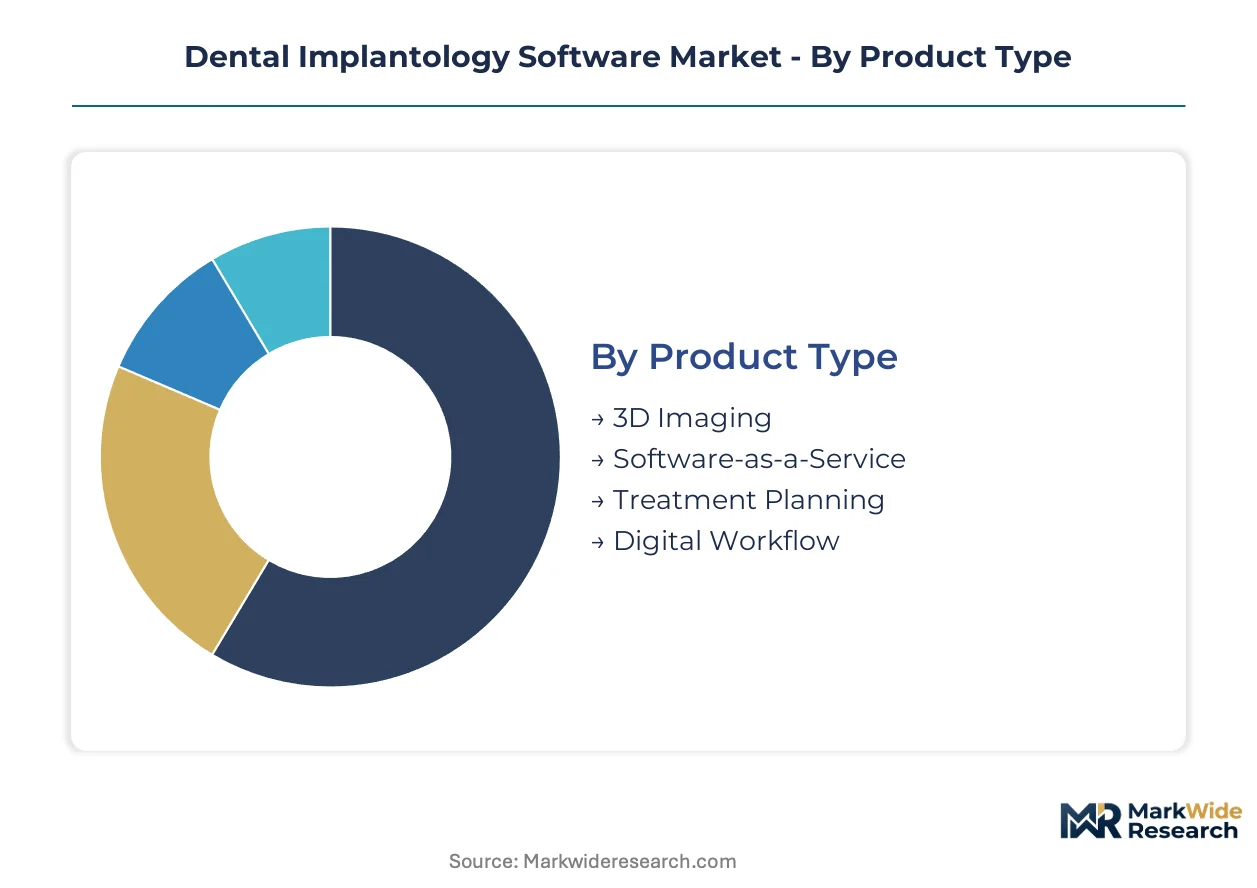
Dental implantology software segments reflect divergent upgrade cycles across hardware-tethered imaging systems and cloud-native delivery modes. Vendors calibrate R&D investment toward categories where replacement timelines compress and regulatory validation creates sustainable margin structures.
Product Type:
Upgrade cycles vary dramatically between capital-intensive imaging hardware and subscription-based software tiers, with replacement decisions tied to CBCT depreciation schedules and SaaS contract renewals.
- 3D Imaging:Cone-beam computed tomography reconstruction algorithms process DICOM datasets into volumetric renderings for bone density assessment and nerve canal mapping. Demand concentrates in Germany and South Korea where dental clinics replace CBCT units on accelerated five-year cycles driven by MFDS and German KBA-equivalent technical standards evolution.
- Software-as-a-Service:Cloud-hosted treatment planning modules eliminate local server infrastructure while enabling remote laboratory collaboration. Mid-sized dental group practices in the United States favor SaaS procurement for operational expenditure classification and centralized multi-location oversight.
- Treatment Planning:Osteotomy trajectory design applications interface with intraoral scanners and surgical guides for submillimeter placement precision.
- Digital Workflow:End-to-end platforms integrate impression capture, prosthetic design, and manufacturing coordination across distributed clinical sites.
Treatment Planning sits at the top of the volume ranking, with Software-as-a-Service climbing the fastest.
End User:
Customer procurement authority differs across solo practitioners, institutional purchasers, and academic research centers, shaping pricing architecture and sales cycle duration.
- Dental Clinics:General practice settings generate the highest seat volume for cloud-based planning tools, with purchasing decisions driven by chair-time efficiency and laboratory collaboration requirements. United States-based dental service organizations negotiate enterprise agreements spanning fifty-plus locations.
- Oral Surgeons:Specialist practitioners command premium pricing for surgical navigation integration and real-time haptic feedback systems. Academic medical centers in South Korea pilot augmented reality overlays for complex full-arch reconstructions.
- Orthodontists:Tooth movement simulation and interdisciplinary implant coordination drive specialized module adoption.
- Research Institutions:Longitudinal outcome datasets and algorithmic validation studies create non-commercial demand for predictive analytics tools.
Dental Clinics dominate absolute seat deployment, with Oral Surgeons expanding most quickly on a revenue-per-user basis.
Technology:
Technology maturity curves separate commercially validated platforms from emerging modalities still navigating regulatory evidence thresholds.
- AI-Powered Solutions:Machine learning models trained on implant survival datasets automate radiographic interpretation and outcome probability scoring. FDA software-as-a-medical-device guidance and EU MDR Class IIa classification impose version-locking constraints that partition AI modules into validated releases rather than continuous deployment.
- Cloud-Based Platforms:Browser-accessible planning environments reduce implementation timelines from months to weeks while converting capital expenditure to recurring operational spend. Western European multi-location chains prioritize cloud procurement for automatic feature updates without capital approval cycles.
- Augmented Reality:Real-time surgical overlays with haptic feedback mechanisms integrate drill depth visualization without operative field diversion.
- Virtual Simulation:Preoperative rehearsal environments enable prosthetic outcome preview and patient communication.
Cloud-Based Platforms capture the broadest installed base, while AI-Powered Solutions gain share fastest among premium-tier purchasers.
Application:
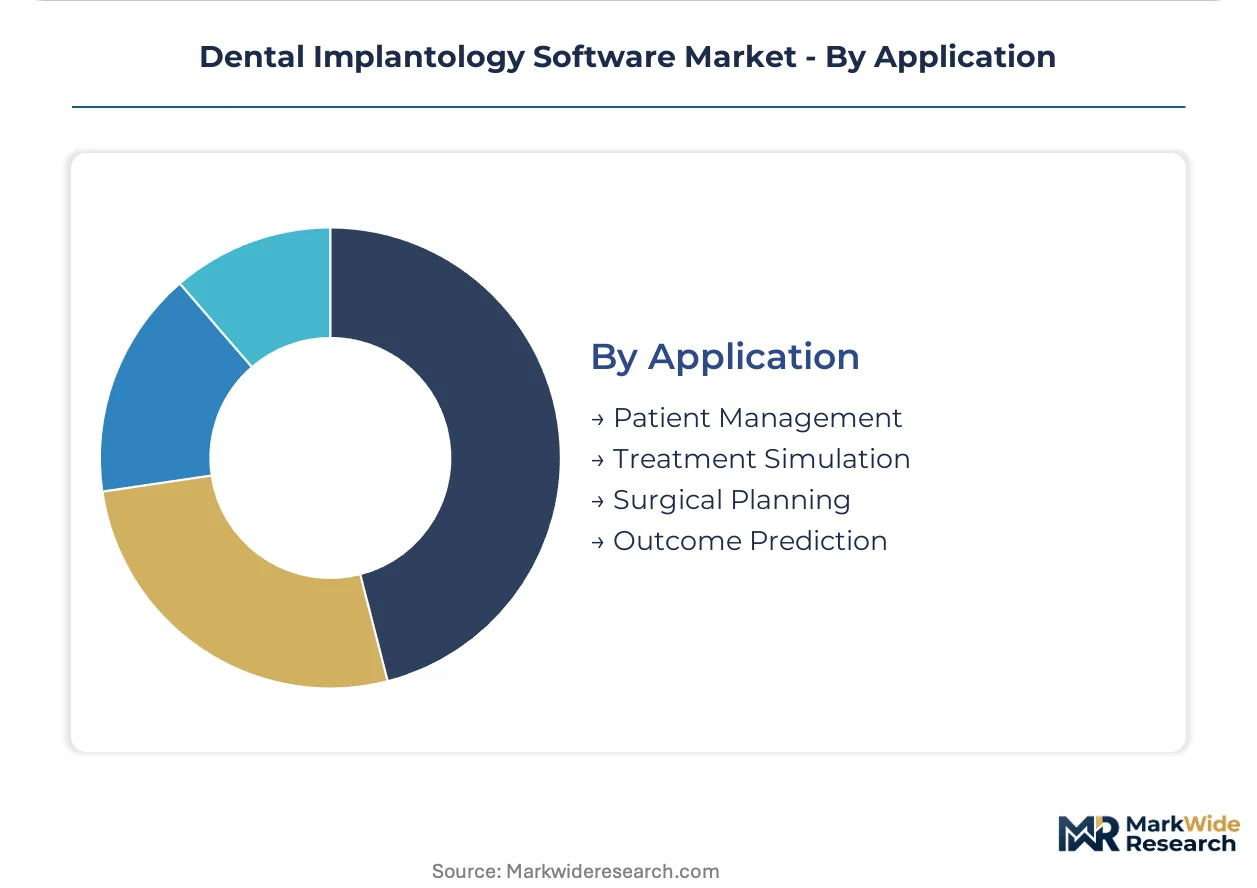
Application modules align with distinct clinical workflow stages, from initial patient intake through postoperative surveillance.
- Surgical Planning:Osteotomy design, abutment selection, and guide fabrication modules command concentrated margin pools due to ISO 13485 and IEC 62304 validation requirements. Regulatory moats protect established vendors with quality management infrastructure in place.
- Treatment Simulation:Visual prosthetic preview and patient communication tools reduce case acceptance friction and informed consent documentation burden. German university hospitals integrate simulation modules into predoctoral training curricula.
- Patient Management:Electronic health record integration and appointment scheduling coordinate implant case logistics.
- Outcome Prediction:Longitudinal survival modeling and risk stratification algorithms support evidence-based treatment selection.
Surgical Planning leads category revenue, with Outcome Prediction showing the steepest expansion trajectory as predictive analytics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dental clinics outpace German laboratories in cloud-platform adoption, while South Korean academic centers drive surgical navigation innovation. Each market shapes distinct procurement patterns and regulatory compliance burdens.
United States
Dental service organizations managing fifty-plus locations negotiate enterprise SaaS agreements for centralized treatment planning oversight. FDA software-as-a-medical-device guidance clarifies validation pathways for surgical planning algorithms, accelerating submissions from established vendors. The Greater Boston corridor hosts multiple digital dentistry startups developing AI-augmented diagnostic tools.
Germany
Dental laboratories in Bavaria and North Rhine-Westphalia deploy intraoral scanners at accelerating rates, generating structured datasets for implant planning modules. EU Medical Device Regulation Class IIa classification imposes notified body involvement for algorithmic updates, extending time-to-market for new features. Berlin-Brandenburg university hospitals pilot augmented reality overlays for complex full-arch reconstructions.
South Korea
Academic medical centers in Seoul Capital Area pilot real-time surgical navigation with haptic feedback for complex cases. MFDS technical standards evolution drives accelerated five-year CBCT replacement cycles among Seoul-based dental clinics. Busan-Ulsan industrial clusters manufacture tracking arrays and display systems for integrated ergonomic consoles.
Switzerland
Cantonal dental associations in Zurich and Geneva promote ISO 13485-certified treatment planning platforms for quality assurance. Swissmedic oversight aligns with EU MDR requirements for surgical guidance software, creating streamlined market access. Basel-region precision engineering firms supply calibration instrumentation for surgical navigation hardware.
United Kingdom
London and Southeast England dental group practices favor subscription pricing for operational expenditure classification. MHRA recognition of FDA-cleared software reduces duplicate validation burdens for US-origin platforms. Midlands-based dental laboratories expand cloud collaboration with clinicians across distributed clinical sites.
Dental Implantology Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hardware-integrated vendors commanding premium positioning against pure-play software developers. The vendor base concentrates around three strategic archetypes: scanner-to-software ecosystem builders, implant hardware-to-planning vertical integrators, and cloud-native SaaS specialists. Dominant competitive moves include strategic partnerships between CBCT manufacturers and planning software vendors, plus portfolio diversification into AI-augmented outcome prediction modules.
Among Nordic-origin integrated platform developers, Planmeca occupies a position exemplifying CBCT-to-surgery navigation convergence. Danish scanner-to-software ecosystem builders include 3Shape, which represents the digital impression pipeline archetype. Swiss implant hardware-to-planning vertical integrators feature Straumann Group, sitting within the premium-tier vendor category that controls both surgical fixture supply and companion planning tools.
| Leading Market Players |
|---|
| Planmeca |
| Blue Sky Bio |
| 3Shape |
| CareStack |
| Adit |
| Dentsply Sirona |
| Exocad |
| Dental Wings |
| Straumann Group |
| Others |
Value Chain & Pricing Dynamics
Software engineering talent concentration in the Greater Boston corridor and Zurich-Brandenburg corridor creates labor-cost differentials that widen pricing-tier spreads between premium AI-augmented modules and standard cloud-based planning tools.
Pricing Analysis
Capacity additions in South Korea and Germany are reshaping price floors for surgical navigation hardware while subscription pricing for cloud-native treatment planning modules displaces perpetual licenses. Three-tier pricing structure across premium AI-augmented, standard cloud-based, and economy on-premise levels stratifies by ISO 13485 certification grade and FDA software-as-a-medical-device clearance status. Pricing pressure stems from mid-sized dental group practices in the United States consolidating procurement into enterprise SaaS agreements. Solo practitioners exhibit highest price sensitivity, while oral surgeons in academic medical centers demonstrate lowest sensitivity due to reimbursement structures.
Supply Chain Analysis
Workforce availability for precision optics and embedded systems engineering constrains manufacturing scale-up in Busan-Ulsan industrial clusters and Basel-region precision engineering hubs. Supply concentrates in South Korea, Germany, and Switzerland for tracking arrays, display systems, and calibration instrumentation. Component dependencies include CMOS sensors, optical tracking modules, and surgical-grade aluminum alloys. Single-source vulnerability for haptic feedback actuators sourced from Japanese suppliers creates exposure. Distribution runs through CBCT manufacturer bundling agreements and direct SaaS provisioning to dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Medical Device Regulation compliance costs in Germany exceed FDA software-as-a-medical-device pathway expenses in the United States by substantial margins, creating cost-advantaged entry points for US-origin platforms.
For Market Incumbents: Cement regulatory moats by accelerating ISO 13485-certified AI module version-locking ahead of EU MDR Class IIa classification enforcement. Deepen backward integration into CBCT hardware manufacturing to capture companion software demand from Seoul-based clinics replacing units on accelerated five-year cycles. Priority defensive moves center on quality management infrastructure investments that extend time-to-market for algorithmic challengers. For New Entrants and Emerging Players: Cloud-native SaaS routes into mid-sized dental group practices in the United States offer the most penetrable white-space target, with operational expenditure classification preferences and centralized multi-location oversight needs creating procurement openness. Target orthodontic interdisciplinary coordination modules as underserved application layer. Go-to-market leverage rests on DICOM-RT interoperability certification that bypasses legacy hardware integration failures. For Investors and Strategic Acquirers: Implant hardware-to-planning vertical integrators are the most active acquirer in this space, seeking AI-augmented outcome prediction capabilities to differentiate premium-tier offerings. Five-to-ten year viability hinges on regulatory science keeping pace with machine learning model iteration cycles. Acquisition target archetype: cloud-native SaaS specialists with FDA-cleared surgical planning algorithms and established dental service organization channel relationships. Signal to watch: notified body backlog duration for EU MDR algorithmic update submissions as inflection indicator for European market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Module Development | FDA software-as-a-medical-device guidance clarifies validation pathways for machine learning models trained on longitudinal implant survival datasets. |
| Cloud Platform Integration | Browser-accessible planning environments reduce implementation timelines for mid-sized dental group practices seeking operational expenditure classification. |
| Strategic Partnership with CBCT Manufacturers | Bundling agreements with cone-beam computed tomography unit vendors create captive demand for companion treatment planning software. |
| Acquisition of Surgical Navigation Specialist | Real-time haptic feedback and augmented reality overlay capabilities command premium pricing from oral surgeons in academic medical centers. |
| Geographic Expansion into South Korea | MFDS technical standards evolution drives accelerated hardware replacement cycles among Seoul-based dental clinics. |
Study Parameters
Direct dialogue with implantology software product managers, dental clinic IT procurement officers, CBCT manufacturer channel partners, and regulatory affairs specialists at notified bodies grounded qualitative findings. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation summaries, MFDS registration databases, and dental laboratory association technology adoption surveys. Bottom-up and top-down triangulation cross-checked vendor-reported seat deployments against CBCT unit shipment data and dental service organization enterprise agreement disclosures.
Bottom-up modeling aggregated deployment mode, end-user specialty, and technology maturity segment volumes across the analysis window, while top-down calibration applied macroeconomic healthcare IT expenditure patterns. CAGRs derived from logistic diffusion curves fitted to cloud-platform adoption rates and regulatory submission velocity trends. Forecast inputs incorporated ISO 13485 certification pipeline backlogs and AI model validation cycle durations specific to surgical planning algorithms.
The model assumes a particular technology adoption path; alternative pathways for augmented reality surgical navigation would alter the outlook if haptic feedback integration costs decline faster than projected. Forecasts reflect assumptions about EU MDR notified body capacity expansion and FDA software-as-a-medical-device guidance stability. Material deviation in MFDS technical standards evolution or dental service organization consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Asia Pacific Healthcare IT Market