
 Malocclusion Market | 2026-2036
Malocclusion Market Size, Share, and Industry Trends Forecast 2026-2036
Malocclusion Market Outlook
Digital intraoral scanning combined with AI-driven treatment planning is reshaping how orthodontic appliances are designed, manufactured, and delivered to patients. Align Technology leverages its proprietary thermoplastic material science and vertical software stack to sustain leadership in clear aligner production. 3M anchors its position through decades of bracket-and-wire innovation and deep channel relationships with orthodontic practices worldwide. Straumann Group differentiates by integrating digital dentistry platforms with its implant and orthodontic portfolios across European and Asian markets.
Malocclusion refers to misalignment between the upper and lower dental arches, measured by deviation from ideal occlusal contact as quantified by indices such as the Index of Orthodontic Treatment Need or the American Board of Orthodontics discrepancy index. Clear aligners, fabricated from medical-grade multilayer thermoplastic polymers through thermoforming or direct 3D printing, correct tooth position through sequential staging of controlled force application. The product type dimension shows aligners capturing the fastest expansion while braces retain volume in complex skeletal cases and pediatric protocols. Delivery mode insights reveal hybrid models combining in-office scanning with remote monitoring are displacing purely home-based approaches as clinicians seek liability protection and treatment fidelity.
The FDA regulates orthodontic devices as Class II medical products requiring 510(k) premarket notification, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations on aligner and bracket manufacturers. BIS certification in India and NMPA registration in China create divergent approval timelines that shape geographic launch sequencing for product portfolios. Stakeholders must monitor how regulatory convergence around software-as-medical-device classifications for AI planning tools will alter competitive barriers and compliance costs across key markets.
Market Dynamics
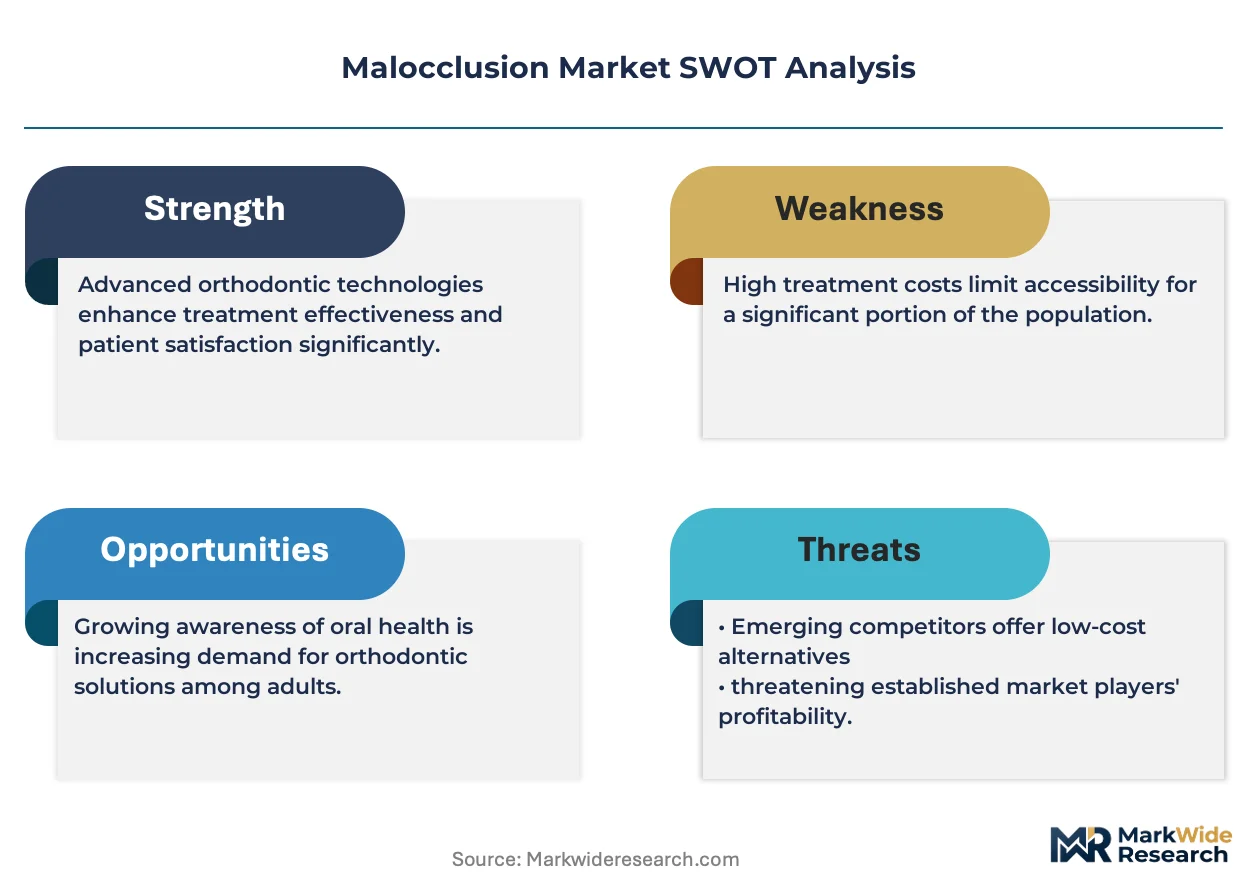
Digital intraoral scanning and AI-driven treatment planning are compressing the traditional orthodontic workflow from weeks to days, forcing incumbents to restructure service delivery models or cede volume to digitally native competitors.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for Class II orthodontic devices reduces time-to-market for novel aligner materials and remote monitoring platforms, encouraging R&D investment in thermoplastic polymer science.
- Teen patient segment expansion:Social media visibility of orthodontic outcomes drives parental willingness to pay for aesthetic alternatives to metal brackets, particularly in suburban United States dental markets.
- Hybrid delivery model maturation:In-office scanning combined with asynchronous remote monitoring satisfies liability-conscious clinicians while capturing convenience-seeking adults who resist frequent office visits.
Market Restraints
- Medical-grade PETG supply concentration:Specialized multilayer thermoplastic feedstock production centers on German and Japanese chemical suppliers, exposing aligner manufacturers to input cost volatility and currency risk.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for orthodontic devices extend certification timelines and inflate compliance staffing costs for CE marking renewals.
- Complex skeletal malocclusion treatment ceiling:Severe Class III cases with significant mandibular prognathism remain outside aligner biomechanical capability, preserving bracket-and-wire protocols for oral surgeons.
Strategic Opportunities
- India BIS certification arbitrage:Early movers securing Bureau of Indian Standards approval for clear aligner systems gain first-mover positioning in a dental market where orthodontic penetration lags China by a decade.
- AI treatment planning software-as-medical-device convergence:Regulatory clarity on autonomous staging algorithms creates white space for vendors bundling predictive outcome visualization with aligner fabrication.
- Direct-pay employer channel development:Self-insured corporations in the United States adding adult orthodontia to supplemental benefits packages bypass traditional insurance preauthorization friction.
Industry Challenges
- Orthodontic-digital technician skill hybridization:Clinics struggle to recruit staff fluent in both clinical biomechanics and 3D modeling software, creating treatment planning bottlenecks during scaling phases.
- NMPA registration timeline unpredictability:China's National Medical Products Administration review windows for imported aligner systems vary dramatically, complicating inventory and launch sequencing for multinational portfolios.
- Legacy practice management system integration:Established orthodontic offices running decade-old patient record platforms face costly middleware development to connect with cloud-based aligner ordering portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malocclusion Market |
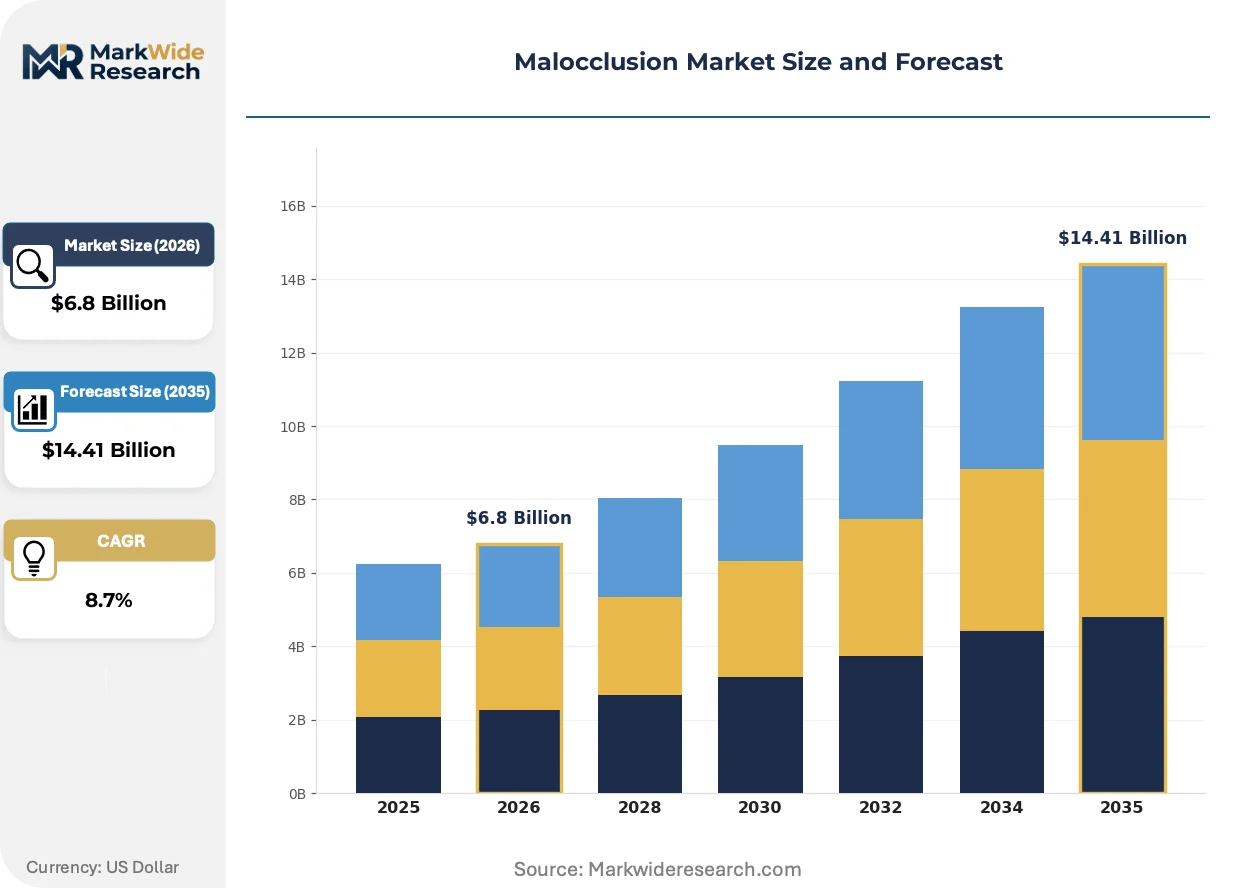
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Retainers, Aligners, Headgear Delivery Mode: In-Office, Home-Based, Online Consultation, Hybrid End User: Orthodontists, General Dentists, Specialists, Patients Age Group: Children, Teens, Adults, Seniors |
| Companies Covered | Align Technology, 3M, Dentsply Sirona, Ormco, Henry Schein, Straumann Group, Envista, 3Shape, Angel Aligner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malocclusion Market Strategic Shifts
Orthodontic appliance production is bifurcating between precision-manufactured clear systems and next-generation bracket architectures, with digital workflow penetration determining competitive survival across practice types.
Direct 3D printing of aligners from photopolymer resins is collapsing the thermoforming bottleneck that has constrained Align Technology's licensed manufacturer network for two decades. Independent dental laboratories in Germany and South Korea are adopting continuous liquid interface production systems to fabricate same-day aligner sets for local orthodontic practices. This distributed manufacturing model compresses shipping distances and enables same-appointment delivery workflows previously impossible with centralized thermoforming.
The EU Medical Device Regulation's 2021 enforcement transition is forcing orthodontic device manufacturers to rebuild clinical evidence dossiers for legacy aligner and bracket products originally cleared under the Medical Device Directive. Smaller European competitors lacking post-market surveillance infrastructure are exiting the aligner market rather than absorbing compliance costs. German orthodontic practices report extended backorders for certain bracket systems as manufacturers prioritize MDR remediation over production capacity.
Adult patients in the United States and China are unbundling orthodontic treatment from traditional insurance preauthorization workflows, paying out-of-pocket through installment financing platforms integrated directly into practice management software. This payment behavior shift bypasses the historical gatekeeper role of dental benefit administrators and compresses the decision cycle from consultation to treatment initiation. Urban practices in Shanghai and New York report average case acceptance intervals dropping by half compared to insurance-dependent patient cohorts.
Malocclusion Market Segmentation
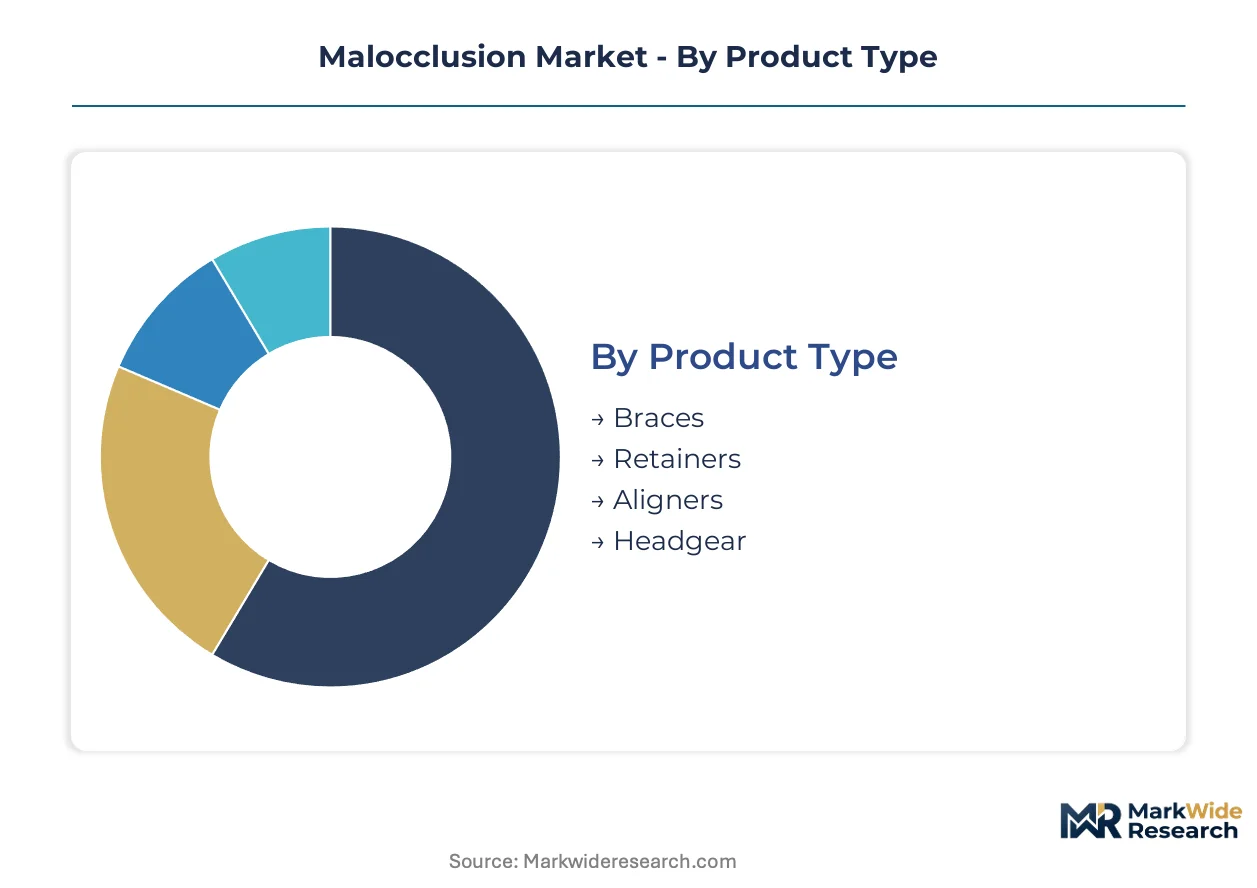
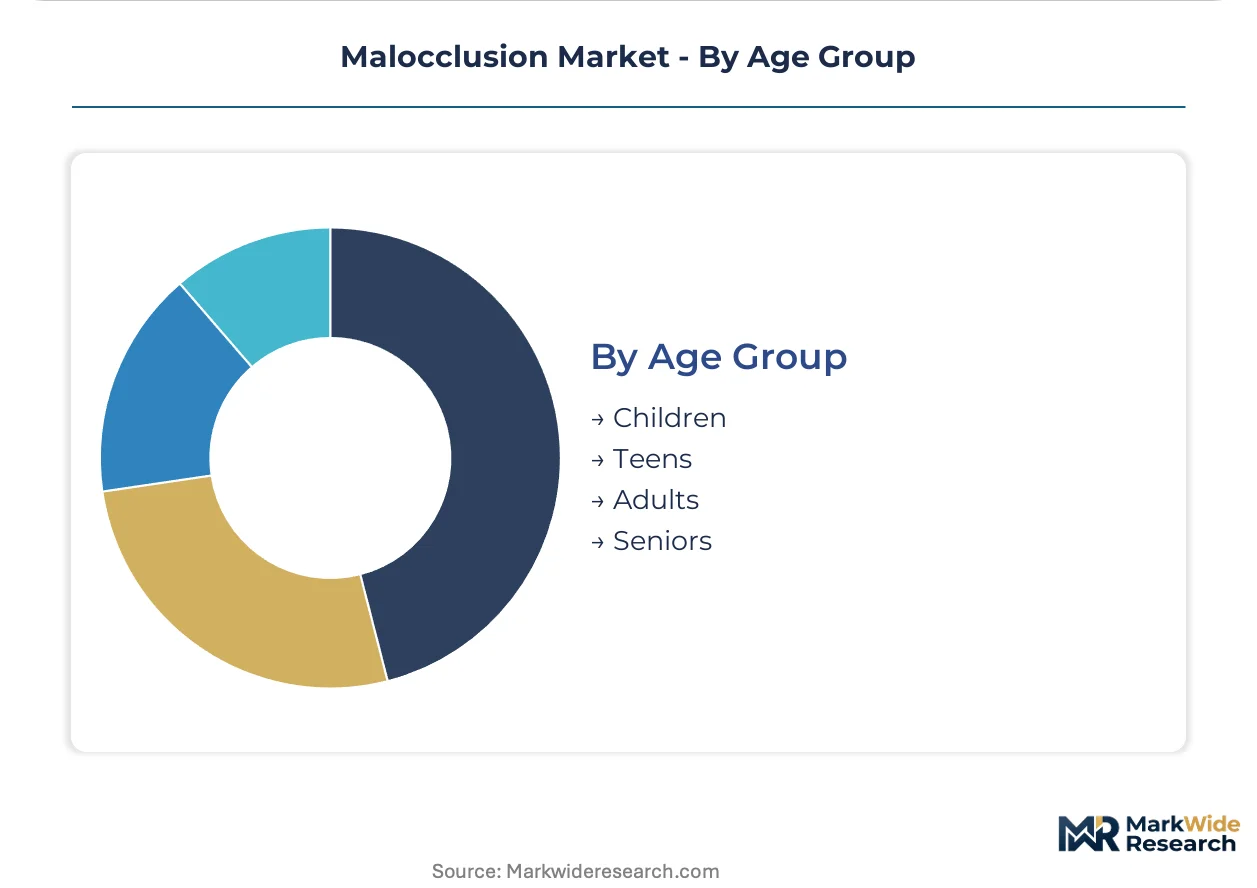
Orthodontic treatment modalities fragment across four structural dimensions that determine reimbursement pathways, regulatory classification, and channel economics. Product type and delivery mode classifications shape manufacturing scale requirements, while end-user and age group segments dictate marketing spend allocation and clinical training investments.
Product Type:
Material composition and biomechanical mechanism define cost structures and treatment duration across orthodontic appliance categories.
- Aligners:Medical-grade multilayer thermoplastic polymers deliver controlled force through sequential staging. Demand concentrates among image-conscious adults in suburban United States markets where direct-pay financing platforms bypass insurance preauthorization friction.
- Braces:Stainless steel or ceramic brackets bonded to enamel surfaces with archwire mechanics handle complex skeletal malocclusions. Volume persists in pediatric protocols and severe Class III cases where aligner biomechanical capability reaches its ceiling.
- Retainers:Removable Hawley or fixed lingual designs maintain post-treatment tooth position. Post-orthodontic compliance drives replacement cycles.
- Headgear:Extraoral anchorage appliances correct skeletal discrepancies through orthopedic force application. Restricted to growing patients with significant maxillary or mandibular disharmony.
Braces command the established base. The steepest expansion runs through aligners.
Delivery Mode:
Patient-clinician interaction intensity determines liability exposure and reimbursement coding complexity.
- Hybrid:Digital intraoral scanning combined with asynchronous remote monitoring balances convenience with clinical oversight. General dentists in Germany and China adopt this model to extend orthodontic services without full specialist training.
- In-Office:Traditional chairside diagnosis, appliance fitting, and adjustment protocols. Orthodontic practices in the United States maintain this as the default for teen patients where parental liability concerns predominate.
- Home-Based:Direct-to-consumer impression kits with remote treatment planning. Regulatory scrutiny from FDA and state dental boards constrains expansion.
- Online Consultation:Virtual triage and treatment simulation without physical examination. Serves as a lead generation funnel rather than standalone care delivery.
In-office retains volume leadership. Hybrid delivery gains share fastest as liability-conscious clinicians seek workflow efficiency.
End User:
Professional credential requirements and reimbursement authority create distinct purchasing behaviors across clinical settings.
- Orthodontists:Board-certified specialists with exclusive focus on malocclusion correction. Complex case volume and premium pricing power sustain their position as the highest-value channel.
- General Dentists:Primary care providers expanding into clear aligner therapy through manufacturer certification programs. Rural United States practices represent untapped penetration opportunity.
- Specialists:Oral surgeons and periodontists integrating orthodontic pre-prosthetic preparation. Implant-driven treatment planning creates aligner demand for space management.
- Patients:Self-directed purchasers through direct-to-consumer platforms. Financing integration and social media marketing drive conversion in urban China markets.
Orthodontists anchor premium pricing. General dentists represent the volume expansion frontier.
Age Group:
Skeletal maturation status determines treatment modality eligibility and biomechanical response characteristics.
- Teens:Mixed dentition through permanent dentition completion enables growth modification and comprehensive alignment. Parental payment authorization and social visibility of outcomes concentrate demand in United States suburban dental markets.
- Adults:Fully developed skeletal structures with aesthetic motivation driving discretionary spend. Direct-pay employer benefits and installment financing platforms accelerate case acceptance in corporate-heavy metropolitan areas.
- Children:Early interceptive protocols targeting habits and jaw discrepancies. Limited aligner suitability restricts volume to functional appliances and partial braces.
- Seniors:Pre-prosthetic alignment and periodontal stabilization cases. Medicare exclusion of adult orthodontia constrains penetration to affluent self-pay segments.
Teens sustain the core revenue base. Adults climb the fastest as workplace aesthetic expectations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent suburban parents drive orthodontic spend in the United States, while corporate employees in Shanghai and Beijing accelerate adult aligner adoption through employer-sponsored benefits. Urban professionals across Germany and China's coastal provinces are reshaping demand concentration.
United States
Teen patient volume concentrates in suburban dental markets where parental payment authorization meets social media visibility of treatment outcomes. FDA 510(k) clearance pathways streamline novel aligner material approvals, compressing time-to-market for thermoplastic innovations. The Dallas-Fort Worth metroplex hosts expanding orthodontic group practices adopting hybrid delivery models combining chairside scanning with remote monitoring platforms.
Germany
General dentists in Bavaria and North Rhine-Westphalia extend into clear aligner therapy through manufacturer certification programs, capturing patients outside specialist channels. EU MDR enforcement since 2021 imposes stricter clinical evidence requirements on orthodontic device manufacturers, extending CE marking timelines. The Stuttgart industrial corridor supplies specialized multilayer thermoplastic feedstock to aligner fabricators across Europe.
China
White-collar professionals in Shanghai and Shenzhen drive adult aligner demand through direct-pay financing platforms integrated into practice management software. NMPA registration timelines for imported aligner systems vary unpredictably, complicating launch sequencing for multinational portfolios. The Yangtze River Delta manufacturing cluster hosts domestic aligner producers scaling thermoforming capacity for regional distribution.
India
Orthodontic penetration lags China by approximately a decade, creating first-mover opportunity for BIS-certified clear aligner systems. Bureau of Indian Standards approval requirements diverge from FDA and EU frameworks, necessitating separate clinical dossier preparation. Mumbai and Delhi dental schools are expanding continuing education programs in digital orthodontic workflows to address technician skill gaps.
Japan
Aesthetic-conscious adults in Tokyo and Osaka metropolitan areas favor discreet orthodontic solutions compatible with professional workplace norms. PMDA marketing authorization for orthodontic devices maintains rigorous clinical trial expectations, favoring established manufacturers with post-market surveillance infrastructure. The Nagoya medical device manufacturing belt supplies precision components for bracket-and-wire systems distributed across Asia-Pacific markets.
Malocclusion Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated aligner manufacturers and diversified dental conglomerates. The vendor base separates into three strategic archetypes: thermoplastic material innovators with proprietary software stacks, bracket-and-wire incumbents leveraging decades of orthodontic practice relationships, and digital dentistry platforms integrating orthodontic modules with broader implant and restorative portfolios. Dominant competitive moves include M&A activity targeting AI treatment planning capabilities and strategic partnerships between aligner manufacturers and intraoral scanner producers to lock in digital workflow adoption.
Among North American orthodontic technology developers, Align Technology exemplifies the vertically integrated archetype combining material science with treatment planning software. German-Swiss dental conglomerates including Dentsply Sirona and Straumann Group occupy positions spanning digital impression systems through final appliance delivery. Henry Schein represents the distribution-centric model, anchoring channel access for both established bracket manufacturers and emerging aligner brands seeking orthodontic practice penetration.
| Leading Market Players |
|---|
| Align Technology |
| 3M |
| Dentsply Sirona |
| Ormco |
| Henry Schein |
| Straumann Group |
| Envista |
| 3Shape |
| Angel Aligner |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into landed cost spreads for German-manufactured multilayer thermoplastic feedstock, amplifying price differentiation between centralized thermoforming operations and emerging distributed 3D printing networks serving orthodontic practices.
Pricing Analysis
Cost-plus contracts with medical-grade PETG suppliers index to regional chemical commodity benchmarks, insulating aligner manufacturers from spot volatility while passing through currency-adjusted resin costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared systems with AI planning integration from basic thermoformed alternatives and unbranded dental laboratory outputs. Cost compression in the economy tier is intensifying because domestic Chinese producers are scaling thermoforming capacity for regional distribution. General dentists in rural United States markets exhibit highest price sensitivity, while board-certified orthodontists in suburban Dallas-Fort Worth corridors demonstrate lowest elasticity due to complex case premiums.
Supply Chain Analysis
Upstream feedstock for medical-grade multilayer thermoplastics draws from specialized polymer production centered in Germany, Japan, and the United States, with Stuttgart's industrial corridor supplying precision resin formulations to European aligner fabricators. Key component dependencies include photopolymer resins for direct 3D printing, nickel-titanium archwires for bracket systems, and cobalt-chrome alloys for fixed retainers. Single-source vulnerability concentrates in German chemical suppliers controlling proprietary multilayer extrusion patents. Distribution runs through orthodontic group purchasing organizations in the United States, manufacturer-certified dental laboratories in Germany, and direct hospital procurement channels in China's Yangtze River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malocclusion correction represents a high-growth disruption as AI-driven treatment planning software achieves regulatory clarity under FDA software-as-medical-device frameworks, collapsing the traditional orthodontic workflow from weeks to days.
For Market Incumbents: Build captive supply of medical-grade thermoplastic feedstock through backward integration into German or Japanese polymer production, securing margin protection against resin cost volatility while accelerating CE marking timelines under EU MDR post-market surveillance obligations. Incumbents must simultaneously lock in digital workflow adoption through exclusive intraoral scanner partnerships, defending against digitally native competitors offering same-day aligner delivery via distributed 3D printing networks. For New Entrants and Emerging Players: Build out BIS certification capabilities for the Indian orthodontic market, where Bureau of Indian Standards approval creates first-mover positioning in a dental market with orthodontic penetration lagging China by approximately a decade. White-space targets include employer-sponsored direct-pay channels in United States corporations adding adult orthodontia to supplemental benefits, and general dentist certification programs in rural markets bypassing specialist referral friction. A software-first go-to-market bundling predictive outcome visualization with aligner fabrication differentiates against hardware-centric incumbents. For Investors and Strategic Acquirers: AI treatment planning specialists with autonomous staging algorithms and existing FDA 510(k) clearances represent the most defensible acquisition archetype as regulatory convergence around software-as-medical-device classifications alters competitive barriers. Long-term viability in the five-to-ten-year window hinges on capturing orthodontic-digital technician hybrid talent pools and integrating cloud-based ordering portals with legacy practice management systems. The signal to watch is NMPA registration timeline compression for imported aligner systems in China, indicating regulatory pathway maturation for multinational portfolio expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Treatment Planning FDA Submission | Software-as-medical-device classification under FDA 510(k) creates competitive moats for autonomous staging algorithms. |
| EU MDR CE Marking Pathway | Post-market surveillance infrastructure investments separate compliant manufacturers from exiting European competitors. |
| Hospital System Partnership | Integrated dental service organizations in United States suburban markets lock in teen patient volume through exclusive aligner contracts. |
| Software Companion Development | Remote monitoring platforms bundled with aligner therapy satisfy liability-conscious clinicians in hybrid delivery models. |
| Reimbursement Strategy | Direct-pay employer channel development bypasses traditional insurance preauthorization friction in corporate-heavy metropolitan areas. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across orthodontic specialists, general dentists expanding into clear aligner therapy, dental laboratory technicians, and biomedical engineers at thermoplastic polymer manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR clinical evidence dossiers, NMPA registration filings, and orthodontic group purchasing organization contract disclosures. Bottom-up patient volume estimates by age segment and delivery mode were triangulated against top-down manufacturer shipment data across the analysis window.
Calibration against historical adoption curves for digital intraoral scanning and remote monitoring platforms anchored the projection framework. Segmentation dimensions modeled include product type, delivery mode, end-user credential requirements, and age group skeletal maturation status, with regional regulatory cluster effects incorporated for United States, Germany, China, and India. CAGRs were derived from slope-consistent growth trajectory analysis rather than endpoint anchoring, with AI treatment planning penetration rates and hybrid delivery model adoption curves serving as primary demand-side forecast inputs.
Stress conditions across NMPA registration timeline variability, medical-grade PETG supply disruption, and EU MDR compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory pathway stability and software-as-medical-device classification convergence. Cross-checking against orthodontic practice management system adoption benchmarks and dental school continuing education program expansion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Global Dentures Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Splints Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Veneers Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Handpieces Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Asia-Pacific Dental Aligners Market