
 Europe Dental Aligners Market | 2026-2036
Europe Dental Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Aligners Market Foresight
AI-driven treatment planning software is rewriting clinical workflows for European orthodontists, compressing case design timelines from weeks to days. Align Technology leverages proprietary algorithms to sustain its technology leadership across Western Europe. Institut Straumann AG anchors its position through backward integration into intraoral scanning hardware. Dentsply Sirona competes via open-architecture platforms that interoperate with third-party chairside systems.
Europe dental aligners are removable, transparent thermoplastic devices fabricated through multi-layer polyurethane or polyethylene terephthalate glycol (PETG) sheets, thermoformed over 3D-printed dental models to exert controlled orthodontic force. Their primary commercial purpose is aesthetic tooth movement without fixed metal appliances. Clear aligners lead product type revenue due to adult willingness to pay premium prices for invisible correction, while the home care end user segment grows fastest as direct-to-consumer models bypass traditional clinic gatekeepers. Teenagers remain the most volume-heavy age group, though young adults now drive margin expansion through complex case acceptance.
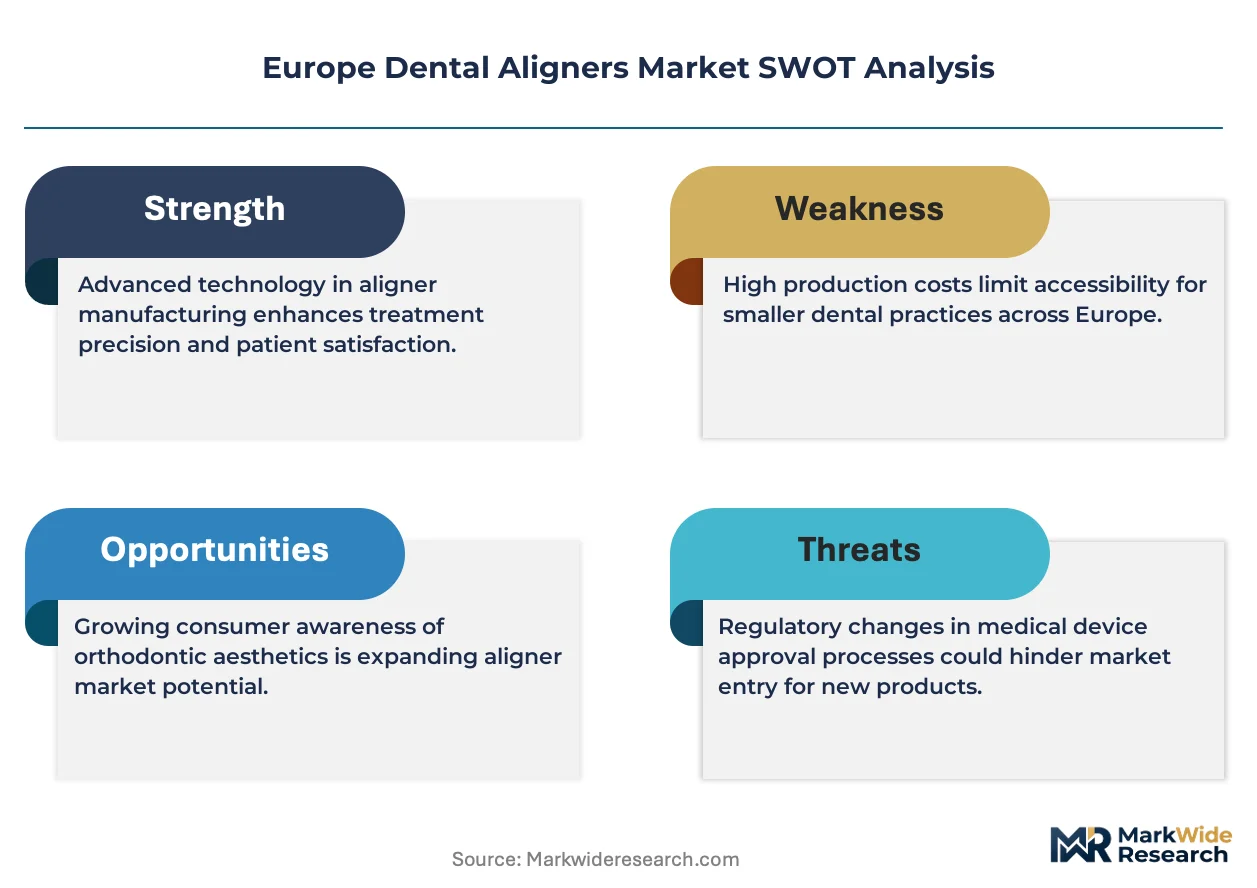
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies in Germany and France extending certification timelines for novel materials. GDPR constraints limit patient data flows across borders, complicating centralized AI training datasets for treatment algorithms. Stakeholders must monitor how national reimbursement bodies in Italy and Spain classify aligners relative to traditional orthodontic coverage, as this classification will determine addressable patient pools without reference to specific forecast years.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines for novel aligner materials while simultaneously elevating barriers to market entry, forcing manufacturers to recalibrate clinical evidence packages and notified body relationships across member states.
Growth Catalysts
- Adult aesthetic demand:Patients aged 25-45 in Germany and France are requesting invisible orthodontic correction at unprecedented rates, expanding addressable case complexity beyond traditional teen markets.
- AI treatment planning:Machine learning algorithms now automate tooth movement simulation, reducing orthodontist chair time and enabling case throughput expansion without proportional specialist hiring.
- CE marking harmonization:Mutual recognition of notified body assessments across EU member states is streamlining multi-country product launches, reducing redundant technical documentation burdens for manufacturers.
Market Restraints
- Polymer feedstock volatility:Medical-grade PETG and polyurethane sheet prices fluctuate with petrochemical indices, compressing gross margins for thermoforming-dependent production models.
- Notified body concentration:Germany and France host the majority of EU MDR-certified bodies for Class IIa devices, creating queue bottlenecks that extend time-to-market for new entrants.
- Fixed appliance substitution:Lingual braces and ceramic brackets retain cost advantages for severe malocclusions, limiting aligner penetration in complex orthodontic cases.
Strategic Opportunities
- Spanish reimbursement expansion:Regional health authorities in Catalonia and Andalusia are piloting aligner inclusion in public dental benefits, potentially unlocking subsidized patient volumes.
- Direct-to-consumer channels:Remote monitoring platforms paired with mail-order impression kits are bypassing traditional orthodontic gatekeepers, capturing price-sensitive segments in Italy and Poland.
- Intraoral scanner convergence:Chairside digital impression systems are integrating with cloud-based treatment planning, collapsing the traditional lab-mediated workflow into single-visit patient onboarding.
Industry Challenges
- Orthodontist training deficits:Clear aligner biomechanics requires distinct expertise from fixed appliance protocols, and European dental schools are graduating practitioners with uneven digital orthodontic preparation.
- GDPR-compliant data architecture:Cross-border patient record transfers for centralized AI model training confront fragmented national interpretations of data localization requirements, complicating algorithm development.
- Extended MDR clinical evidence timelines:Novel material submissions now require prospective clinical studies rather than equivalence arguments, stretching R&D-to-revenue cycles substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Aligners Market |
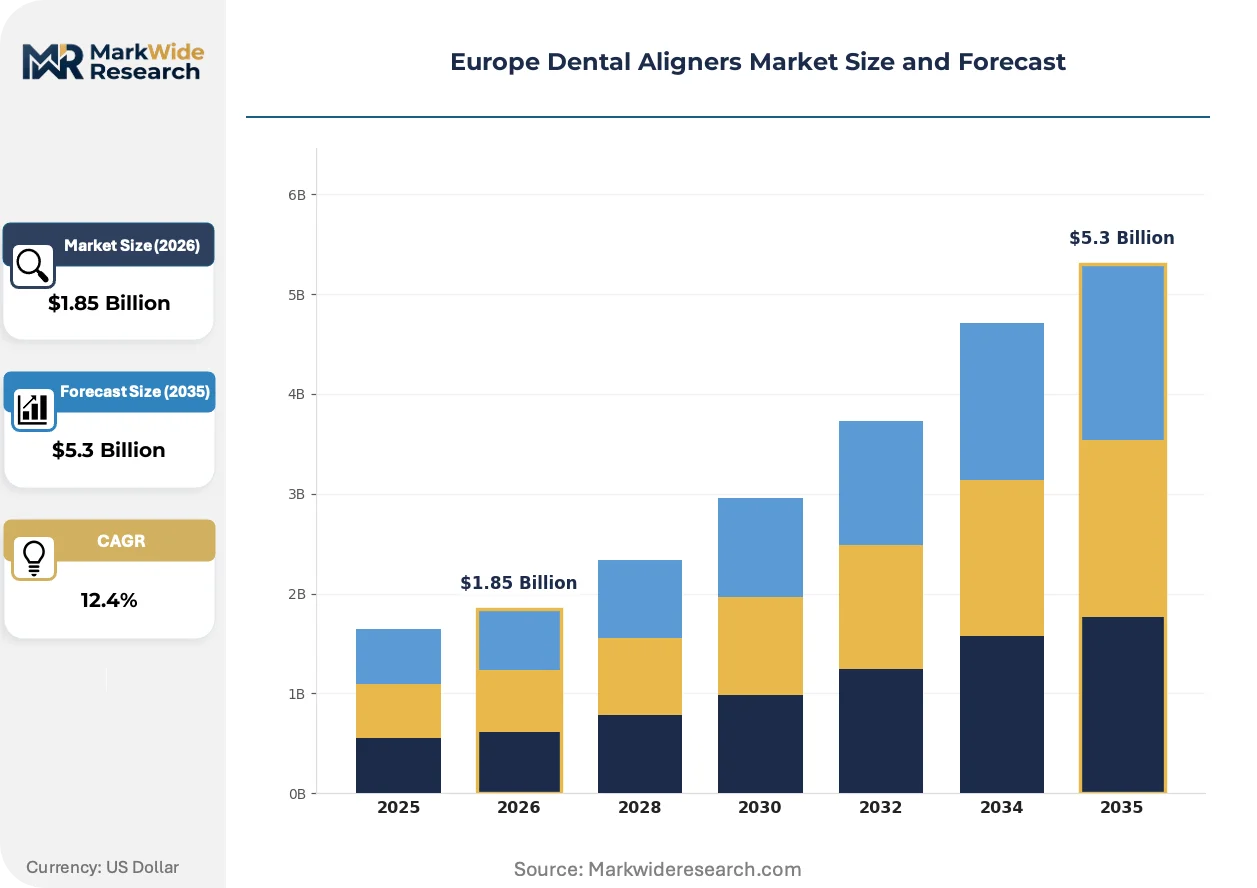
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligner, Traditional Braces, Retainers, Interproximal Reduction End User: Orthodontists, Dental Clinics, Home Care, Research Institutions Age Group: Teenagers, Young Adults, Adults, Seniors Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Align Technology, Dentsply Sirona, Institut Straumann AG, 3M Company, Envista Holdings Corporation, Dentaurum GmbH & Co. KG, Ormco Corporation, Argen Corporation, K Line Europe GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Aligners Market Shifts & Advancements
Digital workflow compression is eliminating traditional laboratory intermediaries from European aligner production, while regulatory digitization and shifting patient acquisition channels are redefining competitive advantage beyond product specifications alone.
Multi-layer thermoplastic materials are migrating from single-density polyurethane constructions toward engineered stiffness gradients that optimize force delivery across treatment phases. German orthodontic practices are adopting these advanced sheets for moderate-to-complex cases previously reserved for fixed appliances. The technology is migrating from premium-tier products into mid-market offerings as patent expirations and manufacturing scale reduce material cost premiums.
CE marking under the EU MDR now requires clinical performance data for novel aligner materials rather than predicate device equivalence. This elevates development costs for European entrants while advantaging incumbents with established clinical study archives. Manufacturers are responding by sponsoring multi-center trials in German university hospitals to preempt notified body questions during conformity assessment.
Patient acquisition is fragmenting across hybrid digital-physical channels as direct-to-consumer platforms capture initial interest before referring complex cases to affiliated clinics. Italian and Spanish consumers increasingly initiate treatment journeys through social media advertising and remote dental monitoring apps rather than traditional orthodontic referrals. This channel shift concentrates marketing spend in performance advertising and tele-dentistry infrastructure, diverting resources from conventional professional education budgets.
Europe Dental Aligners Market Segmentation
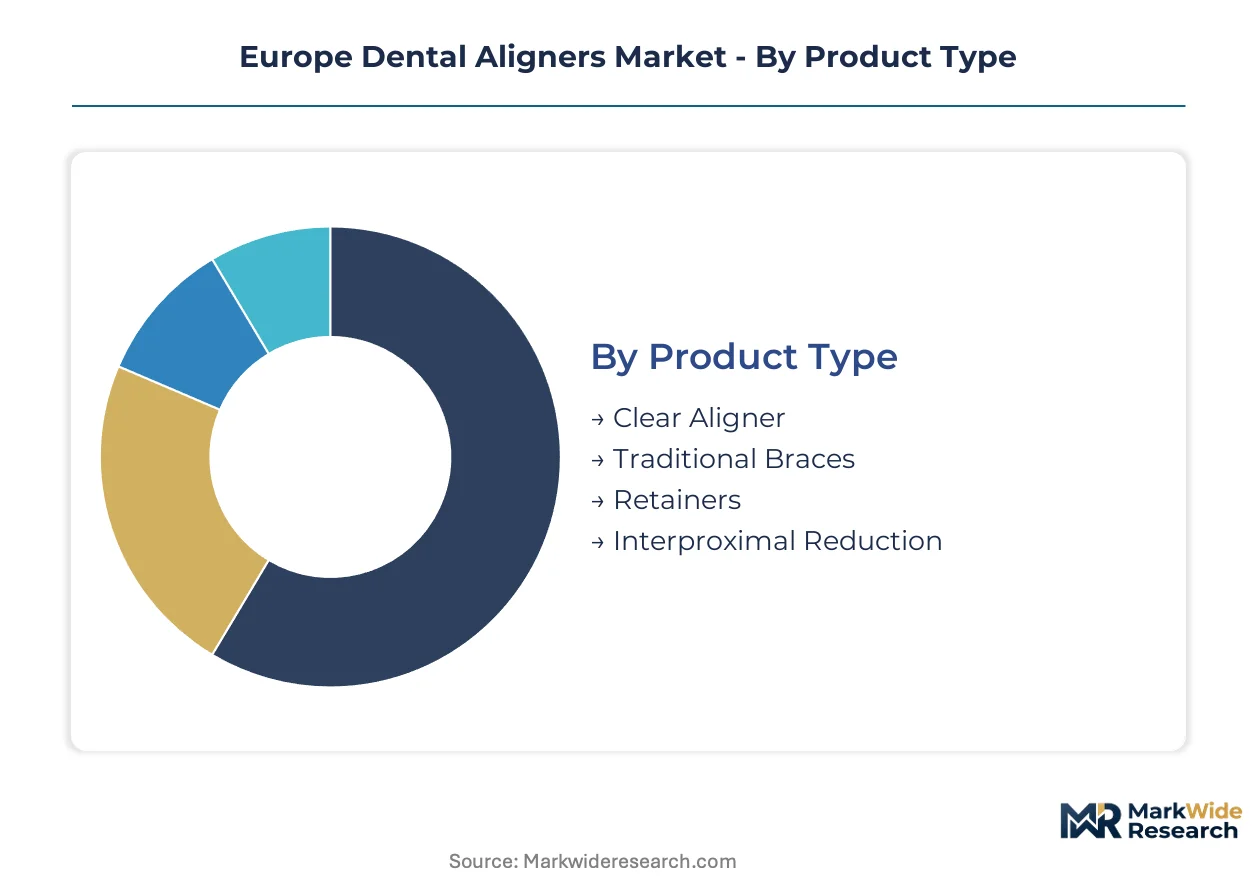
Segmentation in the Europe dental aligners market reveals how reimbursement frameworks, clinical workflows, and patient acquisition channels fragment demand across distinct customer profiles. Understanding these divisions allows manufacturers to calibrate material specifications, pricing tiers, and regulatory evidence packages to specific access pathways.
Product Type:
Mature thermoplastic technologies coexist with emerging material engineering approaches across this spectrum, with clinical acceptance varying by case complexity and aesthetic requirements.
- Clear Aligner:Multi-layer polyurethane or PETG thermoplastic sheets deliver controlled orthodontic force through sequential 3D-printed model fabrication. German and French orthodontic practices drive premium uptake for moderate-to-complex cases previously reserved for fixed appliances, though polymer feedstock volatility compresses margins for thermoforming-dependent producers.
- Traditional Braces:Fixed metal or ceramic bracket systems retain cost advantages for severe malocclusions and adolescent compliance-challenged cases. Lingual and ceramic variants limit clear aligner penetration in complex orthodontic segments across Southern Europe where public reimbursement favors established protocols.
- Retainers:Post-treatment stabilization devices, typically vacuum-formed or fixed wire constructions, secure orthodontic outcomes.
- Interproximal Reduction:Enamel stripping procedures performed adjunctively to create arch space, executed chairside with diamond strips or burs.
Clear Aligner handles the majority of throughput; Interproximal Reduction is the fastest mover on share as adjunctive case complexity rises.
End User:
Customer type determines channel economics, with professional gatekeepers yielding to direct-to-consumer platforms in price-sensitive segments.
- Orthodontists:Specialist practitioners with exclusive focus on tooth movement correction, commanding premium case fees and complex malocclusion referrals. AI treatment planning adoption concentrates in German university hospital networks where digital workflow compression reduces chair time per case.
- Dental Clinics:General dentistry practices integrating aligner services through intraoral scanner convergence and cloud-based planning platforms. Spanish and Italian clinics pilot remote monitoring to extend geographic reach beyond metropolitan centers.
- Home Care:Direct-to-consumer models leveraging mail-order impression kits and tele-dentistry oversight, expanding fastest in Poland and Italy where marketing spend shifts to performance advertising and social media patient acquisition.
- Research Institutions:University dental schools and clinical trial sponsors generating MDR-compliant evidence for novel material submissions.
Dental Clinics handle the majority of throughput; Home Care is expanding most quickly on share as channel gatekeepers fragment.
Age Group:
Volume concentration and margin expansion diverge across generational cohorts with distinct aesthetic priorities and payment capacities.
- Teenagers:Volume-heavy segment driven by parental-funded correction and compliance-dependent treatment protocols, concentrated in comprehensive orthodontic benefit frameworks.
- Young Adults:Aesthetic-conscious patients aged 25-35 accepting complex case premiums and extended treatment timelines, driving margin expansion across Western European private healthcare markets.
- Adults:Patients aged 35-55 seeking discreet correction for relapse or untreated adolescent malocclusion, representing the steepest expansion trajectory as professional appearance concerns override cost sensitivity.
- Seniors:Emerging segment addressing age-related tooth migration and restorative pre-alignment, constrained by limited reimbursement for elective orthodontic intervention.
Teenagers handle the majority of throughput; Adults is climbing the fastest on share as aesthetic demand broadens beyond traditional demographic boundaries.
Distribution Channel:
Channel configuration reflects the collapse of traditional laboratory intermediaries into integrated digital-physical patient journeys.
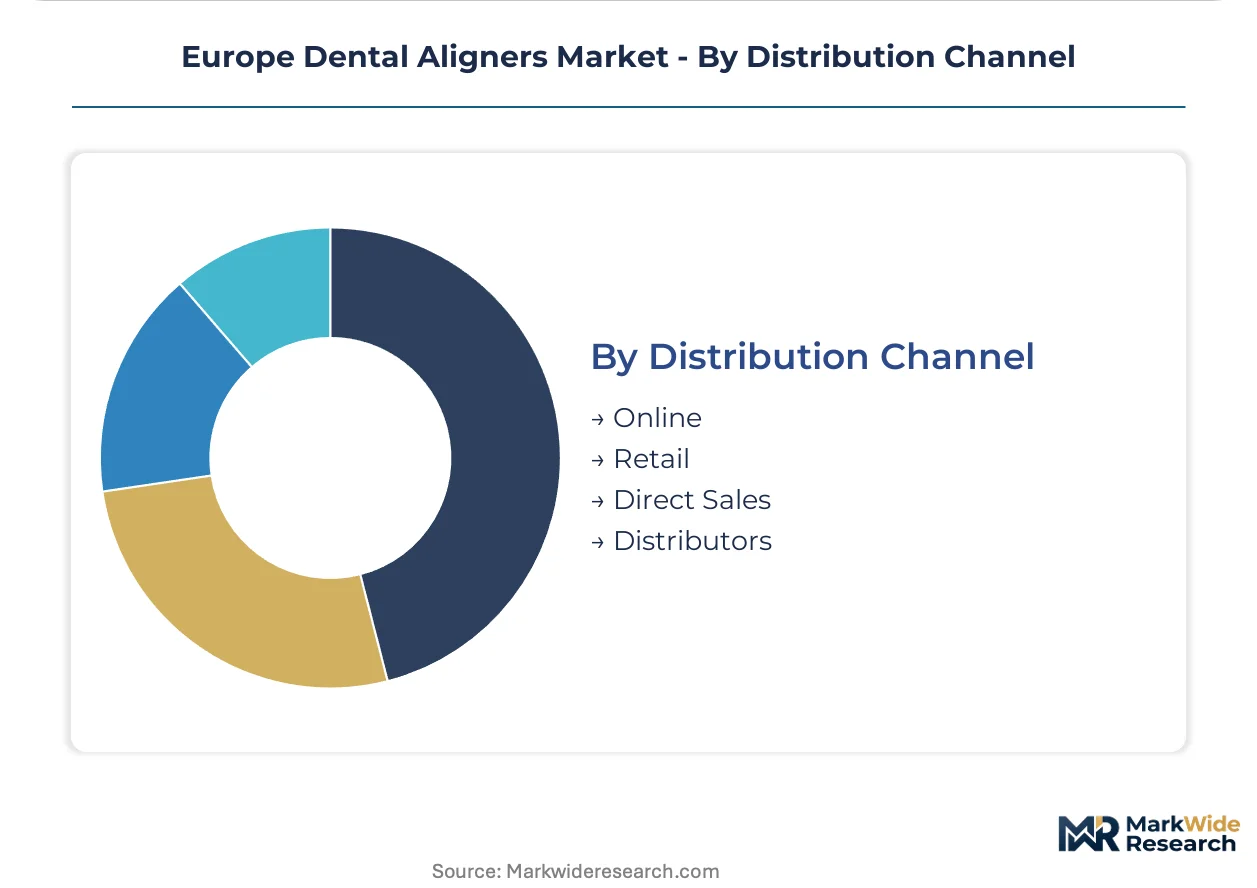
- Online:E-commerce platforms and direct-to-consumer websites capturing initial patient interest through performance marketing, particularly effective in Italian and Spanish markets where social media advertising initiates treatment discovery.
- Retail:Pharmacy and optical chain partnerships for impression kit distribution and initial screening, limited by MDR restrictions on medical device self-selection.
- Direct Sales:Manufacturer field forces calling on orthodontic practices and dental clinic groups, sustaining professional education and scanner placement programs across German metropolitan clusters.
- Distributors:Regional dental supply intermediaries inventorying aligner materials and adjunctive products for independent practitioners in fragmented Eastern European markets.
Direct Sales handles the majority of throughput; Online is gaining share fastest as patient acquisition fragments across hybrid digital-physical pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aligner manufacturers export precision thermoplastic devices to French and Italian orthodontic networks, establishing a north-south trade corridor that channels production from Rhine-Ruhr industrial zones into Mediterranean patient markets.
Germany
Adult aesthetic demand in Berlin and Munich drives premium clear aligner uptake, with patients aged 25-45 accepting complex case fees exceeding traditional adolescent brackets. The EU MDR notified bodies in TÜV SÜD and BSI Medical extend certification timelines for novel PETG materials, requiring prospective clinical evidence rather than predicate equivalence. The Rhine-Ruhr corridor concentrates thermoforming production, with Düsseldorf-area fabricators supplying digital workflow-integrated practices across North Rhine-Westphalia.
France
Parisian orthodontic practices adopt AI treatment planning platforms at rates matching German adoption curves, compressing case design from laboratory-mediated weeks to chairside days. ANSM, the national health product safety agency, enforces MDR compliance alongside CNIL data protection oversight for patient record transfers used in algorithm training. The Île-de-France cluster anchors demand, with Lyon and Marseille practices piloting remote monitoring extensions into Auvergne-Rhône-Alpes and Provence hinterlands.
Italy
Direct-to-consumer platforms capture initial patient interest through social media performance advertising, bypassing traditional orthodontic gatekeepers in Milan and Rome. Regional health authorities in Lombardy and Lazio maintain limited public reimbursement for aligners, classifying most cases as elective aesthetic procedures. The Bologna-Modena industrial district hosts emerging thermoplastic sheet converters serving mid-market clear aligner brands with reduced certification burdens.
Spain
Catalonia and Andalusia pilot aligner inclusion in regional public dental benefits, unlocking subsidized patient volumes previously restricted to private payment. The Spanish Agency for Medicines and Health Products coordinates with regional health departments on MDR implementation timelines, creating fragmented market access conditions. Barcelona practices integrate intraoral scanner networks with cloud-based planning, collapsing traditional laboratory intermediaries from patient onboarding workflows.
United Kingdom
London orthodontic groups consolidate through multi-site scanner placement and centralized treatment planning, achieving economies of scale in patient acquisition. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking post-Brexit, diverging from EU MDR mutual recognition and duplicating certification burdens for cross-channel suppliers. The Southeast England corridor concentrates premium demand, with Manchester and Birmingham practices expanding into price-sensitive segments through dental clinic partnerships.
Europe Dental Aligners Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering, with neither consolidation nor pure fragmentation dominating structure. Incumbents with established notified body relationships and clinical evidence archives hold regulatory access advantages, while mid-scale entrants concentrate on material differentiation or geographic white spaces. Two archetypes predominate: integrated digital-physical workflow providers and standalone thermoplastic fabricators. Competitive moves center on backward integration into intraoral scanning hardware and strategic partnerships with orthodontic practice groups for captive demand generation.
Among US-based technology-orthodontic hybrids, Align Technology and Dentsply Sirona exemplify divergent positioning archetypes, with the former representing proprietary closed-system control and the latter open-architecture interoperability. Institut Straumann AG, the Swiss dental implant and device group, anchors the European-origin tier through upstream integration strategies. These three entities collectively illustrate how geographic origin, corporate structure, and vertical scope define competitive positioning without requiring equivalent scale or identical channel strategies.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| Institut Straumann AG |
| 3M Company |
| Envista Holdings Corporation |
| Dentaurum GmbH & Co. KG |
| Ormco Corporation |
| Argen Corporation |
| K Line Europe GmbH |
| Others |
Supply & Pricing Matrix
Polymer feedstock volatility in petrochemical-linked PETG and polyurethane sheet markets compresses gross margins for thermoforming-dependent producers while simultaneously widening pricing spreads between premium multi-layer material tiers and standard single-density alternatives. This input cost instability forces manufacturers to recalibrate supply chain footprints and pricing architectures in parallel.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects generational material technology gaps, with next-generation engineered stiffness gradient sheets commanding case fees exceeding legacy single-density constructions by substantial margins. Certification grade under EU MDR and volume scale through dental clinic group purchasing agreements serve as the primary price differentiation drivers. Pricing pressure stems from direct-to-consumer platforms capturing price-sensitive segments in Italy and Poland, forcing traditional clinic-channel premiums downward. Home care end users exhibit highest price sensitivity, while German orthodontic practices accepting complex adult cases demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between Germany and China for medical-grade polymer feedstock concentrates supply risk in the Rhine-Ruhr thermoforming corridor, where Düsseldorf-area fabricators depend on Asian petrochemical derivatives. Germany, China, and South Korea anchor upstream PETG and polyurethane sheet production, with multi-layer material engineering concentrated in German and Swiss specialty chemical operations. Single-source vulnerability in notified body certification through TÜV SÜD and BSI Medical creates queue bottlenecks extending time-to-market. Distribution runs through direct sales forces calling on orthodontic practice clusters and dental supply distributors serving fragmented Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in MDR-compliant clinical evidence generation and AI treatment algorithm development concentrates strategic leverage among incumbents with established notified body relationships and multi-center trial archives.
For Market Incumbents: Build regulatory evidence moats by sponsoring prospective clinical studies in German university hospitals to preempt notified body questions during novel material conformity assessment. Deepen backward integration into intraoral scanning hardware to collapse laboratory intermediaries from patient onboarding workflows. Defend against direct-to-consumer platform erosion by capturing complex case referrals through affiliated clinic networks. For New Entrants and Emerging Players: Build out white-space presence in Spanish regional reimbursement pilots, where Catalonia and Andalusia public dental benefits unlock subsidized patient volumes underserved by established competitors. Target mid-market clear aligner positioning through Bologna-Modena industrial district partnerships, leveraging reduced certification burdens for standard material tiers. Pursue social media performance advertising and tele-dentistry infrastructure as primary go-to-market angles in Italian and Polish price-sensitive segments. For Investors and Strategic Acquirers: EU MDR full implementation reshapes the acquisition landscape by elevating development costs for clinical evidence-dependent entrants while advantaging targets with established study archives and notified body relationships. Long-term viability centers on algorithm-enabled treatment planning capabilities and scanner-integrated workflow control. Monitor Spanish regional health authority reimbursement classification decisions as the critical inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR-compliant clinical evidence packages accelerate notified body assessments across German and French certification queues. |
| Backward Integration | Captive intraoral scanner production collapses laboratory intermediaries from chairside-to-fabrication workflows. |
| Hospital System Partnership | German university hospital networks generate prospective trial data for novel material conformity submissions. |
| Software Companion Development | AI treatment planning algorithms compress case design timelines from laboratory-mediated weeks to chairside days. |
| Reimbursement Strategy | Spanish regional benefit inclusion pilots unlock subsidized patient volumes beyond private payment markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthodontists, dental clinic operators, intraoral scanner manufacturers, thermoplastic sheet converters, and notified body certification specialists. Secondary validation drew from EU MDR implementation guidance, ANSM and BfArM regulatory filings, dental reimbursement policy documents in Italy and Spain, and petrochemical feedstock trade data. Bottom-up case volume estimates and top-down market sizing triangulated across practitioner survey responses and import-export customs records.
Calibration against historical adoption curves for digital orthodontic workflows anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product type by material generation, end user by channel gatekeeper status, age group by aesthetic priority and payment capacity, and distribution channel by digital-physical integration level. CAGRs derived from logistic diffusion modeling of adult aesthetic demand penetration and AI treatment planning adoption rates, with polymer feedstock price indices and MDR certification timeline assumptions as key forecast inputs.
Stress conditions across polymer cost volatility bands, notified body queue duration scenarios, and Spanish reimbursement expansion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MDR implementation consistency and adult patient willingness-to-pay trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Prophylaxis Pastes Market
Dental Devices
North America Dental Lab Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Forceps Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Dam Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Restoration Market
Dental Devices
UAE Dental Devices Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Caries Market
Dental Devices
Dental Implant Motors Market