
 Dental Implants and Dental Prosthetics Market | 2026-2036
Dental Implants and Dental Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Implants and Dental Prosthetics Market Analysis
Switzerland is rewriting the competitive map for precision implant manufacturing. Straumann Group leverages its Basel-based R&D campus to sustain dominance in premium titanium fixtures. Dentsply Sirona anchors North American distribution through its Charlotte, North Carolina operational hub. Zimmer Biomet competes on orthopedic-to-dental technology transfer, applying joint-replacement metallurgy to oral implantology.
Dental implants and dental prosthetics comprise titanium or zirconia fixtures surgically embedded in maxillofacial bone, typically achieving osseointegration thresholds of 35-45 Ncm insertion torque before prosthetic loading. These devices restore masticatory function and alveolar bone preservation for edentulous or partially edentulous patients. Titanium alloys occupy the structural core of the implant fixture segment due to proven biocompatibility and fatigue resistance under cyclic occlusal loads. Zirconia abutments and full-arch prosthetics represent the fastest-expanding material category, driven by aesthetic demands in anterior restorations and metal-free protocols. Full-arch prosthetics concentrate margin pools through bundled surgical and laboratory workflows that consolidate chairside and technical fees.
FDA 510(k) premarket notification governs titanium implant clearance in the United States, while the EU Medical Device Regulation (MDR) and CE marking framework enforce biocompatibility and clinical evidence standards across European markets. Japan's PMDA and METI coordinate pharmaceutical and industrial standards for imported and domestically manufactured devices, creating layered compliance requirements for foreign entrants. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital dentistry guidance to calibrate regulatory investment against commercial timelines.
Market Dynamics
Osseointegration science and digital surgical workflows are compressing treatment timelines from months to weeks, forcing laboratories and clinics to reconfigure their capacity planning around same-day loading protocols.
Growth Catalysts
- Japan's PMDA streamlined approval pathways:METI-coordinated industrial standards for titanium fixtures accelerate foreign manufacturer entry into East Asian markets.
- Zirconia anterior restorations:Aesthetic-driven metal-free protocols in cosmetic dentistry expand addressable patient segments beyond traditional titanium candidates.
- Germany's Rhine-Ruhr laboratory cluster:Concentrated technical expertise around Cologne enables bundled surgical-laboratory workflows that capture margin pools.
Market Restraints
- Titanium alloy input volatility:Aerospace and orthopedic demand for Ti-6Al-4V ELI creates periodic supply competition for implant-grade material.
- EU MDR notified body capacity constraints:CE marking backlogs extend commercialization timelines for European market entrants by twelve to eighteen months.
- All-ceramic fatigue limitations:Zirconia's brittle fracture risk under cyclic occlusal loads restricts indications in posterior molar zones.
Strategic Opportunities
- South Korea's geriatric edentulism wave:MFDS-regulated domestic manufacturing incentives create localized production advantages for regional players.
- Digital dentistry convergence:Intraoral scanning merged with CAD-CAM milling collapses traditional laboratory intermediation in chairside workflows.
- India's CDSCO emerging regulatory framework:Medical device rules harmonization opens import substitution opportunities for value-tier titanium fixtures.
Industry Challenges
- Prosthodontic technician scarcity:Specialized ceramist and digital design skills concentrate in aging European workforces with limited pipeline replacement.
- FDA 510(k) predicate device drift:Substantial equivalence determinations for novel surface topographies generate unpredictable review cycles.
- Legacy practice management integration:Chairside milling and surgical planning software requires retraining workflows resistant to capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Implants and Dental Prosthetics Market |
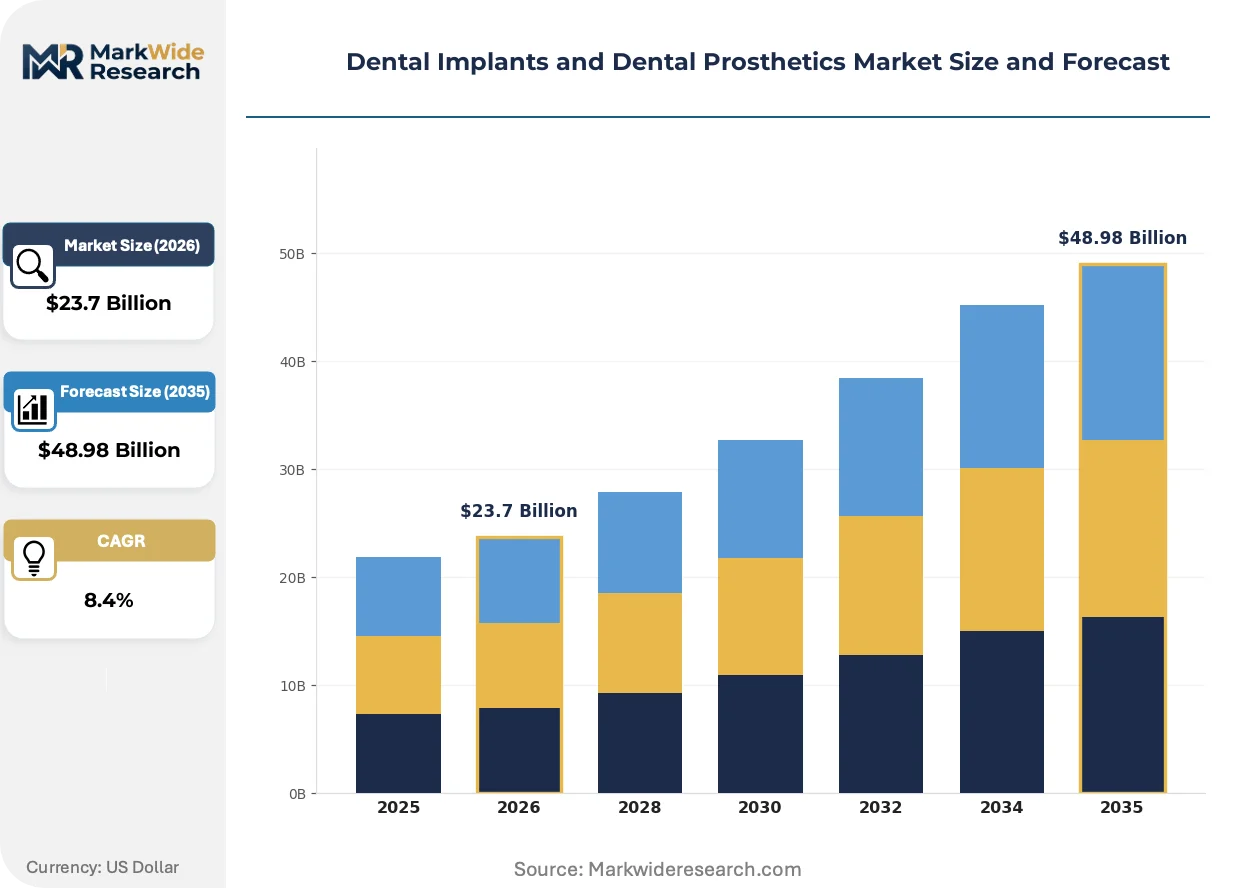
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Tooth Implants, Multi-Unit Implants, Implant-supported Bridges, Full-arch Prosthetics Material: Titanium, Zirconia, Stainless Steel, Composite Resins Procedure Type: Immediate Loading, Delayed Loading, Bone Grafting, Sinus Lift End User: Dentists, Oral Surgeons, Prosthodontists, Dental Clinics |
| Companies Covered | Straumann Group, Dentsply Sirona, Zimmer Biomet Holdings, Envista Holdings Corporation, Nobel Biocare Services, Osstem Implant, Ivoclar Vivadent, BioHorizons, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Implants and Dental Prosthetics Market Emerging Trajectories
Digital thread technologies are dissolving boundaries between diagnostic imaging, surgical planning, and final prosthetic fabrication, compressing value chains that historically spanned multiple independent suppliers.
Computer-guided implant surgery is collapsing the traditional separation between radiographic assessment and surgical execution. Oral surgeons in Germany and Switzerland adopt real-time navigation systems at accelerating rates. This capability compression enables general practitioners to perform procedures previously reserved for specialists, redistributing volume across practice types.
The EU Medical Device Regulation's clinical evidence requirements are reshaping product development economics. Manufacturers must generate post-market surveillance data for legacy titanium fixtures already in circulation. Smaller European laboratories dependent on third-party implant systems face supplier consolidation as compliance costs disproportionately burden mid-tier device makers.
Patient financing platforms are fragmenting traditional payer concentration in elective dental restoration. Third-party credit services displace out-of-pocket payment in US and Australian markets. This behavioral shift expands treatment accessibility among middle-income demographics previously priced out of full-arch reconstruction.
Dental Implants and Dental Prosthetics Market Segmentation
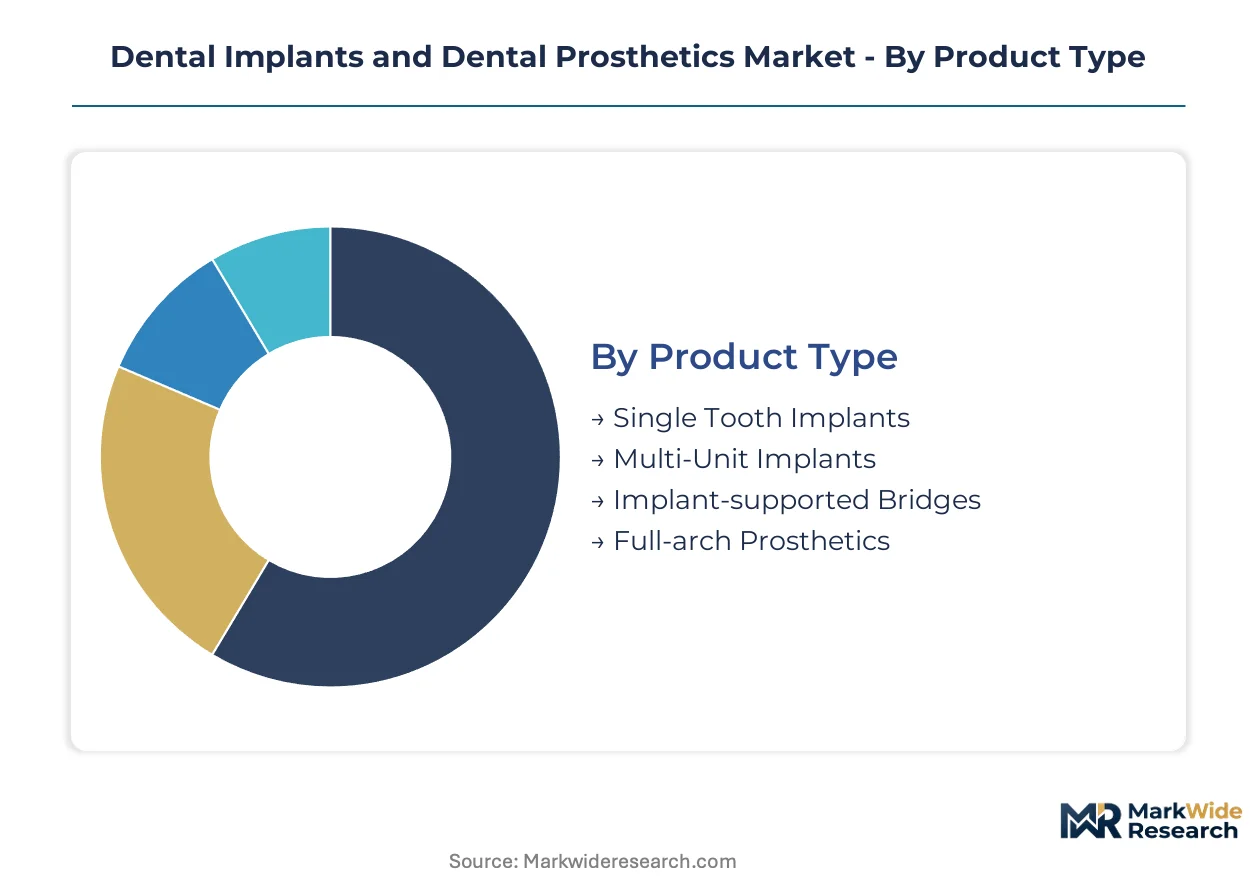
Dental implant and prosthetic segmentation reveals distinct clinical workflows, material science trade-offs, and practitioner capability requirements that shape procurement patterns and margin structures across the value chain.
Product Type:
The use-case spectrum spans isolated tooth replacement through full-arch reconstruction, with procedure complexity and bundled service economics determining segment profitability.
- Single Tooth Implants:Titanium fixtures with screw-retained crowns address individual edentulous sites. Demand concentrates in German and Swiss private practices where fee-for-service models reward precision surgical workflows.
- Full-arch Prosthetics:All-on-four or all-on-six configurations replace entire maxillary or mandibular arches. Japan's geriatric clinics are adopting these protocols fastest as edentulism rates climb among aging cohorts.
- Multi-Unit Implants:Three-unit to six-unit restorations bridge partially edentulous spans.
- Implant-supported Bridges:Fixed prostheses anchored by two or more fixtures restore contiguous missing teeth.
The dominant share belongs to Single Tooth Implants, while Full-arch Prosthetics is closing the gap fastest.
Material:
Cost tier differentiation separates premium biocompatible metals from aesthetic ceramics and value-engineered alternatives.
- Titanium:Ti-6Al-4V ELI alloys deliver proven osseointegration and fatigue resistance under cyclic occlusal loads. FDA 510(k) predicates concentrate around Straumann and Zimmer Biomet surface topographies, creating regulatory moats for established suppliers.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystals enable metal-free anterior restorations. South Korean aesthetic clinics are driving adoption fastest amid patient demand for translucent, gum-friendly alternatives.
- Stainless Steel:Cost-sensitive temporary abutments and provisional restorations.
- Composite Resins:Chairside-milled provisional prostheses and diagnostic wax-ups.
Titanium commands the installed base, though Zirconia is gaining share fastest in anterior applications.
Procedure Type:
Volume concentration tracks toward accelerated treatment protocols that compress chair time and laboratory turnaround.
- Immediate Loading:Provisional prosthesis attachment within 48 hours of fixture placement. Swiss and German surgical centers are refining same-day protocols that eliminate the traditional three-to-six-month integration delay.
- Bone Grafting:Autograft, allograft, or synthetic augmentation restores deficient alveolar ridges. Indian dental tourism hubs are bundling these procedures with implant placement to capture price-sensitive international patients.
- Delayed Loading:Conventional two-stage surgery with submerged healing periods.
- Sinus Lift:Lateral or crestal elevation procedures enable posterior maxillary implant placement.
Delayed Loading retains the volume base, yet Immediate Loading is expanding most quickly among digitally equipped practices.
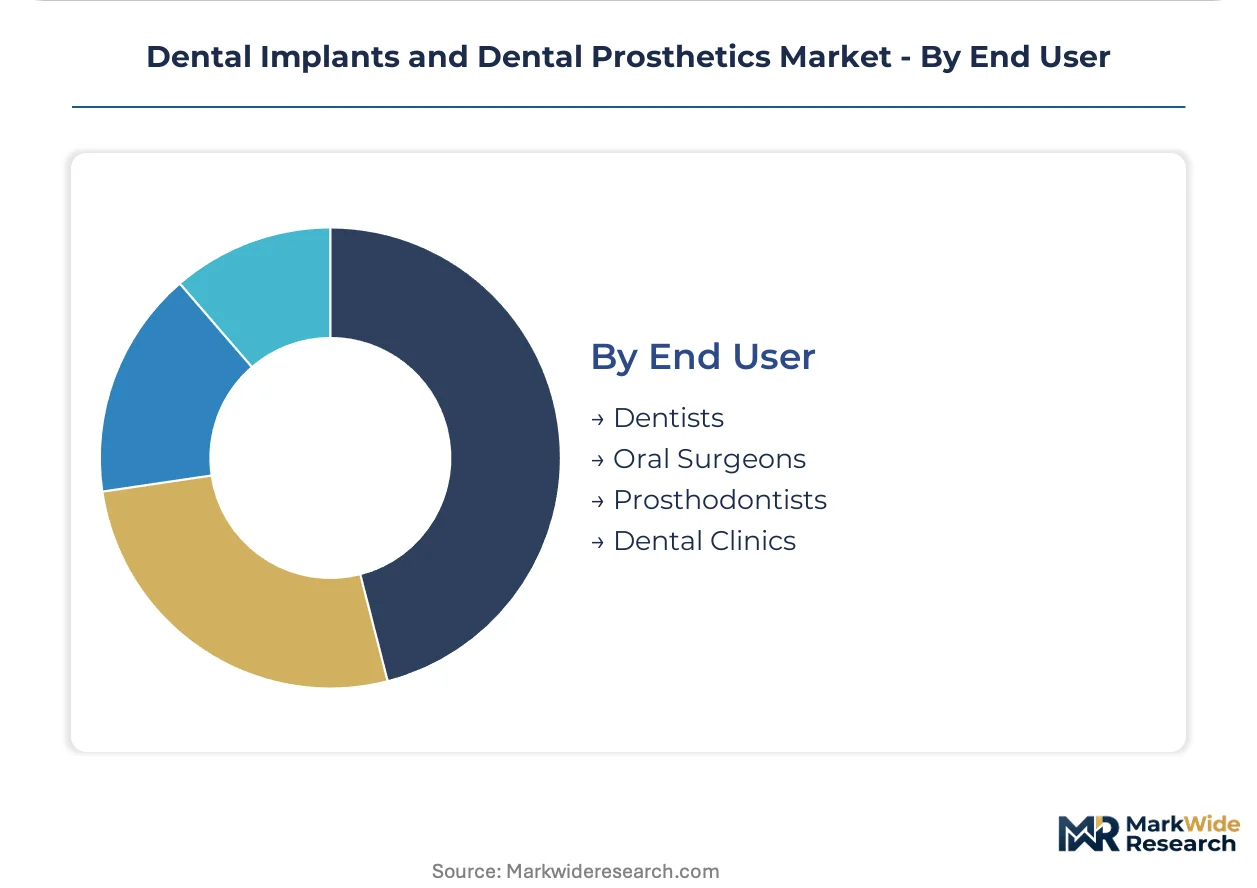
End User:
Customer type stratification reflects training depth, capital intensity, and regulatory scope of practice boundaries.
- Oral Surgeons:Maxillofacial specialists command complex full-arch and graft-dependent cases. Australia's major metropolitan hospitals are consolidating these procedures into dedicated implant centers with in-house CAD-CAM milling.
- Dental Clinics:Corporate and franchise chains aggregate volume through standardized protocols. Brazil's expanding clinic networks are deploying intraoral scanners to centralize laboratory workflows.
- Dentists:General practitioners performing straightforward single-tooth placements.
- Prosthodontists:Specialists in complex restorative rehabilitation and occlusal reconstruction.
Dental Clinics capture the dominant procedure volume, while Oral Surgeons retain the premium case mix.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy supply chains concentrate in Swiss and German precision manufacturing corridors, while demand expansion radiates from aging population centers in East Asia. Regulatory fragmentation across FDA, PMDA, and EU MDR frameworks forces manufacturers to maintain parallel compliance infrastructures. Clinical adoption patterns diverge sharply between fee-for-service private markets and socialized reimbursement systems.
United States
Private practice consolidation and corporate dental chains drive volume aggregation in metropolitan markets. FDA 510(k) premarket notification governs titanium fixture clearance, with predicate device pathways favoring established surface topography portfolios. Charlotte, North Carolina anchors North American distribution infrastructure for multinational suppliers.
Germany
Rhine-Ruhr laboratory clusters around Cologne bundle surgical and technical workflows for margin capture. EU Medical Device Regulation enforces biocompatibility and clinical evidence standards through CE marking frameworks. Bavarian precision engineering corridors supply CNC-milled abutments to European implant networks.
Japan
Geriatric edentulism rates among aging cohorts accelerate full-arch prosthetic adoption in urban clinics. PMDA and METI coordinate pharmaceutical and industrial standards for imported titanium devices. Tokyo and Osaka metropolitan areas concentrate specialist oral surgery capacity for complex rehabilitation cases.
Switzerland
Basel-based R&D campuses sustain dominance in premium titanium fixture metallurgy and surface engineering. Swissmedic enforces medical device quality standards that exceed baseline EU MDR requirements. Zürich and Geneva private practices command premium fee structures for immediate-loading protocols.
South Korea
Aesthetic-driven zirconia anterior restorations expand addressable patient segments beyond traditional titanium candidates. MFDS-regulated domestic manufacturing incentives create localized production advantages for regional players. Seoul Capital Area clinics deploy intraoral scanning at accelerating rates for chairside workflow integration.
Dental Implants and Dental Prosthetics Market Vendor Landscape
Premium metallurgy specialists and diversified dental conglomerates split the market along technology depth versus distribution breadth vectors. The vendor base concentrates around three strategic archetypes: Swiss-German precision manufacturers with captive titanium supply chains, American orthopedic-to-dental technology transfer platforms, and Korean-Chinese value-tier fabricators exploiting cost-advantaged production. Dominant competitive moves include backward integration into implant-grade alloy sourcing and geographic expansion through distributor acquisition in emerging markets.
Among Basel-based precision manufacturers, Straumann Group exemplifies the premium metallurgy archetype through its captive R&D infrastructure. Dentsply Sirona occupies a position bridging European manufacturing heritage with North American distribution scale. Zimmer Biomet represents the orthopedic-to-dental technology transfer model, applying joint-replacement metallurgy expertise to oral implantology applications.
| Leading Market Players |
|---|
| Straumann Group |
| Dentsply Sirona |
| Zimmer Biomet Holdings |
| Envista Holdings Corporation |
| Nobel Biocare Services |
| Osstem Implant |
| Ivoclar Vivadent |
| BioHorizons |
| Henry Schein |
| Others |
Supply Flow & Price Mechanics
Titanium alloy input volatility from aerospace and orthopedic demand competition determines both the spread between premium and economy fixture tiers and the geographic configuration of implant manufacturing networks. Manufacturers with captive metallurgy capabilities in Swiss and German precision corridors command pricing power while outsourcing-dependent competitors absorb margin compression.
Pricing Analysis
FDA 510(k) predicate device pathways dictate the pricing tier structure across the United States market, with substantial equivalence determinations creating regulatory moats that sustain premium positioning for established surface topography portfolios. Three-tier pricing structure across premium, standard, and economy levels separates Straumann-grade fixtures from mid-tier Korean manufacturers and value-engineered Indian alternatives. Cost compression in the economy tier is intensifying because CDSCO import substitution incentives attract price-sensitive domestic fabricators. Dental clinic chains exhibit highest price sensitivity due to volume procurement leverage, while Swiss private practices demonstrate lowest sensitivity amid fee-for-service reimbursement models.
Supply Chain Analysis
Export control restrictions on precision CNC milling equipment and laser-sintering platforms limit technology transfer to emerging manufacturing hubs, concentrating high-value production in Switzerland, Germany, and select American orthopedic corridors. Ti-6Al-4V ELI alloy supply draws from aerospace-certified foundries in the United States, Germany, and Japan, with implant-grade specification tightening creating qualified-supplier scarcity. Single-source vulnerability pervades yttria-stabilized zirconia feedstock for aesthetic anterior applications, where South Korean and Japanese ceramic processors dominate refined powder supply. Distribution runs through specialized dental laboratory networks in the Rhine-Ruhr corridor and North American dental service organizations, bypassing traditional device distributor intermediation for high-volume clinic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental implant markets exhibit durable defensive moats through regulatory entrenchment, where FDA predicate pathways and EU MDR clinical evidence requirements create decade-long incumbent advantages that new capital cannot readily replicate.
For Market Incumbents: Pre-empt Korean and Chinese value-tier challengers by securing captive titanium alloy supply through backward integration into aerospace-certified foundry partnerships, while accelerating same-day loading protocol certification to capture digitally equipped general practitioner volume before mid-tier competitors complete software integration. For New Entrants and Emerging Players: India's CDSCO-harmonized import substitution framework for value-tier titanium fixtures represents the most penetrable entry point for capital-constrained manufacturers, with Brazilian corporate dental clinic chains offering secondary white-space for standardized immediate-loading protocols. Go-to-market execution should prioritize GPO contracting with hospital-based oral surgery centers over fragmented private practice direct sales. For Investors and Strategic Acquirers: EU MDR notified body capacity constraints and post-market surveillance data requirements reshape the acquisition landscape toward mid-tier European laboratories facing supplier consolidation pressure. Five-to-ten year viability favors targets with existing CE-marked titanium portfolios and established PMDA relationships for East Asian expansion. The signal to watch is FDA digital dentistry guidance publication timing, which would force acquisition premium recalibration for chairside milling-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Implant-Grade Alloy Supply | Captive Ti-6Al-4V ELI sourcing insulates margin from aerospace demand competition. |
| Same-Day Loading Protocol Certification | FDA 510(k) clearance for accelerated osseointegration claims captures digitally equipped practitioner volume. |
| EU MDR Post-Market Surveillance Infrastructure | Clinical evidence generation capabilities determine survival for mid-tier European device makers. |
| Intraoral Scanning Platform Partnership | CAD-CAM workflow integration with chairside milling collapses traditional laboratory intermediation. |
| South Korean MFDS Domestic Manufacturing Incentives | Localized production advantages for regional players target geriatric edentulism demand acceleration. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with oral surgeons, prosthodontists, dental laboratory directors, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body capacity reports, PMDA pharmaceutical and industrial standards filings, and hospital procurement contract disclosures. Bottom-up volume estimates from procedure-type segmentation triangulated against top-down manufacturer revenue analysis.
Forecast inputs across the analysis window incorporated titanium fixture and zirconia abutment demand trajectories, geriatric edentulism rate projections, digital dentistry adoption curves, and regulatory pathway timeline assumptions. Segmentation modeling spanned product type complexity tiers, material science categories, procedure acceleration protocols, and end-user capability stratification. CAGRs derived from weighted regression across historical procedure volume trends and forward-looking practitioner capacity expansion plans.
Practitioners should monitor FDA digital dentistry guidance publication, EU MDR notified body capacity resolution, and titanium alloy spot market volatility for early signals of forecast deviation. Material shifts in predicate device substantial equivalence determination standards or osseointegration torque threshold clinical requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Mexico Dental Devices Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Chile Dental Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Malocclusion Market
Dental Devices
Global Dental Labs Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Healing Caps Market
Dental Devices
North America Dental Aligners Market