
 Argentina Nuclear Imaging Market | 2026-2036
Argentina Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Nuclear Imaging Market Outlook
Hospital procurement channels in Argentina is fragmenting as public-sector tenders decentralize to provincial health ministries and private imaging centers negotiate directly with manufacturers. Siemens Healthineers AG leverages its installed base of SPECT systems to sustain service-contract revenue across Argentine public hospitals. GE HealthCare competes through localized technical support teams that anchor customer loyalty in Buenos Aires and Córdoba. Koninklijke Philips N.V. differentiates by positioning its hybrid imaging portfolio toward cardiology departments seeking PET-CT integration.
Argentina nuclear imaging encompasses gamma cameras, SPECT systems, PET scanners, and hybrid imaging systems that detect gamma-ray emissions from radiopharmaceutical tracers to visualize organ function and metabolic activity at resolutions reaching millimeter scale. These technologies serve primarily to diagnose cancer staging, assess myocardial perfusion, and evaluate neurological disorders before therapeutic intervention. Hybrid imaging systems command the strongest margin pools as PET-CT and PET-MRI configurations justify premium pricing through fused anatomical and functional datasets. Oncology applications lead procedural volume given Argentina's expanding molecular radiotherapy programs, while cardiology segments grow fastest as stress-testing protocols shift toward myocardial perfusion imaging with technetium-based tracers.
ANMAT, Argentina's national pharmaceutical and medical device regulator, enforces Good Manufacturing Practice standards for radiopharmaceutical production that constrain local tracer supply and shape import-dependent procurement patterns. The Argentine Nuclear Regulatory Authority (ARN) mandates operator certification and facility shielding protocols that limit installation sites to accredited tertiary centers. Stakeholders must monitor ARN's pending updates to cyclotron licensing requirements, as these rules will determine whether domestic fluorodeoxyglucose production expands or hospitals remain tethered to imported tracer schedules.
Market Dynamics
ANMAT's radiopharmaceutical import protocol revisions are compressing tracer procurement cycles while ARN's cyclotron licensing deliberations determine whether domestic fluorodeoxyglucose production expands or hospitals remain import-dependent. This regulatory dualism shapes capital allocation across Argentine imaging centers.
Growth Catalysts
- Oncology protocol expansion:Buenos Aires tertiary centers are embedding PET-CT into precision cancer staging pathways, creating procedural volume anchors for hybrid imaging systems.
- ANMAT streamlining:Updated import protocols for technetium-based tracers are reducing customs clearance friction and stabilizing supply schedules for SPECT-equipped facilities.
- Cardiology shift:Myocardial perfusion imaging protocols are migrating from exercise treadmill testing to technetium-sestamibi SPECT, generating replacement demand for gamma camera fleets.
Market Restraints
- Import dependency:Argentina lacks domestic molybdenum-99 production, forcing hospitals to source generators from North American and European suppliers with currency exposure.
- ARN facility constraints:Mandatory lead shielding specifications and operator certification requirements restrict PET-CT installations to accredited tertiary centers in Córdoba and Buenos Aires provinces.
- Cyclotron licensing uncertainty:Pending ARN rules on medical cyclotron operation are freezing domestic FDG production investments and perpetuating tracer import schedules.
Strategic Opportunities
- Provincial decentralization:Public-sector tenders are fragmenting to Mendoza, Santa Fe, and Tucumán health ministries, opening procurement channels beyond metropolitan Buenos Aires.
- PET-MRI convergence:Hybrid system vendors can target neurological departments seeking fused metabolic and soft-tissue imaging for epilepsy and dementia protocols.
- Private imaging center expansion:Direct manufacturer negotiations are replacing distributor intermediaries for capital equipment, compressing transaction costs and accelerating installation timelines.
Industry Challenges
- Radiopharmacist scarcity:ARN-certified personnel for tracer handling and quality control are concentrated in Buenos Aires, limiting facility expansion to secondary cities.
- Currency volatility exposure:Dollar-denominated service contracts and spare parts pricing are compressing maintenance budgets for public hospital SPECT fleets.
- Legacy system integration:PACS connectivity standards vary across Argentine hospital networks, complicating hybrid imaging data fusion with existing radiology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Nuclear Imaging Market |
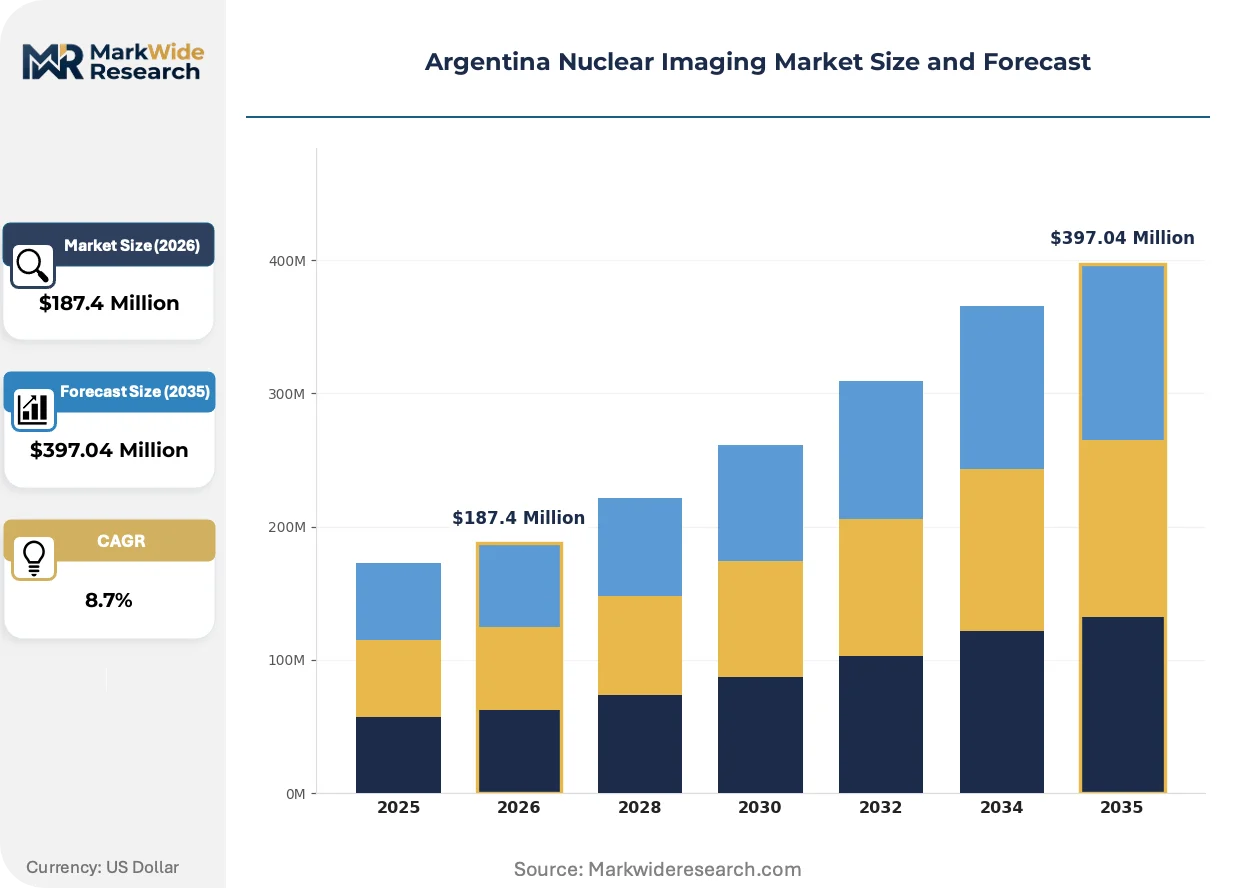
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, SPECT Systems, PET Scanners, Hybrid Imaging Systems End User: Hospitals, Imaging Centers, Research Institutions, Diagnostic Laboratories Technology: Digital Imaging, Analog Imaging, Photon Counting, Image Reconstruction Application: Oncology, Cardiology, Neurology, Rheumatology |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Hitachi Medical Corporation, Mediso Ltd., United Imaging Healthcare Co., Ltd., Neusoft Medical Systems Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Nuclear Imaging Market Strategic Shifts
Artificial intelligence applications are penetrating Argentine nuclear imaging workflows, compressing reconstruction times and enabling quantitative biomarker extraction. These capabilities are reshaping competitive differentiation among equipment vendors.
Digital PET detector technology is virtualizing analog photomultiplier architectures, enabling direct photon-to-digital conversion that improves timing resolution and reduces detector dead time. Oncology departments at Buenos Aires teaching hospitals are prioritizing these systems for low-dose protocols. The technology is virtualizing conventional SPECT-CT upgrade pathways by making full PET-CT replacement economically preferable.
ANMAT's alignment with International Council for Harmonisation guidelines is harmonizing radiopharmaceutical dossier requirements with FDA and EMA standards, reducing regulatory friction for multinational tracer suppliers. Argentine manufacturers seeking to enter the FDG market must now demonstrate compliance with these elevated documentation thresholds. Imported generator suppliers are accelerating product registration submissions to capture cyclotron licensing delays.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, negotiating technical support separately through third-party biomedical engineering firms. This disintermediation is compressing OEM service margins while expanding independent maintenance provider market share. The pattern is most visible in Córdoba's private hospital cluster, where imaging center administrators prioritize localized response times over manufacturer brand affiliation.
Argentina Nuclear Imaging Market Segmentation
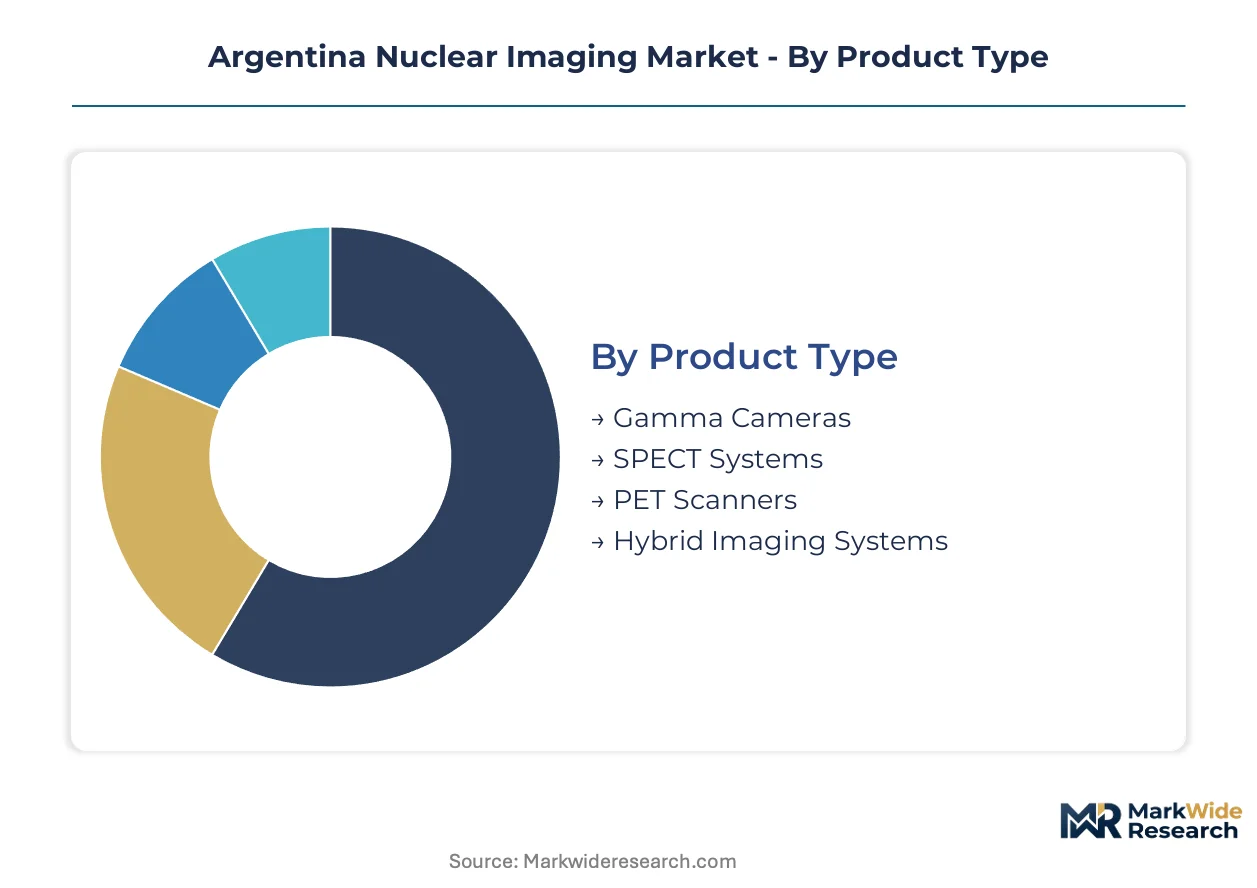
Segmentation in Argentina's nuclear imaging market reveals how procurement priorities diverge across facility types and clinical applications. Equipment specifications, tracer availability constraints, and regulatory accreditation requirements shape distinct demand profiles that vendors must navigate.
Product Type:
After-sales service intensity varies sharply across product categories, with hybrid systems demanding specialized biomedical engineering support while standalone gamma cameras rely on routine maintenance schedules.
- Hybrid Imaging Systems:PET-CT and PET-MRI configurations fuse metabolic and anatomical datasets at millimeter resolution. Buenos Aires oncology departments anchor demand as precision staging protocols expand; these systems justify premium capital outlays through procedural volume concentration in tertiary centers.
- PET Scanners:Standalone positron emission tomography systems detect gamma-ray emissions from fluorodeoxyglucose and other radiopharmaceutical tracers. Córdoba's cardiology institutes are expanding PET utilization for myocardial viability assessment, though tracer import dependency constrains utilization rates.
- SPECT Systems:Single photon emission computed tomography platforms using thallium-201 and technetium-based tracers dominate myocardial perfusion imaging across Argentine public hospitals.
- Gamma Cameras:Conventional Anger camera technology supports basic nuclear medicine procedures in provincial health ministry facilities with limited capital budgets.
Hybrid imaging systems hold the largest share; momentum sits with PET scanners as cardiology protocols shift toward metabolic assessment.
End User:
Procurement authority fragmentation across facility types creates divergent sales cycles, with public hospital tenders requiring multi-ministry approvals while private imaging centers execute rapid direct negotiations.
- Hospitals:Tertiary academic medical centers in Buenos Aires province concentrate PET-CT utilization for oncology staging and neurological diagnosis. ANMAT import protocols and ARN facility shielding requirements restrict installations to accredited institutions with certified radiopharmacist staffing.
- Imaging Centers:Private diagnostic facilities in Córdoba and Mendoza are unbundling service contracts from capital purchases, negotiating directly with manufacturers to compress transaction timelines. These centers prioritize technetium-sestamibi SPECT for cardiology stress testing.
- Research Institutions:University-affiliated nuclear medicine departments drive clinical trial enrollment and novel tracer protocol development.
- Diagnostic Laboratories:Independent pathology networks are expanding molecular imaging partnerships to capture oncology referral flows.
Hospitals command the dominant installed base; imaging centers are expanding most quickly as provincial decentralization opens new procurement channels.
Technology:
Detector architecture choices determine capital intensity and operational flexibility, with digital platforms commanding price premiums that analog systems cannot match in Argentine peso-denominated budgets.
- Digital Imaging:Solid-state cadmium-zinc-telluride detectors enable direct photon-to-digital conversion with improved energy resolution. Buenos Aires teaching hospitals are prioritizing these platforms for low-dose oncology protocols.
- Photon Counting:Emerging detector technology eliminates electronic noise through individual photon registration. Research institutions are piloting these systems for quantitative biomarker extraction in neurodegenerative disease protocols.
- Analog Imaging:Conventional photomultiplier tube architectures persist in legacy SPECT installations across provincial public hospitals.
- Image Reconstruction:Iterative algorithm implementations and artificial intelligence-assisted processing are penetrating Argentine workflows to compress reconstruction times.
Digital imaging dominates new capital allocation; photon counting represents the steepest expansion trajectory as research partnerships accelerate technology transfer.
Application:
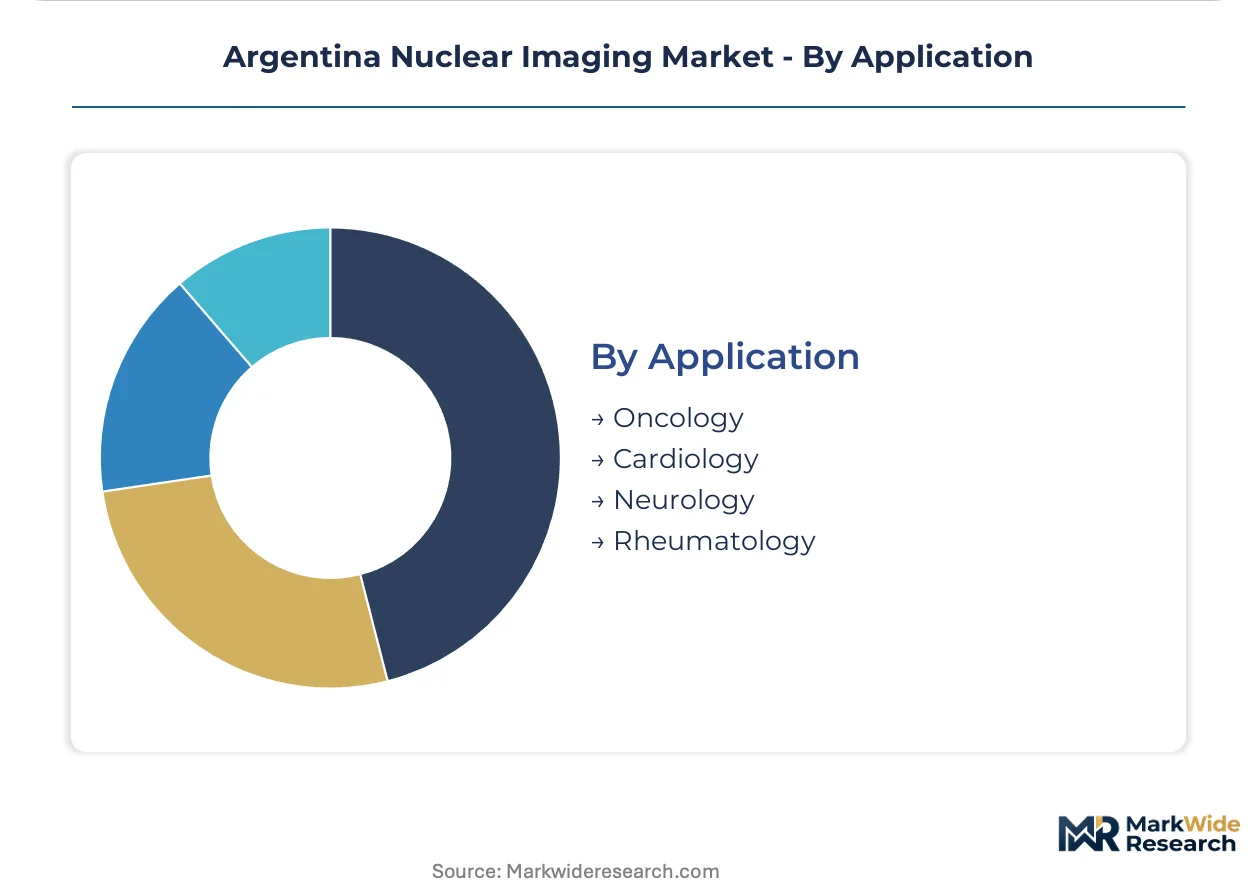
Clinical utilization patterns reflect epidemiological burden and reimbursement alignment, with oncology procedures generating volume anchors while cardiology segments climb fastest on protocol migration.
- Oncology:Cancer staging, treatment response monitoring, and radiation therapy planning drive PET-CT procedural volume. Molecular radiotherapy expansion across Buenos Aires hospitals is embedding hybrid imaging into precision oncology pathways.
- Cardiology:Myocardial perfusion imaging with technetium-sestamibi SPECT is displacing exercise treadmill testing. Córdoba's private hospital cluster is leading this protocol shift.
- Neurology:Epilepsy focus localization and dementia differential diagnosis utilize PET metabolic imaging and SPECT cerebral perfusion studies.
- Rheumatology:Bone scintigraphy and white blood cell imaging support infection and inflammation assessment in tertiary referral patterns.
Oncology anchors procedural volume; cardiology is gaining share fastest as stress-testing protocols migrate toward molecular imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANMAT's regulatory framework anchors demand concentration in the metropolitan Buenos Aires corridor, where tertiary care density and ARN-accredited facilities enable advanced molecular imaging deployment.
Buenos Aires Province
Oncology departments at teaching hospitals are expanding PET-CT utilization for precision cancer staging protocols. ANMAT's streamlined radiopharmaceutical import protocols are reducing customs clearance friction for technetium-based tracers. The provincial capital anchors the national installed base, with Hospital de Clínicas and Fundación Favaloro driving hybrid imaging procedural volume.
Córdoba Province
Cardiology institutes are migrating stress-testing protocols toward myocardial perfusion imaging with technetium-sestamibi SPECT. ARN facility shielding requirements restrict PET-CT installations to accredited tertiary centers with certified radiopharmacist staffing. The Córdoba private hospital cluster is unbundling service contracts from capital purchases, negotiating directly with manufacturers.
Mendoza Province
Public-sector tenders are decentralizing to provincial health ministries, opening procurement channels beyond the traditional Buenos Aires concentration. ARN's pending cyclotron licensing deliberations are freezing domestic FDG production investments across western Argentina. Diagnostic imaging centers in Greater Mendoza are prioritizing gamma camera upgrades for basic nuclear medicine procedures.
Santa Fe Province
Rosario's medical complex is embedding molecular imaging into radiation therapy planning pathways. The country's national pharmaceutical regulator enforces Good Manufacturing Practice standards that constrain local tracer supply and perpetuate import dependency. Research institutions at Universidad Nacional de Rosario are piloting novel tracer protocols for neurodegenerative disease assessment.
Tucumán Province
Provincial health ministry tenders are fragmenting procurement authority across northern Argentina. Currency volatility exposure on dollar-denominated service contracts is compressing maintenance budgets for public hospital SPECT fleets. San Miguel de Tucumán's tertiary centers are expanding SPECT-CT utilization for infection and inflammation assessment in rheumatology referral patterns.
Argentina Nuclear Imaging Market Competitive Environment
Multinational imaging conglomerates and specialized radiopharmaceutical suppliers split the market along capital equipment versus tracer supply vectors. Siemens Healthineers AG leverages its installed base of SPECT systems to sustain service-contract revenue across Argentine public hospitals. GE HealthCare competes through localized technical support teams that anchor customer loyalty in Buenos Aires and Córdoba. Koninklijke Philips N.V. differentiates by positioning its hybrid imaging portfolio toward cardiology departments seeking PET-CT integration. The dominant competitive moves center on disintermediating distributor networks through direct manufacturer negotiations and unbundling service contracts from capital equipment purchases.
Among European-based conglomerates, Siemens Healthineers AG and Koninklijke Philips N.V. exemplify the full-modality archetype, occupying positions that span gamma cameras through PET-MRI configurations. GE HealthCare represents the North American integrated healthcare technology model, anchoring customer relationships through embedded service infrastructure. These three companies sit within the premium-tier equipment segment, where hybrid system specifications justify capital outlays through procedural volume concentration in ARN-accredited tertiary centers.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Hitachi Medical Corporation |
| Mediso Ltd. |
| United Imaging Healthcare Co., Ltd. |
| Neusoft Medical Systems Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in domestic fluorodeoxyglucose production concentrates pricing power with North American and European tracer suppliers, while ARN's pending cyclotron licensing deliberations freeze capital commitments that would otherwise expand local manufacturing capacity and compress import premiums.
Pricing Analysis
Metropolitan Buenos Aires commands 15-20% capital equipment premiums over Córdoba and Mendoza provinces due to ARN accreditation density and radiopharmacist concentration. Pricing stratifies across premium hybrid imaging systems, standard SPECT configurations, and economy gamma camera tiers, with differentiation driven by detector architecture sophistication and after-sales service bundling. Cost compression in the public hospital segment is intensifying as dollar-denominated maintenance contracts expose budgets to peso volatility. Private imaging centers in Córdoba demonstrate the least price sensitivity, prioritizing localized technical response times over capital outlay minimization.
Supply Chain Analysis
Molybdenum-99 feedstock draws from reactor complexes in Canada, the Netherlands, and South Africa, with no domestic Argentine production anchoring hospital generator procurement to offshore schedules. Argentine nuclear imaging rests on technetium-99m generator imports, fluorodeoxyglucose cold kits, and lead shielding materials for facility compliance. Single-source vulnerability concentrates in North American molybdenum-99 suppliers, where reactor maintenance cycles periodically disrupt global availability. Distribution runs through ANMAT-licensed radiopharmaceutical importers that maintain cold-chain logistics to ARN-accredited tertiary centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's nuclear imaging market represents early-cycle expansion as provincial health ministry decentralization fragments procurement authority beyond metropolitan Buenos Aires, opening addressable demand in secondary cities previously tethered to capital corridor referrals.
For Market Incumbents: Harden service-contract profitability by embedding localized biomedical engineering teams in Córdoba and Mendoza before provincial tender fragmentation accelerates. Anchor customer loyalty through cyclotron licensing contingency planning that positions vendors for domestic FDG production partnerships when ARN rules finalize. Prioritize backward integration into radiopharmaceutical distribution partnerships to capture tracer margin pools currently accruing to importers. For New Entrants and Emerging Players: Pursue direct manufacturer negotiations with private imaging centers in Córdoba's unbundled procurement environment, where transaction cost compression outweighs brand heritage preferences. Target neurological departments seeking PET-MRI convergence for epilepsy and dementia protocols as the most penetrable application segment. Deploy third-party biomedical engineering service capabilities as the primary go-to-market angle against OEM-incumbent maintenance bundling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent radiopharmaceutical distributors with ANMAT import licenses and established cold-chain logistics networks. Long-term viability over a decade horizon hinges on ARN cyclotron licensing resolution that would enable domestic FDG production economics. Monitor ARN regulatory bulletin releases as the definitive inflection signal for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ARN Cyclotron Licensing Compliance | Domestic FDG production authorization would reshape tracer economics for Buenos Aires hospital networks. |
| Provincial Tender Fragmentation | Direct manufacturer access to Mendoza and Santa Fe health ministries bypasses traditional distributor markups. |
| Digital Detector Platform Migration | Solid-state CZT technology adoption at teaching hospitals creates replacement cycles for analog SPECT fleets. |
| AI-Assisted Image Reconstruction Integration | Workflow compression capabilities differentiate vendor proposals in public hospital procurement evaluations. |
| Radiopharmacist Training Pipeline Investment | ARN-certified personnel scarcity outside Buenos Aires limits facility expansion to secondary cities. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with nuclear medicine department heads, biomedical engineering directors, hospital procurement committee members, and ANMAT regulatory affairs specialists; and secondary validation against ARN facility accreditation databases, ANMAT radiopharmaceutical registration filings, and provincial health ministry tender documentation. Bottom-up equipment installation tracking and top-down healthcare expenditure triangulation anchored market sizing.
Forecast inputs considered product type segmentation across hybrid imaging systems, PET scanners, SPECT platforms, and gamma cameras; end-user concentration across tertiary hospitals, private imaging centers, and research institutions; and technology migration patterns from analog to digital detector architectures. CAGRs were derived from procedural volume trajectories in oncology staging and cardiology perfusion imaging, cross-referenced against ANMAT import protocol streamlining assumptions and ARN regulatory timeline scenarios across the projection horizon.
Sensitivities concentrate around ARN cyclotron licensing delays, peso-dollar exchange rate volatility affecting service contract affordability, and molybdenum-99 supply interruptions from aging reactor infrastructure. Cross-checking against hospital capital expenditure budget disclosures in provincial health ministry transparency portals is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
United States Mammography Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market